
 India Renewable Energy Market | 2026-2036
India Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
India Renewable Energy Market Outlook
Utility-scale buyer concentration is hardening as state discoms consolidate procurement through larger solar park tenders and fewer but bigger power purchase agreements. Adani Green Energy Limited leverages its integrated development-execution model to dominate gigawatt-scale solar-wind hybrid projects. ReNew Power anchors its position through long-term offtake contracts with industrial buyers seeking renewable power directly. Tata Power Renewable Energy Limited sustains competitive differentiation through its distributed solar rooftop channel and captive power arrangements with manufacturing clusters.
India renewable energy encompasses solar photovoltaic, onshore wind, small hydro, and biomass-based systems engineered to convert natural flux into grid-synchronized electricity, with photovoltaic modules typically rated between 300W and 700W peak output per panel under standard test conditions. Solar photovoltaic capacity leads installed base expansion due to plunging module costs and the PLI scheme's domestic manufacturing push, while offshore wind represents the fastest-growing technology segment as the government auctions seabed leases along Tamil Nadu and Gujarat coasts. Utility-scale applications command the largest share of capital deployment, though commercial and industrial rooftop installations are capturing margin pools through higher tariffs and faster commissioning timelines.
The Ministry of New and Renewable Energy shapes project economics through reverse auction mechanisms and viability gap funding, while the Central Electricity Authority mandates renewable purchase obligations that force discoms to contract clean power. BIS certification requirements for solar modules and inverters create quality barriers that filter out low-grade imports, and state-level solar policies in Rajasthan, Gujarat, and Karnataka establish land allocation and evacuation infrastructure priorities. Stakeholders must monitor whether green hydrogen offtake agreements materialize at scale and how interstate transmission charges evolve for renewable-rich states supplying demand centers elsewhere.
Market Dynamics
Utility-scale solar procurement is consolidating around fewer but larger tenders as state discoms in Gujarat and Rajasthan bundle gigawatt-scale park allocations, compressing developer margins while favoring vertically integrated players with captive module supply.
Growth Catalysts
- PLI Scheme for Solar Modules:Domestic manufacturing incentives under the Ministry of New and Renewable Energy are redirecting capital toward polysilicon-to-module integration, reducing import dependence on Southeast Asian supply chains.
- Green Hydrogen Mission:Electrolyzer demand from refineries and fertilizer plants is creating anchor offtake for renewable power, with Gujarat and Rajasthan positioning as hydrogen export hubs.
- Offshore Wind Auctions:Seabed leases along Tamil Nadu and Gujarat coasts are unlocking capacity factors above 50 percent, attracting developers with hybrid project experience.
Market Restraints
- Land Acquisition Bottlenecks:Solar park development in Maharashtra and Karnataka faces fragmented landholdings and competing agricultural use, extending project timelines by 18-24 months.
- Transmission Evacuation Gaps:Renewable-rich western states lack interstate corridor capacity to deliver power to demand centers in Delhi and Punjab, forcing curtailment during peak generation.
- Polysilicon Price Volatility:Concentrated supply from Chinese ingot and wafer producers exposes Indian module assemblers to input cost swings that reverse auction tariffs cannot absorb.
Strategic Opportunities
- Captive Power for Manufacturing Clusters:Textile and chemical parks in Tamil Nadu and Andhra Pradesh are bypassing discoms through direct bilateral contracts with renewable developers.
- Agrivoltaics in Water-Stressed Districts:Dual-use solar installations over horticulture and drip-irrigated crops are unlocking land access in Madhya Pradesh where pure solar faces resistance.
- Green Ammonia Export Corridors:Kandla and Mundra ports are positioning as bunkering hubs for maritime ammonia, requiring dedicated renewable offtake contracts with electrolyzer developers.
Industry Challenges
- Grid Integration Complexity:State load dispatch centers lack forecasting tools and storage co-location mandates to manage solar duck curves, forcing frequency regulation burdens on thermal plants.
- BIS Certification Backlogs:Module and inverter testing capacity at Bureau of Indian Standards labs is creating 4-6 month approval delays, holding up project financial closures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Renewable Energy Market |
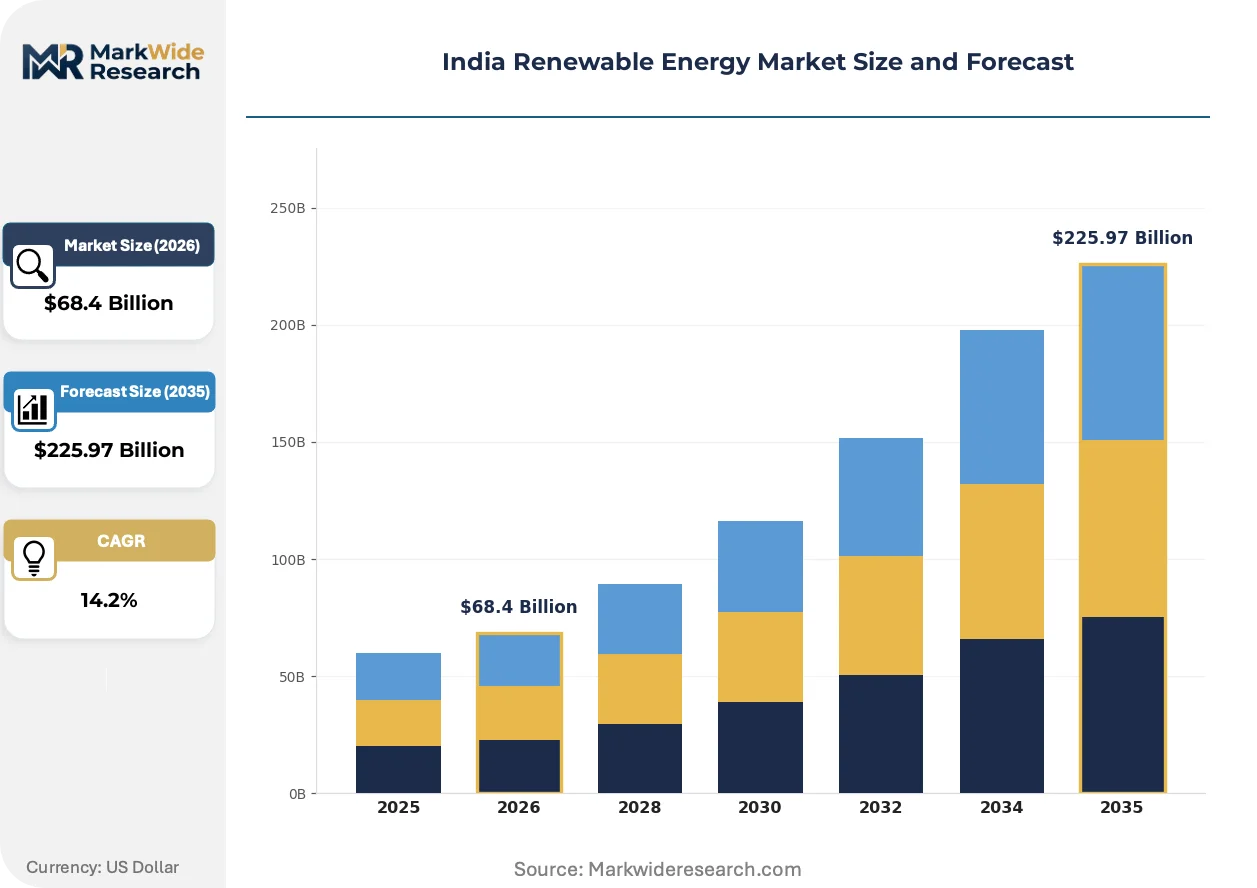
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $225.97 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Wind, Biomass, Hydro End User: Residential, Commercial, Industrial, Utility Technology: Photovoltaic, Concentrated Solar Power, Offshore Wind, Biogas Application: Electricity Generation, Heating, Water Pumping, Charging Stations |
| Companies Covered | Adani Green Energy Limited, ReNew Power, Sterling and Wilson Renewable Energy, Tata Power Renewable Energy Limited, NTPC Green Energy Limited, JSW Energy, Suzlon Energy Limited, Azure Power Global Limited, ACME Solar Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Renewable Energy Market Strategic Shifts
Technology convergence between solar generation and storage is restructuring project economics, while regulatory pressure on domestic content and evolving procurement models are compressing traditional development timelines.
Bifacial modules with tracking systems are integrating DC coupling with battery inverters to eliminate AC conversion losses. Industrial offtakers in cement and steel are specifying these configurations for 24/7 renewable supply contracts. The architecture is integrating balance-of-plant vendors into single-point EPC arrangements that reduce interface risk.
The Ministry of New and Renewable Energy's Approved List of Models and Manufacturers mandates domestic cell and module sourcing for government projects. This is fragmenting developer procurement strategies between ALMM-compliant domestic supply and exempted open-access bilateral contracts. Large-scale solar park tenders in Rajasthan are most affected, with bidders restructuring consortiums to include captive module manufacturing.
Corporate buyers are consolidating renewable procurement through round-the-clock contracts that bundle solar, wind, and storage rather than separate technology-specific PPAs. This is displacing plain-vanilla solar-only auctions in Maharashtra and Karnataka. The shift is most visible among data center operators and automotive OEMs seeking firm dispatchable power without thermal backup.
India Renewable Energy Market Segmentation
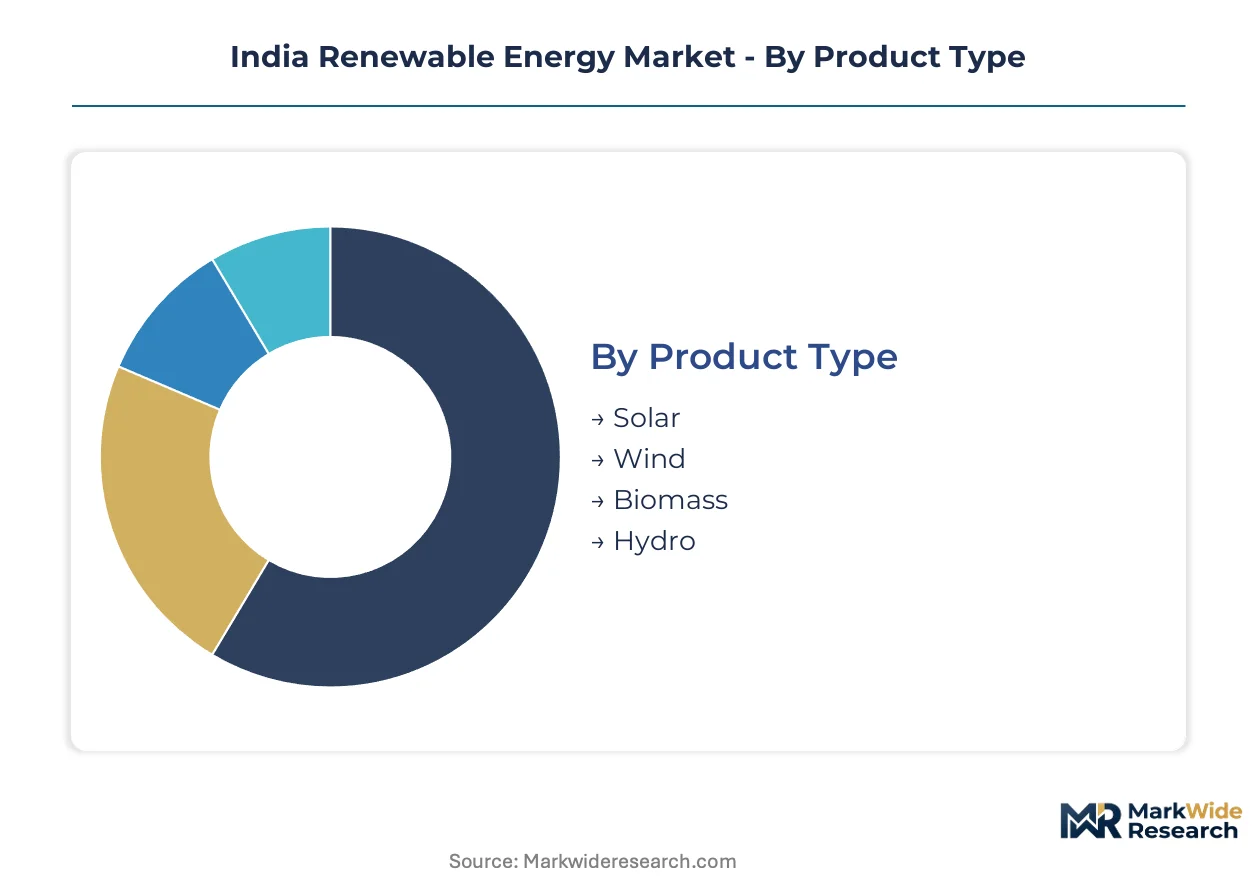
Segmentation reveals how capital allocation and policy incentives reshape competitive positioning across technology platforms and customer tiers. Understanding where procurement concentrates and where margins diverge enables targeted positioning against the Central Electricity Authority's renewable purchase obligations and state-level discom tendering patterns.
Product Type:
Supply concentration in polysilicon and turbine nacelle manufacturing determines which technologies achieve cost parity fastest against thermal baseload.
- Solar:Photovoltaic modules rated 300-700W peak output dominate capacity additions, with Gujarat and Rajasthan state discoms bundling gigawatt-scale park tenders that favor developers with captive module supply under the PLI scheme. Land acquisition bottlenecks in Maharashtra and Karnataka compress margins for pure-play developers lacking integrated land access.
- Wind:Onshore turbines in Tamil Nadu and Gujarat coastal corridors deliver capacity factors above 35 percent, though gearbox and generator imports expose developers to currency fluctuation. Offshore seabed leases are unlocking higher capacity factors above 50 percent along the same coastlines.
- Biomass:Agricultural residue-fired systems cluster around Punjab and Haryana rice belt, constrained by feedstock collection logistics and seasonal availability.
- Hydro:Small run-of-river projects in Himalayan states face extended environmental clearance timelines that stretch project development cycles.
Solar absorbs the bulk of installed capacity; offshore wind within the wind category is expanding most quickly.
End User:
Customer type dictates tariff structure, counterparty risk profile, and whether projects connect at transmission or distribution voltage levels.
- Residential:Rooftop installations below 10kW capacity rely on state-level net metering policies, with Maharashtra and Karnataka offering the most favorable settlement mechanisms. Discom financial stress in some states has delayed subsidy disbursements, extending payback periods.
- Commercial:Office complexes and retail chains in Delhi-NCR and Bengaluru procure through open-access arrangements, bypassing state discoms to contract directly with renewable developers for 15-20 year tenors.
- Industrial:Captive power demand from textile parks in Tamil Nadu and chemical clusters in Gujarat anchors bilateral contracting, with round-the-clock renewable-plus-storage contracts displacing diesel backup and grid draw.
- Utility:State discoms in Rajasthan, Gujarat, and Karnataka consolidate procurement through larger solar park tenders with fewer but bigger power purchase agreements, compressing developer margins while favoring vertically integrated players.
Utility-scale deployment commands the dominant share of capital deployment; industrial offtake is climbing the fastest as manufacturing clusters bypass discom intermediation.
Technology:
Technology selection hinges on BIS certification requirements, domestic content mandates under the ALMM regime, and whether projects qualify for government viability gap funding.
- Photovoltaic:Crystalline silicon modules with bifacial architecture and single-axis tracking dominate utility-scale deployment, with DC-coupled battery integration eliminating AC conversion losses for industrial round-the-clock contracts.
- Concentrated Solar Power:Parabolic trough and solar tower configurations with molten salt storage enable dispatchable renewable supply, though higher capital intensity limits deployment to Rajasthan solar parks with dedicated land allocation.
- Offshore Wind:Fixed-bottom turbines in Tamil Nadu and Gujarat shallow waters represent the steepest expansion trajectory, with seabed auctions attracting developers with hybrid project execution experience.
- Biogas:Anaerobic digesters processing agricultural waste and municipal sewage yield compressed biogas for transport fuel blending, constrained by feedstock supply chain fragmentation outside concentrated dairy and sugar belt geographies.
Photovoltaic technology anchors current installed base; offshore wind represents the fastest-growing trajectory as seabed leasing accelerates.
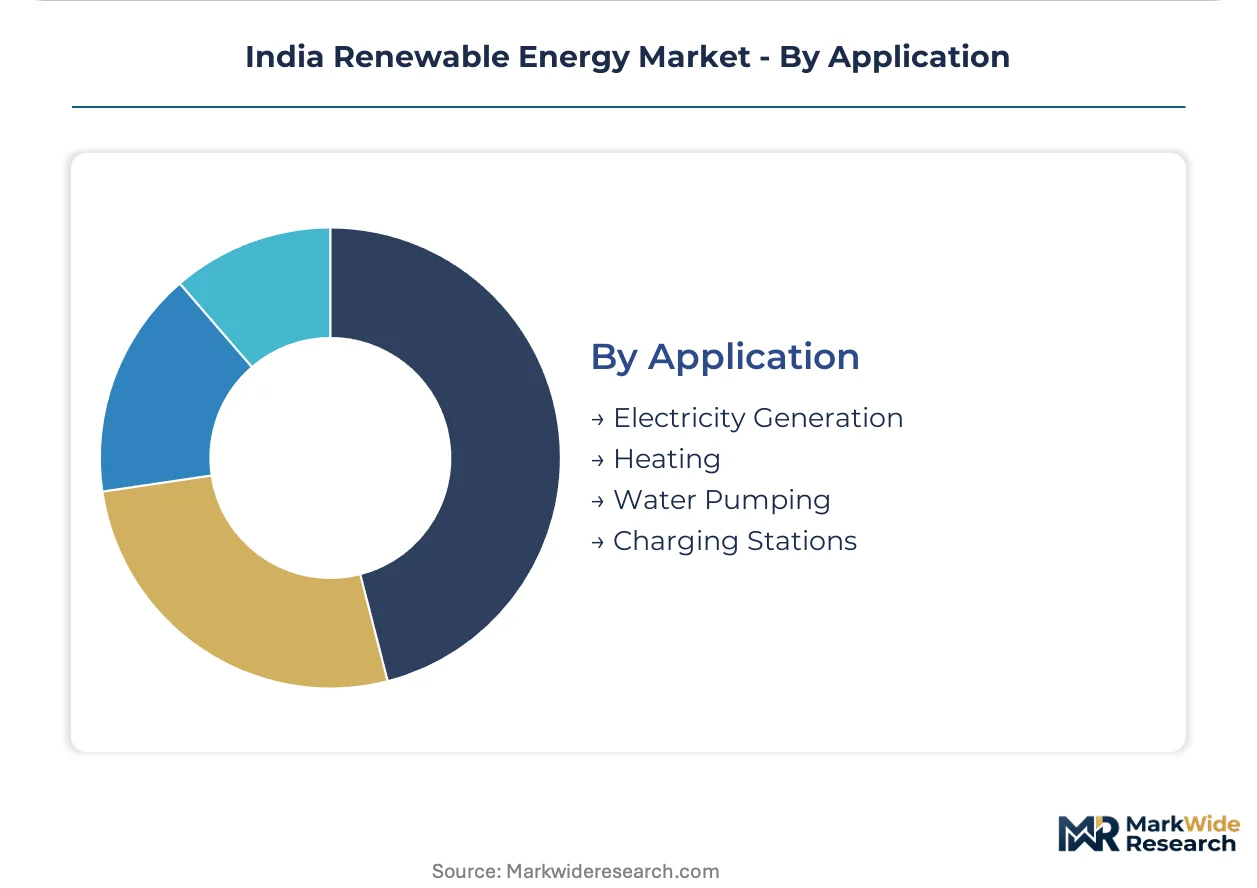
Application:
Application type determines whether renewable assets serve grid-synchronized electricity markets or displace fossil fuel in thermal and transport end-uses.
- Electricity Generation:Grid-connected solar parks and wind farms constitute the primary deployment mode, with interstate transmission charges and renewable purchase obligations shaping project economics across state boundaries.
- Heating:Solar thermal collectors for industrial process heat in dairy and food processing clusters face competition from biomass boilers, with limited policy support compared to electricity-focused incentives.
- Water Pumping:Off-grid solar pumps for agricultural irrigation in Rajasthan and Gujarat reduce diesel dependence, though maintenance networks remain sparse in remote districts.
- Charging Stations:Solar-powered electric vehicle charging infrastructure along highway corridors in Maharashtra and Karnataka anchors demand for distributed generation with storage co-location.
Electricity generation captures the overwhelming share of deployed capacity; charging station applications are gaining share fastest as electric vehicle adoption accelerates in western and southern states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for renewable energy concentrates in western and southern states where solar irradiance and wind corridors overlap with industrial land availability. Gujarat and Rajasthan anchor utility-scale deployment through state discom procurement consolidation. The Ministry of New and Renewable Energy channels viability gap funding toward these high-resource zones.
Gujarat
Gujarat's solar parks and offshore wind seabed leases attract gigawatt-scale developers seeking hybrid project execution. The state's renewable purchase obligations under CEA mandates force discoms to contract clean power at scale. Mundra and Kandla ports position as green ammonia export corridors requiring dedicated electrolyzer offtake.
Rajasthan
Rajasthan's desert tracts host the nation's largest solar park allocations with capacity factors exceeding 22 percent. Land allocation policies under the state solar policy prioritize evacuation infrastructure for renewable-rich districts. Phased manufacturing clusters in Jodhpur and Jaisalmer integrate module assembly with park development.
Tamil Nadu
Tamil Nadu's wind corridors and offshore seabed leases along the Gulf of Mannar unlock capacity factors above 50 percent. The state's captive power policy enables textile parks in Tiruppur and Coimbatore to bypass discoms through direct bilateral contracts. Bifacial tracking installations dominate new capacity additions.
Karnataka
Karnataka's commercial and industrial open-access framework attracts data center operators seeking round-the-clock renewable supply. The state's net metering settlement mechanisms for rooftop installations remain among the most favorable nationally. Bengaluru's manufacturing clusters drive distributed solar demand through captive power arrangements.
Maharashtra
Maharashtra faces fragmented landholdings that extend solar project timelines by 18-24 months despite strong industrial demand. The state's electric vehicle charging corridor along Mumbai-Pune expressway anchors distributed generation with storage co-location. Discom financial stress has delayed subsidy disbursements for residential rooftop segments.
India Renewable Energy Market Competitive Environment
Western India producers anchor the utility-scale tier; southern specialists hold captive power and distributed generation positions. The vendor base stratifies across vertically integrated gigawatt developers, pure-play EPC contractors, and industrial offtake aggregators. Three archetypes dominate: integrated park developers with captive module supply, open-access bilateral specialists, and rooftop-channel operators with discom relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure land banks and transmission access.
Among integrated developers, Adani Green Energy Limited and Tata Power Renewable Energy Limited exemplify the park-scale archetype with backward integration into module manufacturing under PLI scheme incentives. ReNew Power occupies a position within the open-access specialist tier, anchoring long-term offtake structures with industrial buyers seeking renewable power directly. These three entities represent the competitive core around which mid-scale developers and EPC contractors orbit.
| Leading Market Players |
|---|
| Adani Green Energy Limited |
| ReNew Power |
| Sterling and Wilson Renewable Energy |
| Tata Power Renewable Energy Limited |
| NTPC Green Energy Limited |
| JSW Energy |
| Suzlon Energy Limited |
| Azure Power Global Limited |
| ACME Solar Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
The Ministry of New and Renewable Energy's Approved List of Models and Manufacturers gates both qualified supply and premium-tier pricing access, bifurcating developer procurement between ALMM-compliant domestic modules commanding tariff premiums and exempted open-access bilateral contracts trading at compressed rates.
Pricing Analysis
Volume versus margin splits sharply across the developer base: gigawatt-scale park tenders in Rajasthan and Gujarat compress tariffs through reverse auction mechanisms, while distributed rooftop and captive power arrangements in Karnataka and Tamil Nadu preserve healthier margins through bilateral negotiation. Price differentiation hinges on BIS certification tier and captive module manufacturing status under PLI scheme incentives. Cost compression in utility-scale segments is intensifying because state discoms consolidate procurement through fewer but larger tenders. Industrial offtakers exhibit the lowest price sensitivity, prioritizing round-the-clock supply assurance over tariff minimization.
Supply Chain Analysis
Logistics and freight costs from Chinese ingot and wafer producers to Indian module assembly plants expose developers to input cost volatility that reverse auction tariffs cannot fully absorb. Polysilicon supply concentrates in China, with Southeast Asian cell and module facilities serving as secondary sourcing nodes. Raw material dependencies span polysilicon, silver paste for metallization, and aluminum frames. Single-source vulnerability in Chinese wafer supply creates margin risk during commodity price spikes. Distribution runs through EPC contractors integrating balance-of-plant components into single-point project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over polysilicon-to-module production under the PLI scheme determines pricing power and project win rates.
For Market Incumbents: Cement dominance in gigawatt-scale solar park development by securing captive polysilicon supply through PLI scheme manufacturing licenses. Deepen upstream control over ingot and wafer production to insulate margins from Chinese input cost swings. Defend against emerging pure-play EPC contractors by locking long-term land allocation agreements in Rajasthan and Gujarat before seabed auctions accelerate offshore wind competition. For New Entrants and Emerging Players: Begin with agrivoltaic installations in water-stressed Madhya Pradesh districts where pure solar faces land access resistance. Target textile and chemical manufacturing clusters in Tamil Nadu and Andhra Pradesh seeking captive power through direct bilateral contracts. Establish go-to-market positioning through round-the-clock renewable-plus-storage offerings that displace diesel backup and grid draw for industrial offtakers. For Investors and Strategic Acquirers: Green hydrogen offtake agreements materializing at scale with Gujarat and Rajasthan refineries is the leading indicator that electrolyzer demand will anchor renewable power contracting. Frame long-term viability around developers with integrated manufacturing-execution capabilities spanning polysilicon through module assembly. Monitor BIS certification backlogs as the critical signal: approval delays beyond four months indicate testing capacity constraints that will advantage players with pre-certified product pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | PLI scheme incentives from the Ministry of New and Renewable Energy reduce import exposure to Chinese supply chains. |
| Seabed Lease Acquisition | Tamil Nadu and Gujarat offshore wind auctions unlock capacity factors above 50 percent for hybrid-experienced developers. |
| Round-the-Clock Contracting | Industrial offtakers in cement and steel specify bundled solar-wind-storage configurations displacing thermal backup. |
| Agrivoltaic Land Access | Dual-use solar over horticulture crops unlocks project sites in Madhya Pradesh where pure solar faces resistance. |
| Green Ammonia Export Positioning | Kandla and Mundra port bunkering hubs require dedicated electrolyzer offtake contracts with renewable developers. |
Study Parameters
Multi-period observation of state discom tender awards, module import volumes, and green hydrogen mission allocations anchored the trend analysis, supplemented by interviews with utility planning officers at Gujarat and Rajasthan discoms, IPP project developers managing gigawatt-scale parks, EPC contractors integrating balance-of-plant systems, and grid operators at state load dispatch centers. Secondary validation drew from Central Electricity Authority renewable purchase obligation compliance data, Ministry of New and Renewable Energy PLI scheme disbursement records, Bureau of Indian Standards certification backlogs, and interstate transmission charge regulatory filings. Bottom-up project pipeline tracking and top-down policy impact assessment were triangulated to reconcile capacity addition forecasts.
Segment-weighting across the projection horizon applied technology-specific capacity factor assumptions, state-level land availability scores, and regulatory framework maturity indices. The analytical framework modeled solar photovoltaic, onshore wind, offshore wind, and green hydrogen electrolyzer demand as distinct revenue streams, with cross-segment hybrid project economics treated as an overlay dimension. CAGRs were derived from regression-based capacity addition curves against policy milestone triggers, incorporating BIS certification throughput constraints and transmission evacuation gap resolution timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; utility-scale solar and onshore wind carry tighter precision than offshore wind and green hydrogen given auction timing uncertainty. Forecasts reflect assumptions about PLI scheme continuation, interstate transmission charge rationalization, and electrolyzer cost decline curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Zimbabwe Renewable Energy Market