
 Brazil Wind Energy Market | 2026-2036
Brazil Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Wind Energy Market Outlook
ANVISA's environmental licensing alignment with the EU Green Deal supply-chain requirements is consolidating procurement standards for turbine component imports. Neoenergia SA leverages its transmission integration across the Northeast to sustain project pipeline visibility. Vestas Wind Systems AS anchors its nacelle assembly presence in Ceará to compete on logistics cost. Siemens Gamesa Renewable Energy SA differentiates through blade technology adapted to Brazil's high-shear wind regimes.
Brazil wind energy encompasses the conversion of kinetic atmospheric flow into grid-connected electricity through horizontal-axis turbines typically rated between 2 MW and 6 MW, with rotor diameters exceeding 130 meters optimized for low-to-medium wind density sites. The technology serves base-load displacement, industrial decarbonization targets, and rural electrification needs across the national interconnected system. Onshore installations dominate operational capacity while offshore frameworks remain nascent pending regulatory seabed leasing. Extra-large capacity turbines command margin concentration due to scale economies in power purchase agreement bidding. Repowering of early-2000s fleets in Rio Grande do Norte presents structural growth as aging 850 kW units face efficiency thresholds.
ANEEL's distributed generation net metering rules and BNDES local content financing requirements shape equipment sourcing decisions and foreign OEM joint-venture structures. IBAMA's environmental licensing timelines for Atlantic Forest corridor projects constrain site development velocity and capital commitment schedules. EPE's decennial energy expansion plans and the national hydrogen strategy under MME redirect long-term offtake negotiations toward green ammonia and e-fuel export hubs. Stakeholders must monitor transmission auction schedules and subsea cable regulatory frameworks to time capacity commitments against interconnection bottlenecks.
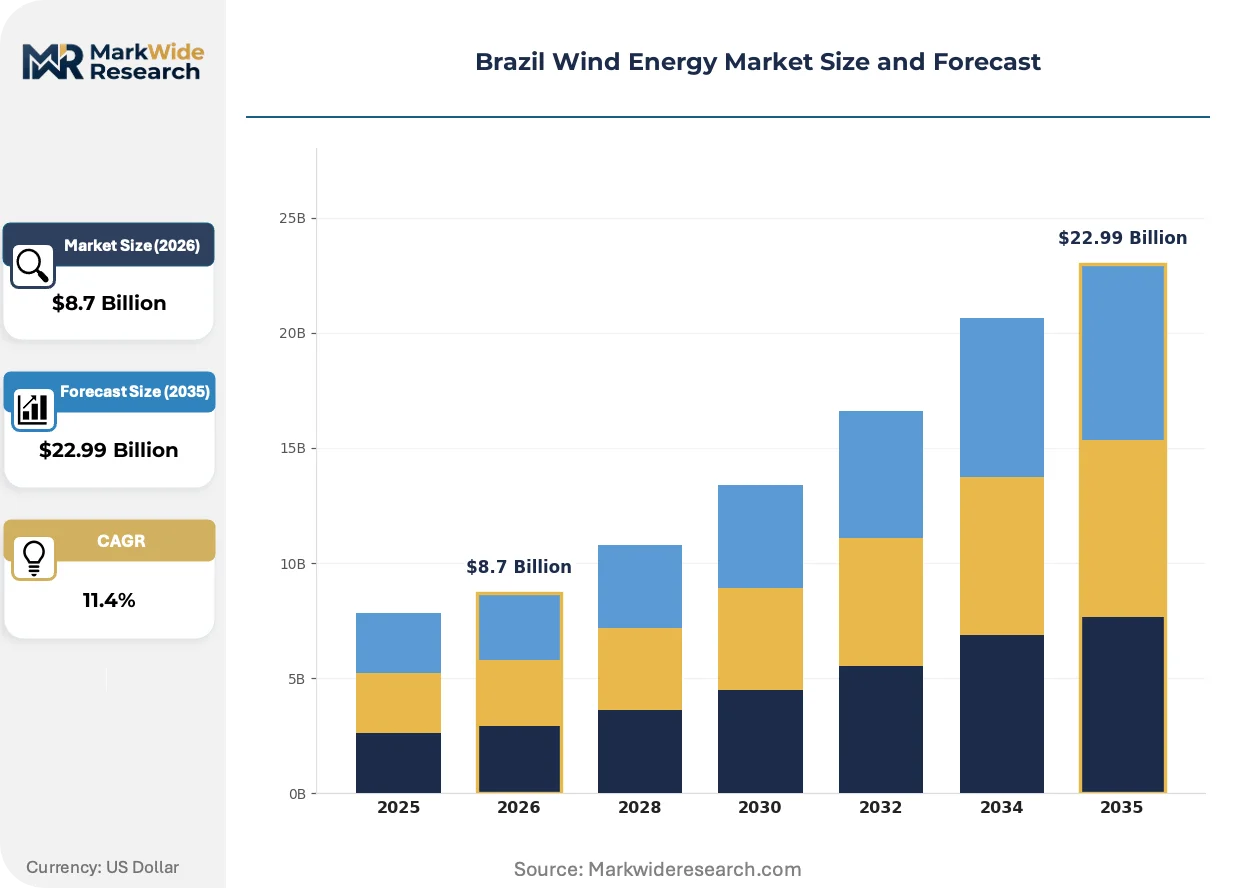
Market Dynamics
ANEEL's distributed generation net metering rules under Lei 14.300/2022 are redistributing capital flows toward self-production clusters, compressing traditional utility-scale procurement timelines and forcing developers to reconfigure project origination strategies around industrial offtakers rather than auction-based contracting.
Growth Catalysts
- Lei 14.300/2022:The distributed generation framework enables commercial and industrial consumers to offset grid purchases through self-owned wind assets, unlocking captive demand from aluminum smelters and data centers seeking 24/7 renewable supply.
- Green hydrogen export corridors:MME's national hydrogen strategy redirects long-term offtake negotiations toward green ammonia and e-fuel production hubs, anchoring capacity expansion in transmission-linked zones.
- Rio Grande do Norte repowering:Aging 850 kW units from the early 2000s face efficiency thresholds that mandate turbine replacement, creating structural replacement demand independent of greenfield auction schedules.
Market Restraints
- IBAMA licensing velocity:Environmental permitting timelines for Atlantic Forest corridor projects extend capital commitment schedules and increase carrying costs for developers holding land options.
- BNDES local content requirements:Financing eligibility mandates domestic equipment sourcing that constrains foreign OEM supply flexibility and extends procurement lead times for specialized components.
- Transmission interconnection queues:Northeast region grid congestion limits dispatch certainty for new capacity, forcing developers to absorb basis risk or defer construction until auctioned transmission expansion energizes.
Strategic Opportunities
- Bahia transmission expansion zones:Substation upgrades and new 500 kV corridors create greenfield development potential in previously constrained wind corridors with medium wind density profiles.
- Offshore regulatory framework:Pending seabed leasing rules under MME consultation will unlock floating and fixed-bottom capacity in shallow Atlantic waters with higher capacity factors than onshore equivalents.
- Corporate PPA aggregation platforms:Energy marketing companies are bundling smaller commercial offtakers into synthetic portfolios that meet minimum scale thresholds for project finance, expanding addressable demand beyond large industrials.
Industry Challenges
- Specialized technician scarcity:Blade repair, gearbox overhaul, and high-voltage commissioning skills concentrate in Ceará and Rio Grande do Norte, creating wage inflation and mobilization delays for projects in emerging states.
- Logistics corridor saturation:Oversized nacelle and blade movements through Pecém and Suape ports face scheduling conflicts with oil platform components and agricultural export seasons, compressing installation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Wind Energy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Horizontal Axis, Vertical Axis End User: Utilities, Independent Power Producers, Commercial, Residential Installation: New, Retrofit, Repower, Expansion Capacity: Small Scale, Medium Scale, Large Scale, Extra Large |
| Companies Covered | Neoenergia SA, Vestas Wind Systems AS, Siemens Gamesa Renewable Energy SA, Nordex SE, ABB Ltd, Enel Green Power Brasil, GE Vernova, Statkraft Energias Renovaveis SA, 2W Energia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Wind Energy Market Strategic Shifts
Digital twin integration and predictive maintenance algorithms are compressing OPEX forecasts and reshaping lender risk assessments. Technology convergence across generation, storage, and green fuel synthesis is redefining project economics.
Advanced blade monitoring systems using fiber-optic strain sensors and edge-computing analytics are decentralizing maintenance decision-making from centralized control rooms to turbine-level autonomous diagnostics. Industrial offtakers with 24/7 renewable targets are deploying these systems to minimize downtime penalties in corporate PPA structures. The shift is decentralizing service relationships from OEM captive contracts to independent service provider networks.
ANVISA's environmental licensing alignment with EU Green Deal supply-chain requirements is consolidating procurement standards for turbine component imports. Blade and nacelle manufacturers must now document carbon intensity across steel, fiberglass, and rare earth magnet supply chains to maintain market access. European-bound export projects face the strictest compliance verification, forcing Brazilian developers to tier supplier qualification criteria by destination market.
Long-term service agreements are unbundling from initial equipment supply, with independent asset managers negotiating direct contracts with specialized blade repair and gearbox refurbishment shops. This disintermediation compresses maintenance costs by 15-25% versus OEM-integrated service packages. The pattern is most visible in Rio Grande do Norte's mature fleet, where aging assets justify third-party technical risk assumption.
Brazil Wind Energy Market Segmentation
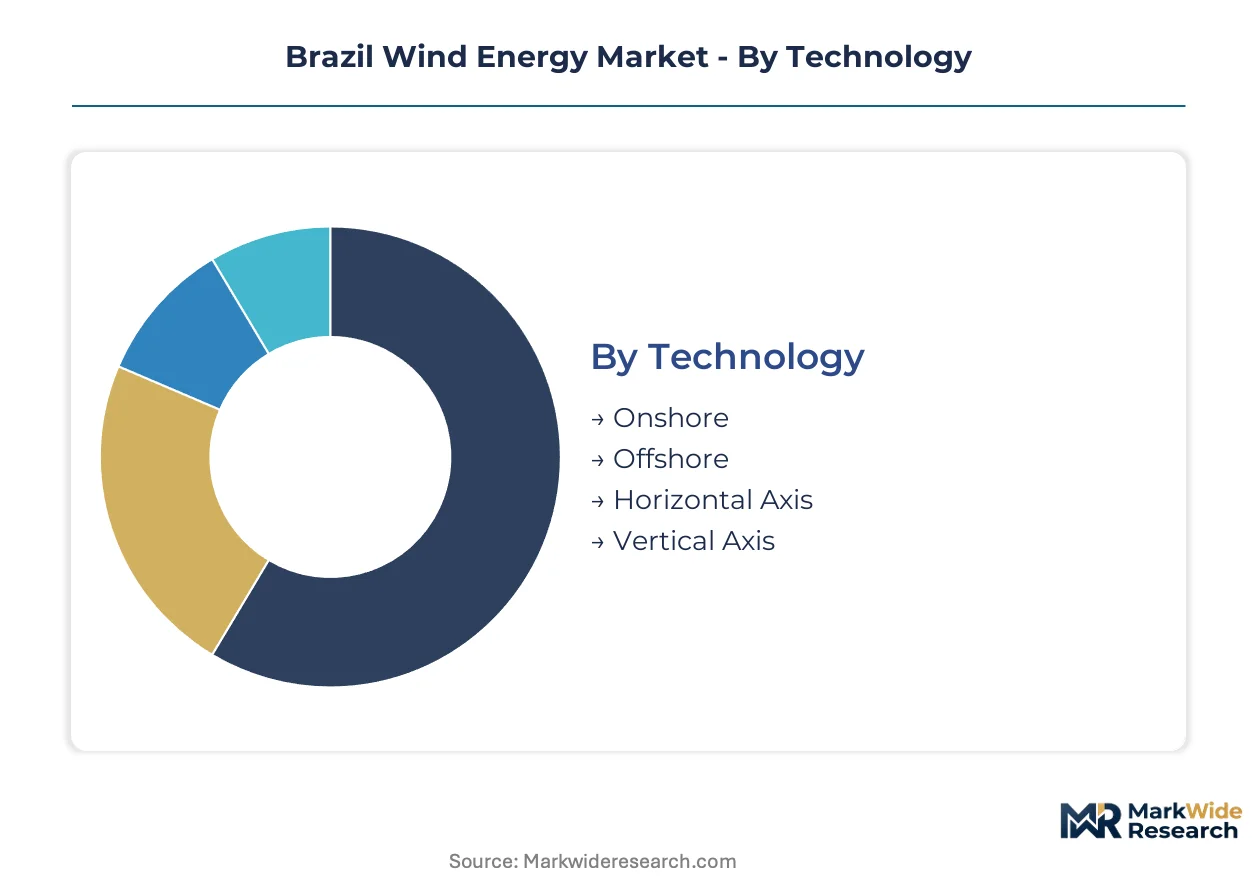
Technology choices in Brazil wind energy determine ANEEL licensing pathways and BNDES financing eligibility. End-user categories shape power purchase agreement structures and net metering access under Lei 14.300/2022.
Technology:
IBAMA environmental approvals and ANEEL grid connection permits apply differentially across turbine configurations, with offshore projects facing seabed leasing delays that onshore installations avoid.
- Onshore:Horizontal-axis turbines rated 2-6 MW dominate operational capacity across Rio Grande do Norte and Bahia corridors. Aluminum smelters and data centers in these states anchor procurement through 24/7 corporate PPAs.
- Offshore:Fixed-bottom and floating platforms await MME regulatory framework finalization for Atlantic seabed leasing. Higher capacity factors than onshore equivalents attract green hydrogen export hub developers.
- Horizontal Axis:Three-blade upwind designs optimized for Brazil's low-to-medium wind density sites.
- Vertical Axis:Darrieus and Savonius configurations for distributed generation micro-installations.
Onshore sits at the top of the volume ranking, with offshore climbing the fastest pending regulatory clarity.
End User:
Customer scale determines access to BNDES local content financing and Lei 14.300/2022 net metering benefits.
- Utilities:State-owned distributors and generation subsidiaries participate in ANEEL capacity auctions with long-term offtake guarantees. Transmission-linked project development in Bahia concentrates their procurement.
- Independent Power Producers:Merchant developers and private equity-backed platforms negotiate bilateral corporate PPAs outside auction frameworks. Rio Grande do Norte repowering portfolios dominate their asset base.
- Commercial:Industrial offtakers with captive demand under distributed generation rules.
- Residential:Individual consumers with sub-75 kW net metering eligibility.
Utilities command the largest installed base, though independent power producers are expanding most quickly through bilateral contracting.
Installation:
Project type dictates capital deployment timelines and equipment sourcing strategies under BNDES local content mandates.
- New:Greenfield development in transmission-auctioned corridors requires IBAMA licensing and ANEEL generation permits. Bahia's 500 kV expansion zones concentrate new capacity deployment.
- Repower:Replacement of aging 850 kW units from early-2000s installations in Rio Grande do Norte with modern 4-6 MW turbines. Efficiency thresholds and component obsolescence drive structural replacement demand.
- Retrofit:Control system and drivetrain upgrades to extend operational life of mid-vintage assets.
- Expansion:Capacity additions at existing substations with available grid headroom.
New installations lead absolute capacity additions, with repowering gaining share fastest as early fleet vintages reach replacement thresholds.
Capacity:
Scale tier determines project finance structures, OEM equipment availability, and O&M service contract models.
- Extra Large:Turbines exceeding 5 MW with rotor diameters above 150 meters command margin concentration in power purchase agreement bidding. Scale economies attract utility and IPP developers with access to long-dated project finance.
- Large Scale:3-5 MW units optimized for medium wind density sites in Ceará and Piauí emerging corridors.
- Medium Scale:1-3 MW configurations for commercial and industrial distributed generation.
- Small Scale:Sub-1 MW micro-turbines for rural electrification and residential net metering.
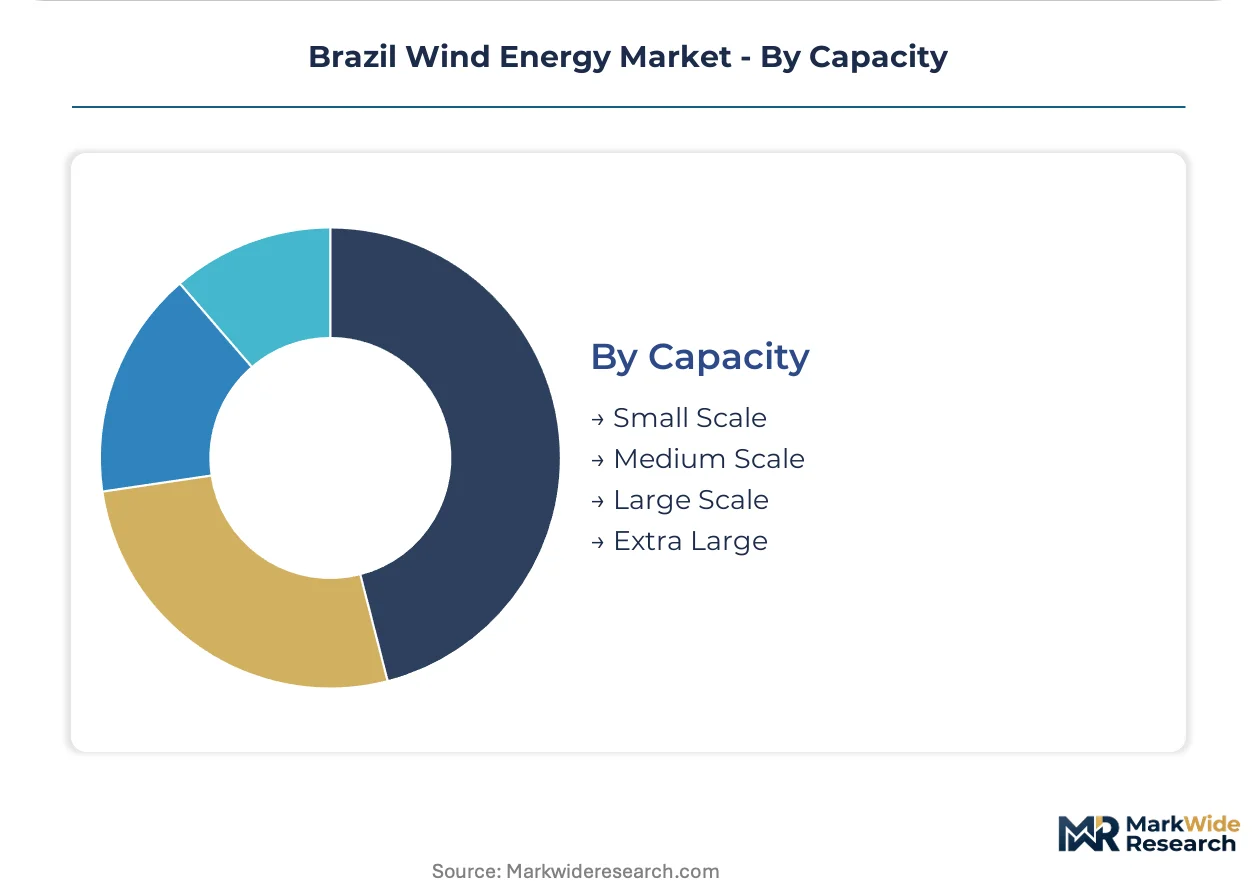
Extra large capacity dominates utility-scale procurement, while medium scale shows the steepest expansion trajectory under Lei 14.300/2022 distributed generation rules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's wind energy sector traces its commercial scale-up to the early 2000s, when ANEEL's PROINFA program catalyzed the first utility-scale installations across the Northeast corridor. State-level resource endowments and transmission infrastructure now determine deployment velocity.
Rio Grande do Norte
Aluminum smelters and data centers anchor 24/7 corporate power purchase agreements across the state's onshore wind corridors. ANEEL's distributed generation net metering rules under Lei 14.300/2022 accelerate self-production clusters near industrial zones. The state's aging 850 kW turbine fleet from early-2000s installations drives structural repowering demand independent of greenfield auction schedules.
Bahia
Transmission-linked zones concentrate utility-scale procurement as 500 kV corridor expansions unlock previously constrained wind resources. EPE's decennial energy expansion plans prioritize substation upgrades that reduce interconnection queues for new capacity. The state's medium wind density profiles attract developers seeking scale economies in power purchase agreement bidding.
Ceará
Port logistics through Pecém anchor nacelle assembly and component import operations for OEMs serving the broader Northeast region. IBAMA's environmental licensing timelines for Atlantic Forest-adjacent projects constrain site development velocity in southern municipalities. The state's technician labor pool concentrates blade repair and gearbox overhaul capabilities.
Piauí
Emerging wind corridors with medium density profiles attract large-scale turbine deployments as transmission auctions resolve grid headroom constraints. BNDES local content financing requirements shape equipment sourcing decisions for projects seeking development capital. The state's land availability supports greenfield expansion at lower land option costs than mature neighboring markets.
São Paulo
Industrial offtaker headquarters and energy trading desks coordinate corporate PPA aggregation across remote generation assets. The state's financial infrastructure anchors project finance structuring for distributed generation portfolios under Lei 14.300/2022. Grid congestion limits direct in-state development, redirecting capital toward Northeast transmission-linked zones.
Brazil Wind Energy Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology differentiation and service bundling dimensions. The market structure consolidates around three tiers: integrated utility-developers with transmission assets, pure-play independent power producers with bilateral contracting expertise, and foreign OEMs with localized assembly presence. Strategic archetypes include captive offtake aggregators, repowering specialists, and hydrogen-export hub developers. Dominant competitive moves encompass transmission integration acquisitions and third-party service agreement disintermediation.
Within the integrated utility-developer tier, Neoenergia SA and Enel Green Power Brasil exemplify players leveraging transmission integration across the Northeast to sustain project pipeline visibility. Among foreign OEMs with localized presence, Vestas Wind Systems AS and Siemens Gamesa Renewable Energy SA occupy positions differentiated by logistics cost competition and blade technology adaptation respectively. These named entities represent archetypal strategies rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Neoenergia SA |
| Vestas Wind Systems AS |
| Siemens Gamesa Renewable Energy SA |
| Nordex SE |
| ABB Ltd |
| Enel Green Power Brasil |
| GE Vernova |
| Statkraft Energias Renovaveis SA |
| 2W Energia |
| Others |
Value Chain & Pricing Dynamics
ANVISA's carbon-intensity documentation mandates for turbine component imports gate qualified supply and premium-tier pricing access, forcing developers to tier supplier qualification criteria by destination market and compressing margin structures for non-compliant equipment.
Pricing Analysis
Long-term power purchase agreement contracting with inflation-indexed escalators dominates Brazil wind energy pricing, separating utility-scale auction winners from bilateral corporate offtakers on basis risk allocation. Price differentiation rests on BNDES local content certification tier and Vestas or Siemens Gamesa brand premium for nacelle supply. Cost compression in the distributed generation segment is intensifying because Lei 14.300/2022 net metering benefits attract merchant developers without auction price floors. Aluminum smelters and data centers show least price sensitivity due to 24/7 renewable supply requirements, while commercial aggregators face acute margin pressure.
Supply Chain Analysis
Specialized blade repair and gearbox overhaul technician scarcity in Ceará and Rio Grande do Norte constrains manufacturing throughput and extends commissioning timelines for projects in emerging states. Component supply concentrates in Denmark, Spain, and China for nacelle assembly, with rare earth magnet sourcing drawing from Chinese processing facilities. Logistics chokepoints at Pecém and Suape ports create single-point vulnerability for oversized component movements. Distribution runs through OEM-integrated service networks transitioning toward independent provider disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil wind energy operates as a late-cycle quality story where premium specifications command pricing power, justified by aluminum smelter and data center demand shifts toward 24/7 renewable supply with guaranteed availability clauses.
For Market Incumbents: Extend service agreement unbundling to capture third-party maintenance margins in Rio Grande do Norte's aging fleet, while deepening backward integration into blade repair capabilities to defend against independent provider encroachment. Prioritize transmission integration acquisitions in Bahia's 500 kV expansion zones to lock in interconnection certainty before auction saturation compresses development spreads. For New Entrants and Emerging Players: Begin with corporate PPA aggregation platforms bundling sub-utility-scale offtakers into synthetic portfolios that meet project finance minimums, targeting São Paulo-based industrial headquarters with remote Northeast generation assets. Lei 14.300/2022 distributed generation rules offer the most penetrable regulatory pathway for merchant developers without auction track records. For Investors and Strategic Acquirers: Roll-up economics work for repowering specialists because Rio Grande do Norte's aging 850 kW fleet replacement demand runs independent of greenfield auction cycles and offers contracted cash flow visibility. Monitor ANEEL transmission auction schedules as inflection indicators for basis risk compression in development-stage assets.| Strategic Initiative | Industry Significance |
|---|---|
| Transmission Integration Acquisition | Secures interconnection priority in ANEEL auctioned corridors before grid congestion limits dispatch. |
| Corporate PPA Aggregation Platform | Bundles commercial offtakers into synthetic portfolios meeting BNDES project finance scale thresholds. |
| Third-Party Service Disintermediation | Compresses maintenance costs 15-25% versus OEM-integrated packages in mature Rio Grande do Norte fleet. |
| Repowering Portfolio Buildup | Captures structural replacement demand as early-2000s 850 kW turbines hit efficiency thresholds. |
| Green Hydrogen Export Hub Development | Anchors long-term offtake negotiations under MME national hydrogen strategy in transmission-linked zones. |
Study Parameters
Multiple input streams — structured interviews with utility planning officers and IPP project developers, EPC contractor bid documentation, and ANEEL regulatory filings — were reconciled against secondary validation from EPE decennial energy expansion plans, BNDES financing disbursement records, and IBAMA environmental licensing databases. Bottom-up project pipeline aggregation and top-down macro demand forecasting were triangulated to cross-check capacity deployment assumptions.
Data-stream reconciliation across technology segmentation, end-user categories, installation types, and capacity tiers informed the analytical framework over the projection horizon. CAGRs were derived from installed base evolution modeling and replacement cycle analysis. Forecast inputs incorporated ANEEL auction schedule timing, MME hydrogen strategy implementation velocity, and Lei 14.300/2022 net metering uptake curves.
Several conditions sit outside the modeled scope, including MME offshore seabed leasing framework finalization dates and Atlantic Forest corridor IBAMA licensing timeline variability. Practitioners should monitor ANEEL transmission auction award schedules and subsea cable regulatory consultations for early signals of interconnection bottleneck resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Canada Wind Energy Market