
 Wind Power Converter Systems Market | 2026-2036
Wind Power Converter Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Converter Systems Market Analytics
China's massive offshore wind build-out is rewriting supply chain geography for converter systems. ABB leverages its marine-certified drive platforms to anchor European offshore demand. Siemens sustains technology leadership through direct-drive converter integration. Sungrow Power Supply Co. Ltd competes aggressively on cost for utility-scale installations across Asia-Pacific.
Wind power converter systems transform variable-frequency generator output into grid-synchronized electricity using insulated-gate bipolar transistor stacks rated for 690 V to several kilovolts. These systems enable pitch control, reactive power management, and fault ride-through capability essential for modern turbine operation. Voltage source converters dominate installed base due to modular scalability and mature semiconductor supply chains, while multilevel converters gain traction in offshore applications where medium-voltage output reduces cable losses. Gear drive technology still occupies the majority of onshore deployments, though direct drive architectures displace gearbox-dependent systems in offshore and low-maintenance segments.
China's NMPA and GB standards, alongside EU F-Gas Regulation and CE marking requirements, shape converter thermal management design and refrigerant selection for cooling systems. The US FAA and grid interconnection standards from FERC influence turbine converter control algorithms for frequency response and voltage regulation. Stakeholders must monitor semiconductor substrate transitions from silicon to silicon carbide, as this material shift promises efficiency gains but demands recalibration of qualification protocols and supplier qualification timelines.
Market Dynamics
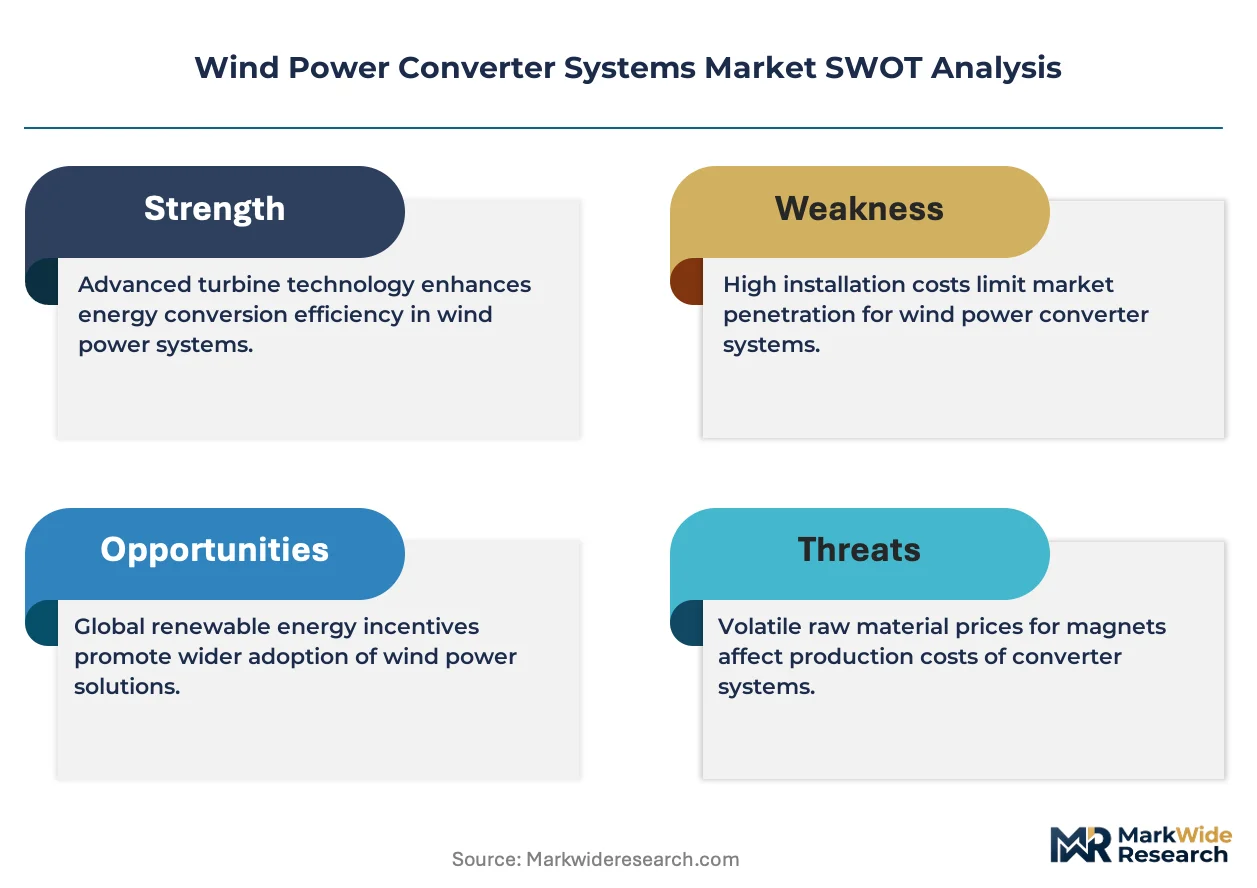
Silicon carbide semiconductor substrates are forcing a wholesale recalibration of converter qualification protocols, compressing supplier timelines while unlocking efficiency thresholds that silicon-based insulated-gate bipolar transistors cannot reach.
Growth Catalysts
- Offshore wind build-out:China's coastal provinces are commissioning multi-gigawatt arrays that demand medium-voltage converter architectures with fault ride-through capability certified to GB standards.
- F-Gas Regulation:The EU mandate on fluorinated greenhouse gases is accelerating thermal management redesign, pushing converter manufacturers toward liquid-cooled platforms that eliminate refrigerant-dependent systems.
- Grid code harmonization:Synchronized frequency response requirements under FERC interconnection rules and Chinese dispatch protocols are refreshing installed base control algorithms.
Market Restraints
- Silicon carbide substrate scarcity:Wafer supply concentrates among Japanese and US substrate specialists, creating qualification bottlenecks for converter original equipment manufacturers.
- Medium-voltage cable costs:Offshore array interconnection requires specialized subsea cabling whose copper and aluminum pricing volatility directly impacts project returns.
- Direct-drive generator compatibility:Full-power converter architectures face integration friction with legacy doubly-fed induction generator fleets, limiting retrofit applicability.
Strategic Opportunities
- Floating offshore platforms:Japan's forthcoming commercial arrays present first-mover positioning for motion-compensated converter enclosures rated to maritime vibration standards.
- Servitization models:Power purchase agreement structures are unbundling converter availability guarantees from turbine supply contracts, creating recurring revenue streams for specialized service providers.
- Silicon carbide qualification protocols:IEC working groups are drafting accelerated life-testing standards that will compress certification cycles for next-generation semiconductor stacks.
Industry Challenges
- Power electronics engineering scarcity:Converter control firmware development requires specialized expertise in grid-forming inverters that outstrips current graduate program output.
- Multi-standard certification burden:Simultaneous CE marking, GB compliance, and UL listing for a single product platform extends time-to-revenue by twelve to eighteen months.
- Legacy turbine integration complexity:Retrofit converter installations must synchronize with existing pitch control systems and supervisory control architectures without full turbine replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Converter Systems Market |
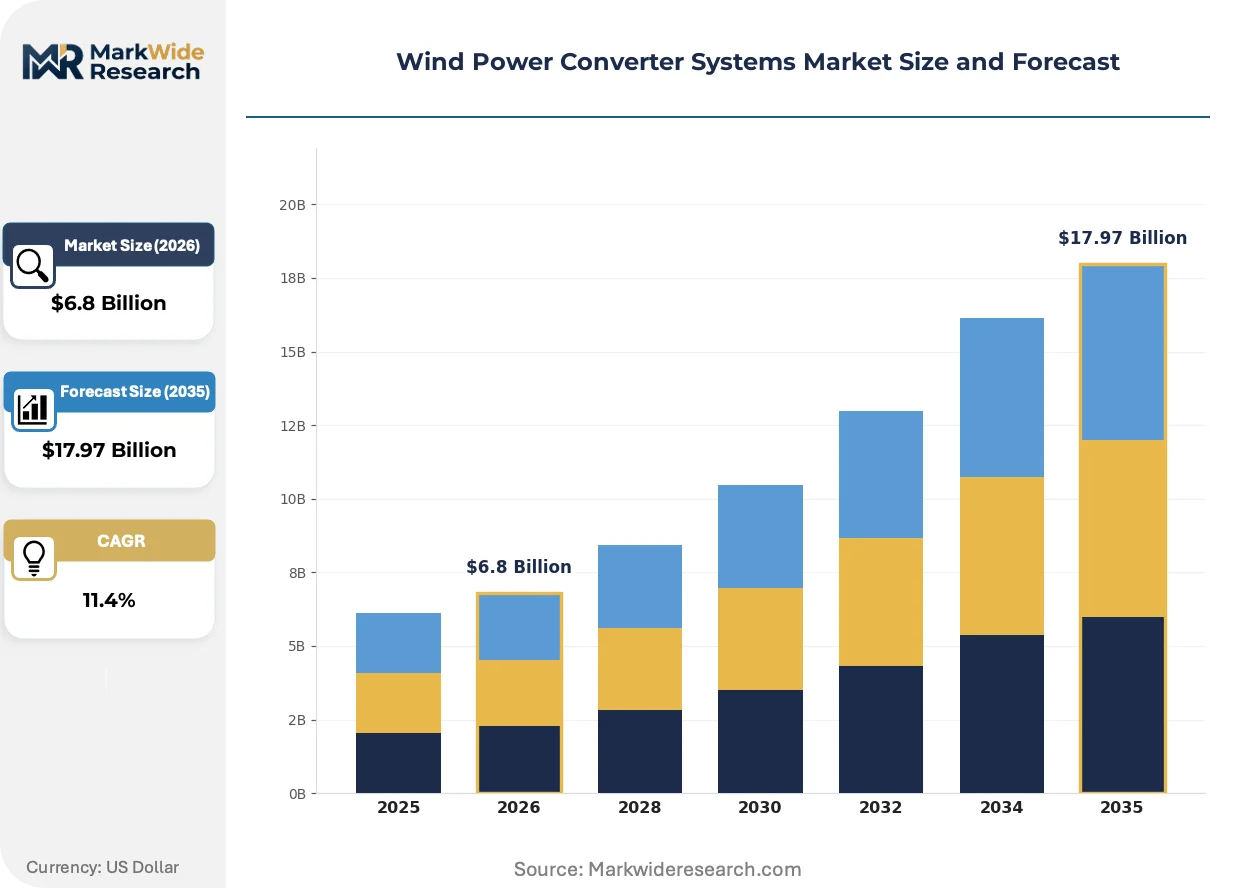
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Source Converters, Current Source Converters, Multilevel Converters, Grid Converters Technology: Direct Drive, Gear Drive, Induction Generators, Synchronous Generators End User: Utility Scale, Commercial, Residential, Offshore Application: Energy Storage, Power Generation, Grid Integration, Renewable Energy |
| Companies Covered | ABB, Alstom, Sungrow Power Supply Co. Ltd, AMSC Windtec, Schneider, Siemens, Emerson, Vacon, Ingeteam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Converter Systems Market Evolving Landscape
Digital twin architectures are virtualizing converter development workflows, compressing prototype iterations while enabling predictive maintenance models that shift operational expenditure structures for offshore asset operators.
Modular multilevel converter topologies are virtualizing the traditional voltage source converter paradigm by stacking series-connected cells to achieve medium-voltage output without transformer step-up. Offshore developers in the North Sea and China's Jiangsu province are specifying these architectures for 66 kV array collection systems. The technology is virtualizing cable loss calculations, enabling longer inter-turbine distances that reshape wind farm layout optimization.
The EU F-Gas Regulation is banning refrigerants with global warming potential above specified thresholds, forcing converter manufacturers to abandon vapor-compression cooling in favor of liquid-cooled cold plate designs. This thermal management pivot demands recalibration of enclosure sealing standards and corrosion protection protocols. German and Danish converter suppliers are responding with marine-grade aluminum cold plate platforms rated for twenty-five-year salt spray exposure.
Buyer consolidation among European utility-scale developers is compressing converter procurement cycles from multi-year framework agreements to single-tender project awards. This contracting model shift is disintermediating traditional distributor relationships and forcing direct manufacturer engagement with engineering-procurement-construction contractors. The pattern is most visible in German and UK offshore auctions where converter availability guarantees now determine turbine selection outcomes.
Wind Power Converter Systems Market Segmentation
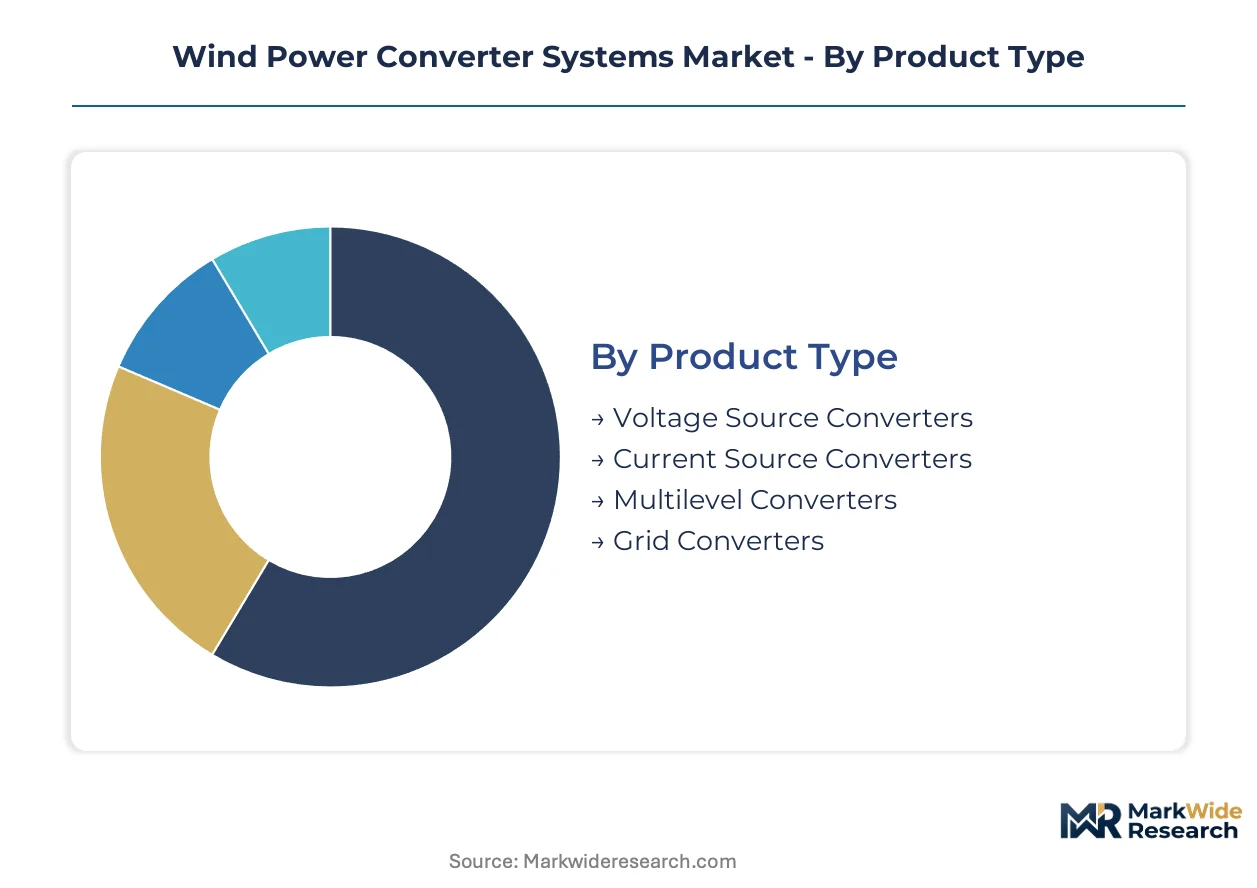
Converter segmentation reveals how turbine architecture, grid connection requirements, and installation environment shape procurement decisions. Each dimension carries distinct technical specifications, certification burdens, and supplier qualification criteria that determine competitive positioning.
Product Type:
Use-case spectrum spans onshore utility installations requiring cost-optimized standard platforms through offshore arrays demanding fault-tolerant medium-voltage architectures.
- Voltage Source Converters:Modular IGBT-based stacks dominate installed base through mature semiconductor supply chains and standardized 690 V output ratings. Demand concentrates in German and Chinese onshore utility fleets where grid code harmonization under FERC and GB standards drives control algorithm refresh cycles.
- Multilevel Converters:Stacked series-connected cell architectures achieve medium-voltage output without transformer step-up, reducing cable losses across extended inter-turbine distances. China's Jiangsu province and North Sea developers specify these systems for 66 kV collection networks where array layout optimization demands longer transmission spans.
- Current Source Converters:Thyristor-based designs persist in legacy installations requiring minimal control complexity.
- Grid Converters:Specialized synchronization equipment for hybrid renewable-storage installations.
The dominant share belongs to Voltage Source Converters, while Multilevel Converters is closing the gap fastest.
Technology:
Cost tier differentiation separates premium direct-drive architectures from standardized gearbox-dependent systems.
- Direct Drive:Permanent magnet synchronous generators eliminate gearbox maintenance burdens through full-power converter integration. Siemens anchors European offshore demand with integrated direct-drive platforms rated for salt spray exposure and maritime vibration standards.
- Gear Drive:Doubly-fed induction generator configurations retain cost advantages in onshore deployments where maintenance access remains economical. Gearbox-dependent systems face retrofit friction against full-power converter architectures, limiting upgrade pathways for installed base fleets.
- Induction Generators:Squirrel-cage designs serve emerging markets with simplified control requirements.
- Synchronous Generators:Wound-rotor variants enable variable-speed operation in specific grid conditions.
Direct Drive commands premium pricing in offshore applications, though Gear Drive retains volume leadership across onshore installations.
End User:
Customer type determines procurement scale, financing structure, and availability guarantee requirements.
- Utility Scale:Multi-gigawatt developers negotiate framework agreements with converter availability guarantees tied to turbine selection outcomes. Procurement compression from multi-year contracts to single-tender awards is disintermediating traditional distributor relationships in German and UK offshore auctions.
- Offshore:Floating platform arrays in Japan and fixed-bottom installations in China's coastal provinces demand motion-compensated enclosures and medium-voltage output. EU F-Gas Regulation is accelerating thermal management redesign toward liquid-cooled cold plate systems.
- Commercial:Distributed generation portfolios below 50 MW with standardized interconnection protocols.
- Residential:Small-scale installations with simplified grid-tie inverter requirements.
Utility Scale absorbs the majority of converter volume, while Offshore is expanding most quickly.
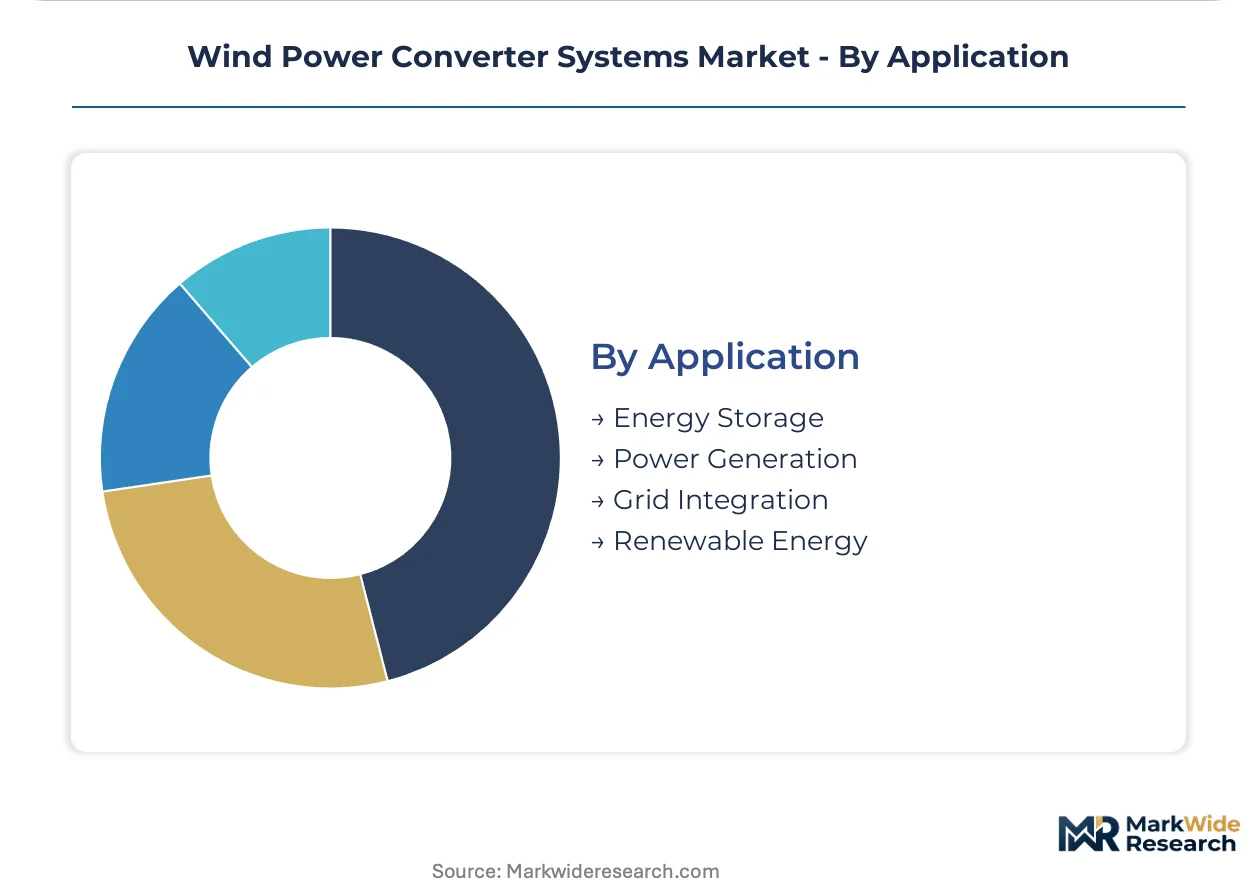
Application:
Maturity gradient separates established power generation deployments from emerging grid integration and storage hybrid configurations.
- Power Generation:Baseline wind-to-electricity conversion represents the foundational use case with standardized fault ride-through and reactive power management requirements. Grid code harmonization under EU and Chinese regulations refreshes control algorithm specifications across installed base.
- Energy Storage:Battery-hybrid converter platforms enable frequency regulation and arbitrage revenue streams. Digital twin architectures are virtualizing development workflows for storage-integrated systems.
- Grid Integration:Grid-forming inverter capabilities for weak-grid and islanded operation.
- Renewable Energy:Multi-technology hybrid installations combining wind with solar or hydrogen production.
Power Generation maintains foundational volume, while Energy Storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards from China's NMPA anchor converter qualification protocols for the fastest-expanding offshore wind segment. FERC interconnection rules and EU F-Gas Regulation shape competing certification frameworks across the three dominant demand geographies.
China
Jiangsu province commissions multi-gigawatt fixed-bottom arrays requiring medium-voltage converter architectures. GB standards mandate fault ride-through capability for coastal installations. Yangtze River Delta converter suppliers are scaling liquid-cooled cold plate production for salt spray exposure.
Germany
North Sea offshore auctions compress procurement cycles from framework agreements to single-tender awards. EU F-Gas Regulation bans high-global-warming-potential refrigerants, forcing thermal management redesign. Hamburg and Bremerhaven industrial clusters are certifying marine-grade aluminum enclosures for twenty-five-year service life.
United States
FERC Order 2023 synchronizes frequency response requirements across interconnection queues. Texas and California utility-scale developers negotiate converter availability guarantees tied to turbine selection. Gulf Coast fabrication yards are tooling for motion-compensated enclosures targeting floating platform arrays.
Japan
METI feed-in-tariff revisions accelerate commercial floating offshore wind timelines. JIS standards govern maritime vibration certification for converter systems. Kyushu and Chubu regional developers are specifying medium-voltage architectures for 66 kV collection networks.
United Kingdom
Contracts for Difference auctions drive offshore capacity additions in North Sea lease areas. CE marking and marine certification requirements extend product qualification timelines. Scottish and East Anglian project pipelines are absorbing converter volume from compressed tender schedules.
Wind Power Converter Systems Market Competitive Landscape
Capability concentration sits with European specialists holding marine certification expertise; scale advantage sits with Asia-Pacific fabricators serving utility-volume procurement. The market structures around three tiers: integrated turbine-converter platforms, independent power electronics suppliers, and regional system integrators. Dominant competitive moves include backward integration into semiconductor qualification workflows and geographic expansion through engineering-procurement-construction contractor partnerships.
Within the integrated platform tier, ABB and Siemens exemplify archetypes combining marine-certified drive expertise with direct-drive generator integration. Sungrow Power Supply Co. Ltd occupies a position among Asia-Pacific scale specialists competing on cost for utility-scale installations. These three anchors illustrate the geographic bifurcation between European capability concentration and Asia-Pacific volume leadership.
| Leading Market Players |
|---|
| ABB |
| Alstom |
| Sungrow Power Supply Co. Ltd |
| AMSC Windtec |
| Schneider |
| Siemens |
| Emerson |
| Vacon |
| Ingeteam |
| Others |
Value Network & Pricing Analysis
Yantian-to-Rotterdam container rates compress converter procurement margins while amplifying price spreads between Asia-Pacific fabricators and European marine-certified suppliers. This freight corridor's volatility feeds directly into landed cost differentiation, with liquid-cooled cold plate platforms commanding premium positioning against air-cooled alternatives in offshore tenders.
Pricing Analysis
Geographic price spreads between Chinese utility-scale suppliers and German marine-certified specialists exceed two-to-one for equivalent power ratings. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked offshore platforms from GB-compliant domestic Chinese systems and legacy retrofit configurations. Cost compression in standard-tier onshore converters is intensifying because Sungrow and domestic Yangtze River Delta suppliers are scaling IGBT stack production for multi-gigawatt framework agreements. Utility-scale developers in Texas and Jiangsu province exhibit highest price sensitivity, while North Sea floating platform developers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Silicon carbide wafer feedstock draws from Japanese substrate specialists and US wafer manufacturers, creating qualification bottlenecks for converter original equipment manufacturers. German and Danish industrial clusters anchor final assembly capacity for marine-grade aluminum enclosures, while Chinese provinces of Jiangsu and Guangdong concentrate IGBT module packaging and liquid-cooled cold plate fabrication. Single-source vulnerability concentrates in silicon carbide substrate supply, with Japanese and US specialists controlling wafer output. Distribution runs through direct manufacturer engagement with engineering-procurement-construction contractors, disintermediating traditional distributor relationships in compressed German and UK offshore tender schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converter availability guarantees and predictive maintenance contracts are expanding faster than hardware revenue, creating service-attach economics that favor integrated platform providers over component specialists. Recurring revenue from performance-based O&M agreements now determines project financeability in offshore auctions.
For Market Incumbents: Entrench marine certification expertise through accelerated silicon carbide qualification protocols and backward integration into semiconductor substrate partnerships. ABB and Siemens should expand Hamburg and Bremerhaven cold plate production capacity before EU F-Gas Regulation deadlines eliminate refrigerant-dependent competitors. Threat substitution from Chinese cost-optimized suppliers demands CE marking differentiation through twenty-five-year salt spray warranties.
For New Entrants and Emerging Players: Establish a beachhead in Japan's floating offshore wind segment where motion-compensated enclosure standards create first-mover protection against established European suppliers. METI feed-in-tariff revisions and JIS maritime vibration certification requirements present white-space positioning absent Chinese price competition. Kyushu and Chubu regional developers offer go-to-market entry through 66 kV collection network specifications.
For Investors and Strategic Acquirers: Power electronics engineering boutiques with grid-forming inverter firmware capabilities represent priority acquisition targets as graduate program output fails to match demand. Long-term viability hinges on converter servitization economics displacing transactional hardware procurement. Watch IEC accelerated life-testing standard finalization as inflection signal compressing silicon carbide certification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Qualification Acceleration | IEC working group standards compress certification timelines for next-generation semiconductor stacks. |
| Liquid-Cooled Cold Plate Manufacturing Scale-Up | EU F-Gas Regulation bans drive thermal management redesign toward marine-grade aluminum platforms. |
| Floating Platform Converter Enclosure Development | Japan's METI tariffs create first-mover positioning for motion-compensated systems rated to JIS vibration standards. |
| Servitization Model Implementation | Power purchase agreement structures unbundle availability guarantees from turbine supply contracts. |
| Direct EPC Contractor Engagement | Compressed German and UK offshore tender schedules disintermediate traditional distribution channels. |
Research Methodology
A standing panel of converter control firmware engineers, offshore project developers, EPC procurement directors, and grid interconnection specialists provided ongoing calibration against secondary validation from FERC filings, NMPA GB standard drafts, EU F-Gas Regulation impact assessments, and IEA wind technology roadmaps. Primary interviews with plant engineers at Jiangsu province array installations and Hamburg industrial cluster suppliers combined with customs data on semiconductor substrate trade flows. Bottom-up stack-up from turbine OEM converter specifications and top-down triangulation against national wind capacity targets anchored volume estimates.
Scenario-bracketing around silicon carbide adoption velocity and floating offshore wind commercialization timelines shaped analytical framework construction across the analysis window. Segmentation modeling spanned converter topology, generator integration architecture, end-user procurement scale, and regional regulatory cluster. CAGRs derived from installed capacity pipeline analysis and technology refresh cycle assumptions. Forecast inputs incorporated grid code harmonization schedules under FERC Order 2023 and Chinese dispatch protocols alongside EU thermal management regulation compliance deadlines.
Sensitivities concentrate around silicon carbide substrate supply expansion, offshore cable commodity pricing volatility, and graduate program output for power electronics engineering specialization. Forecasts reflect assumptions on semiconductor material transitions and qualification protocol evolution. Cross-checking against IEA technology cost benchmarks and national wind auction award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
France Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Wind Power SCADA Market