
 Bladeless Wind Turbines Market | 2026-2036
Bladeless Wind Turbines Market Size, Share, and Industry Trends Forecast 2026-2036
Bladeless Wind Turbines Market Intelligence
Spain's push for distributed renewable generation is fragmenting the traditional wind energy supplier base. Vortex Bladeless, a key innovator from Spain, specializes in its namesake vortex-induced vibration technology. Aeromine Technologies competes with a distinct rooftop-integrated design for commercial buildings. Meanwhile, Katrick Technologies positions its solutions for low-wind speed environments, targeting niche applications.
Bladeless wind turbines generate electricity from wind without using rotating blades, often harnessing aerodynamic instability. These systems typically rely on principles like vortex-induced vibration, where a mast oscillates in the wind to produce energy. Vortex-Induced Vibration technology currently leads development, but Piezoelectric Generation offers potential for smaller-scale devices. Remote Power Supply and Telecommunications applications are expanding quickly due to the technology's lower noise and smaller physical footprint.
International Electrotechnical Commission (IEC) standards for wind turbines are being adapted to cover these novel designs, impacting market access. Concurrently, municipal zoning regulations in the United States and Germany influence urban deployment feasibility and permitting timelines. Stakeholder focus now turns to demonstrating long-term operational reliability and achieving cost-parity with conventional distributed generation technologies.
Market Dynamics
The push for decentralized energy generation in noise-sensitive urban and remote locations is the central force shaping the market. This demand pattern favors the technology's smaller footprint and lower acoustic profile, creating a distinct niche separate from utility-scale wind farms.
Growth Catalysts
- Policy Support:Incentives under frameworks like the EU Green Deal are accelerating investment into novel renewable technologies, including bladeless systems, to meet distributed generation targets.
- Telecommunications Demand:The expansion of 5G networks requires reliable, low-maintenance power sources for remote towers and edge computing nodes, an ideal application for this technology.
- Urban Integration:Architectural and municipal planning demand in countries like Spain is concentrating on aesthetic, low-impact energy solutions that can be integrated directly onto building rooftops and public infrastructure.
Market Restraints
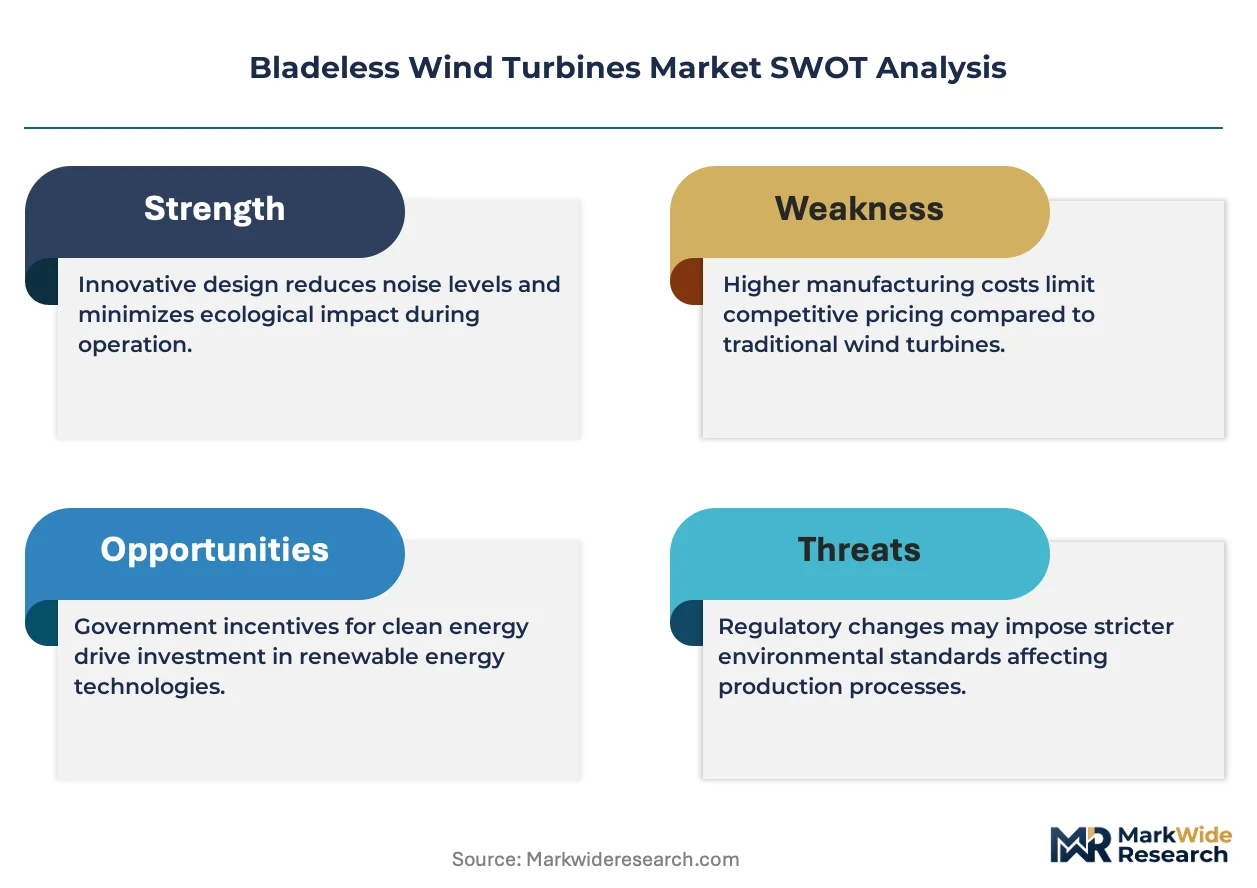
- High Initial Cost:The technology faces challenges achieving cost-parity with established distributed generation alternatives, primarily rooftop solar photovoltaics, which have mature manufacturing scales.
- Performance Limitations:Vortex-induced vibration systems exhibit lower energy conversion efficiency compared to traditional turbines, particularly in areas with inconsistent or low-velocity wind patterns.
- Regulatory Uncertainty:Ambiguous municipal zoning codes and a lack of specific permitting pathways in many United States and German cities create project delays and increase deployment costs.
Strategic Opportunities
- Hybrid Energy Solutions:Pairing bladeless turbines with solar panels and battery storage creates resilient, 24-hour power systems for commercial buildings, microgrids, and critical infrastructure.
- Piezoelectric Technology Advancement:The development of more efficient piezoelectric materials presents an opportunity to scale down devices for low-power applications, such as wireless sensor networks and IoT devices.
- Remote Agricultural Power:There is an untapped market in providing power for automated irrigation systems, environmental monitoring, and robotic equipment in off-grid agricultural zones.
Industry Challenges
- Demonstrating Long-Term Reliability:A primary challenge is the lack of extensive, long-term operational data to validate system durability and performance, which is a prerequisite for securing project financing.
- Certification and Standardization:The process of adapting International Electrotechnical Commission (IEC) standards to cover novel aerodynamic and generation principles is complex and time-consuming, slowing market access.
- Specialized Workforce Scarcity:A shortage of technicians and engineers with expertise in the installation and maintenance of oscillation-based energy systems constrains the ability to scale deployments globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bladeless Wind Turbines Market |
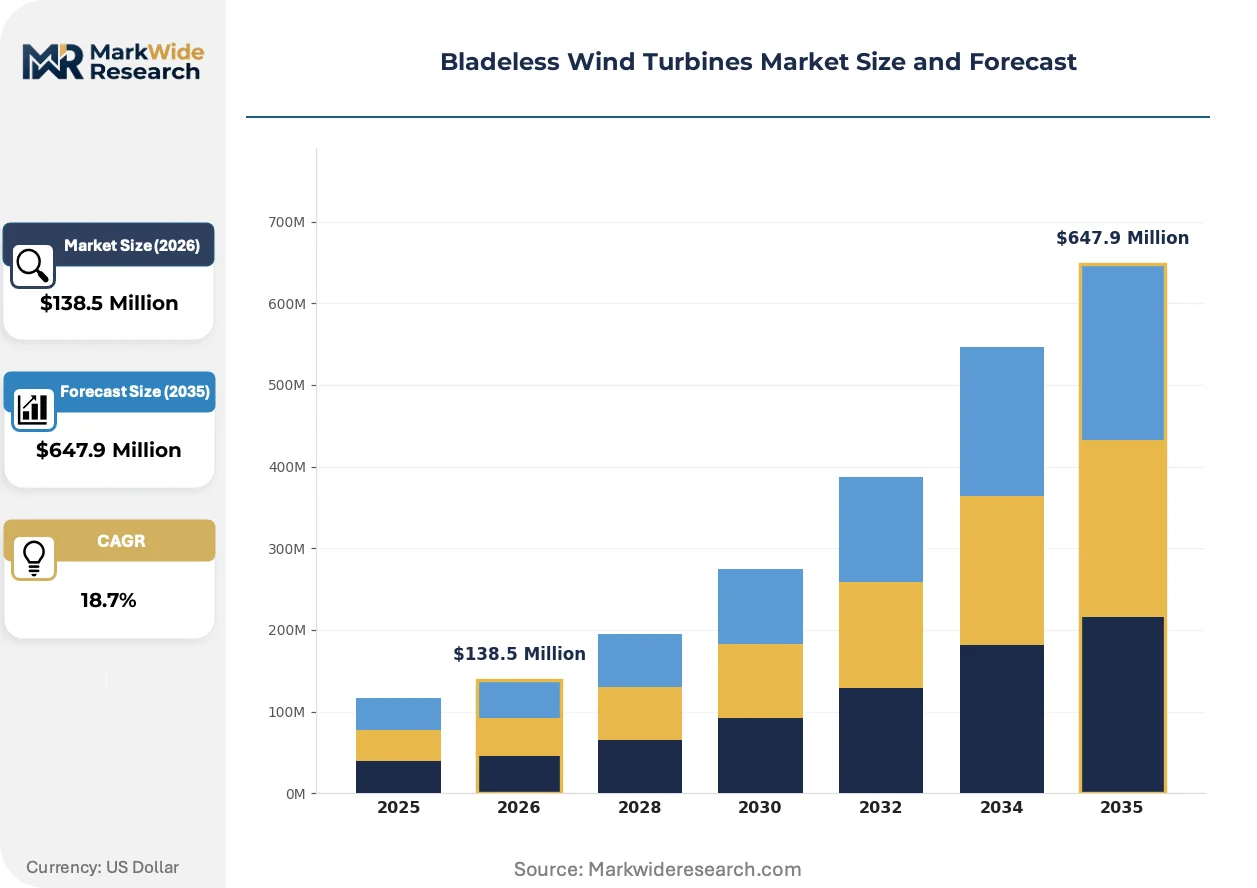
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $647.9 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vortex-Induced Vibration, Piezoelectric Generation, Electrostatic Generation, Magnetic Induction, Oscillatory Motion Application: Grid Integration, Remote Power Supply, Telecommunications, Military Installations, Marine Buoys End User: Energy Companies, Telecom Operators, Government Entities, Research Institutes, Utility Providers Installation Type: Onshore Deployment, Offshore Deployment, Urban Settings, Isolated Locations |
| Companies Covered | Halcium Energy, Katrick Technologies, Aeromine Technologies, Innoventum, EWICON, Vortex Bladeless, SheerWind, Aurea Technologies, Saphon Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bladeless Wind Turbines Market Strategic Shifts & Innovations
Innovation is focused on optimizing energy capture from aerodynamic instability and integrating these systems into specific, high-value applications. Material science advancements and sophisticated modeling are enabling designs tailored for urban and remote power generation where traditional turbines are impractical.
Vortex-Induced Vibration (VIV) technology harnesses wind-driven oscillations in a semi-rigid mast to generate electricity. Telecommunications operators and remote infrastructure managers are the primary adopters due to the system's low maintenance needs. This technology is collapsing the functional boundary between structural masts and energy assets, enabling passive infrastructure to become an active power source.
Revised International Electrotechnical Commission (IEC) standards are being developed to encompass non-traditional wind energy converters. This regulatory evolution provides a crucial framework for validating safety, performance, and reliability, which is essential for bankability and insurance. Technology developers in Spain and the United States are now aligning their designs with these emerging IEC criteria to ensure future market compliance.
Demand is shifting from purchasing standalone components to procuring fully integrated remote power systems that include generation, storage, and controls. This trend disintermediates traditional electrical parts distributors in favor of specialized system integrators who can deliver a turnkey solution. This shift is most visible within the Telecommunications sector for powering off-grid cell sites and remote industrial monitoring installations.
Bladeless Wind Turbines Market Segmentation
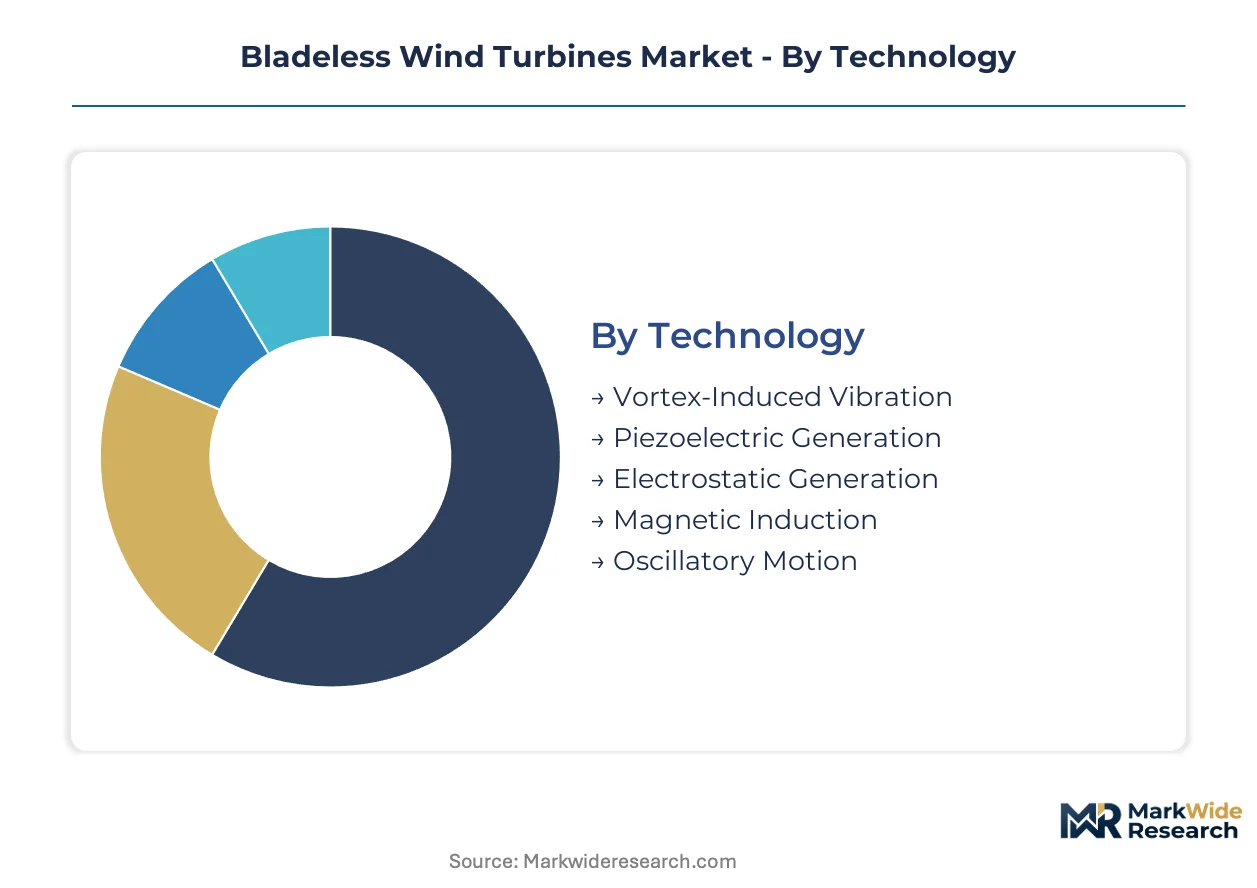
The bladeless wind turbines market exhibits diverse segmentation, reflecting varied technological approaches and distinct application environments. Understanding these segments helps clarify the specific value propositions and operational considerations for different market participants.
Technology:
After-sales service intensity varies significantly across bladeless turbine technologies, influenced by system complexity and operational principles.
- Vortex-Induced Vibration:This technology harnesses aerodynamic instability, causing a mast to oscillate in the wind to generate electricity. Demand is concentrating within the telecommunications sector and for remote infrastructure managers due to the system's inherent low maintenance needs and ability to transform passive structures into active power sources.
- Piezoelectric Generation:Piezoelectric materials convert mechanical stress directly into electrical energy, enabling compact, solid-state devices. Adoption is expanding for smaller-scale devices, wireless sensor networks, and IoT applications, driven by the potential for miniaturization and energy harvesting in low-power scenarios.
- Electrostatic Generation:This method generates electricity by harnessing charge differences created by wind flow over specialized surfaces.
- Magnetic Induction:Magnetic induction systems utilize moving magnets within coils to produce electrical currents from wind-driven motion.
- Oscillatory Motion:This broad category encompasses various non-rotary designs that convert kinetic energy from wind into electricity through repetitive movement.
By volume, Vortex-Induced Vibration technology leads. By growth pace, Piezoelectric Generation is ahead.
Application:
Different customer types prioritize distinct application features, influencing the design and deployment of bladeless wind turbine systems.
- Telecommunications:These applications involve powering remote cell towers, base stations, and edge computing nodes where grid access is limited or unreliable. The expansion of 5G networks specifically requires reliable, low-maintenance power sources for widespread deployment.
- Remote Power Supply:This segment covers providing electricity to off-grid locations, critical infrastructure, and isolated industrial sites. Hybrid energy solutions pairing bladeless turbines with solar panels and battery storage create resilient, 24-hour power systems.
- Grid Integration:Systems designed for grid integration feed generated electricity directly into national or regional power grids, supporting distributed generation initiatives.
- Military Installations:Bladeless turbines power defense sites, surveillance equipment, and remote outposts, providing secure, off-grid energy solutions.
- Marine Buoys:These applications involve powering oceanic sensors, navigational aids, and data collection platforms in harsh maritime environments.
Strategic importance drives investment in Telecommunications applications, while Remote Power Supply offers significant market expansion opportunities.
End User:
The scale of deployment often dictates the end-user segment, with larger entities driving higher volume procurement and smaller ones focusing on niche solutions.
- Telecom Operators:These entities deploy bladeless turbines to power their extensive network infrastructure, particularly for remote and off-grid cell sites. The demand for reliable, low-noise power for critical communication facilities is a primary driver.
- Utility Providers:Utilities integrate distributed generation solutions into their existing energy grids, often for urban settings and isolated communities. Policy support for decentralized energy and renewable targets encourages adoption within this segment.
- Energy Companies:These companies explore novel renewable energy sources to diversify their portfolios and meet sustainability objectives.
- Government Entities:Government bodies support public infrastructure projects, defense applications, and environmental monitoring initiatives using bladeless turbine technology.
- Research Institutes:Academic and private research institutions focus on advancing the technology, validating performance, and exploring new material science applications.
Telecom Operators exert substantial market influence, while Utility Providers represent a critical channel for broader market adoption.
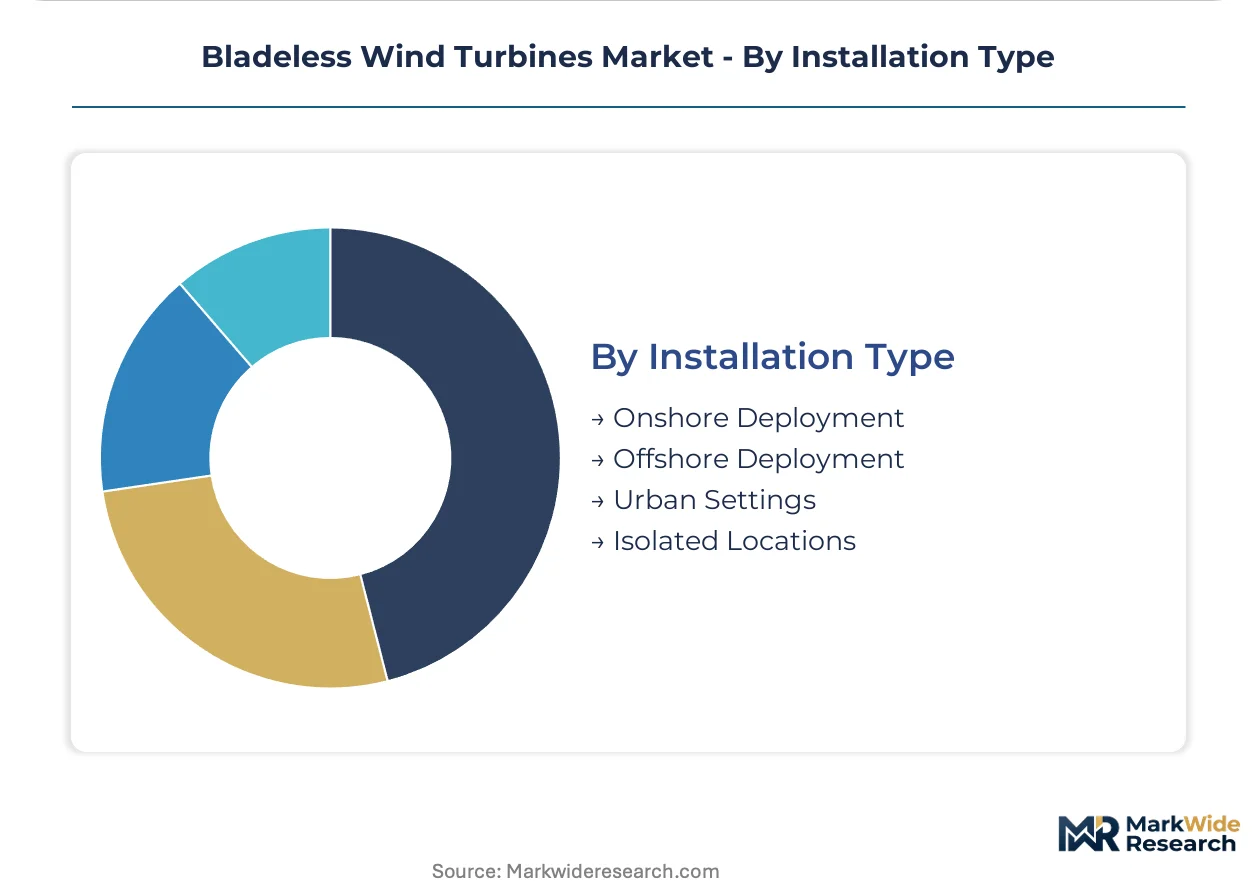
Installation Type:
The maturity of deployment scenarios varies, with established onshore applications contrasting with emerging urban and offshore installations.
- Urban Settings:This installation type involves integrating bladeless turbines directly onto building rooftops, public infrastructure, and within city limits. Architectural and municipal planning demand in countries like Spain concentrates on aesthetic, low-impact energy solutions for these environments.
- Isolated Locations:These deployments target remote sites, off-grid agricultural zones, and distant industrial facilities where traditional grid access is impractical or expensive. The technology's low maintenance needs make it ideal for powering telecommunications towers and automated irrigation systems in such areas.
- Onshore Deployment:Ground-mounted systems in diverse terrains characterize onshore deployments, often serving a range of commercial and industrial applications.
- Offshore Deployment:This involves installing bladeless turbines in marine environments, requiring specialized foundations and robust designs to withstand harsh sea conditions.
Urban Settings and Isolated Locations represent the fastest-growing trajectories, reflecting the technology's unique advantages in these challenging environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal incentives are accelerating investment into novel renewable energy solutions across the continent, directly influencing bladeless wind turbine adoption. This policy support, coupled with national distributed generation targets, drives regional market expansion. Diverse regulatory landscapes and urban planning requirements shape deployment patterns in key countries.
Spain
Spain’s push for distributed renewable generation concentrates demand for bladeless turbines in urban settings and isolated locations. Incentives under the EU Green Deal specifically encourage such novel energy solutions within Spanish municipalities. Barcelona and Madrid explore aesthetic, low-impact energy solutions for direct integration onto building rooftops and public infrastructure.
United States
Demand in the United States stems from the need for decentralized energy generation in remote and noise-sensitive areas. Ambiguous municipal zoning codes and a lack of specific permitting pathways in many US cities create project delays. California and Texas represent significant markets for remote power supply to critical infrastructure and telecommunications towers.
Germany
Germany's focus on urban deployment and renewable energy targets drives interest in bladeless wind turbines. Municipal zoning regulations in German cities influence urban deployment feasibility and permitting timelines. Berlin and Hamburg evaluate low-noise, compact energy solutions for integration into dense urban environments and industrial parks.
China
China's extensive infrastructure development and 5G network expansion generate demand for reliable, low-maintenance power sources. The country's dual carbon goals provide a strategic impetus for exploring diverse renewable energy technologies. Shenzhen and Shanghai see integration of bladeless systems into smart city initiatives and remote industrial monitoring.
India
India requires off-grid power solutions for its vast rural and telecommunications sectors, creating a market for bladeless turbines. The PLI scheme for renewable energy manufacturing could indirectly support local production and deployment. Karnataka and Maharashtra present opportunities for powering automated irrigation systems and remote cell sites.
Bladeless Wind Turbines Market Key Industry Players
Specialized innovators and established energy solution providers split the market for bladeless wind turbines. The competitive landscape features technology-focused startups alongside larger entities exploring portfolio diversification. Strategic partnerships and technology licensing are common competitive moves to accelerate market penetration and expand geographic reach.
Among specialized innovators, Vortex Bladeless, a key innovator from Spain, exemplifies the vortex-induced vibration technology segment, focusing on low-maintenance solutions for remote infrastructure. Aeromine Technologies competes with a distinct rooftop-integrated design for commercial buildings, demonstrating a clear focus on urban integration and commercial applications. Katrick Technologies positions its solutions for low-wind speed environments, targeting specific niche applications in distributed generation where traditional turbines are impractical. These companies collectively anchor the market's innovation trajectory.
| Leading Market Players |
|---|
| Halcium Energy |
| Katrick Technologies |
| Aeromine Technologies |
| Innoventum |
| EWICON |
| Vortex Bladeless |
| SheerWind |
| Aurea Technologies |
| Saphon Energy |
| Others |
Cost & Logistics Intelligence
Spanish innovation clusters are shaping the cost structure of bladeless wind turbine systems. Their specialized manufacturing capabilities influence market pricing across different application segments.
Pricing Analysis
Geographic price spreads for bladeless wind turbines vary significantly, influenced by regional policy support and regulatory hurdles. The dominant pricing model is project-based, often incorporating long-term service agreements for remote deployments. Price differentiation stems from system performance tiers and the level of integrated after-sales service. Pricing softness stems from the high initial cost compared to mature alternatives like rooftop solar photovoltaics, making remote agricultural applications particularly cost-conscious, unlike less sensitive telecom operators.
Supply Chain Analysis
International Electrotechnical Commission (IEC) standards, acting as market access controls, influence the global supply flow of bladeless turbine components. Supply concentration for specialized components draws from manufacturing hubs in China, alongside innovation centers in Spain and the United States. The market relies on advanced piezoelectric materials and high-performance composite structures. Regulatory uncertainty and complex certification processes present a structural risk, causing project delays. Distribution runs primarily through specialized system integrators who deliver turnkey remote power solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is undergoing a platform-economics inflection, driven by the emergence of integrated remote power systems. These systems combine generation, storage, and controls into a cohesive energy ecosystem.
For Market Incumbents: Entrench market position by accelerating investment into long-term operational reliability studies and performance validation. Form strategic partnerships to offer hybrid energy solutions that integrate solar and battery storage. This counters the threat of cost-parity challenges from established distributed generation alternatives like rooftop solar. Focus on IEC certification investment to ensure broad market access and regulatory compliance.
For New Entrants and Emerging Players: Pursue niche applications where traditional wind solutions are impractical or undesirable. Target remote agricultural power for automated irrigation systems as a white-space opportunity. Develop smaller-scale piezoelectric devices for wireless sensor networks and IoT applications, leveraging their potential for miniaturization. A focused go-to-market angle emphasizes ultra-low maintenance and silent operation for noise-sensitive environments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized innovators demonstrating proven operational reliability and clear pathways to cost-parity. The long-term viability of bladeless wind turbines is strong, especially for distributed generation in urban and remote settings. Target acquisition profiles include technology-focused startups with proprietary oscillation-based energy conversion or advanced piezoelectric materials. The achievement of widespread IEC certification across diverse product lines serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnerships | Accelerates market penetration for novel oscillation-based energy conversion designs into remote applications. |
| Hybrid System Development | Creates resilient 24-hour power solutions for critical telecommunications infrastructure. |
| Specialized Workforce Training Programs | Addresses scarcity of technicians for oscillation-based energy system maintenance. |
| IEC Standard Alignment Investment | Ensures market compliance and bankability for novel aerodynamic energy converters. |
| Urban Integration Design Focus | Meets aesthetic and low-impact energy demands in Spanish municipal planning. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary data involved conversations with telecom operators, utility providers, technology developers, and municipal planning officials. Secondary sources included International Electrotechnical Commission (IEC) standards, EU Green Deal policy documents, and national energy agency reports. Bottom-up market sizing was then triangulated with top-down validation from industry reports.
Forecast inputs considered policy support levels, technological advancements, and end-user adoption patterns. The analytical framework modeled market segmentation across technology, application, end user, and installation type throughout the forecast period. Compound Annual Growth Rates (CAGRs) were derived from historical data and projected market dynamics. Key industry-specific inputs included global 5G network expansion rates and national distributed generation targets.
Sensitivities concentrate around evolving municipal zoning regulations and unforeseen technological breakthroughs. Forecasts reflect current market assumptions regarding cost-parity achievement and long-term operational reliability. Material shifts in policy support or performance efficiency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Global Small Wind Power Market