
 India Snack Bar Market | 2026-2036
India Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
India Snack Bar Market Foresight
Single-serve multipack bundling is repositioning household purchase behavior away from individual unit trials. Mondelez India Foods Pvt. Ltd. leverages its chocolate and biscuit supply chain to anchor bundled snack bar displays at kirana counters. Yoga Bar (Sproutlife Foods Pvt. Ltd.) specializes in clean-label protein formulations that dominate premium shelf space in urban supermarkets.
India snack bars comprise compressed cereal, nut, or protein matrices bound by syrups or nut butters, typically shelf-stable for 6-12 months and formulated for 10-20 gram protein delivery per serving. Their primary commercial purpose is to deliver convenient, portion-controlled nutrition to consumers between traditional meals. Granola bars and protein bars together occupy the largest volume share, while cereal bars retain stronger penetration in tier-2 towns where price sensitivity shapes assortment decisions. The ingredient-type dimension reveals structural margin concentration: organic and high-protein variants command premium positioning, whereas low-sugar formulations face formulation cost barriers that limit mass-market scaling.
FSSAI mandates on nutritional labeling and health claims directly constrain product communication and force reformulation investments by domestic manufacturers. BIS packaging standards and state-level food safety enforcement by Maharashtra FDA and Karnataka FDA create compliance heterogeneity that advantages organized players with dedicated regulatory teams. Stakeholders must monitor evolving FSSAI protein claim thresholds and state-level organic certification requirements to anticipate which formulation investments will sustain market access.
Market Dynamics
FSSAI labeling mandates on protein and sugar claims are compressing formulation cycles and forcing domestic manufacturers into rapid reformulation investments. Urban millennial demand for clean-label protein formats is simultaneously pulling premium positioning into mainstream retail channels.
Growth Catalysts
- Protein claim standardization:FSSAI's tightening thresholds for protein content declarations are legitimizing premium pricing for verified formulations. Organized manufacturers with in-house testing capabilities capture shelf space faster than unorganized competitors.
- Modern retail density:Maharashtra and Karnataka's supermarket expansion creates dedicated health-food aisles where snack bars displace traditional namkeen. Kirana stores in Mumbai and Bangalore now stock protein bars alongside biscuit displays.
- Ingredient innovation:Cold-pressed nut butter binding technologies reduce syrup dependence while extending shelf stability. Domestic suppliers of almond and peanut butter are scaling to meet food-grade specifications.
Market Restraints
- Input cost volatility:Imported whey protein concentrate faces tariff fluctuations and rupee depreciation pressure. Domestic brands absorb margin compression or risk losing price-sensitive tier-2 consumers.
- Supply concentration risk:Organic certification for snack bar ingredients clusters in Karnataka and Kerala. Weather disruptions in these states propagate through premium product lines faster than conventional alternatives.
- Technical limitation:Clean-label formulations struggle to match the 12-month shelf life of preservative-laden competitors. Retailers in humid coastal markets reject shortened expiry windows.
Strategic Opportunities
- Underpenetrated geography:Tier-3 towns in Uttar Pradesh and Bihar lack dedicated health-food retail infrastructure. Early movers establishing kirana distribution networks capture habitual trial before organized retail arrives.
- Regulatory tailwind:FSSAI's front-of-pack labeling proposals favor low-sugar products with simplified visual warnings. Brands pre-invested in reduced-sugar formulations gain communication advantages.
- Channel innovation:Quick-commerce platforms in Delhi-NCR and Hyderabad are building dedicated wellness storefronts. Fifteen-minute delivery promises convert impulse snacking into planned nutrition purchases.
Industry Challenges
- Formulation talent scarcity:Food technologists with dual expertise in protein stabilization and Indian palate preferences command premium salaries. Mid-tier manufacturers lose R&D staff to multinational competitors.
- Certification timeline compression:FSSAI's accelerated approval schedules for novel ingredients strain documentation capacity. Smaller brands face 6-12 month delays launching innovative formats.
- Legacy equipment retrofit costs:Extrusion and enrobing lines designed for confectionery require modification for high-fiber matrices. Capital constraints delay production upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Snack Bar Market |
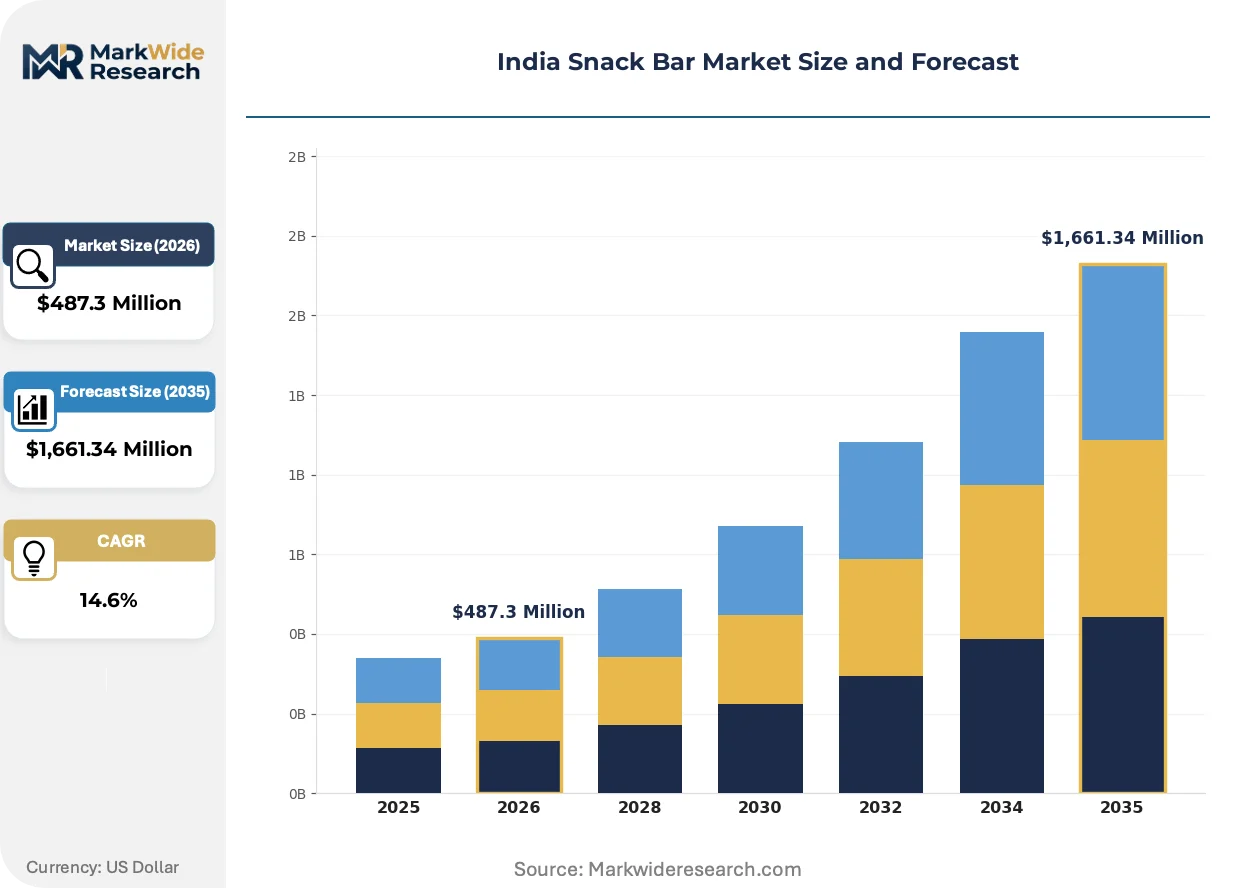
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Cereal Bars, Nut Bars Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores Customer Type: Fitness Enthusiasts, Health-Conscious Consumers, Busy Professionals, Students Ingredient Type: Organic, Gluten-Free, High-Protein, Low-Sugar |
| Companies Covered | Mondelez India Foods Pvt. Ltd., Haldiram's Foods International Pvt. Ltd., Nestlé India Ltd., ITC Ltd., Parle Products Pvt. Ltd., Britannia Industries Ltd., General Mills India Pvt. Ltd., Yoga Bar (Sproutlife Foods Pvt. Ltd.), Mars International India Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Snack Bar Market Shifts & Advancements
Clean-label protein delivery systems are displacing syrup-bound formulations across urban retail. Manufacturers are racing to match shelf stability with ingredient simplicity.
Cold-pressed protein bar manufacturing is absorbing moisture-control challenges that previously required artificial preservatives. Metro-based contract manufacturers in Pune and Gurgaon are retrofitting enrobing lines for nut-butter binding at scale. This technology is absorbing the technical barrier that kept clean-label products out of mass-market kirana distribution.
FSSAI's proposed star-rating system for packaged foods is compressing permissible sugar thresholds in formulation labs. Domestic manufacturers face reformulation costs or label disadvantage in modern retail. Premium protein bar portfolios in Maharashtra supermarkets are responding with accelerated stevia and monk fruit adoption.
Quick-commerce bundling is consolidating household pantry replenishment into weekly multi-pack purchases. Urban millennials in Bangalore and Mumbai are substituting impulse single-unit trials with subscription-style variety packs. This pattern is most visible in protein bar categories where flavor exploration drives repeat engagement.
India Snack Bar Market Segmentation
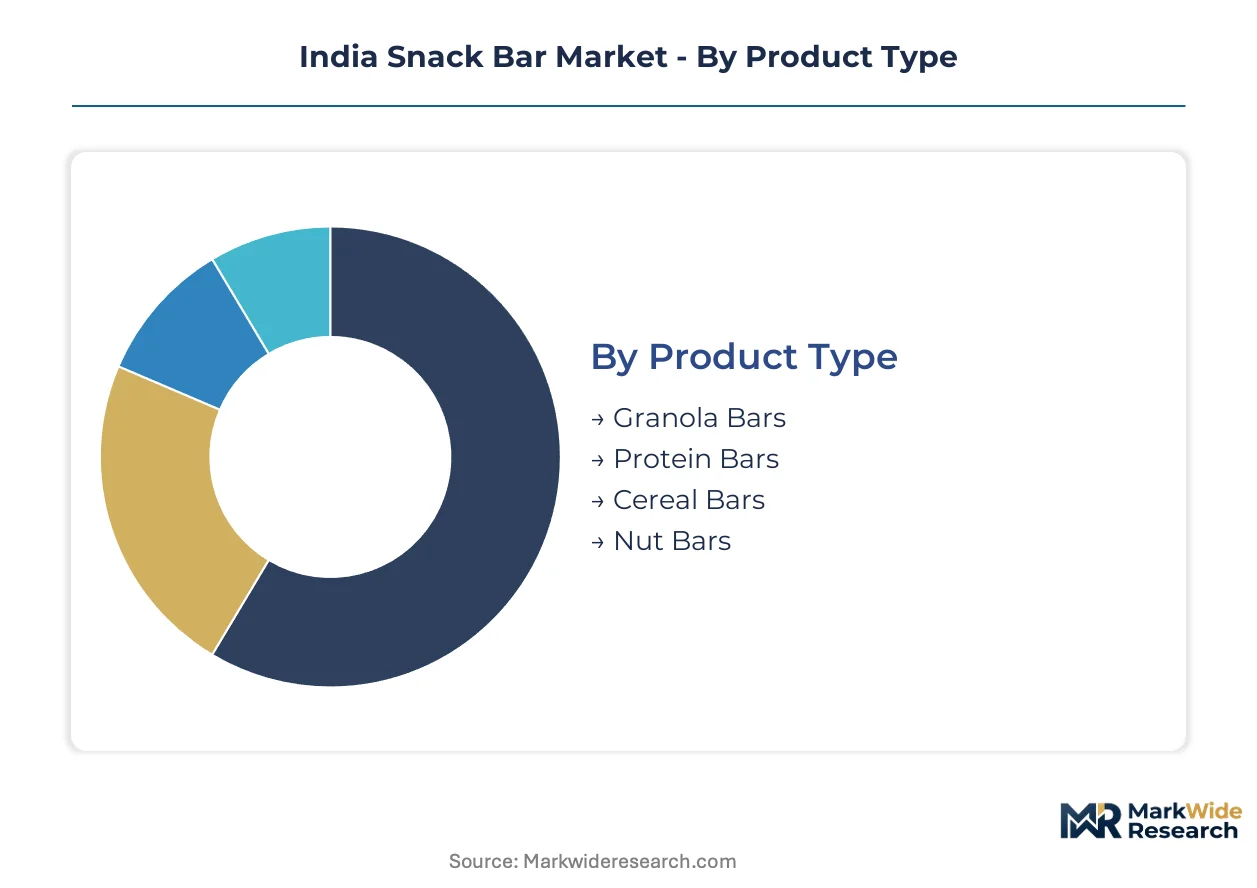
India's snack bar market fragments along four axes that reflect divergent supply chain capabilities and consumer willingness to pay for certified claims. Each category reveals where organized manufacturers can extract premiums versus where price competition dominates.
Product Type:
Supply concentration in binding technologies and protein sourcing separates scalable formats from artisan-dependent alternatives.
- Granola Bars:Compressed oat and honey matrices bound by syrup or nut butter, delivering 150-200 calories per serving with moderate fiber content. Maharashtra and Karnataka supermarkets allocate dedicated shelf space to granola bars as gateway formats for health-curious households transitioning from traditional namkeen.
- Protein Bars:Whey or plant-protein fortified bars engineered for 15-25 gram protein delivery through cold-pressed manufacturing. Urban millennials in Mumbai and Bangalore drive repeat purchases, with FSSAI protein claim thresholds legitimizing premium pricing for verified formulations.
- Cereal Bars:Puffed rice or wheat-based formats with lower protein density and price points accessible to tier-2 towns. Kirana stores in Uttar Pradesh stock cereal bars as biscuit alternatives for school-going children.
- Nut Bars:Whole or chopped almond, cashew, or peanut matrices with minimal processing and higher fat content. Domestic suppliers in Gujarat and Rajasthan struggle to meet food-grade specifications at scale, limiting mass-market penetration.
Today's leader: Protein Bars. Tomorrow's challenger: Granola Bars.
Distribution Channel:
Channel economics determine which claims manufacturers can afford to communicate, with modern retail enabling certification-heavy positioning that kirana economics cannot support.
- Supermarkets:Organized retail chains in metro cities dedicate health-food aisles to certified organic and high-protein variants. Modern retail density in Maharashtra permits front-of-pack labeling investments that recover through basket size premiums.
- Convenience Stores:Urban kirana counters and petrol station formats stock impulse-oriented single-serve units with simplified ingredient lists. Bangalore convenience stores now bundle protein bars with breakfast biscuits to capture morning commute purchases.
- Online Retail:Direct-to-consumer platforms and quick-commerce apps enable subscription bundling and flavor variety packs. Delhi-NCR and Hyderabad platforms build dedicated wellness storefronts with fifteen-minute delivery promises.
- Health Food Stores:Specialized retailers in metro areas curate clean-label and imported formats for affluent consumers. These outlets absorb higher wholesale prices in exchange for educated staff who explain FSSAI certification marks.
Supermarkets dominate volume. Online retail climbs fastest.
Customer Type:
Usage occasion and nutritional literacy shape which ingredient claims resonate, with fitness-oriented buyers demanding transparency that casual snackers disregard.
- Fitness Enthusiasts:Gym-goers and amateur athletes prioritizing protein content per rupee spent, verified by third-party testing. This segment tolerates stevia aftertaste and compressed texture in exchange for macronutrient certainty.
- Health-Conscious Consumers:Households seeking permissible indulgence through low-sugar or organic positioning without strict athletic requirements. Karnataka's organic certification clusters enable credible supply for this demand.
- Busy Professionals:Metro-based white-collar workers substituting skipped meals with portion-controlled nutrition during commutes. Quick-commerce platforms target this segment with office-delivery subscriptions.
- Students:Price-sensitive younger buyers in tier-2 and tier-3 towns purchasing cereal bars as affordable energy sources during exam periods.
Fitness enthusiasts anchor premium pricing. Busy professionals expand the addressable base.
Ingredient Type:
Certification requirements and input cost structures create tiered margin profiles that only some manufacturers can navigate profitably.
- Organic:Ingredients sourced from Karnataka and Kerala farms with third-party certification, commanding 40-60% wholesale premiums. Weather disruptions in these states propagate supply constraints faster than conventional alternatives.
- Gluten-Free:Oat or millet-based formulations excluding wheat, targeting celiac and lifestyle gluten-avoiders. Domestic millet processing infrastructure in Rajasthan supports scaling this segment.
- High-Protein:Whey concentrate or isolate fortification with FSSAI-verified protein claims. Imported whey faces tariff and currency volatility that compresses margins for brands without backward integration.
- Low-Sugar:Stevia, monk fruit, or sugar alcohol formulations responding to FSSAI front-of-pack labeling proposals. Reformulation costs and aftertaste challenges limit mass-market adoption despite regulatory tailwinds.
High-Protein captures current investment. Low-Sugar awaits regulatory enforcement to unlock scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India pioneered organized snack bar manufacturing through Maharashtra's biscuit and confectionery heritage. Gujarat's nut processing clusters and Karnataka's organic certification infrastructure subsequently shaped ingredient sourcing patterns. Today, state-level food safety enforcement and modern retail density determine where premium formats achieve scalable distribution.
Maharashtra
Mumbai's supermarket chains dedicate health-food aisles to protein-fortified formats, with kirana counters in Pune and Nagpur now bundling snack bars alongside biscuit displays. FSSAI labeling mandates for sugar claims force reformulation investments by domestic manufacturers headquartered in the state. Thane and Nashik host contract manufacturing facilities retrofitting enrobing lines for cold-pressed nut butter binding.
Karnataka
Bangalore's urban millennials drive clean-label protein bar adoption through quick-commerce wellness storefronts with fifteen-minute delivery promises. The state's organic certification clusters in Kodagu and Chikkamagaluru supply certified ingredients commanding wholesale premiums. Mysuru and Hubli-Dharwad serve as secondary distribution hubs penetrating tier-2 towns before organized retail arrives.
Gujarat
Domestic suppliers of almond and peanut butter in Anand and Rajkot struggle to scale food-grade specifications for mass-market snack bar binding. The state's legacy confectionery equipment base requires capital-intensive modification for high-fiber protein matrices. Surat's modern retail expansion creates dedicated shelf space for imported whey protein formulations.
Delhi-NCR
Gurugram-based contract manufacturers absorb technical barriers that previously kept clean-label products out of mass-market distribution. The National Capital Region's quick-commerce density converts impulse snacking into planned nutrition purchases through subscription-style variety packs. Noida hosts R&D facilities where food technologists command premium salaries for dual expertise in protein stabilization and Indian palate preferences.
Tamil Nadu
Chennai's convenience store networks stock cereal bars as affordable energy sources for students during examination periods. The state's millet processing infrastructure in Salem and Coimbatore supports gluten-free formulation scaling. Coimbatore's engineering base supplies modified extrusion equipment for domestic manufacturers expanding beyond conventional confectionery formats.
India Snack Bar Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and protein claim dimensions. Organized manufacturers with in-house FSSAI testing capabilities capture shelf space faster than unorganized competitors struggling with documentation capacity. Three archetypes dominate: multinational confectionery giants leveraging chocolate and biscuit supply chains; domestic clean-label specialists commanding premium positioning; and diversified FMCG conglomerates cross-selling through existing kirana networks. Competitive moves concentrate on portfolio diversification into protein-fortified formats and strategic partnerships with quick-commerce platforms for fifteen-minute delivery infrastructure.
Within the multinational confectionery tier, Mondelez India Foods Pvt. Ltd. and Mars International India Pvt. Ltd. exemplify supply chain leverage from adjacent categories. Among domestic clean-label specialists, Yoga Bar (Sproutlife Foods Pvt. Ltd.) occupies a position exemplifying premium shelf space capture in urban supermarkets. Diversified FMCG conglomerates including ITC Ltd. and Britannia Industries Ltd. represent archetypes of cross-category distribution muscle penetrating tier-2 kirana networks before organized retail arrives.
| Leading Market Players |
|---|
| Mondelez India Foods Pvt. Ltd. |
| Haldiram's Foods International Pvt. Ltd. |
| Nestlé India Ltd. |
| ITC Ltd. |
| Parle Products Pvt. Ltd. |
| Britannia Industries Ltd. |
| General Mills India Pvt. Ltd. |
| Yoga Bar (Sproutlife Foods Pvt. Ltd.) |
| Mars International India Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Captive sourcing of cold-pressed nut butter binding technology anchors both supply security and pricing power for organized manufacturers retrofitting enrobing lines in Maharashtra and Karnataka. This integration choice insulates premium protein bar portfolios from imported whey concentrate volatility while compressing formulation cycles for FSSAI-compliant claims.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic formulations from conventional protein bars and entry-level cereal alternatives. Certification grade and volume scale drive price differentiation, with FSSAI-verified protein claims commanding shelf space premiums. Cost compression in the economy tier intensifies because domestic brands absorb rupee depreciation pressure on imported whey rather than lose tier-2 consumers. Students in Uttar Pradesh and Bihar exhibit highest price sensitivity, while fitness enthusiasts in Mumbai tolerate texture trade-offs for macronutrient certainty.
Supply Chain Analysis
Single-source vulnerability sits with Karnataka and Kerala organic certification clusters, where weather disruptions propagate through premium product lines faster than conventional alternatives. Raw material dependencies center on imported whey protein concentrate, domestic almond and peanut butter, and cold-pressed binding syrups. Tariff exposure on whey concentrate compresses margins for brands lacking backward integration into nut butter processing. Distribution runs through modern retail chains in metro cities, kirana networks in tier-2 towns, and quick-commerce platforms building fifteen-minute delivery infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India snack bar market reads as a late-cycle quality story. Urban millennial demand has shifted decisively toward FSSAI-verified protein specifications and clean-label ingredient transparency.
For Market Incumbents: Hedge against formulation talent scarcity by captive investment in Pune and Gurgaon R&D facilities where protein stabilization expertise commands premium salaries. Defend shelf space by accelerating stevia and monk fruit adoption ahead of FSSAI front-of-pack labeling enforcement, converting regulatory compliance into communication advantage before unorganized competitors recover documentation capacity.
For New Entrants and Emerging Players: The gap between premium protein bar pricing and economy cereal bar positioning creates white-space opportunity in tier-3 Uttar Pradesh and Bihar kirana networks. Target habitual trial before organized retail arrives by establishing distribution partnerships with regional biscuit wholesalers. Lead with gluten-free millet formulations leveraging Rajasthan processing infrastructure as the go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for domestic clean-label specialists because FSSAI certification timelines strain smaller brands into six-to-twelve-month launch delays. Mid-cap manufacturers with in-house testing capabilities and established modern retail relationships represent priority acquisition targets. Watch quick-commerce platform wellness storefront expansion as the inflection signal converting impulse snacking into planned nutrition subscriptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Manufacturing Scale-Up | Contract manufacturers in Thane retrofit enrobing lines for nut-butter binding at volume. |
| FSSAI Certification Pre-Investment | Early stevia and monk fruit adoption secures front-of-pack labeling advantages ahead of enforcement. |
| Quick-Commerce Platform Partnership | Fifteen-minute delivery promises in Delhi-NCR convert impulse trials into subscription retention. |
| Backward Integration into Nut Butter | Domestic suppliers in Gujarat scale food-grade almond and peanut specifications for mass binding. |
| Tier-3 Kirana Network Expansion | Early distribution in Uttar Pradesh and Bihar captures habitual purchase before organized retail arrives. |
Research Methodology
Direct dialogue with brand managers, category buyers at modern retail chains, contract manufacturing facility heads, and FSSAI regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from FSSAI notification archives, Maharashtra FDA enforcement records, Karnataka organic certification databases, and Nielsen retail audit data covering health-food aisle distribution. Bottom-up volume estimates from individual SKU velocities triangulated against top-down category expenditure projections.
Top-down macroeconomic modeling anchored demand drivers to urbanization rates and modern retail penetration curves, while bottom-up segmentation tracked protein bar versus granola bar versus cereal bar adoption patterns across metro, tier-2, and tier-3 geographies. The analytical framework modeled product type, distribution channel, customer archetype, and ingredient certification tier throughout the forecast period. CAGRs emerged from iterative reconciliation of historical trajectory analysis with structural breakpoint identification around regulatory enforcement timing.
The model assumes a particular technology adoption path; alternative pathways for cold-pressed binding equipment deployment would alter the outlook for clean-label shelf stability and mass-market kirana penetration. Forecasts reflect assumptions about FSSAI enforcement consistency, rupee exchange rate bands, and organic certification supply reliability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Saudi Arabia Snack Bar Market
Snacks
Low Calorie Dip Market
Snacks
High Carb Low Fat Snack Market
Snacks
Pretzel Salts Market
Snacks
Organic Chips Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Australia Snack Bar Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Cereal Bars Market
Snacks
Better for You Snacks Market
Snacks
Snack Subscription Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Low Fat Crackers Market
Snacks
Dried Fruit Snacks Market