
 Pretzel Salts Market | 2026-2036
Pretzel Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Pretzel Salts Market Insights
Germany is narrowing the gap between artisan tradition and industrial scale in pretzel salt supply. Cargill Incorporated leverages its bulk logistics network to dominate European food-manufacturer supply chains. Jacobsen Salt Co differentiates through craft positioning and Pacific Northwest provenance. Morton Salt anchors North American private-label and retail jar segments with deep grocery channel control.
Pretzel salts are sodium chloride-based crystalline products, typically coarse-grained with particle sizes between 1.5 mm and 4 mm, engineered to adhere to dough surfaces and create the characteristic glossy, flavorful crust of baked pretzels. Sea salt variants command premium positioning in gourmet cooking and specialty snacking applications due to trace mineral content and artisanal harvesting credentials, while coarse salt sustains volume leadership in commercial baking and food manufacturing where cost efficiency and consistent adhesion matter most. Bulk containers dominate food-service and bakery procurement for operational efficiency, whereas jars and sachets capture household and restaurant tabletop segments with convenience-driven margin structures.
FDA sodium guidance and EU EFSA reformulation thresholds are reshaping product development cycles, pushing manufacturers toward reduced-sodium blends and mineral-enhanced sea salt certifications. Germany's BfR and the U.S. FDA both scrutinize anti-caking agent allowances, directly affecting import eligibility and label claims for international suppliers. Stakeholders must monitor evolving sodium threshold enforcement and certification parity between organic and conventional salt streams to protect market access.
Market Dynamics
Clean-label sodium reduction mandates from the FDA and EU EFSA are compressing formulation cycles, forcing manufacturers to reformulate around sea salt and mineral-enhanced variants while maintaining the adhesion properties that define pretzel crust quality.
Growth Catalysts
- EU EFSA Reformulation Thresholds:Sodium caps in processed foods are accelerating adoption of reduced-sodium sea salt blends among industrial bakeries seeking compliance without sacrificing texture.
- Artisan Bakery Expansion:Specialty producers in Germany and Austria are scaling procurement of coarse crystalline salts for traditional laugenbrezel production, anchoring premium segment demand.
- Trace Mineral Positioning:Pacific Northwest harvesting credentials are enabling premium pricing for unrefined sea salt variants in gourmet snacking applications.
Market Restraints
- Potassium Chloride Substitution Limits:Reduced-sodium blends face technical barriers as potassium chloride disrupts yeast fermentation and crust gloss in traditional pretzel recipes.
- Anti-Caking Agent Scrutiny:Germany's BfR and the FDA enforce divergent ferrocyanide allowances, fragmenting import eligibility for international suppliers.
- Evaporative Harvest Volatility:Sea salt production concentrates in coastal zones vulnerable to climate-driven precipitation shifts, compressing supply predictability.
Strategic Opportunities
- Food-Service Bulk Contracting:Untapped penetration in US regional bakery chains offers volume pathways outside saturated European procurement channels.
- Organic Certification Parity:USDA Organic and EU Organic equivalence negotiations are creating streamlined label claims for cross-Atlantic suppliers.
- Mineral-Enhanced Positioning:Magnesium and potassium fortification protocols are converging with clean-label demands to open functional snacking segments.
Industry Challenges
- Reformulation Timeline Compression:FDA sodium guidance phase-ins are forcing R&D cycles below 18 months for mid-tier manufacturers lacking in-house mineralogy capabilities.
- Legacy Equipment Adaptation:Coarse salt adhesion systems in existing pretzel production lines require retrofitting for reduced-sodium blend flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pretzel Salts Market |
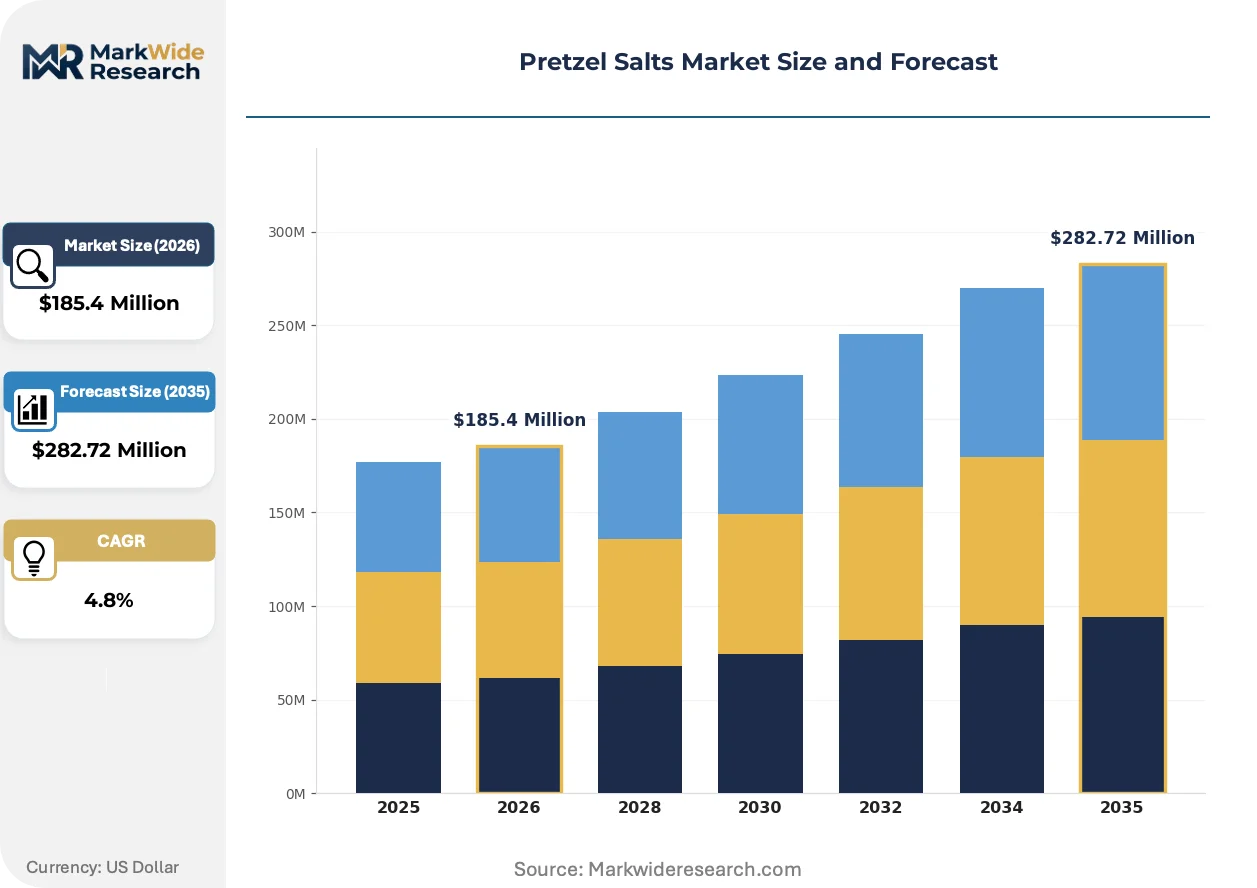
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $282.72 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse Salt, Flavored Salt, Sea Salt, Organic Salt Application: Snacking, Baking, Food Service, Gourmet Cooking Packaging Type: Bags, Jars, Bulk Containers, Sachets End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Cargill Incorporated, Morton Salt, Hoosier Hill Farm, Jacobsen Salt Co, SaltWorks, San Francisco Salt Company, Southwest Salt Company, Barry Farm Foods, QualiTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pretzel Salts Market Trends and Innovations
Digital quality assurance systems are virtualizing crystalline grading and adhesion testing protocols, compressing the gap between artisan harvesting credentials and industrial-scale consistency requirements.
Sensor-based crystalline analysis is virtualizing traditional manual inspection of salt particle geometry and moisture content. Industrial bakeries in Germany and the Netherlands are deploying inline spectroscopy for real-time adhesion prediction. This virtualization is compressing batch rejection rates and enabling just-in-time procurement from multiple harvest sources.
EU EFSA sodium reduction benchmarks are tightening enforcement timelines for processed baked goods, forcing reformulation investments ahead of scheduled compliance windows. Mid-sized manufacturers face disproportionate lab certification burdens relative to multinationals with captive analytical capabilities. The industrial pretzel segment is responding with staged blend transitions rather than abrupt sodium cuts.
Direct-procurement platforms are disintermediating traditional ingredient distributors for bulk salt contracts. Regional bakery cooperatives in Bavaria and Baden-Württemberg are aggregating demand through digital purchasing consortia. This concentration is most visible in southern Germany, where Mittelstand bakery networks command sufficient volume to bypass conventional wholesale channels.
Pretzel Salts Market Segmentation
Pretzel salt procurement splits sharply between industrial-scale baking operations and artisan craft producers, with packaging and certification tiers creating distinct margin architectures across each channel. Understanding these fault lines reveals where reformulation investments concentrate and which specifications command premium positioning.
Product Type:
Mature commodity grades anchor volume procurement while emerging specialty variants capture margin expansion through clean-label certification.
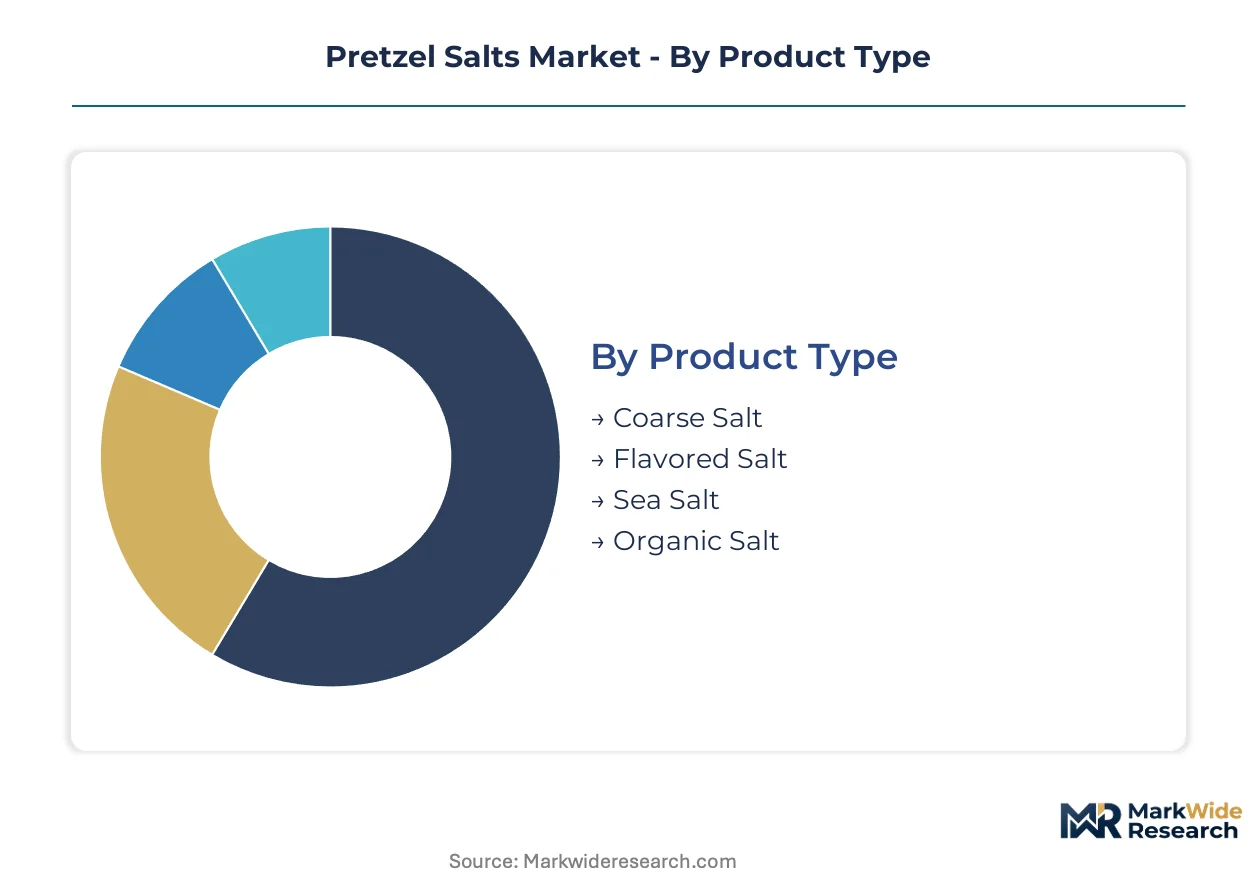
- Coarse Salt:Crystalline sodium chloride with particle sizes between 1.5 mm and 4 mm, engineered for dough surface adhesion and characteristic crust gloss. Industrial bakeries in Germany specify this grade for laugenbrezel production where consistent granule geometry controls melting rate during alkaline bath treatment. Coarse salt retains volume leadership; organic salt holds the steepest expansion curve.
- Sea Salt:Unrefined evaporative harvest retaining trace magnesium, potassium, and calcium compounds. Pacific Northwest harvesting credentials enable premium positioning in US gourmet snacking applications, though mineral variability complicates industrial standardization protocols. FDA sodium guidance accelerates adoption as a perceived clean-label alternative despite comparable sodium density.
- Flavored Salt:Sodium chloride base infused with smoke, malt, or spice extracts for differentiated crust profiles. Limited penetration outside specialty craft bakeries due to flavor inconsistency risks in high-temperature baking environments.
- Organic Salt:Certified harvest meeting USDA Organic or EU Organic standards with restricted processing aids and anti-caking agents. Supply concentration in Mediterranean evaporative operations creates import dependency for North American manufacturers seeking label parity.
Coarse salt dominates tonnage; organic certification unlocks the fastest pricing expansion.
Application:
Cost tier stratification separates commodity volume plays from premium positioning opportunities.
- Baking:Industrial pretzel manufacturing demands precise granule size distribution for automated salting stations and uniform crust development. German Mittelstand bakeries drive specification tightening as digital quality assurance systems enable real-time adhesion monitoring. Baking commands procurement volume; gourmet cooking climbs fastest.
- Snacking:Packaged pretzel products require salt formulations compatible with extended shelf stability and flavor retention through oil roasting or dry baking processes. Reduced-sodium blend development concentrates here due to FDA guidance targeting processed snack categories.
- Food Service:Tabletop and back-of-house procurement prioritizes flowability and anti-caking performance over mineral content. Regional US bakery chains represent underpenetrated contracting opportunities outside established European supply relationships.
- Gourmet Cooking:Chef-driven demand for finishing salts with distinct crystalline structure and provenance storytelling. Trace mineral positioning and artisan harvesting credentials support three-to-five-fold pricing premiums over commodity grades.
Baking absorbs the heaviest procurement tonnage; gourmet cooking scales fastest through premium channel expansion.
Packaging Type:
Supply concentration in bulk logistics shapes competitive access for smaller procurement entities.
- Bulk Containers:500 kg to 1,000 kg flexible intermediate bulk containers dominate industrial bakery and food manufacturer procurement. Cargill's European distribution network leverages this format for just-in-time delivery to German manufacturing clusters.
- Jars:Retail-facing 200 g to 500 g glass or PET containers for household and restaurant tabletop segments. Morton Salt's grocery channel control anchors North American placement.
- Bags:5 kg to 25 kg woven polypropylene for mid-scale bakery operations and food-service distributors. Price sensitivity here limits premium variant penetration.
- Sachets:Single-serve 1 g to 5 g packets for airline, hospitality, and institutional catering. Convenience-driven margin structures support profitability despite minimal individual volume.
Bulk containers retain procurement dominance; sachets expand through hospitality recovery.
End User:
Customer type fragmentation creates divergent specification pressures across the value chain.
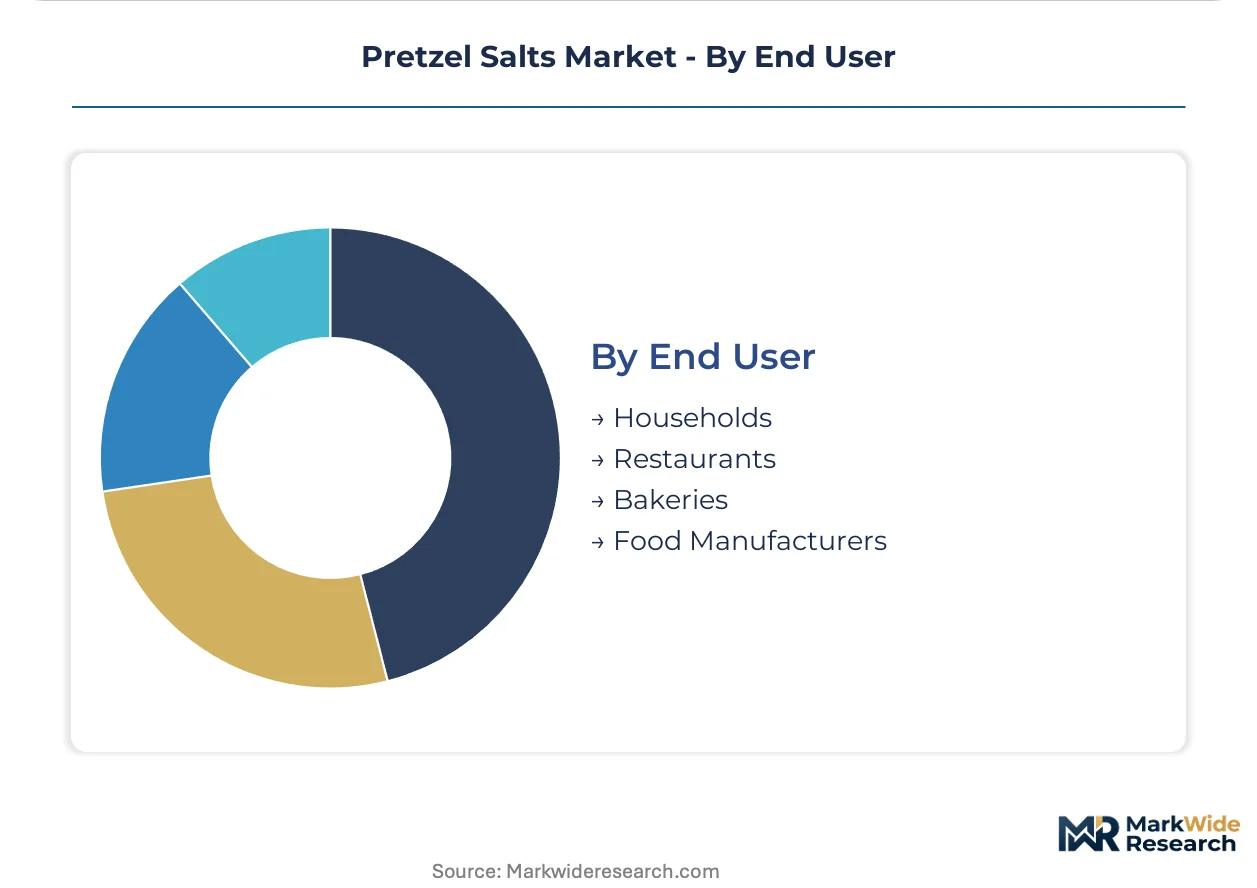
- Food Manufacturers:Large-scale pretzel producers with captive R&D capabilities driving reduced-sodium blend development. EU EFSA reformulation thresholds compress their formulation cycles below 18 months.
- Bakeries:Artisan and industrial operations spanning German Mittelstand networks to US regional chains. Equipment retrofit requirements for reduced-sodium blend handling create adoption friction.
- Restaurants:Tabletop presentation and kitchen prep demand split between commodity coarse salt and premium finishing variants. Procurement consolidation through broadline distributors limits direct supplier relationships.
- Households:Retail jar and bag purchasers responding to clean-label positioning and regional provenance marketing. Price elasticity constrains organic variant penetration outside affluent urban markets.
Food manufacturers drive specification evolution; bakeries represent the most fragmented contracting environment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Evaporative salt harvests concentrate in coastal zones spanning three continents, with regulatory divergence between FDA sodium guidance and EU EFSA reformulation thresholds fragmenting procurement standards across major consumption markets.
Germany
Mittelstand bakery networks in Bavaria and Baden-Württemberg drive coarse salt procurement for traditional laugenbrezel production. The BfR enforces strict anti-caking agent allowances that filter import eligibility for non-EU suppliers. Stuttgart and Munich manufacturing clusters anchor industrial-scale contracting through digital purchasing consortia.
United States
Regional bakery chains in the Midwest and Southeast represent underpenetrated bulk contracting opportunities outside established European supply relationships. FDA sodium reduction guidance targets processed snack categories, compressing reformulation timelines below 18 months for mid-tier manufacturers. Pacific Northwest harvesting credentials from Oregon and Washington enable premium positioning in gourmet snacking segments.
France
Artisan bakery expansion in Île-de-France and Auvergne-Rhône-Alpes sustains demand for sea salt variants with trace mineral positioning. ANSM and CNIL oversight of food additive labeling creates compliance complexity for imported salt blends. Lyon and Paris food-service clusters concentrate procurement of certified organic variants for restaurant tabletop segments.
Netherlands
Industrial pretzel manufacturing in the Randstad region deploys inline spectroscopy for real-time salt adhesion prediction. ECHA REACH compliance requirements for anti-caking agents shape import sourcing decisions from Mediterranean evaporative operations. Rotterdam logistics hubs facilitate just-in-time delivery to German manufacturing clusters across the border.
Canada
Health Canada and PMRA sodium reduction frameworks for processed foods accelerate adoption of mineral-enhanced sea salt blends. Ontario and Quebec bakery cooperatives aggregate demand through regional distribution networks. Toronto and Montreal food-service markets concentrate procurement of bulk containers for back-of-house operations.
Pretzel Salts Market Competitive Landscape
Bulk-commodity suppliers and craft-positioned specialists split the market into divergent margin architectures. Consolidation pressure concentrates around logistics networks capable of just-in-time delivery to industrial baking clusters, while fragmentation persists in premium segments where provenance storytelling commands pricing power. Three archetypes dominate: multinational agribusiness conglomerates with captive bulk distribution, regional evaporative harvesters with organic certification credentials, and specialty saltworks with chef-driven brand equity. Competitive moves center on backward integration into evaporative harvesting assets and geographic expansion through distributor partnerships in underpenetrated North American markets.
Within the multinational agribusiness tier, Cargill Incorporated anchors European food-manufacturer supply chains through bulk logistics dominance. Morton Salt exemplifies grocery-channel control across North American private-label and retail jar segments. Jacobsen Salt Co occupies a craft-positioned niche leveraging Pacific Northwest provenance credentials for premium gourmet applications.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Morton Salt |
| Hoosier Hill Farm |
| Jacobsen Salt Co |
| SaltWorks |
| San Francisco Salt Company |
| Southwest Salt Company |
| Barry Farm Foods |
| QualiTech |
| Others |
Pricing and Supply Chain Analysis
Mediterranean evaporative harvesting clusters in Sicily and Sardinia anchor global coarse salt capacity, with their seasonal output fluctuations directly transmitting into spot-price volatility for industrial bakery procurement contracts. German Mittelstand networks mitigate this exposure through long-term offtake agreements, while North American buyers absorb sharper price swings due to thinner inventory buffers.
Pricing Analysis
EU EFSA sodium reduction thresholds dictate the pricing tier structure across organic, sea salt, and coarse crystalline grades. Three-tier pricing structure across premium, standard, and economy levels separates certified organic harvests from conventional sea salt and commodity coarse grades. Cost compression in the standard tier is intensifying because mid-sized manufacturers lack captive mineralogy capabilities for reduced-sodium blend development. Food manufacturers with integrated R&D operations demonstrate lowest price sensitivity; regional bakery cooperatives exhibit highest elasticity.
Supply Chain Analysis
REACH compliance restrictions on ferrocyanide anti-caking agents limit cross-border flows from non-EU evaporative operations into German manufacturing clusters. Supply concentrates in Italy, Spain, and Portugal for Mediterranean sea salt; Germany and Poland for rock salt processing. Production draws from coastal solar evaporation ponds, underground brine extraction, and mechanical harvesting equipment. Single-source vulnerability concentrates in Sicilian organic certification streams. Distribution runs through Rotterdam logistics hubs for just-in-time delivery to Bavarian bakery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized mineralogy expertise for reduced-sodium blend formulation represents the scarcest capability in this market, with fewer than a dozen European laboratories capable of certifying adhesion performance under FDA and EU EFSA reformulation timelines simultaneously.
For Market Incumbents: Pre-empt potassium chloride substitution limits by acquiring captive evaporative harvesting assets in climate-resilient coastal zones. Cargill's bulk logistics network faces displacement risk from digital purchasing consortia aggregating Mittelstand demand; reinforce channel control through embedded quality assurance partnerships with spectroscopy equipment vendors. For New Entrants and Emerging Players: US regional bakery chains in the Midwest and Southeast represent the most penetrable entry point outside saturated European procurement channels. Pacific Northwest provenance credentials enable premium positioning in gourmet snacking segments underserved by Mediterranean suppliers. A direct-procurement platform play targeting bakery cooperatives bypasses established distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among organic-certified evaporative harvesters with EU-USDA equivalence agreements. Long-term viability hinges on climate-adaptive sourcing footprints and mineral-enhanced product pipelines. Acquisition targets should demonstrate inline spectroscopy deployment capabilities. The signal to watch is BfR-FDA regulatory harmonization progress on anti-caking agent allowances.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Evaporative Harvesting | Cargill's Mediterranean asset footprint secures supply continuity for German industrial bakery clusters. |
| Digital Purchasing Consortium Formation | Bavarian Mittelstand networks aggregate demand to bypass traditional wholesale salt distributors. |
| Inline Spectroscopy Deployment | Dutch industrial bakeries compress batch rejection rates through real-time adhesion prediction protocols. |
| Organic Certification Parity Investment | Cross-Atlantic suppliers streamline label claims through USDA-EU Organic equivalence negotiations. |
| Mineral-Enhanced Product Line Extension | Magnesium and potassium fortification protocols open functional snacking segments beyond traditional baking. |
Research Methodology
Cross-validation between salt industry procurement directors and regulatory affairs specialists anchors the qualitative findings in documented compliance timelines. Primary interviews with bakery plant managers, evaporative harvest operations heads, food-service distribution channel partners, and supermarket category buyers combined with secondary validation from FDA guidance documents, EU EFSA scientific opinions, BfR additive assessments, and customs trade flow records. Bottom-up volume aggregation from manufacturing cluster surveys and top-down market sizing from evaporative capacity estimates triangulate demand figures.
Calibration against historical price elasticity patterns and procurement cycle timing refines the analytical framework across the analysis window. Segmentation dimensions include product type tier, application end-use, packaging format scale, and regional regulatory cluster. CAGRs derive from installed bakery equipment capacity growth and organic certification expansion trajectories. Forecast inputs incorporate climate-driven precipitation volatility models for Mediterranean harvest zones and sodium reduction enforcement phase-in schedules.
Practitioners should monitor EU EFSA threshold tightening and FDA compliance window announcements for early signals of reformulation investment acceleration. Forecasts reflect assumptions on anti-caking agent regulatory parity and evaporative harvest yield stability. Material shifts in BfR-FDA harmonization progress or coastal climate disruption severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Crackers Market
Snacks
High Fiber Snack Foods Market
Snacks
Fiber Bars Market
Snacks
Europe Extruded Snack Food Market
Snacks
Jerky Snacks Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Seafood Snacks Market
Snacks
Salty Puffed Snacks Market
Snacks
North America Potato Chips Market
Snacks
Super Low Calorie Snacks Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Argentina Snack Bar Market
Snacks
Baked Savoury Snacks Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
Meat Snacks Market
Snacks
Candy and Snack Food Pouches Market