
 Flexible Plastic Snack Food Packaging Market | 2026-2036
Flexible Plastic Snack Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Plastic Snack Food Packaging Market Foresight
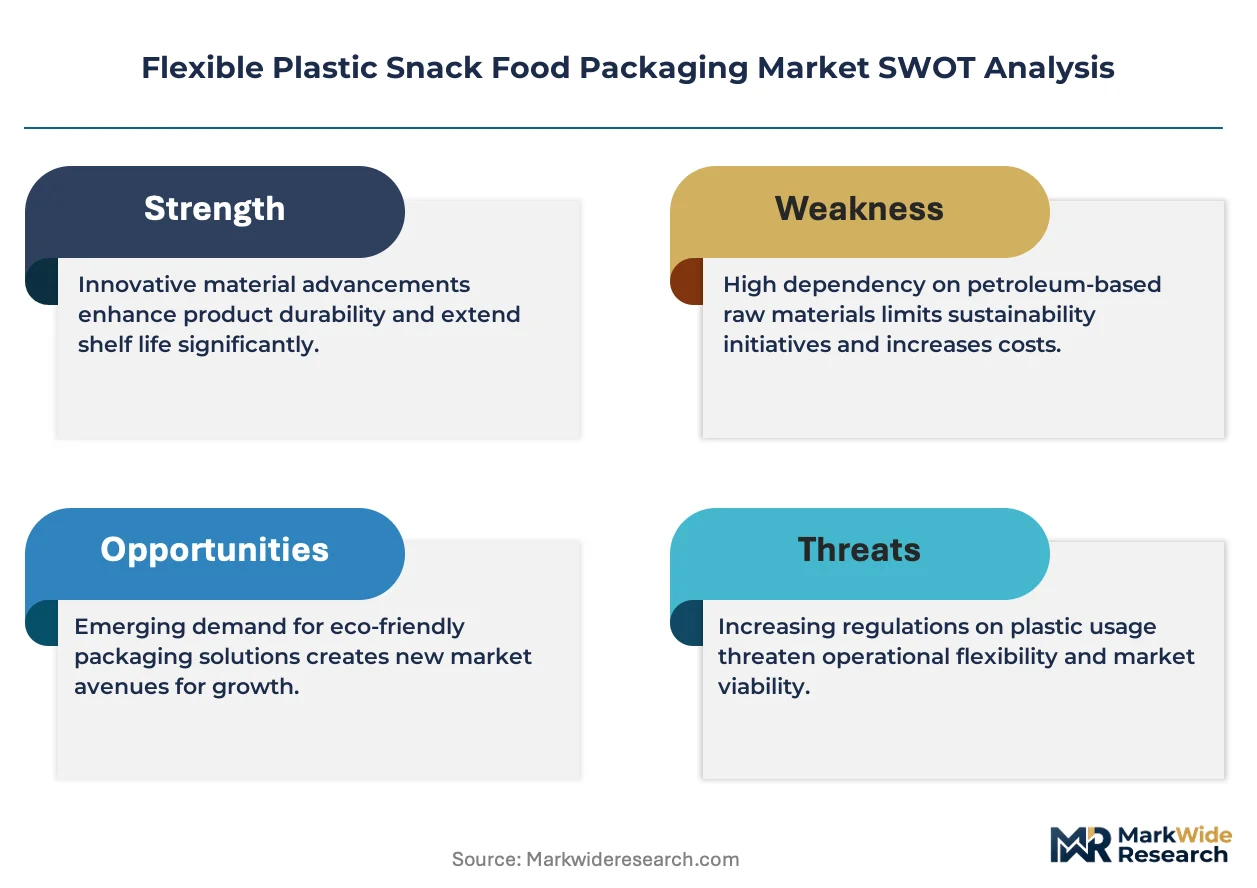
The premium-commodity split in flexible plastic snack food packaging is repositioning around barrier performance and sustainability credentials versus cost-per-unit economics. Amcor Plc leverages its global film manufacturing footprint to anchor premium multilayer solutions for oxygen-sensitive snacks. Mondi Plc competes through integrated kraft paper-plastic hybrid structures that reduce fossil-derived content without sacrificing seal integrity.
Flexible plastic snack food packaging comprises polymer-based films, laminates, and coextruded structures—typically 15–150 micrometers thick—engineered to provide moisture barriers, oxygen scavenging, and mechanical protection for shelf-stable foods. Polypropylene and polyethylene dominate material type volumes due to cost efficiency and heat-seal compatibility, though polyester and nylon gain share in high-barrier applications for nuts and extruded snacks. Stand-up pouches and flow wrap formats lead packaging format growth, driven by vertical form-fill-seal efficiency and on-shelf differentiation for snack manufacturers.
The US FDA governs food contact substance compliance under 21 CFR, while the EPA regulates per- and polyfluoroalkyl substance phaseouts affecting grease-resistant snack wrappers. The EU Packaging and Packaging Waste Regulation mandates recycled content minimums that reshape flexible film specifications across European supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and PFAS restrictions to align material roadmaps with compliance timelines.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing lead times for recycled-content flexible films, forcing snack manufacturers to requalify entire packaging specifications before 2030 compliance deadlines. This regulatory compression is reshaping supplier relationships across European supply chains.
Growth Catalysts
- High-barrier film adoption:Oxygen-sensitive snack categories—nuts, extruded products, and baked crisps—are converting to multilayer coextruded structures. North American processors are expanding capital allocation toward vertical form-fill-seal lines compatible with these formats.
- Extended Producer Responsibility frameworks:France's AGEC Law and Germany's VerpackG are creating compliance-driven demand for recyclable mono-material laminates. Brand owners are redesigning packaging portfolios to meet minimum recyclability thresholds.
- India retail distribution expansion:Domestic snack brands are scaling packaged retail presence beyond traditional kirana stores into organized modern trade and e-commerce fulfillment. Flexible pouches dominate this channel transition due to lightweight logistics and shelf-ready presentation.
Market Restraints
- Polypropylene resin volatility:Feedstock cost swings tied to naphtha and propylene monomer pricing compress converter margins. Contract structures rarely pass through full input fluctuations within quarterly windows.
- Recycled food-grade polymer scarcity:rPP and rPE suitable for direct food contact remain supply-constrained. European converters face allocation limits from mechanical recycling infrastructure still scaling toward regulatory minimums.
- PFAS regulatory friction:US EPA phaseout timelines for grease-resistant coatings are forcing snack wrapper redesigns. Alternative fluorine-free barriers require extended migration testing and customer requalification cycles.
Strategic Opportunities
- Paper-plastic hybrid structures:Kraft paper-laminate formats reduce fossil-derived content while maintaining heat-seal integrity. European brand owners are piloting these structures for premium positioning in sustainability-sensitive retail channels.
- Chemical recycling feedstock partnerships:Pyrolysis-derived circular polymers offer food-contact compliance pathways mechanical recycling cannot achieve. Early offtake agreements with technology developers are securing volume allocations ahead of commercial scale-up.
- Smart packaging integration:Time-temperature indicators and freshness sensors are converging with flexible substrates. High-value nut and dried fruit segments are adopting these features to differentiate against private label competition.
Industry Challenges
- Migration testing capacity bottlenecks:Food-contact compliance validation for new multilayer structures requires specialized analytical laboratories. Queue times for EU 10/2011 and FDA 21 CFR testing are extending reformulation timelines.
- Legacy equipment retrofit requirements:Existing horizontal and vertical form-fill-seal assets often lack tension control and sealing temperature precision for thinner, higher-recycled-content films. Capital expenditure for line upgrades competes with sustainability program budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Plastic Snack Food Packaging Market |
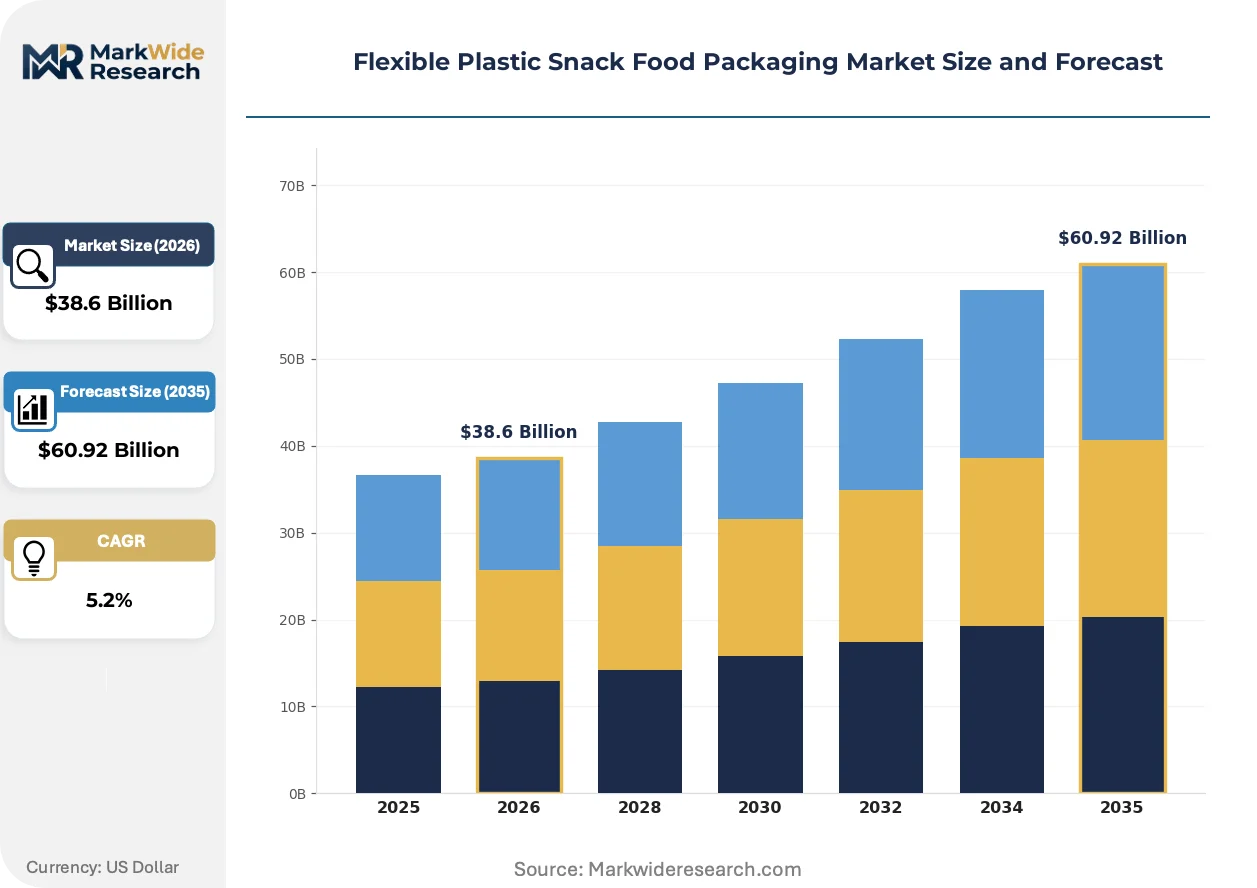
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $60.92 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyethylene, Polyester, Nylon, Aluminum Foil, Cellophane Packaging Format: Pouch, Bag, Wrapper, Flow Wrap, Stand-up Pouch, Gusseted Bag End User: Snack Manufacturers, Confectionery Producers, Beverage Companies, Foodservice Providers Application: Potato Chips, Nuts, Extruded Snacks, Bakery Snacks, Confectionery Packaging, Dried Fruit Packaging |
| Companies Covered | Sonoco Products Company, Berry Global Group, Inc., Amcor Plc, Uflex Limited, Constantia Flexibles Group GmbH, Mondi Plc, Sealed Air Corporation, ProAmpac LLC, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Plastic Snack Food Packaging Market Shifts & Advancements
Active barrier technologies and regulatory compliance architectures are reshaping material specifications faster than converter equipment cycles can absorb, creating specification fragmentation across snack packaging portfolios.
Mono-material polyethylene laminates are electrifying flexible packaging design by enabling mechanical recyclability without sacrificing moisture and oxygen protection. European snack brands are accelerating adoption ahead of 2025 EPR fee differentiation. The technology is compressing demand for legacy multilayer structures that lack viable end-of-life pathways.
REACH restrictions on intentionally added microplastics are forcing reformulation of anti-slip and anti-fog additives common in snack films. Industrial consequence includes accelerated substitution with bio-based surface modifiers and mineral alternatives. High-clarity confectionery and nut packaging segments in Germany and France are most affected, with suppliers racing to validate replacement chemistries before 2027 enforcement.
Direct-to-consumer subscription snack boxes are fragmenting order sizes and compressing packaging changeover frequency. Small-batch craft brands and functional nutrition startups are bypassing traditional retail distribution through this channel. The shift is most visible in US and UK urban markets where fulfillment speed expectations demand pre-formed pouch formats over rollstock supply.
Flexible Plastic Snack Food Packaging Market Segmentation
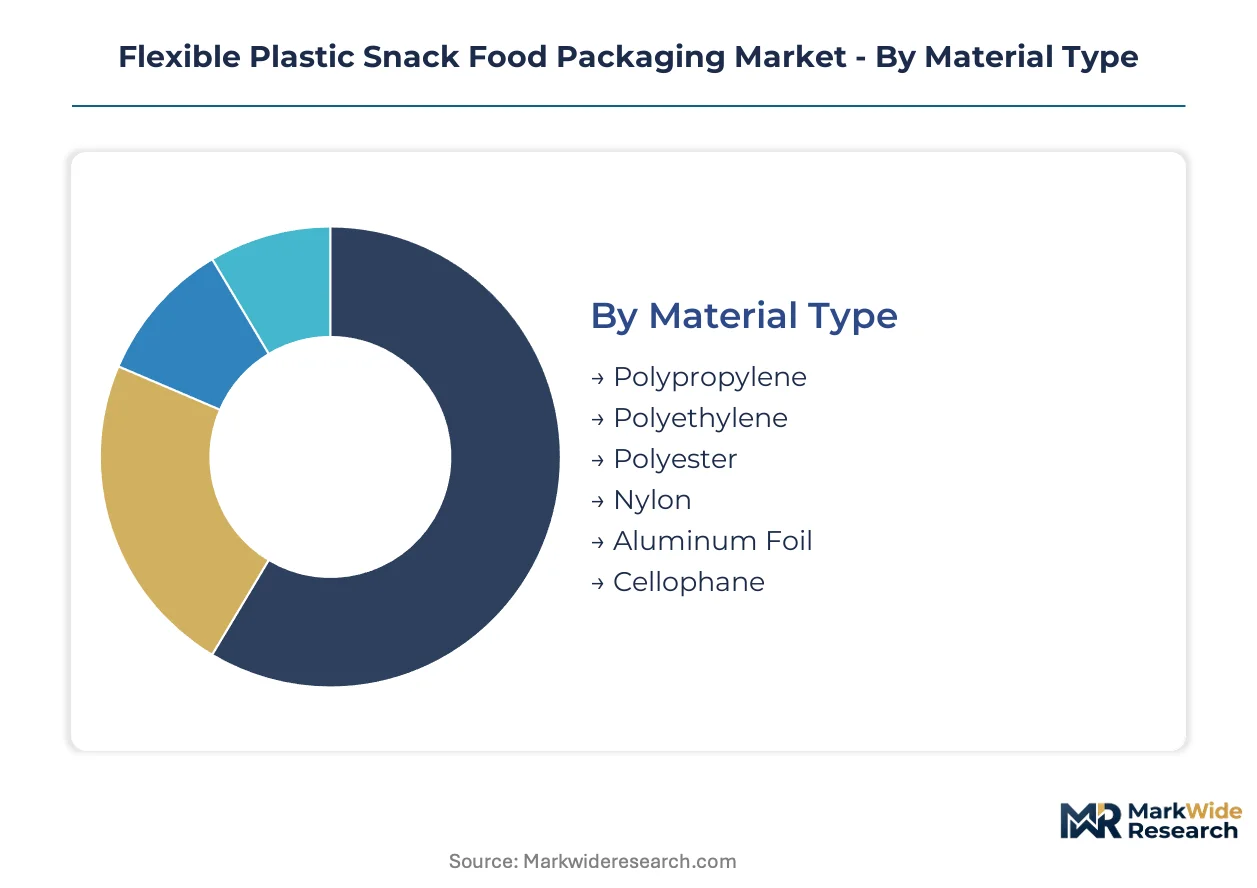
Flexible plastic snack food packaging segments reflect divergent performance requirements across oxygen sensitivity, moisture protection, and shelf-life extension. Material selection and format engineering directly determine barrier efficacy, converting efficiency, and end-of-life pathways for snack manufacturers.
Material Type:
Polypropylene and polyethylene dominate commodity volume, while premium barrier applications concentrate in polyester and nylon laminates.
- Polypropylene:Biaxially oriented and cast PP films deliver cost-efficient moisture barriers with broad heat-seal windows. Snack manufacturers in India deploy PP for potato chip and extruded snack formats where oxygen sensitivity remains moderate.
- Polyethylene:Linear low-density and high-density PE grades enable mono-material recyclable structures compliant with France's AGEC Law and Germany's VerpackG. European brand owners are accelerating PE laminate adoption ahead of EPR fee differentiation.
- Polyester:Metallized and coextruded PET layers provide oxygen scavenging for nut and dried fruit applications. Metallization thickness specifications vary by shelf-life targets.
- Nylon:Polyamide films contribute puncture resistance and aroma barrier properties to multilayer snack laminates. Coextruded nylon-PE structures serve vacuum-packed meat snacks and premium nut mixes.
- Aluminum Foil:Ultra-thin foil laminates deliver near-zero oxygen and light transmission for sensitive confectionery and functional snack categories. Foil content complicates mechanical recyclability.
- Cellophane:Regenerated cellulose films offer grease resistance and dead-fold characteristics for twist-wrap confectionery. Biodegradability positioning attracts sustainability-focused European brands.
Today's leader: Polypropylene. Tomorrow's challenger: Polyethylene mono-material laminates.
Packaging Format:
Format selection hinges on vertical form-fill-seal equipment compatibility, logistics cube efficiency, and retail shelf differentiation requirements.
- Pouch:Three-side-seal and four-side-seal pouches serve single-serve and multi-serve snack portions. Pre-formed pouch supply dominates direct-to-consumer subscription channels in US urban markets.
- Bag:Side-gusseted and pillow bags remain the workhorse format for high-volume potato chip production. Bag structures prioritize seal integrity under distribution stress.
- Wrapper:Individual portion wrappers for confectionery and granola bars demand precise dead-fold and tear propagation control. Wrapper formats face PFAS regulatory pressure for grease-resistant coatings.
- Flow Wrap:Horizontal form-fill-seal flow wrap maximizes throughput for bakery snacks and extruded products. Film tension control requirements intensify with thinner gauge specifications.
- Stand-up Pouch:Doyen and K-seal bottom gusset structures command premium shelf positioning for nuts, dried fruit, and functional snacks. Zipper and spout fitment integration expands resealability.
- Gusseted Bag:Quad-seal and side-gusseted formats optimize pallet density for club store and e-commerce bulk packs. Gusset geometry engineering affects shelf stability and fill rates.
Stand-up pouches are climbing the fastest as snack brands prioritize shelf differentiation and resealability.
End User:
End-user procurement patterns diverge between multinational snack conglomerates with centralized specification authority and regional craft brands with agile format experimentation.
- Snack Manufacturers:PepsiCo, Mondelez, and domestic Indian brands drive specification standardization across multilayer barrier films. Capital allocation toward vertical form-fill-seal line upgrades dominates North American processor investment.
- Confectionery Producers:Chocolate and sugar confectionery demand high-barrier structures with precise moisture vapor transmission rates. European producers face REACH microplastic additive restrictions.
- Beverage Companies:Snack co-packing arrangements and cross-category brand extensions create demand for format consistency with beverage packaging portfolios.
- Foodservice Providers:Institutional and airline snack portions require portion-controlled, tamper-evident flexible formats. Foodservice procurement prioritizes total delivered cost over premium barrier specifications.
Snack manufacturers anchor current volume. Confectionery producers are gaining specification influence through sustainability-driven material transitions.
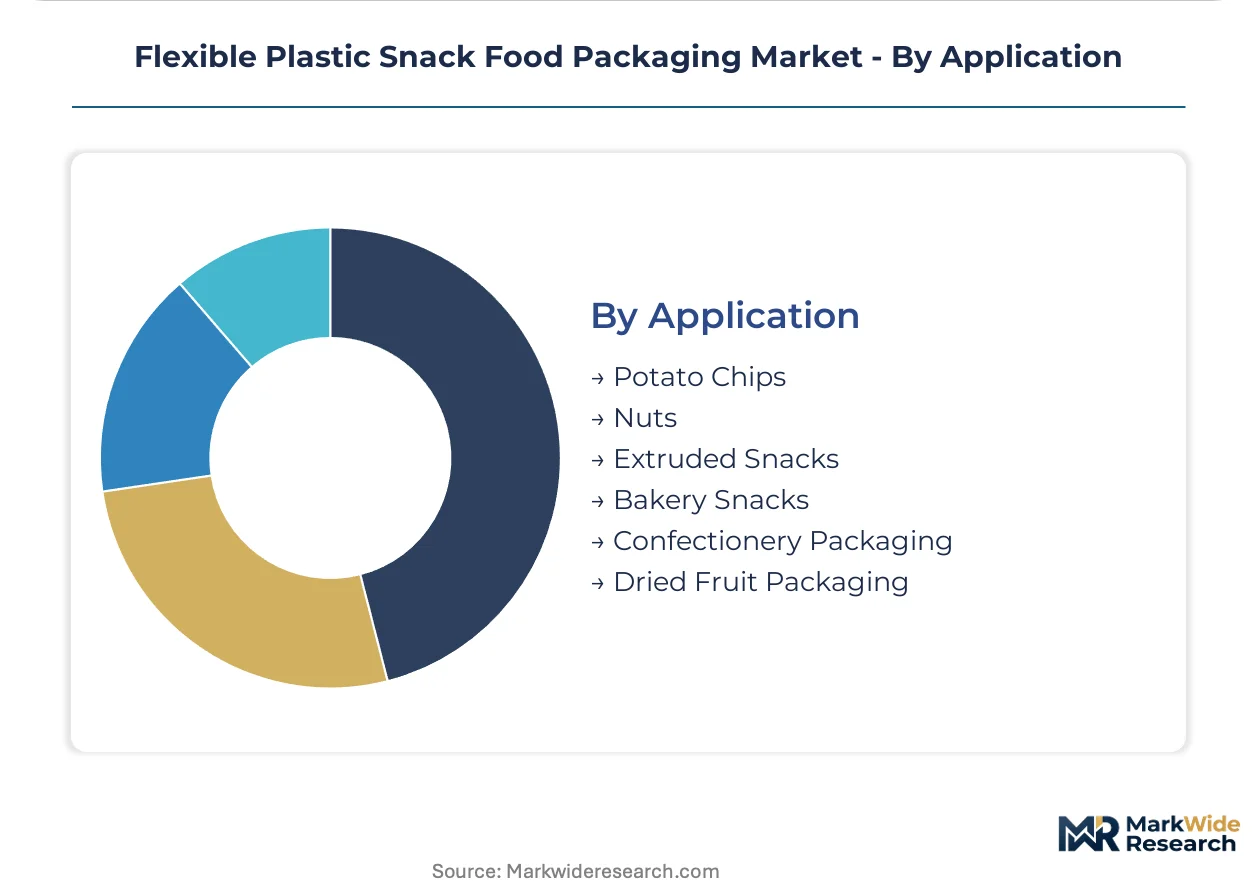
Application:
Application-specific oxygen sensitivity and oil content dictate multilayer complexity and regulatory compliance intensity.
- Potato Chips:High oil content and fragile product geometry demand nitrogen flush compatibility and puncture-resistant films. North American processors specify metallized or coextruded structures.
- Nuts:Unsaturated fat oxidation drives the most demanding oxygen barrier requirements across snack categories. Vacuum and modified atmosphere packaging adoption concentrates in premium nut segments.
- Extruded Snacks:Puffed and direct-expanded products tolerate moderate barriers but require moisture protection and seal integrity under compression. Indian domestic brands scale extruded snack pouch formats.
- Bakery Snacks:Cookies, crackers, and savory biscuits balance moisture barrier with grease resistance. PFAS phaseout timelines from the US EPA force wrapper redesigns.
- Confectionery Packaging:Chocolate fat bloom prevention and sugar crystallization control demand precise temperature stability and moisture barriers. European producers pilot paper-plastic hybrid structures.
- Dried Fruit Packaging:Hygroscopic product characteristics require moisture barriers with anti-fog clarity for retail presentation. Time-temperature indicator integration differentiates premium dried fruit brands.
Nuts command premium barrier specifications today. Dried fruit packaging is expanding most quickly through functional nutrition market positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter recycled-content mandates than the United States, while India scales domestic snack manufacturing faster than any other major economy. These divergent regulatory and demand trajectories are fragmenting regional packaging specifications.
United States
PepsiCo and Mondelez drive specification standardization for multilayer barrier films across their North American operations. The EPA's PFAS phaseout timelines force snack wrapper redesigns with fluorine-free grease barriers. Chicago and Dallas-Fort Worth anchor major flexible film converting clusters serving regional snack processors.
Germany
VerpackG extended producer responsibility frameworks create compliance-driven demand for mono-material PE laminates. The EU Packaging and Packaging Waste Regulation mandates recycled content minimums that reshape film specifications. The Rhine-Ruhr industrial corridor concentrates converter capacity serving Central European snack brands.
India
Domestic snack brands scale packaged retail distribution beyond traditional kirana stores into organized modern trade and e-commerce. FSSAI food contact regulations govern polymer safety standards for flexible packaging. Maharashtra and Gujarat host expanding flexible film manufacturing serving Haldiram's and Balaji Wafers.
China
Snack manufacturers upgrade packaging for premium nut and dried fruit exports to European and North American markets. SAMR regulates food contact materials under GB standards with increasing stringency. The Yangtze River Delta concentrates flexible packaging innovation clusters in Shanghai and Jiangsu Province.
France
AGEC Law anti-waste provisions accelerate adoption of paper-plastic hybrid structures for premium snack positioning. EPR fee differentiation by 2025 compresses demand for non-recyclable multilayer formats. The Lyon-Auvergne-Rhône-Alpes region hosts specialty converters developing kraft paper-laminate solutions.
Flexible Plastic Snack Food Packaging Market Competitive Landscape
Top-tier vendors anchor premium multilayer barrier solutions, while mid-scale converters compete on regional responsiveness and format agility. The vendor base stratifies across integrated film manufacturers, specialty laminators, and equipment-integrated packaging suppliers. Three archetypes dominate: global material science conglomerates with captive resin supply, regional converters with vertical form-fill-seal line integration, and sustainability-focused innovators commercializing mono-material structures. Competitive moves center on chemical recycling feedstock partnerships and legacy equipment retrofit programs for thinner, higher-recycled-content films.
Among publicly listed packaging conglomerates, Amcor Plc and Mondi Plc occupy positions reflecting divergent strategic bets on material transition. Amcor exemplifies the integrated global film manufacturer archetype with broad geographic manufacturing footprints. Mondi represents the paper-plastic hybrid specialist positioning for European sustainability-driven procurement. Sonoco Products Company sits within the diversified industrial packaging tier with snack food exposure through its consumer segment.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Berry Global Group, Inc. |
| Amcor Plc |
| Uflex Limited |
| Constantia Flexibles Group GmbH |
| Mondi Plc |
| Sealed Air Corporation |
| ProAmpac LLC |
| Huhtamaki Oyj |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation mandates for recycled-content minimums are forcing snack manufacturers to requalify specifications ahead of compliance deadlines, compelling converters to secure scarce rPP and rPE allocations and compressing margins across European supply chains.
Pricing Analysis
Capacity additions in India are reshaping price floors for commodity-grade polypropylene films as domestic converters scale output for Haldiram's and Balaji Wafers. Three-tier pricing structure across premium multilayer barrier, standard coextruded, and economy mono-material levels stratifies by oxygen transmission rate performance and FSSAI certification tier. Pricing pressure stems from naphtha feedstock volatility that converters cannot fully pass through quarterly contracts. Regional craft brands in the US direct-to-consumer channel exhibit highest price sensitivity, while European multinational snack conglomerates absorb premiums for VerpackG-compliant mono-material laminates.
Supply Chain Analysis
Skilled technician availability constraints in Maharashtra and Gujarat are limiting expansion speed for vertical form-fill-seal line installation and maintenance capacity. Supply concentrates in China, India, and Germany, with the Yangtze River Delta and Rhine-Ruhr corridor anchoring film manufacturing and the Maharashtra-Gujarat belt scaling fastest. Raw material flows draw from Saudi and US Gulf Coast propylene monomer, South Korean biaxial orientation equipment, and German metallization technology. Single-source vulnerability sits with pyrolysis-derived circular polymer feedstock developers still pre-commercial scale. Distribution runs through converter-direct relationships with multinational snack processors, supplemented by regional distributors serving mid-scale Indian domestic brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible plastic snack food packaging functions as a stable compounder, with regulatory-driven material transitions and India retail expansion providing durable demand foundations resistant to cyclical downturn.
For Market Incumbents: Deepen chemical recycling feedstock partnerships to secure food-contact-compliant circular polymer allocations ahead of European competitors. Expand captive film manufacturing in Maharashtra and Gujarat to capture India demand growth and reduce logistics exposure. Prioritize AGEC Law and VerpackG certification investment to defend premium positioning against emerging mono-material specialists. For New Entrants and Emerging Players: Begin with paper-plastic hybrid structure development for European premium channels where sustainability positioning commands price premiums. Target France and Germany as most penetrable geographies given AGEC Law and VerpackG compliance gaps among incumbent portfolios. Pursue direct-to-consumer subscription box pouch supply as the go-to-market angle, leveraging pre-formed format agility against rollstock-optimized incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty converters possessing pyrolysis offtake agreements and India manufacturing licenses. Long-term viability centers on 5-10 year regulatory compliance runway and circular polymer technology maturation. Monitor chemical recycling commercial scale-up announcements as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material PE Laminate Scale-Up | VerpackG fee differentiation by 2025 accelerates converter investment in recyclable structures. |
| Chemical Recycling Feedstock Partnership | Pyrolysis-derived polymers unlock food-contact compliance pathways mechanical recycling cannot achieve. |
| India Manufacturing Footprint Expansion | Maharashtra and Gujarat clusters capture Haldiram's and Balaji Wafers procurement localization. |
| Smart Packaging Integration | Time-temperature indicators differentiate premium nut brands against private label competition. |
| PFAS-Free Barrier Development | US EPA phaseout timelines force fluorine-free grease-resistant wrapper redesign investment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with snack manufacturer procurement directors, flexible film converter plant managers, polymer resin procurement leads, and FSSAI regulatory affairs specialists with secondary validation through FDA 21 CFR filings, EU 10/2011 compliance databases, SEC 10-K packaging segment disclosures, and Indian customs polymer trade records. Bottom-up volume modeling across material type, packaging format, and application segments triangulated against top-down macroeconomic anchors.
Historical reference periods anchored the projection horizon through comparable-period growth rate analysis and structural breakpoint identification. Segmentation dimensions modeled include material type barrier tier, packaging format equipment compatibility, end-user procurement centralization level, and regional regulatory framework cluster. CAGRs derived from segment-level volume trajectory analysis incorporating vertical form-fill-seal line installation rates, recycled-content mandate compliance timelines, and India modern trade expansion pace.
Several conditions sit outside the modeled scope, including unannounced PFAS regulatory acceleration, propylene monomer supply disruptions from geopolitical events, and chemical recycling technology commercialization delays. Forecasts reflect documented assumptions about regulatory enforcement consistency and feedstock cost pass-through mechanics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Nachos Market
Snacks
Specialty Snacks Market
Snacks
Jerky Snacks Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Sweet Potato Fries Market
Snacks
Granola Bars Market
Snacks
Allergy-Free Snacks Market
Snacks
United Kingdom Snack Bar Market
Snacks
Europe Popcorn Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Potato Chips Market
Snacks
Germany Snack Bar Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Saudi Arabia French Fries Market
Snacks
Organic Chips Market
Snacks
United States Children's Snack Bar Market