
 India Cashew Market | 2026-2036
India Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
India Cashew Market Foresight
Subscription-based procurement platforms for bulk cashew buyers is consolidating supply relationships between processors and food manufacturers. Kalbavi Cashews leverages its coastal processing infrastructure in Karnataka to anchor export volumes. Haldirams competes through its integrated snack manufacturing and captive cashew consumption. Royal Dry Fruits Pvt. Ltd differentiates via premium retail packaging and direct-to-consumer channel control.
India cashew denotes the processed kernel of Anacardium occidentale, typically graded by size (W-180 through W-320), moisture content below 5%, and absence of testa for white wholes, serving as a protein-lipid ingredient across food manufacturing. Whole grades command the highest unit margins in export markets, while roasted and flavored variants within product type are capturing shelf space expansion in domestic modern retail. E-commerce as a distribution channel is displacing traditional mandi-based wholesale for branded cashew sales in tier-two cities.
FSSAI standards govern maximum aflatoxin limits and labeling requirements for packaged cashew products, while BIS certification applies to grading and quality benchmarks for export consignments. The Agricultural and Processed Food Products Export Development Authority regulates export registration and traceability protocols for international shipments. Stakeholders must monitor how evolving EU MRL standards and domestic organic certification expansion reshape processing investments and farm-gate sourcing priorities.
Market Dynamics
Subscription-based procurement platforms are consolidating supply relationships between cashew processors and food manufacturers, compressing traditional mandi-based wholesale intermediation while tightening quality traceability requirements under FSSAI mandates.
Growth Catalysts
- Roasted and flavored variants:These value-added formats are capturing shelf space expansion in domestic modern retail, pulling demand away from commodity whole grades toward processed snack ingredients.
- FSSAI food safety mandates:Tightening aflatoxin limits and labeling requirements are filtering out informal processors, concentrating volume among certified facilities with laboratory testing capabilities.
- Export-oriented production clusters:Maharashtra and Kerala processing infrastructure supports port-adjacent operations that minimize logistics friction for international shipments.
Market Restraints
- Raw cashew nut import dependency:Domestic processing capacity exceeds local farm supply by approximately threefold, forcing reliance on West African and Southeast Asian origins with currency and shipping cost volatility.
- Moisture-controlled storage capex:Kernel quality degradation below 5% moisture thresholds requires climate-controlled warehousing that informal traders cannot finance.
- EU MRL standard divergence:European Union maximum residue limits for agricultural chemicals operate stricter than domestic BIS benchmarks, bifurcating export-grade from domestic-grade processing lines.
Strategic Opportunities
- Organic certification expansion:Farm-level conversion programs in Karnataka and Goa are unlocking premium pricing in German and Dutch retail channels that mandate EU organic equivalence.
- E-commerce direct-to-consumer channels:Tier-two city households are bypassing traditional wholesale mandis for branded packaged cashews through platform-controlled logistics.
- PLI scheme for food processing:Production-linked incentive disbursements for integrated cold chain and value-addition infrastructure are subsidizing processor capital deployment.
Industry Challenges
- Skilled grading labor scarcity:Visual kernel classification into W-180 through W-320 grades requires trained sorters that coastal processing clusters struggle to retain.
- Traceability system integration:APEDA export registration protocols demand farm-to-fork documentation that legacy procurement networks cannot digitize without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cashew Market |
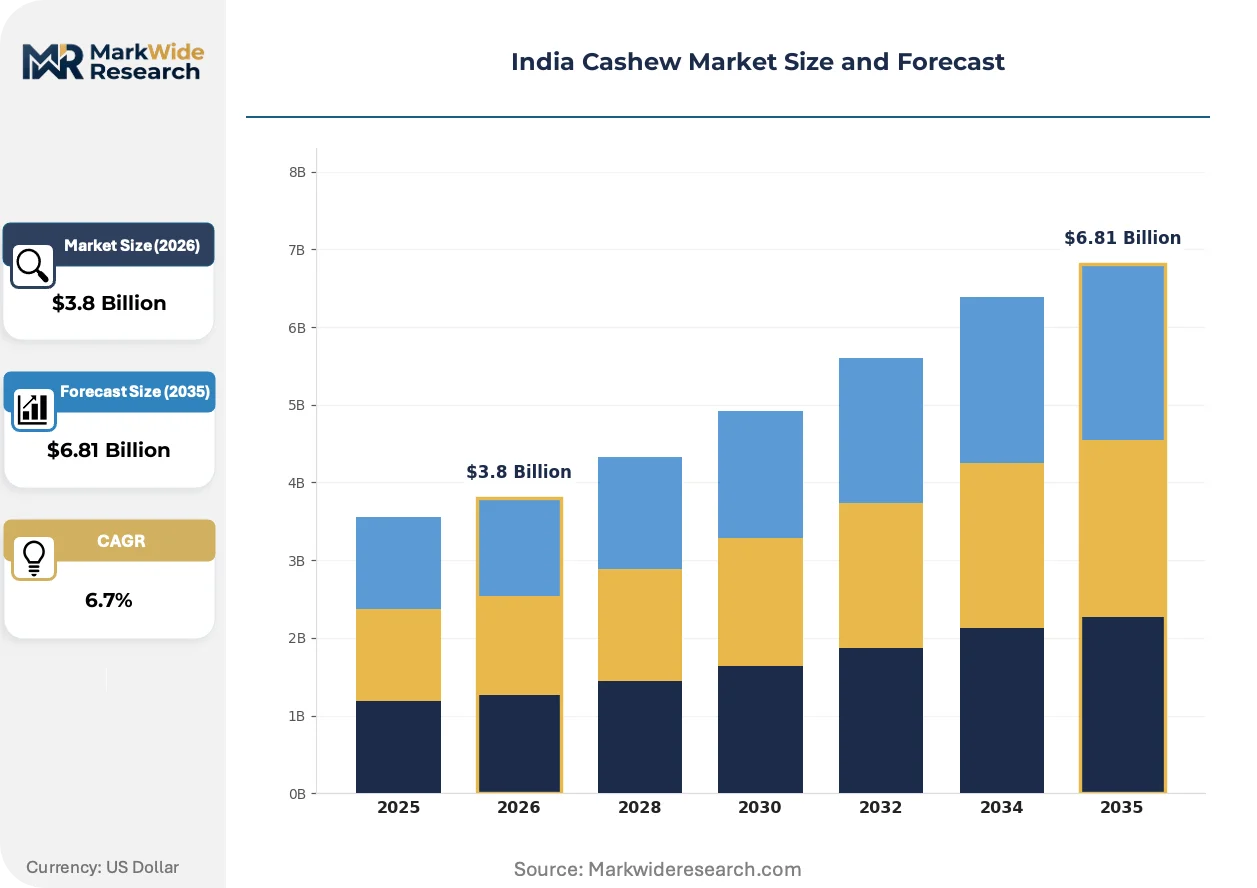
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole, Cut, Roasted, Flavored End User: Food Industry, Snack Producers, Confectionery, Bakery Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales Packaging Type: Bags, Jars, Vacuum Packs, Bulk |
| Companies Covered | Royal Dry Fruits Pvt. Ltd, Haldirams, Delicious Cashew Co., Shakti Dry Foods, Kalbavi Cashews, Wonderland Foods, Athav Products, Sri Kamalam Enterprises, Greendot Health Foods Pvt. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cashew Market Shifts & Advancements
Steam-based testa removal and automated optical sorting are displacing manual processing methods across coastal facilities, while regulatory digitization and channel fragmentation simultaneously reshape competitive positioning.
Steam peeling technology is electrifying kernel processing economics by eliminating the water-intensive soaking stage that previously generated effluent compliance costs. Mid-scale processors in Kollam and Mangalore are adopting these systems at replacement cycle points, cutting water consumption by approximately 70% while improving whole-kernel recovery rates. This capital shift is compressing margins for processors locked into traditional drum-roasting and manual peeling configurations.
FSSAI's 2022 amendment to the Food Safety and Standards (Contaminants, Toxins and Residues) Regulations tightened aflatoxin B1 limits for tree nuts to 10 micrograms per kilogram. Export-oriented processors in Kerala are retrofitting in-house thin-layer chromatography testing to preempt rejection at EU border inspection posts. The compliance burden falls disproportionately on small-scale roasters supplying unorganized retail, accelerating consolidation toward integrated processing-cum-export houses.
Modern trade buyers are consolidating procurement through annual volume contracts with traceability documentation, displacing spot mandi purchases that dominated through 2019. Reliance Retail and DMart are directly sourcing from Karnataka processing clusters with BIS-certified grading, bypassing Mumbai-based commission agents. This channel shift is most visible in Maharashtra's urban corridors, where branded packaged cashews now command 35-40% of modern retail nut shelf space versus under 15% five years prior.
India Cashew Market Segmentation
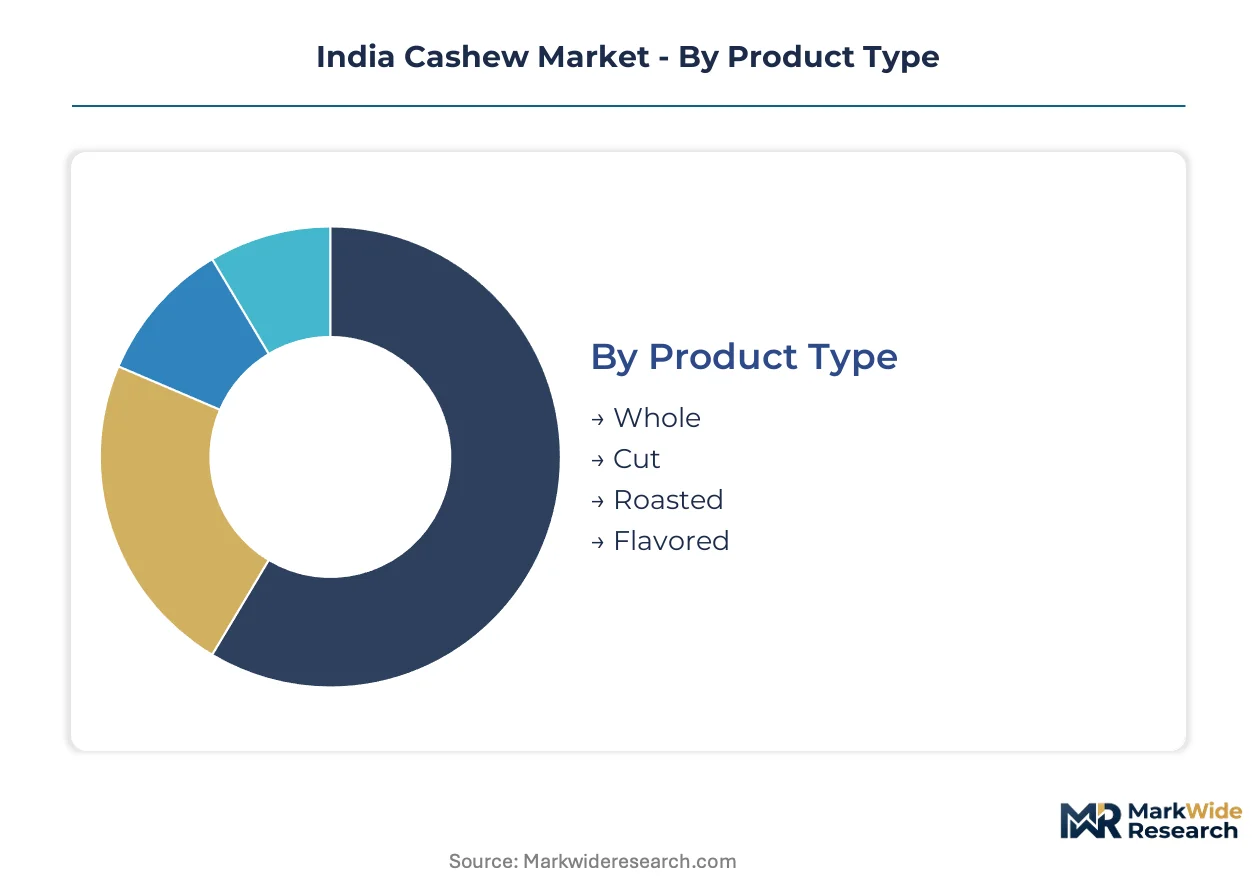
Segmentation in the India cashew market reveals how processing depth and channel control determine margin capture. Upgrade cycles in roasting equipment and packaging automation are redistributing volume between commodity handlers and integrated value-add processors.
Product Type:
Equipment replacement cycles favor processors that can pivot between kernel grades without line reconfiguration.
- Whole:Unbroken kernels graded W-180 through W-320 with testa fully removed and moisture below 5%. Maharashtra and Kerala processing clusters supply export houses demanding visual uniformity for European retail private labels, constrained by FSSAI aflatoxin ceilings that filter out informal operators.
- Roasted:Oil-roasted or dry-roasted kernels with shelf-stable fat stability. Snack producers in Gujarat and Tamil Nadu are expanding captive roasting capacity to secure margin that previously flowed to third-party processors, pulling demand from commodity whole grades.
- Cut:Broken kernel pieces sorted by size for food manufacturing ingredient use. Bakery and confectionery buyers in Mumbai and Delhi NCR specify cut grades for cost-controlled formulations.
- Flavored:Masala, salted, or honey-coated variants targeting impulse purchase occasions. Modern retail shelf space expansion in tier-two cities is accelerating flavor innovation cycles.
Volume placements concentrate in Whole; the faster expansion belongs to Roasted.
End User:
Customer-type stratification separates price-tolerant exporters from cost-pressured domestic ingredient buyers.
- Food Industry:Bulk ingredient procurement for dairy alternatives, protein fortification, and culinary bases. Karnataka processing clusters with BIS-certified grading anchor supply relationships with integrated food manufacturers.
- Snack Producers:Haldirams and regional brands demanding roasted and flavored kernel supply with consistent oil absorption profiles. These buyers are consolidating vendor lists to processors with in-house laboratory testing capabilities.
- Confectionery:Cut and whole grades for praline, chocolate inclusion, and nougat applications. Quality specifications prioritize fat content stability over visual grade.
- Bakery:Cost-optimized cut grades for cookie, cake, and pastry inclusions. Price sensitivity here limits supplier margins compared to export-oriented segments.
Revenue concentration sits with Food Industry; Snack Producers are climbing the fastest.
Distribution Channel:
Channel fragmentation is compressing traditional mandi intermediation while platform logistics reshape tier-two access.
- E-commerce:Branded packaged sales through platform-controlled fulfillment networks. Direct-to-consumer channels are displacing wholesale mandis in Pune, Hyderabad, and Ahmedabad urban corridors.
- Retail:Modern trade and kirana store placement for packaged cashews. Reliance Retail and DMart are consolidating annual volume contracts with traceability documentation.
- Wholesale:Spot mandi transactions and commission-agent mediated bulk sales. This channel retains dominance in raw cashew nut procurement but is losing processed kernel share.
- Direct Sales:Processor-to-manufacturer contracts with fixed pricing and quality specifications. Export-oriented houses in Kollam and Mangalore favor this channel for EU-bound shipments.
Transaction volume still flows through Wholesale; E-commerce is gaining share fastest.
Packaging Type:
Packaging automation investments separate premium-positioned brands from commodity handlers.
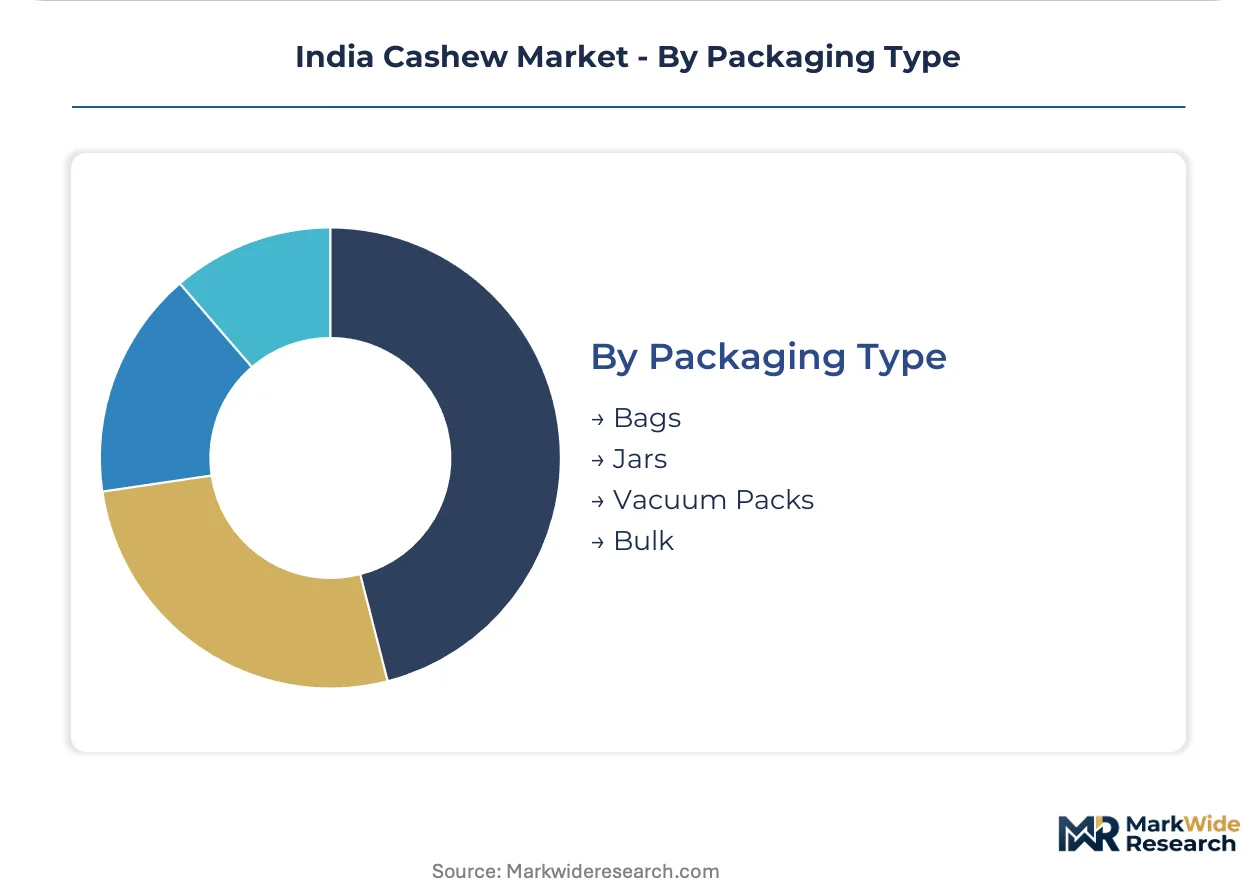
- Vacuum Packs:Oxygen-barrier films extending shelf life to 12-plus months for export and premium domestic positioning. Kerala processors are retrofitting vacuum lines to capture German and Dutch retail listings.
- Jars:Rigid PET or glass containers for modern retail shelf presence and gifting occasions. Royal Dry Fruits and similar brands leverage jar formats for direct-to-consumer channel control.
- Bags:Flexible pouches for economy and standard tier positioning. This format dominates kirana store distribution with lower per-unit packaging cost.
- Bulk:10-25 kg industrial packaging for food manufacturing and institutional catering. Cut grades and roasting inputs move primarily through this channel.
Shipment weight concentrates in Bulk; Vacuum Packs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes roughly three times its domestic raw cashew nut harvest, creating a structural dependency on West African and Southeast Asian farm supply that shapes regional infrastructure investments. Coastal processing clusters concentrate in states with port access and FSSAI-certified laboratory capacity, while inland demand centers pull finished product through diverging channel structures.
Maharashtra
Mumbai anchors India's largest cashew export corridor, with Nhava Sheva port handling containerized kernel shipments to European and Middle Eastern buyers. The state's FSSAI-notified laboratories support aflatoxin testing protocols that preempt EU border rejections. Ratnagiri and Sindhudurg districts host processing estates that upgraded to steam-peeling systems during 2020-2023 replacement cycles, cutting water use while improving whole-kernel recovery rates.
Kerala
Kollam district retains India's densest concentration of legacy processing capacity, with family-owned units clustering around the Ashtamudi Lake waterway network. APEDA export registration requirements have forced digitization investments among mid-scale operators, bifurcating compliant houses from informal traders. The state's organic conversion programs in Kasaragod and Wayanad districts are unlocking German retail listings that mandate EU organic equivalence certification.
Karnataka
Mangalore's coastal processing belt leverages Karnataka's PLI scheme disbursements for integrated cold chain infrastructure, subsidizing vacuum-packaging line deployments. The state's BIS-certified grading facilities anchor annual volume contracts with Reliance Retail and DMart, bypassing Mumbai commission agents. Udupi and Karwar sub-regions are expanding testa-removal capacity to serve snack producers in neighboring Tamil Nadu and Gujarat.
Gujarat
Surat and Vadodara house captive roasting operations for domestic snack brands, pulling cut and whole grades from Karnataka and Maharashtra processors. The state's food manufacturing tax incentives under the Industrial Policy have attracted Haldirams and regional competitors to expand in-house kernel processing. Gandhidham's port infrastructure supports re-export of value-added formats to Gulf Cooperation Council markets with shorter shelf-life requirements.
Tamil Nadu
Chennai's modern retail corridor drives flavored and roasted variant demand, with platform logistics enabling direct-to-consumer penetration in Coimbatore and Madurai tier-two markets. The state's FSSAI enforcement cells have accelerated informal processor exits since 2022, concentrating volume among integrated houses with in-house testing. Tirunelveli and Thoothukudi districts are emerging as alternative processing locations with lower labor costs than Kerala's saturated coastal belt.
India Cashew Market Competitive Landscape
Top-tier vendors anchor export-oriented processing with FSSAI-certified laboratory infrastructure, while mid-scale regional operators compete on flavor innovation and modern retail shelf placement. The vendor base stratifies across integrated processing-cum-export houses, snack manufacturing conglomerates with captive kernel consumption, and premium retail brands controlling direct-to-consumer channels. Three archetypes dominate: coastal processors with port-adjacent logistics, diversified food manufacturers backward-integrating into roasting capacity, and brand houses leveraging packaging automation for tier-two e-commerce penetration. Competitive moves concentrate on vendor list consolidation by snack producers and vacuum-line retrofitting for European retail listings.
Within the coastal processing archetype, Kalbavi Cashews occupies a position exemplifying Karnataka's port-anchored export model, while Kerala-based operators represent the legacy Kollam processing tradition. Haldirams sits within the diversified food manufacturing tier, its captive consumption patterns illustrating backward integration into kernel roasting. Royal Dry Fruits Pvt. Ltd anchors the premium brand house segment, its direct-to-consumer channel control representing packaging-automation investments that bypass traditional wholesale mandis.
| Leading Market Players |
|---|
| Royal Dry Fruits Pvt. Ltd |
| Haldirams |
| Delicious Cashew Co. |
| Shakti Dry Foods |
| Kalbavi Cashews |
| Wonderland Foods |
| Athav Products |
| Sri Kamalam Enterprises |
| Greendot Health Foods Pvt. Ltd |
| Others |
Supply & Pricing Matrix
Backward integration into captive roasting capacity anchors both supply security and margin defense for snack producers competing against commodity kernel traders. Haldirams and Gujarat-based snack manufacturers leverage in-house oil-roasting lines to capture value that previously flowed to third-party processors, while FSSAI-certified export houses in Kerala and Karnataka command premium positioning through laboratory-tested aflatoxin compliance.
Pricing Analysis
Margin tightening in economy-tier cut grades reflects snack producers' captive capacity expansion and reduced spot mandi dependency. Pricing stratifies across premium vacuum-packed export wholes, standard branded retail jars, and economy bulk cuts for bakery ingredient use. Price differentiation rests on FSSAI certification status and BIS grade verification, with uncertified informal operators facing forced exit. Cost-down pressure on standard-tier roasted variants accelerates as Reliance Retail and DMart consolidate annual volume contracts with traceability documentation. Bakery buyers exhibit highest price sensitivity, while German and Dutch retail channels tolerate premium positioning for EU organic equivalence.
Supply Chain Analysis
Direct-to-manufacturer channels handle food industry bulk procurement, bypassing Mumbai commission agents that dominated through 2019. Raw cashew nut supply draws from West African origins—Ivory Coast, Ghana, and Nigeria—plus Vietnam and Cambodia, with Indian processing capacity exceeding domestic farm output threefold. Kernel quality hinges on climate-controlled warehousing below 5% moisture thresholds and steam-peeling equipment retrofits. Single-source vulnerability concentrates in Nhava Sheva port logistics for EU-bound containerized shipments. Distribution runs through Karnataka processing clusters with BIS-certified grading anchoring modern retail contracts, while legacy Kollam waterway networks serve fragmented informal trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic raw cashew nut supply constraints prop kernel pricing, with West African import dependency creating structural vulnerability to currency and shipping cost volatility that sustains processor margin pressure.
For Market Incumbents: Extend FSSAI-certified laboratory infrastructure to preempt EU MRL standard divergence and APEDA traceability mandates that filter informal competitors. Consolidate vendor relationships with snack producers through fixed-price annual contracts, defending against Haldirams-style captive roasting expansion that erodes third-party processor volumes. Prioritize vacuum-packaging line retrofits for German and Dutch retail listings that mandate EU organic equivalence. For New Entrants and Emerging Players: FSSAI's 2022 aflatoxin limit amendment opens a window for laboratory-equipped mid-scale processors to capture share from informal roasters exiting unorganized retail. Target Karnataka and Tamil Nadu tier-two e-commerce corridors where platform logistics enable direct-to-consumer bypass of wholesale mandis. Lead with flavored variant innovation cycles—masala, honey-coated, salted—targeting impulse purchase occasions in modern retail shelf space expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated processing-cum-export houses with APEDA registration and EU organic certification. Long-term viability across the analysis window favors coastal processors with port-adjacent logistics and steam-peeling technology deployment. Watch Karnataka PLI scheme disbursement velocity as inflection indicator for subsidized cold chain infrastructure deployment that reshapes competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Steam-Peeling Technology Deployment | Kollam and Mangalore processors cut water consumption 70% while improving whole-kernel recovery rates. |
| FSSAI Laboratory Certification Investment | In-house thin-layer chromatography testing preempts EU border rejection and filters informal competitors. |
| Direct-to-Consumer E-Commerce Launch | Platform-controlled logistics in Pune and Hyderabad displace traditional mandi-based wholesale intermediation. |
| EU Organic Equivalence Certification | Kasaragod and Wayanad farm-level conversion programs unlock premium German and Dutch retail listings. |
| Cold Chain Infrastructure Expansion | Karnataka PLI scheme disbursements subsidize vacuum-packaging line deployments for export-grade processing. |
Research Methodology
APEDA export registration databases, FSSAI notification records, and BIS certification registries formed the secondary backbone, cross-referenced with customs shipment manifests and modern retail procurement disclosures. Primary interviews with cashew processing plant managers, snack producer procurement leads, Reliance Retail category buyers, and Kerala-based export house operators validated secondary findings. Bottom-up and top-down triangulation reconciled processor capacity estimates with end-user consumption patterns.
Bottom-up modeling built from individual processor output capacities, grade-specific recovery rates, and channel-specific price realizations, while top-down analysis anchored aggregate market sizing to APEDA export value disclosures and modern retail shelf space audit data. Segmentation dimensions spanned product type, end user, distribution channel, and packaging format. CAGRs derived from regression analysis of historical export volume trajectories and domestic modern retail penetration curves, with PLI scheme disbursement schedules and EU MRL standard evolution as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for steam-based testa removal versus traditional water-intensive soaking would alter the outlook for processor capital deployment and water compliance economics. Forecasts reflect assumptions regarding West African raw cashew nut supply continuity, FSSAI enforcement intensity, and EU organic certification uptake rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Pistachios Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Rubus Idaeus (Raspberry) Seeds Market