
 Low-Calorie Sweet Treats Market | 2026-2036
Low-Calorie Sweet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Sweet Treats Market Analytics
Aftermarket recipe licensing revenue is fragmenting as branded food manufacturers seek direct control over low-calorie formulation IP. Nestlé S.A. leverages its in-house sweetener research infrastructure to protect margin pools in chocolate and confectionery. Mondelez International anchors its competitive stance through specialized cookie and biscuit portfolios reformulated with erythritol blends. Halo Top Creamery dominates the ice cream sub-category with a manufacturing model built around high-protein, low-calorie density.
Low-calorie sweet treats comprise confectionery, frozen desserts, and baked goods formulated with non-nutritive or reduced-calorie sweeteners to achieve sub-100 kcal standard serving profiles while maintaining sensory parity with full-sugar equivalents. Manufacturers employ extrusion, cold-press, or cryogenic freezing to preserve texture integrity when sugar bulk is removed. The ice cream segment leads absolute value generation due to premium pricing tolerance, while the gummies category posts the fastest trajectory as gelatin-free, pectin-based formulations with stevia gain shelf space in European and North American health food stores. Monk fruit sweetener applications concentrate margin in specialty channels where clean-label claims command price premiums over sucralose-based mass-market equivalents.
The FDA governs sugar-substitute GRAS determinations and nutrition-labeling claims in the United States, while EFSA evaluates novel food approvals and health claim substantiation across European member states. Japan's Ministry of Health, Labour and Welfare maintains positive-list controls for food additives including erythritol and steviol glycosides, creating divergent compliance pathways for exporters. Stakeholders must monitor pending FAO/WHO Codex revisions on sweetener acceptable daily intake thresholds and calibrate formulation pipelines accordingly.
Market Dynamics
Formulation IP consolidation among branded manufacturers is restructuring competitive access to monk fruit and stevia supply chains, forcing contract manufacturers to rebuild margin through captive extraction partnerships or lose shelf-space allocation to vertically integrated rivals.
Growth Catalysts
- EFSA Novel Food Approvals:Accelerated steviol glycoside clearance timelines reduce European market entry barriers for pectin-based gummy formulations, expanding clean-label distribution.
- Fitness Enthusiast Bulk Purchasing:Weight-conscious consumer cohorts in Germany and Japan now drive case-lot procurement of high-protein frozen desserts through direct-to-factory subscription channels.
- Extrusion Technology Maturation:Cold-press and cryogenic freezing equipment advances enable texture parity in sugar-bulk-reduced baked goods without gelatin dependency.
Market Restraints
- Monk Fruit Supply Concentration:Cultivation remains geographically locked to Guilin prefecture in southern China, exposing formulators to harvest volatility and input cost spikes.
- Erythritol Fermentation Capacity:Microbial production infrastructure concentrates among three industrial biotech suppliers, creating bottleneck risk for cookie and biscuit reformulation pipelines.
- Japan MHLW Positive-List Controls:Additive approval timelines for new sweetener blends extend 18-24 months versus FDA GRAS self-determination pathways, delaying product launches.
Strategic Opportunities
- Saudi Arabian Health-Labeling Mandates:Front-of-pack sugar warning regulations create first-mover advantage for sub-100 kcal confectionery entrants in Gulf retail expansion.
- Pectin-Stevia Convergence:Gelatin-free gummy formulations capture shelf space in European health food channels as clean-label claims displace animal-derived alternatives.
- Direct-to-Consumer Frozen Dessert Subscriptions:Cold-chain logistics investments enable high-protein ice cream brands to bypass traditional retail slotting fee structures entirely.
Industry Challenges
- Sensory Scientist Talent Scarcity:Formulators capable of masking stevia's licorice aftertaste in chocolate applications command premium compensation, constraining R&D team scaling.
- GRAS Self-Determination Documentation:FDA notification requirements for new sweetener blends demand toxicology investment exceeding mid-cap manufacturer cash flow capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Sweet Treats Market |
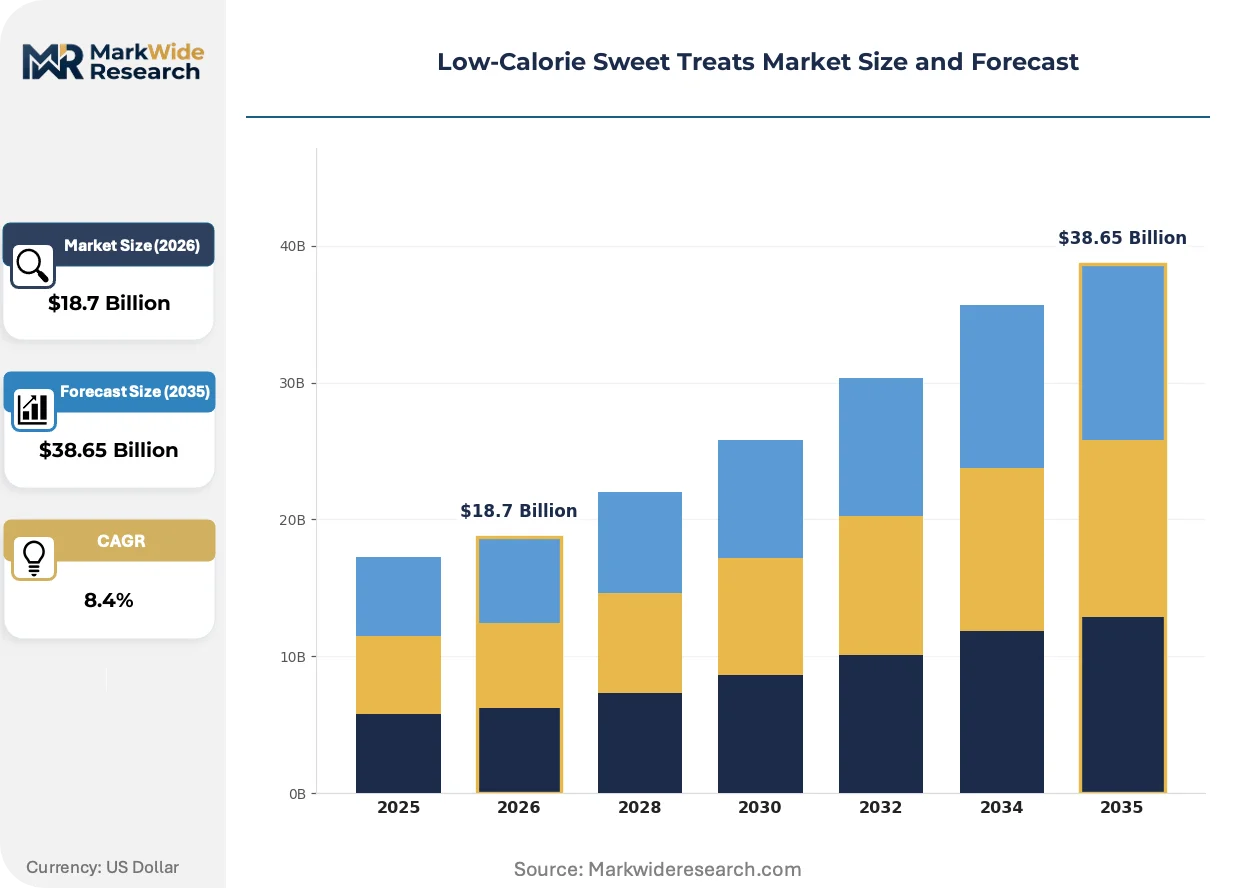
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookies, Chocolate, Gummies, Ice Cream Sweetener Used: Stevia, Erythritol, Sucralose, Monk Fruit Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Target Audience: Fitness Enthusiasts, Weight Watchers, Diabetics, Health-Conscious Consumers |
| Companies Covered | Nestlé S.A., Mondelez International, General Mills, Unilever, The Kraft Heinz Company, Danone S.A., Kellogg Company, Halo Top Creamery, The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Sweet Treats Market Evolving Landscape
Digital formulation platforms are compressing product development cycles while regulatory divergence between FDA self-determination and EFSA novel food pathways forces dual-track compliance investment.
Computational flavor modeling is virtualizing traditional bench-scale recipe iteration, allowing stevia-monk fruit blend optimization in silico before physical production. Mid-sized confectionery manufacturers in the United States adopt these tools to reduce sensory testing costs by half. The technology is virtualizing the historical advantage of large in-house R&D departments, enabling smaller entrants to match formulation precision.
EFSA's tightened health claim substantiation requirements for reduced-calorie positioning now demand human intervention studies rather than compositional analysis alone. Chocolate and frozen dessert manufacturers must redesign clinical trial budgets to maintain on-pack messaging. The ice cream segment bears disproportionate compliance burden given premium pricing tolerance tied to explicit health claims.
Health food store buyers now consolidate procurement through specialized low-calorie distributors rather than direct manufacturer relationships. Independent retailers in Germany and Japan favor curated category management over fragmented supplier negotiations. This channel compression concentrates shelf-access leverage with three dominant health-food distributors, forcing smaller brands to accept margin compression or exit specialty retail entirely.
Low-Calorie Sweet Treats Market Segmentation
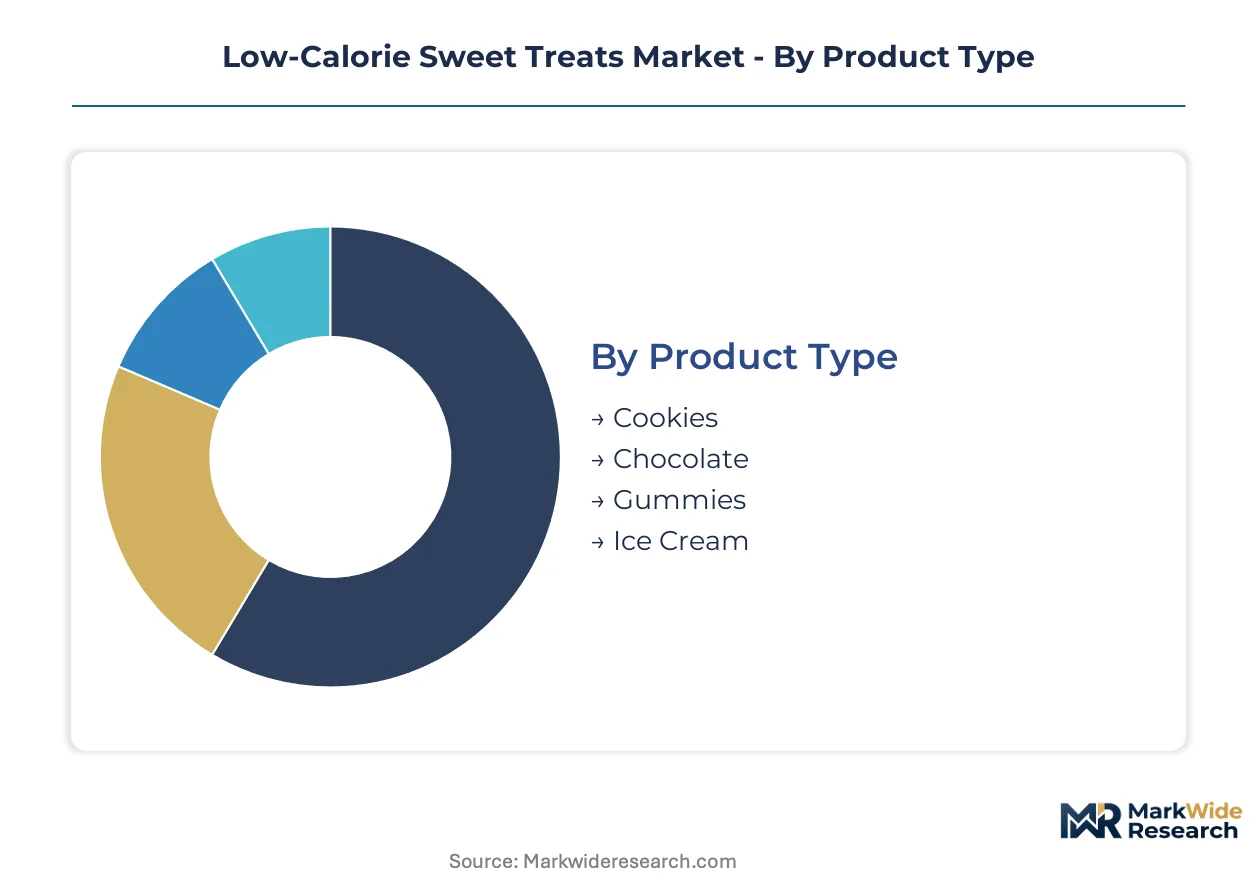
Segmentation in low-calorie sweet treats reveals divergent technical requirements across product physics and consumer physiology. Manufacturers must match sweetener bulk properties to processing constraints while calibrating distribution intensity to audience purchasing frequency.
Product Type:
Mature frozen dessert platforms coexist with emerging gummy formats as formulation science advances.
- Ice Cream:High-protein, low-calorie density formulations rely on cryogenic freezing to maintain texture integrity when sugar bulk is removed. Demand concentrates in the United States and Japan where direct-to-consumer subscription channels bypass traditional retail slotting fees.
- Gummies:Pectin-based, gelatin-free formulations with stevia sweetening capture shelf space in European health food stores as clean-label claims displace animal-derived alternatives. The segment posts the steepest expansion trajectory as EFSA novel food approvals accelerate European market entry.
- Cookies:Erythritol-blended biscuit portfolios address texture challenges through cold-press extrusion technology maturation.
- Chocolate:Monk fruit applications concentrate in specialty channels where clean-label claims command price premiums over sucralose-based mass-market equivalents.
Ice Cream handles the majority of throughput; Gummies is the fastest mover on share.
Sweetener Used:
Cost tier differentiation separates natural extraction from synthetic production pathways.
- Stevia:Steviol glycoside formulations dominate clean-label positioning across European and North American health food channels. FDA GRAS self-determination enables rapid US product launches versus EFSA's novel food approval timelines.
- Monk Fruit:Mogroside V extraction from Guilin prefecture cultivation locks supply geographically, exposing formulators to harvest volatility and input cost spikes in premium chocolate applications.
- Erythritol:Microbial fermentation production concentrates among three industrial biotech suppliers, creating bottleneck risk for cookie and biscuit reformulation pipelines.
- Sucralose:Synthetic high-intensity sweetening retains mass-market confectionery positioning where cost minimization outweighs clean-label premiums.
Stevia handles the majority of throughput; Monk Fruit is expanding most quickly on share.
Distribution Channel:
Volume concentration favors high-frequency retail while margin capture shifts toward specialized curation.
- Supermarkets:Mass-market shelf-space allocation for reduced-calorie positioning drives case-lot procurement in Germany and Japan where health-labeling regulations favor sub-100 kcal standard serving profiles.
- Health Food Stores:Independent retailers in Germany and Japan favor curated category management through three dominant specialized distributors, forcing smaller brands to accept margin compression or exit specialty retail entirely.
- Online Retail:Direct-to-factory subscription channels enable fitness enthusiast bulk purchasing of high-protein frozen desserts with cold-chain logistics investments bypassing traditional retail slotting fee structures.
- Specialty Shops:Premium positioning for monk fruit-sweetened chocolate concentrates in channels where sensory parity with full-sugar equivalents justifies price premiums.
Supermarkets handles the majority of throughput; Health Food Stores is climbing the fastest on share.
Target Audience:
Application intensity varies by physiological constraint and purchasing behavior frequency.
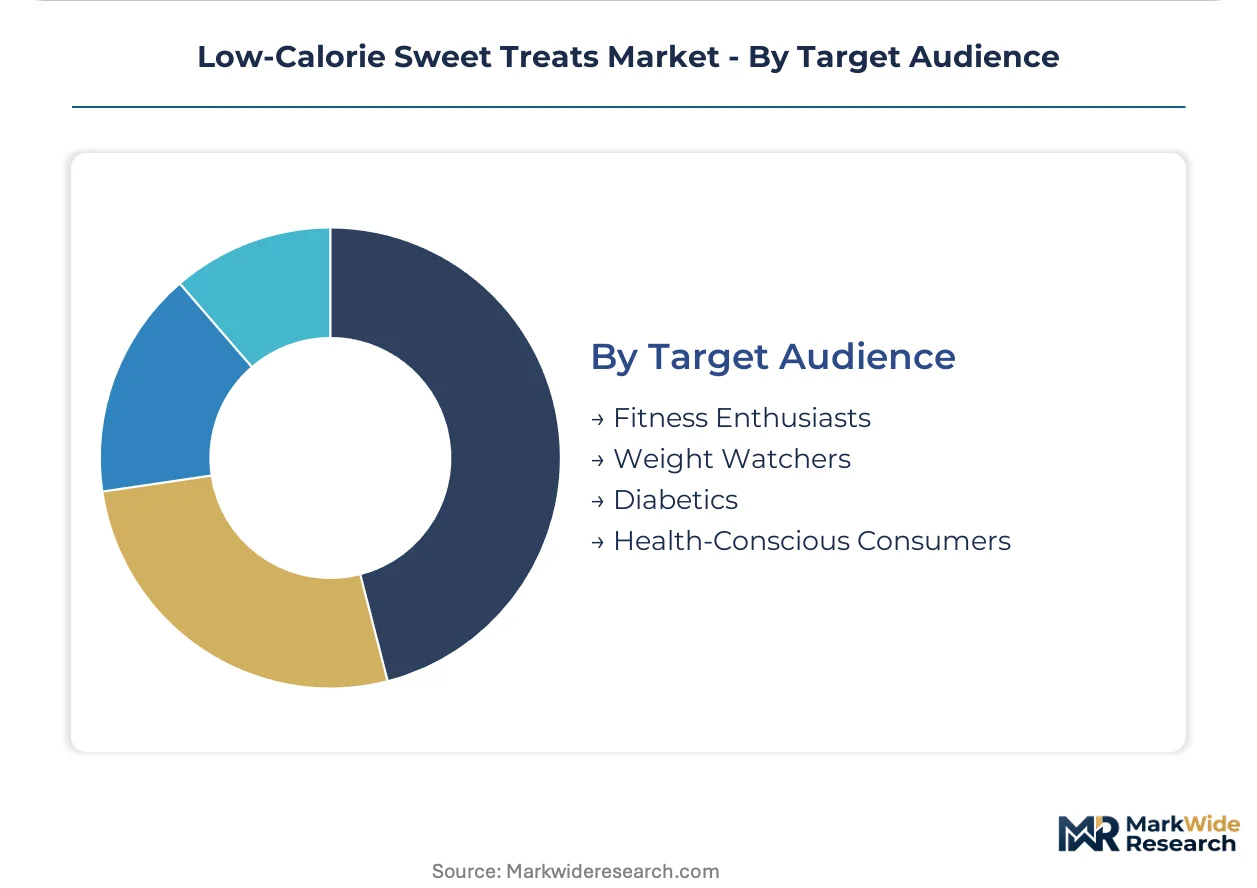
- Fitness Enthusiasts:High-protein, low-calorie density frozen dessert consumption drives direct-to-consumer subscription volumes with case-lot procurement patterns.
- Weight Watchers:Sub-100 kcal standard serving profiles across confectionery and baked goods align with Saudi Arabian front-of-pack sugar warning regulations.
- Diabetics:Glycemic control requirements favor erythritol and stevia formulations with explicit blood glucose management claims.
- Health-Conscious Consumers:Clean-label purchasing decisions displace sucralose-based alternatives in European and North American specialty retail.
Fitness Enthusiasts handles the majority of throughput; Health-Conscious Consumers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for low-calorie sweet treats varies sharply by geography. Japanese consumers accept substantial price premiums for clean-label positioning, while German buyers respond more aggressively to per-unit cost signals in supermarket channels.
United States
Fitness enthusiasts drive case-lot procurement through direct-to-consumer subscription channels for high-protein frozen desserts. FDA GRAS self-determination pathways enable rapid product launches for stevia-based formulations. Chicago and Minneapolis-St. Paul anchor manufacturing concentration as cold-chain logistics investments bypass traditional retail slotting fees.
Germany
Health-labeling regulations and retail shelf-space allocation favor reduced-calorie positioning in mass-market confectionery. EFSA novel food approval timelines for steviol glycosides shape European market entry strategies for pectin-based gummy formulations. Hamburg and Munich concentrate distribution infrastructure as independent health food retailers consolidate procurement through specialized distributors.
Japan
Weight-conscious consumer cohorts exhibit highest tolerance for premium pricing in high-protein, low-calorie density ice cream. Ministry of Health, Labour and Welfare positive-list controls for erythritol and steviol glycosides create 18-24 month approval delays versus FDA pathways. Tokyo and Osaka metropolitan areas dominate demand concentration with specialized retail channels commanding clean-label price premiums.
China
Monk fruit cultivation remains geographically locked to Guilin prefecture in southern China, exposing global formulators to harvest volatility. National food safety standards and SAMR additive approvals govern domestic market access for reduced-calorie positioning. Shanghai and Beijing concentrate import demand for premium chocolate applications where mogroside V extraction commands specialty channel margins.
Saudi Arabia
Front-of-pack sugar warning regulations create first-mover advantage for sub-100 kcal confectionery entrants in Gulf retail expansion. SFDA labeling mandates align with weight management positioning across imported and domestic manufactured goods. Riyadh and Jeddah anchor retail modernization as health-conscious purchasing decisions displace traditional full-sugar alternatives.
Low-Calorie Sweet Treats Market Competitive Landscape
Capability concentration sits with branded manufacturers owning in-house sweetener research infrastructure; scale advantage sits with diversified food conglomerates with existing retail shelf-space allocation. The market structure tilts toward consolidation as formulation IP protection becomes the primary margin defense mechanism. Three strategic archetypes dominate: vertically integrated sweetener researchers, specialized sub-category champions, and diversified portfolio players leveraging existing distribution. M&A activity targets captive extraction partnerships and direct-to-consumer cold-chain capabilities.
Among Swiss-domiciled conglomerates, Nestlé S.A. exemplifies the vertically integrated research archetype through captive sweetener infrastructure. Mondelez International and Halo Top Creamery occupy positions at opposite ends of the specialization spectrum—diversified snacking portfolios versus sub-category concentration in frozen desserts. These three anchors illustrate how formulation control and distribution strategy separate margin pools in a market where sensory parity commands price premiums.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Mondelez International |
| General Mills |
| Unilever |
| The Kraft Heinz Company |
| Danone S.A. |
| Kellogg Company |
| Halo Top Creamery |
| The Hershey Company |
| Others |
Value Network & Pricing Analysis
Monk fruit harvest volatility in Guilin prefecture determines both tier spreads between natural and synthetic sweetener formulations and the geographic shape of extraction partnerships. Manufacturers face pricing compression when cultivation shortfalls force substitution toward higher-cost stevia or erythritol blends, reshaping margin allocation across premium and mass-market positioning.
Pricing Analysis
After-sales licensing revenue from formulation IP drives lifetime value for branded manufacturers controlling proprietary sweetener blends. Three-tier pricing structure across premium monk fruit-sweetened chocolate, standard stevia-based gummies, and economy sucralose confectionery reflects clean-label certification intensity and sensory parity investment. Pricing pressure stems from contract manufacturers losing shelf-space allocation to vertically integrated rivals with captive extraction infrastructure. Fitness enthusiasts purchasing through direct-to-consumer channels show lowest price sensitivity, while mass-market supermarket buyers in Germany respond aggressively to per-unit cost signals.
Supply Chain Analysis
Upstream mogroside V extraction draws from geographically locked cultivation in Guilin prefecture, China, with secondary steviol glycoside sourcing from Paraguay and Kenya. Raw material dependencies center on monk fruit concentrate, erythritol fermentation output, and pectin gelling agents. Single-source vulnerability concentrates in China's harvest cycles, exposing formulators to input cost spikes and reformulation delays. Distribution runs through three dominant health-food distributors in Germany and Japan, with cold-chain direct-to-consumer subscriptions bypassing traditional retail slotting fees entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation scientist scarcity constrains R&D team scaling for stevia aftertaste masking in chocolate applications, creating asymmetric capability gaps between large in-house research departments and mid-cap manufacturers dependent on digital platforms.
For Market Incumbents: Entrench formulation IP control through captive monk fruit extraction partnerships in Guilin prefecture, protecting margin pools from harvest volatility exposure. Expand cryogenic freezing capacity in Chicago and Minneapolis-St. Paul to defend high-protein frozen dessert positioning against subscription-channel entrants. Vertical integration into steviol glycoside processing reduces EFSA novel food approval dependency for European pectin-gummy launches. For New Entrants and Emerging Players: Establish a beachhead in Saudi Arabian confectionery through front-of-pack sugar warning regulatory alignment, capturing first-mover shelf space before incumbent reformulation cycles complete. Target health-conscious consumer segments in European specialty retail with gelatin-free pectin-stevia gummies, leveraging EFSA accelerated approval timelines. Deploy direct-to-consumer cold-chain logistics to bypass distributor consolidation in Germany and Japan. For Investors and Strategic Acquirers: Pending FAO/WHO Codex revisions on sweetener acceptable daily intake thresholds reshape the acquisition landscape, favoring targets with dual-track FDA-EFSA compliance infrastructure already deployed. Long-term viability centers on formulation platforms capable of rapid reconfiguration across monk fruit, stevia, and erythritol blends. Monitor steviol glycoside clearance velocity at EFSA as the signal indicating which portfolio companies can sustain European clean-label positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Extraction Partnership | Guilin prefecture monk fruit sourcing locks input cost predictability for premium chocolate applications. |
| Cryogenic Freezing Scale-Up | Chicago and Minneapolis-St. Paul cold-chain investments bypass traditional retail slotting fee structures. |
| Dual-Track Regulatory Compliance | Parallel FDA GRAS and EFSA novel food pathways accelerate product launches across Atlantic markets. |
| Direct-to-Consumer Subscription Launch | Fitness enthusiast case-lot procurement displaces supermarket dependence in high-protein frozen desserts. |
| Pectin-Stevia Formulation Pivot | Gelatin-free gummy repositioning captures clean-label shelf space in German health food channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at confectionery manufacturers, category buyers at German and Japanese health food retailers, formulation scientists specializing in stevia masking, and cold-chain logistics directors. Secondary validation drew from FDA GRAS notification databases, EFSA novel food approval registers, Japanese MHLW positive-list amendments, and customs records tracking monk fruit concentrate imports. Bottom-up volume estimates from individual product launches were triangulated against top-down category spend data from retail audit channels.
Calibration across the analysis window employed segment-level modeling spanning product type, sweetener technology, distribution channel intensity, and target audience purchasing frequency. CAGRs were derived from trajectory fitting against historical approval-to-launch cycles and subscription-channel adoption curves. Industry-specific inputs included EFSA clearance velocity for steviol glycosides, Guilin prefecture harvest yield variance, and direct-to-consumer cold-chain penetration rates in metropolitan clusters.
Stress conditions across monk fruit harvest shortfalls, erythritol fermentation capacity constraints, and Japanese MHLW approval timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and consumer clean-label premium tolerance. Cross-checking against Nielsen retail audit data and health food distributor procurement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Indonesia Snack Bar Market
Snacks
Potato Chips Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Oat-Based Snacks Market
Snacks
Italy Energy Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
North America Baked Savory Snacks Market
Snacks
Sweet Potato Chips Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Popcorn Market
Snacks
Qatar Potato Chips Market
Snacks
North America Snack Food Market
Snacks
Plant-Based Snacks Market
Snacks
North America Snack Pellets Market
Snacks
South America Energy Bar Market