
 Snack Subscription Market | 2026-2036
Snack Subscription Market Size, Share, and Industry Trends Forecast 2026-2036
Snack Subscription Market Analytics
Delivery logistics talent shortages across last-mile networks is unwinding capacity expansion plans for several subscription operators. Bokksu leverages its Japan-focused sourcing relationships to sustain premium positioning in the Asian snack niche. Universal Yums anchors its model on rotating country-themed curation, while SnackCrate competes through aggressive geographic variety in its monthly offerings.
A snack subscription constitutes a recurring-commerce arrangement where consumers receive curated packaged food assortments at predetermined intervals, typically involving shelf-stable items with defined portion weights, allergen labeling, and temperature-controlled shipping protocols for chocolate or dairy-inclusive products. The service fulfills discovery, convenience, and gifting functions across residential and workplace environments. Healthy Snacks and Gourmet Treats command the dominant margin pools as consumers prioritize functional ingredients and artisanal provenance over mass-market alternatives. Monthly Subscription pricing dominates revenue volume, though Annual Subscription structures capture superior retention economics and reduce churn exposure for platform operators.
The FDA governs nutrition labeling and food safety standards for all interstate snack shipments, while the USDA oversees organic certification claims that many healthy-oriented subscriptions prominently feature. State-level cottage food laws create fragmented compliance terrain for small-batch suppliers integrating into subscription supply chains. Stakeholders must monitor evolving packaging waste regulations and extended producer responsibility frameworks as sustainability disclosure requirements tighten across multiple jurisdictions.
Market Dynamics
The snack subscription sector is experiencing acute pressure from last-mile logistics capacity constraints, as delivery network talent shortages force operators to compress geographic expansion timelines and prioritize retention economics over acquisition scale.
Growth Catalysts
- Corporate wellness mandates:Employer-funded food perk programs are expanding rapidly as retention strategies, with curated snack boxes now standard in hybrid workplace environments across technology and professional services sectors.
- FDA Nutrition Facts modernization:Updated labeling requirements for packaged foods are accelerating clean-label sourcing investments, pushing subscription services toward transparent ingredient disclosure that resonates with health-conscious subscribers.
- Rotational curation models:Country-themed discovery formats are capturing sustained engagement by delivering novel sensory experiences that resist the commoditization affecting static product assortments.
Market Restraints
- Last-mile labor scarcity:Delivery network capacity constraints in dense urban corridors are inflating per-unit fulfillment costs and constraining serviceable market expansion.
- Cocoa and nut input volatility:Climate-driven supply disruptions in West African cocoa regions and California almond belts are compressing margin structures for premium chocolate-inclusive assortments.
- State cottage food fragmentation:Inconsistent small-batch producer regulations across US jurisdictions create compliance friction for artisanal supplier onboarding.
Strategic Opportunities
- Annual subscription lock-in:Prepaid twelve-month structures reduce churn exposure and improve cash flow predictability for platform operators willing to sacrifice near-term revenue velocity.
- Temperature-controlled shipping protocols:Investment in cold-chain capabilities for dairy-inclusive and chocolate-heavy assortments opens premium positioning unavailable to ambient-only competitors.
- Extended producer responsibility frameworks:Early compliance with emerging packaging waste regulations in California and New York jurisdictions creates defensible sustainability credentials.
Industry Challenges
- Allergen cross-contamination protocols:Maintaining segregated handling infrastructure for gluten-free and nut-free SKUs demands capital-intensive facility reconfiguration.
- Supplier certification timelines:Organic and non-GMO verification processes from USDA-accredited bodies extend supplier onboarding cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snack Subscription Market |
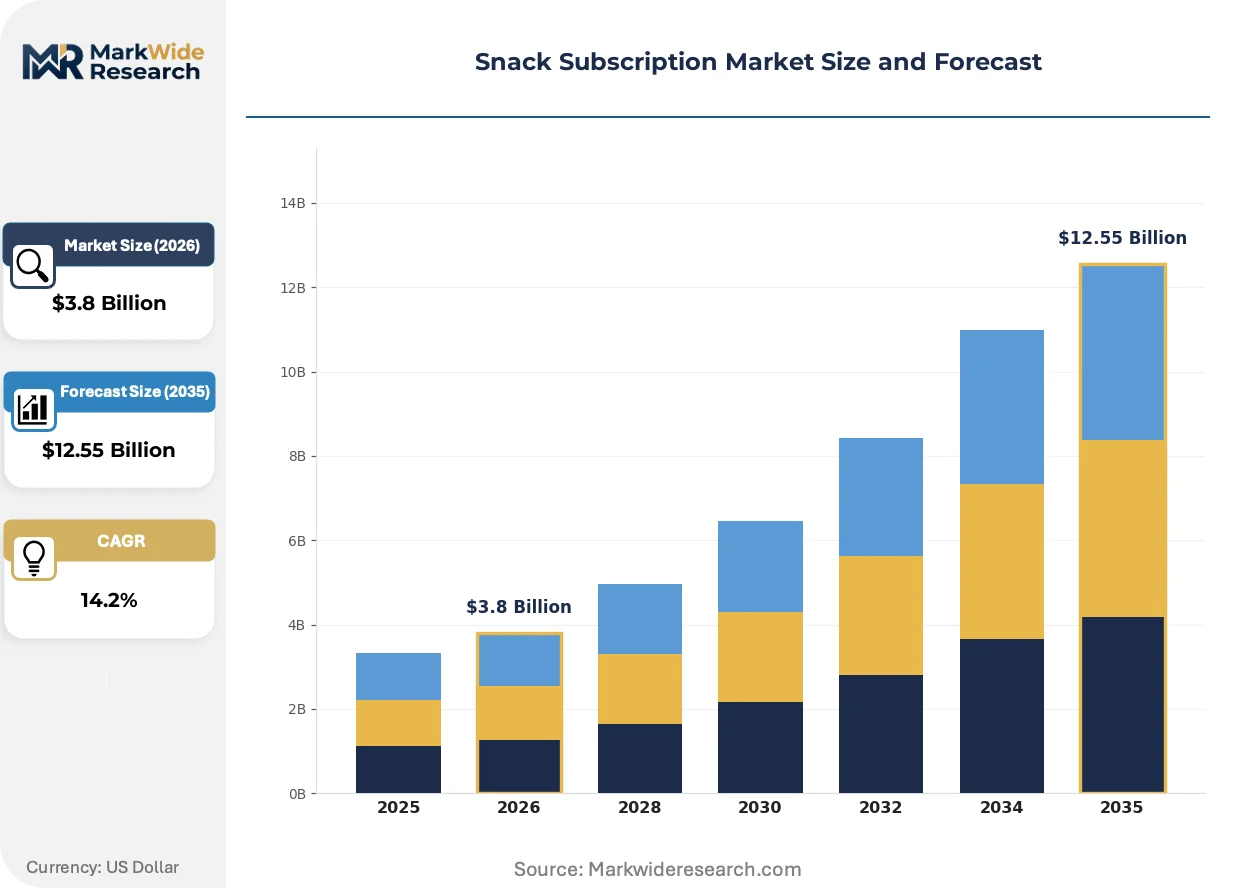
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Healthy Snacks, Gourmet Treats, Sweet Snacks, Savory Snacks Pricing Model: Monthly Subscription, Quarterly Subscription, Annual Subscription, Pay-As-You-Go Delivery Frequency: Weekly, Bi-Weekly, Monthly, Seasonal Customer Segment: Families, Professionals, Students, Fitness Enthusiasts |
| Companies Covered | SnackCrate, Munch Addict, Bokksu, Japan Crate, Candy Club, TokyoTreat, Sakuraco, ZenPop, Universal Yums, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snack Subscription Market Evolving Landscape
Discovery-driven curation is displacing convenience-centric positioning as the primary subscriber value proposition, with sensory novelty and artisanal provenance now commanding premium pricing power over mass-market accessibility.
Artificial intelligence-powered preference matching is fragmenting the traditional one-box-fits-all model. Machine learning algorithms analyze individual consumption patterns and dietary restrictions to generate hyper-personalized assortments. Premium subscribers in coastal metropolitan clusters are adopting these tools fastest, enabling operators to capture superior lifetime value through reduced cancellation rates.
Extended producer responsibility legislation in California and New York is mandating packaging waste reduction targets for direct-to-consumer food shippers. Subscription operators must redesign outer containers and individual product wraps to meet recycled content minimums. Healthy snack segments with sustainability-forward positioning are absorbing compliance costs fastest to maintain price premiums.
Employer procurement of snack subscriptions as standardized workplace amenities is displacing individual consumer purchasing. Human resources departments now negotiate enterprise contracts with volume tiers and dietary accommodation guarantees. Technology sector campuses in Austin, Seattle, and San Francisco are exhibiting the densest adoption of this B2B channel shift.
Snack Subscription Market Segmentation
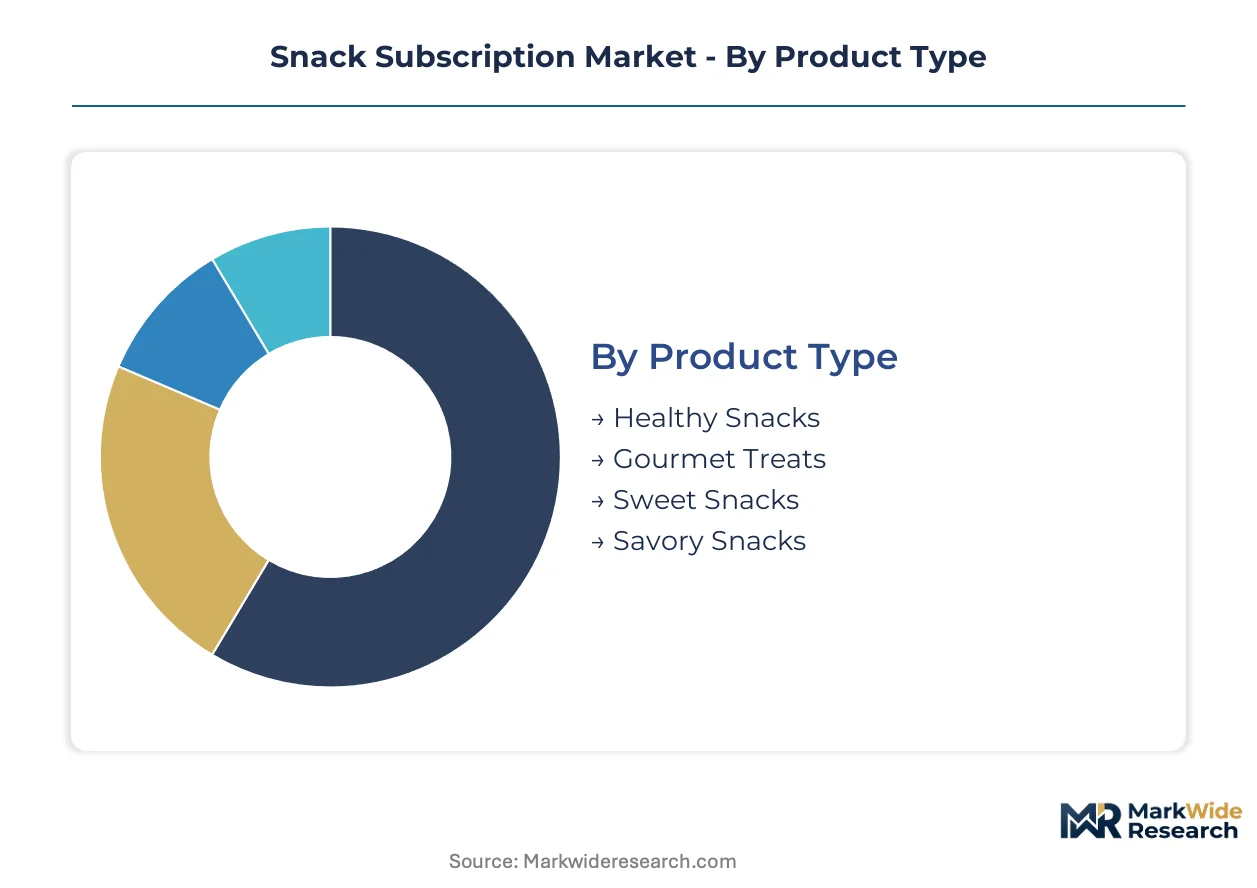
Snack subscription operators must align curation depth, price architecture, and delivery cadence with discrete consumption occasions and buyer psychographics. Segmentation discipline separates margin-accretive niches from commodity-adjacent categories vulnerable to supermarket private-label encroachment.
Product Type:
Healthy Snacks face the most acute substitution pressure from mass-market retailers now stocking clean-label alternatives at subscription-competitive price points.
- Healthy Snacks:Functional ingredient formulations featuring protein fortification, probiotic inclusions, and low-glycemic sweeteners. Demand concentrates among fitness enthusiasts in California and New York metropolitan corridors where workplace wellness stipends offset premium pricing.
- Gourmet Treats:Artisanal small-batch products with traceable provenance and limited production runs. Coastal professionals in Seattle and Austin drive adoption through gifting occasions and discovery-oriented personal consumption.
- Sweet Snacks:Chocolate-inclusive and confectionery assortments requiring temperature-controlled logistics. FDA allergen labeling mandates elevate compliance costs for operators sourcing from fragmented cottage food producers.
- Savory Snacks:Shelf-stable crackers, jerky, and seasoned nuts with extended ambient stability. Lower shipping complexity attracts price-sensitive subscribers in secondary metropolitan markets.
Healthy Snacks anchors the volume base while Gourmet Treats gains share at the steepest rate.
Pricing Model:
Prepaid structures concentrate margin protection capabilities among operators with sufficient balance sheet depth to absorb near-term revenue compression.
- Monthly Subscription:Recurring billing at thirty-day intervals with cancellation flexibility. The dominant revenue format across urban millennial and Gen Z subscriber bases prioritizing liquidity preservation.
- Quarterly Subscription:Ninety-day prepaid cycles with modest per-box discounts. Appeals to seasonal gift purchasers and subscribers seeking reduced administrative friction.
- Annual Subscription:Twelve-month upfront payment capturing superior retention economics. Cash flow predictability enables sourcing investments and cold-chain infrastructure expansion.
- Pay-As-You-Go:Single-box purchases without recurring commitment. Highest per-unit pricing accommodates trial behavior and one-time gifting occasions with minimal platform loyalty.
Monthly Subscription generates the transaction volume while Annual Subscription delivers the strongest unit economics.
Delivery Frequency:
Logistics network capacity constraints in dense urban corridors force frequency optimization toward routes with consolidated drop density.
- Weekly:Seven-day replenishment cycles for high-velocity households with multiple snack-consuming members. Last-mile labor scarcity limits viable serviceable markets to primary metropolitan clusters.
- Bi-Weekly:Fourteen-day intervals balancing freshness preferences with shipping cost absorption. The fastest-expanding frequency among hybrid workplace subscribers with irregular office attendance patterns.
- Monthly:Standard thirty-day cadence aligning with salary cycles and budget planning routines. Dominant format for individual professionals and cost-conscious family segments.
- Seasonal:Quarterly or holiday-timed boxes emphasizing limited-edition curation and gifting functionality. Elevated price points support artisanal supplier margins and exclusive sourcing arrangements.
Monthly cadence anchors subscriber retention while Bi-Weekly frequency climbs fastest among corporate wellness deployments.
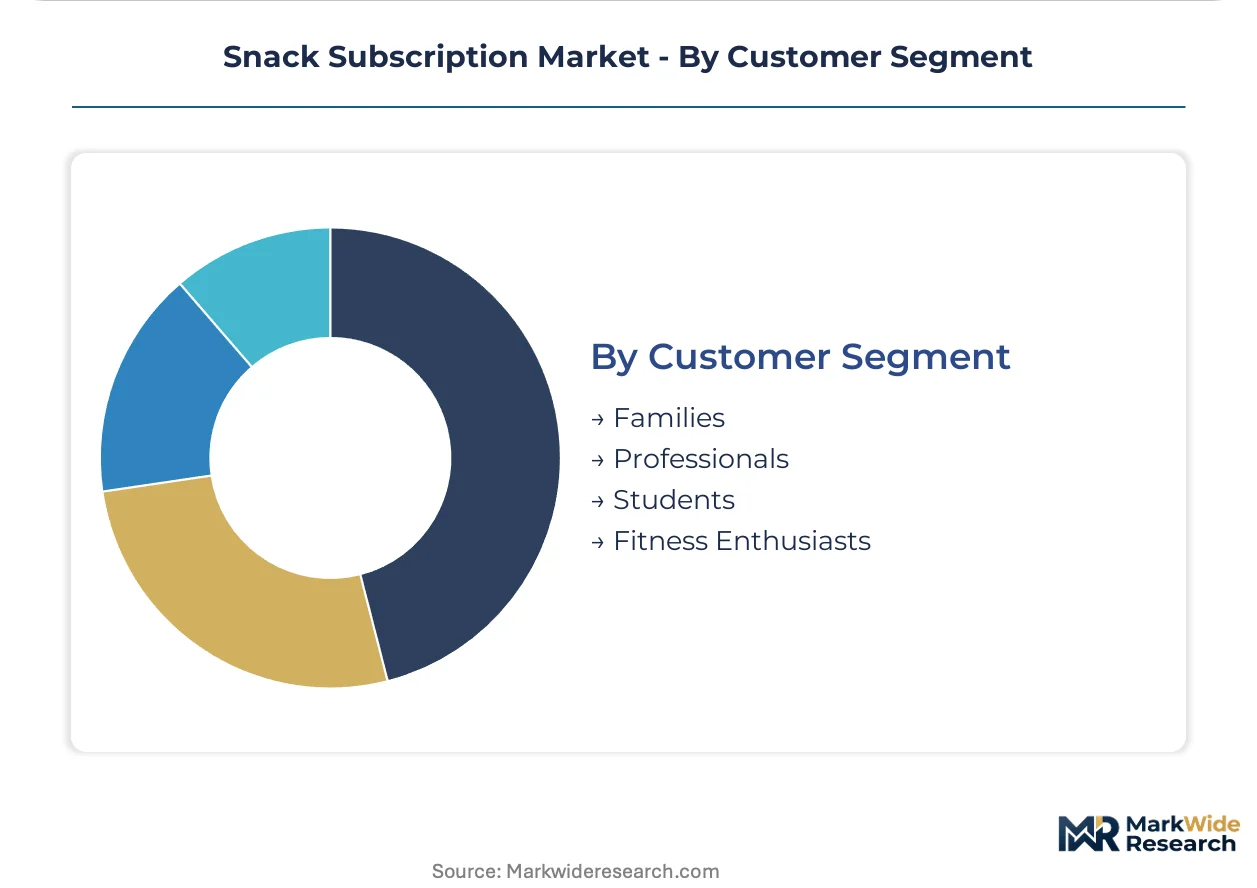
Customer Segment:
Employer-funded procurement is displacing individual purchasing authority across technology and professional services verticals.
- Families:Multi-person households requiring volume-tiered assortments with broad palate accommodation. Allergen segregation protocols and child-friendly portioning drive curation complexity.
- Professionals:Individual subscribers in white-collar employment with discretionary income and workplace consumption habits. Human resources departments now negotiate enterprise contracts with dietary accommodation guarantees.
- Students:Price-sensitive demographic prioritizing value-per-calorie and sharing economy dynamics. Subscription fatigue manifests in higher churn rates absent steep educational discounts.
- Fitness Enthusiasts:Performance-oriented consumers demanding macro-nutrient transparency and functional ingredient verification. USDA organic certification and third-party testing claims command substantial pricing premiums.
Professionals anchor revenue concentration while Fitness Enthusiasts expand most quickly on a percentage basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennials and Gen Z professionals in coastal metropolitan clusters consume snack subscriptions as discovery-oriented lifestyle products, while corporate procurement in technology corridors treats them as standardized workplace amenities. This consumption-mix differential separates individual subscriber markets from employer-funded deployments across national boundaries.
United States
Technology sector campuses in Austin, Seattle, and San Francisco drive densest B2B adoption through human resources-negotiated enterprise contracts. The FDA's updated Nutrition Facts labeling requirements push operators toward transparent ingredient disclosure and clean-label sourcing investments. New York and California metropolitan corridors concentrate individual subscriber demand among fitness enthusiasts prioritizing functional ingredient formulations.
Japan
Artisanal small-batch producers supply premium positioning through traceable provenance and limited production runs that command pricing power in export markets. METI oversees standards for organic and functional food claims that subscription services prominently feature in marketing materials. Tokyo and Osaka anchor domestic consumption while specialized exporters target overseas Japanese diaspora communities.
Germany
Employer-funded wellness stipends offset premium pricing for healthy snack segments featuring protein fortification and probiotic inclusions. EFSA governs nutrition and health claims that operators must substantiate before marketing functional ingredients. Berlin and Munich metropolitan areas concentrate demand among white-collar professionals with discretionary income and workplace consumption habits.
United Kingdom
Hybrid workplace subscribers with irregular office attendance patterns favor bi-weekly delivery frequencies balancing freshness with shipping cost absorption. The Food Standards Agency enforces allergen labeling mandates that elevate compliance costs for operators sourcing from fragmented cottage food producers. London and Southeast England dominate subscriber concentration through gifting occasions and discovery-oriented personal consumption.
South Korea
Fitness enthusiasts demanding macro-nutrient transparency and functional ingredient verification drive fastest percentage-based expansion among customer segments. MFDS regulates health functional food claims that subscription services leverage for premium positioning. Seoul Capital Area concentrates demand through workplace wellness programs and individual professional purchasing.
Snack Subscription Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure fragmenting across geographic curation specializations and temperature-controlled logistics capabilities. The upper tier commands premium positioning through exclusive sourcing relationships and cold-chain infrastructure, while mid-tier operators compete on rotational novelty and price accessibility. Three archetypes dominate: country-themed discovery curators, healthy functional ingredient specialists, and corporate wellness platform providers. Competitive moves concentrate on annual subscription lock-in structures and strategic partnerships with artisanal suppliers.
Within the country-themed discovery tier, Bokksu and Universal Yums exemplify contrasting geographic anchoring strategies. Bokksu occupies a position as a Japan-focused sourcing specialist sustaining premium positioning through exclusive artisanal relationships. Universal Yums represents the rotating multi-country format capturing sustained engagement through novel sensory experiences. SnackCrate sits within the aggressive geographic variety segment, competing through breadth of monthly offerings rather than depth of single-origin curation.
| Leading Market Players |
|---|
| SnackCrate |
| Munch Addict |
| Bokksu |
| Japan Crate |
| Candy Club |
| TokyoTreat |
| Sakuraco |
| ZenPop |
| Universal Yums |
| Others |
Value Network & Pricing Analysis
USDA organic certification gates supplier qualification and price differentiation simultaneously, as subscription operators must absorb four-to-six-month verification timelines while commanding tiered premiums for certified assortments. This regulatory filter concentrates sourcing relationships among established producers capable of sustaining documentation burdens, compressing margin structures for mid-tier operators unable to scale certification investments.
Pricing Analysis
Long-term offtake contracts with artisanal producers anchor premium tier pricing, while spot-market sourcing from cottage food operators supports economy positioning. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic assortments from conventional clean-label and mass-market alternatives. Cost compression in the standard tier is intensifying because California almond and West African cocoa supply disruptions inflate input costs. Students represent the most price-sensitive buyer segment, demanding steep educational discounts, while corporate wellness procurement exhibits the least sensitivity due to employer-funded stipends.
Supply Chain Analysis
Japan and South Korea anchor artisanal snack production through specialized small-batch manufacturers supplying premium export markets. California and Texas concentrate domestic healthy snack manufacturing, with the latter benefiting from lower facility costs and centralized distribution reach. Temperature-controlled logistics for chocolate-inclusive assortments rests on single-source vulnerability to cold-chain carrier capacity constraints in dense urban corridors. Distribution runs through direct-to-consumer parcel networks with last-mile consolidation, though enterprise contracts increasingly bypass retail intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Snack subscription platforms face an inflection toward ecosystem economics as AI-powered preference matching fragments the one-box-fits-all model and employer procurement systems demand API interoperability with HR software stacks.
For Market Incumbents: Consolidate exclusive sourcing relationships with Japan-based artisanal producers before regional competitors replicate Bokksu's provenance-based positioning. Lock in annual subscription structures to reduce churn exposure against emerging AI-curation entrants. Prioritize cold-chain infrastructure investments in Austin and Seattle technology corridors where corporate wellness density justifies premium logistics spend.
For New Entrants and Emerging Players: Bi-weekly delivery frequency for hybrid workplace subscribers represents the most penetrable service gap, as incumbents optimize for monthly cadence and underserve irregular office attendance patterns. Target fitness enthusiasts in South Korea's Seoul Capital Area through macro-nutrient transparency platforms absent from incumbent offerings. Launch with pay-as-you-go trial formats to minimize subscription fatigue barriers before migrating retained users to prepaid structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with under-monetized snack subscription assets lacking dedicated platform investment. Long-term viability hinges on operator ability to sustain exclusive supplier relationships against retail private-label encroachment. Monitor FDA enforcement patterns on cottage food compliance as an inflection indicator for artisanal supplier onboarding costs and competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Annual Subscription Lock-In | Prepaid structures reduce churn exposure and improve cash flow predictability for cold-chain infrastructure expansion. |
| AI-Powered Preference Matching | Machine learning algorithms analyze consumption patterns to generate hyper-personalized assortments for coastal metropolitan subscribers. |
| Cold-Chain Infrastructure Investment | Temperature-controlled shipping protocols enable premium positioning for chocolate-inclusive assortments unavailable to ambient-only competitors. |
| Corporate Wellness Platform Integration | API interoperability with HR software stacks captures employer-funded procurement displacing individual purchasing authority. |
| Extended Producer Responsibility Compliance | Early adherence to California and New York packaging waste regulations creates defensible sustainability credentials. |
Research Methodology
Initial hypotheses were tested against primary input from subscription platform operators, artisanal supplier procurement leads, corporate HR benefits administrators, and last-mile logistics coordinators and refined through secondary validation against FDA labeling guidance documents, USDA organic certification databases, state cottage food law compilations, and trade data on cocoa and almond imports. Bottom-up subscriber cohort analysis and top-down market sizing triangulated volume estimates across the analysis window.
Variance-decomposition across product type, pricing model, delivery frequency, and customer segment dimensions structured the analytical framework. CAGRs were derived from segmented growth trajectory modeling incorporating corporate wellness adoption curves, AI-curation penetration rates, and cold-chain capacity expansion timelines. Input cost volatility for cocoa and nut commodities, alongside regulatory compliance burden trajectories, informed scenario-weighted projections.
Forecasts assume regulatory continuity in FDA nutrition labeling and USDA organic certification regimes; material policy shifts would require re-modeling. Supply disruption scenarios for West African cocoa regions and California agricultural belts represent specific revision triggers. Recalibration cycles align with material shifts in employer wellness stipend adoption and extended producer responsibility enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Cheese Snacks Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Snacks Market
Snacks
Global Rice Snacks Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Snack Products Market
Snacks
United Kingdom Energy Bar Market
Snacks
High Fiber Snack Foods Market
Snacks
Europe Snacks Food Market
Snacks
Dairy Protein Crisps Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
South East Asia Snack Bar Market
Snacks
Sweet Potato Fries Market
Snacks
Savoury Biscuits Market
Snacks
Candy and Snack Food Pouches Market