
 India Alcohol Market | 2026-2036
India Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
India Alcohol Market Outlook
Aftermarket service revenue in licensed bottling and contract distillation is narrowing as integrated players absorb more value in-house. United Spirits Ltd leverages captive manufacturing across multiple states to control quality and cost simultaneously. Radico Khaitan Ltd anchors its position through deep backward integration into grain neutral alcohol production. Sula Vineyards differentiates by dominating the domestic wine category with controlled estate sourcing and direct-to-consumer tourism channels.
India alcohol comprises fermented and distilled beverages containing ethanol, typically manufactured through saccharification, fermentation, and distillation processes with specified gravity and proof standards, serving recreational, social, and ceremonial consumption purposes. Spirits commands the largest revenue pool given higher per-unit taxation and premiumization potential, while RTDs represents the fastest-growing category as younger consumers seek convenience and flavor experimentation. The distribution channel dimension shows supermarkets and online platforms capturing incremental share from traditional liquor stores as state governments relax e-commerce prohibitions.
FSSAI mandates nutritional labeling and manufacturing hygiene standards for alcoholic beverages, while state excise authorities regulate pricing, licensing, and distribution with varying strictness across territories. BIS certification requirements for packaging materials and the PLI scheme for food processing infrastructure collectively shape capital deployment decisions and product standardization. Stakeholders must monitor evolving state excise policies and e-commerce regulations as these determine market access velocity and profitability structures.
Market Dynamics
State excise authorities across Maharashtra, Karnataka, and Telangana are tightening licensing frameworks while simultaneously permitting limited e-commerce trials, creating a bifurcated regulatory environment that rewards integrated manufacturers with multi-state manufacturing footprints.
Growth Catalysts
- PLI scheme for food processing:Capital subsidies for grain neutral alcohol distillation infrastructure are accelerating backward integration investments by licensed bottlers seeking cost control.
- Urban millennial consumption clustering:Metropolitan hospitality corridors in Mumbai, Bengaluru, and Hyderabad are concentrating premium spirits demand through licensed retail network density.
- Saccharification process automation:Continuous fermentation technologies are reducing batch variability and enabling consistent ethanol yields at commercial scale.
Market Restraints
- State-level excise policy fragmentation:Maharashtra's ad valorem taxation diverges from Karnataka's specific duty structures, complicating national pricing strategies.
- Grain neutral alcohol supply concentration:Punjab and Uttar Pradesh dominate feedstock processing, exposing coastal distillers to interstate logistics costs and procurement bottlenecks.
- FSSAI nutritional labeling mandates:Compliance timelines for ingredient disclosure are compressing product reformulation cycles for established portfolios.
Strategic Opportunities
- Telangana's underpenetrated wine segment:Sula Vineyards' direct-to-consumer tourism model remains replicable in Hyderabad's emerging hospitality clusters.
- RTD flavor experimentation:Younger consumers in Bengaluru are accepting premium-priced ready-to-drink formats previously absent from Indian retail.
- E-commerce regulatory relaxation:State excise authorities in select territories are piloting home delivery frameworks through licensed aggregators.
Industry Challenges
- Multi-state manufacturing compliance:BIS certification requirements for packaging materials vary by excise jurisdiction, forcing redundant testing protocols.
- Legacy distributor integration:State-mandated wholesaler tiers resist disintermediation attempts by direct-to-retail platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Alcohol Market |
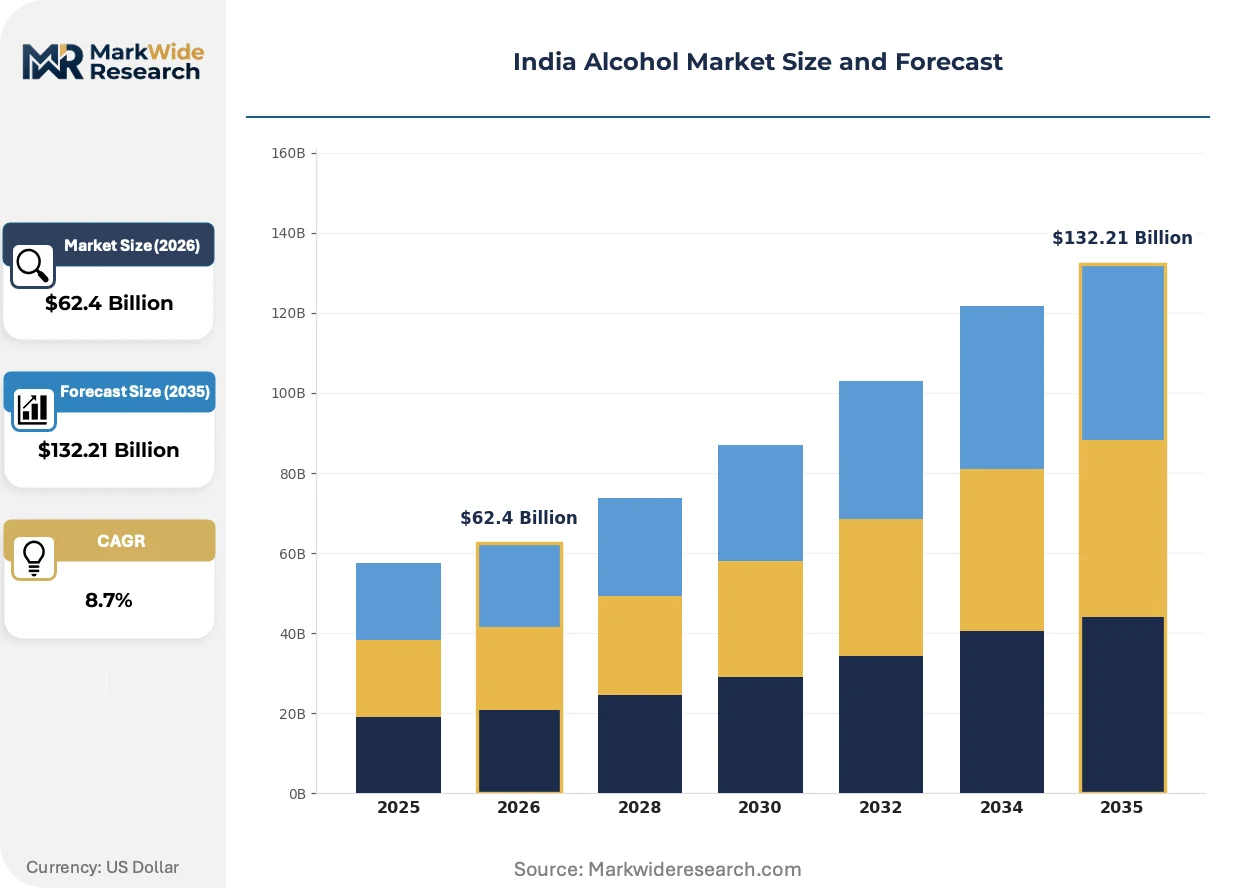
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, RTDs Consumer Age Group: 18-24 Years, 25-34 Years, 35-44 Years, 45+ Years Distribution Channel: Supermarkets, Bars, Online, Convenience Stores Price Segment: Premium, Mid-Range, Budget, Super Budget |
| Companies Covered | Allied Blenders and Distillers Ltd, Tilaknagar Industries Ltd, United Spirits Ltd, Jagatjit Industries, Sula Vineyards, United Breweries Ltd, Som Distilleries & Breweries, Piccadilly Sugar & Allied Industries, Radico Khaitan Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Alcohol Market Strategic Shifts
Product formulation and distribution mechanics are diverging sharply between heritage spirits portfolios and emerging convenience formats, with technology adoption rates splitting along generational consumption boundaries.
Continuous fermentation systems with automated gravity monitoring are collapsing traditional batch-cycle durations in grain neutral alcohol production. Medium-scale distillers in Maharashtra and Karnataka are deploying these systems to match integrated players' throughput consistency. The compression of fermentation-to-bottling timelines is collapsing working capital requirements for contract manufacturers.
FSSAI's phased implementation of nutritional labeling standards for alcoholic beverages is forcing reformulation investments across spirits and wine categories. Manufacturers must disclose caloric content and allergen information by specified deadlines or face distribution suspensions. Premium spirits producers with complex flavor portfolios face the steepest compliance costs as they re-engineer established recipes.
Licensed retail networks in metropolitan India are fragmenting as state governments authorize supermarket alcohol sales and experimental e-commerce channels. Traditional liquor store operators in Mumbai and Bengaluru are losing volume to modern trade formats with superior cold-chain infrastructure. Telangana's pilot home-delivery aggregators represent the most advanced regulatory experiment in channel restructuring.
India Alcohol Market Segmentation
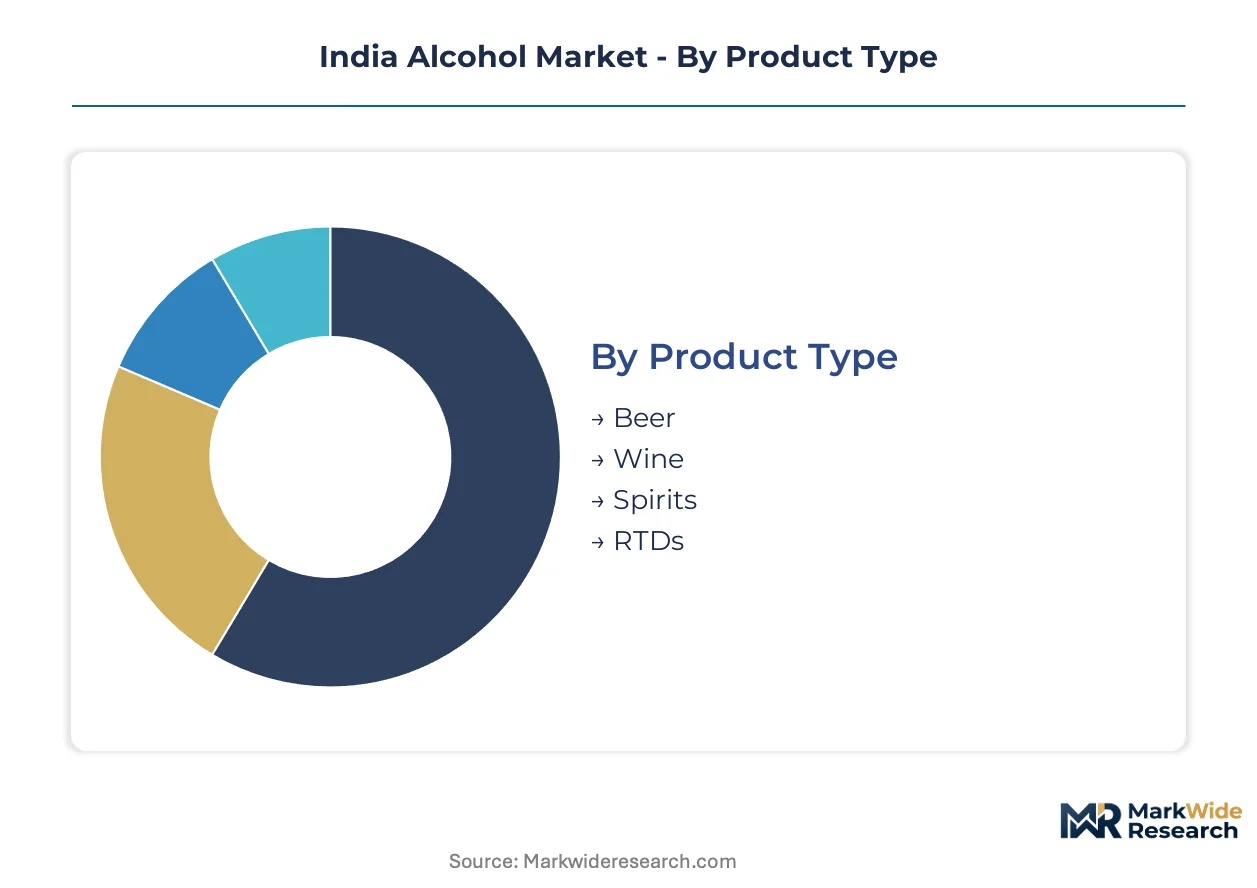
Segmentation in the India alcohol market reveals how excise policy fragmentation, generational consumption shifts, and channel modernization are reshaping competitive positioning. Understanding these divides enables manufacturers to allocate manufacturing capacity and licensing investments across Maharashtra, Karnataka, and Telangana's divergent regulatory environments.
Product Type:
Consumption occasions span ceremonial rituals, metropolitan hospitality, and convenience-driven social gatherings across India's tier-1 cities.
- Spirits:Distilled beverages including whisky, rum, vodka, and gin manufactured through controlled fermentation and distillation with specified gravity standards. Demand concentrates in Mumbai and Bengaluru's licensed retail corridors where urban millennials drive premiumization through higher per-unit taxation acceptance.
- RTDs:Ready-to-drink pre-mixed beverages combining spirits with flavor additives in single-serve packaging. Adoption accelerates fastest in Hyderabad's emerging hospitality clusters where younger consumers prioritize convenience and flavor experimentation over traditional serves.
- Beer:Fermented malt beverages with lower ethanol content serving mass-market recreational consumption. Maharashtra's dense licensed retail network sustains volume leadership despite Karnataka's specific duty structures compressing margins.
- Wine:Fermented grape beverages with controlled estate sourcing requirements. Telangana's underpenetrated category offers expansion potential through direct-to-consumer tourism channels modeled on established Maharashtra operations.
Established volume favors Spirits; emerging adoption favors RTDs.
Consumer Age Group:
Purchasing power and channel preferences stratify sharply across generational cohorts in metropolitan India.
- 25-34 Years:Urban millennials with disposable income concentrated in Mumbai, Bengaluru, and Hyderabad's hospitality corridors. This cohort drives premium spirits adoption through licensed retail network density and experimental consumption patterns.
- 18-24 Years:Entry-level consumers entering legal purchase age with price sensitivity and channel flexibility. Bengaluru's supermarket alcohol pilots capture this cohort's preference for modern trade formats over traditional liquor stores.
- 35-44 Years:Established professionals with brand loyalty and ceremonial consumption requirements. Maharashtra's ad valorem taxation structures align with this segment's willingness to absorb premium pricing for heritage portfolios.
- 45+ Years:Mature consumers with ritualized purchase patterns and distributor relationships. State-mandated wholesaler tiers in Karnataka retain this cohort through legacy channel familiarity.
Volume concentration sits with 25-34 Years; steepest expansion trajectory belongs to 18-24 Years.
Distribution Channel:
Regulatory relaxation is fragmenting traditional state-controlled distribution monopolies across select territories.
- Supermarkets:Modern trade formats with cold-chain infrastructure and standardized pricing. Mumbai and Bengaluru operators are capturing incremental share from traditional liquor stores as state governments authorize experimental retail reforms.
- Online:Licensed aggregator platforms piloting home delivery frameworks. Telangana's regulatory experiment represents the most advanced channel restructuring, though interstate logistics costs complicate national scaling.
- Bars:On-premise licensed establishments serving immediate consumption in metropolitan hospitality corridors. Karnataka's specific duty structures create margin pressure for operators compared to Maharashtra's ad valorem frameworks.
- Convenience Stores:Small-format retail with limited cold-chain capabilities serving impulse purchases. Traditional operators resist disintermediation as state-mandated wholesaler tiers preserve their intermediary role.
Legacy volume flows through Bars; regulatory momentum favors Online.
Price Segment:
Taxation structures and manufacturing scale determine competitive positioning across pricing tiers.
- Premium:Higher-proof spirits and estate-sourced wines with complex flavor portfolios. FSSAI nutritional labeling mandates compress reformulation cycles for established recipes in this tier, elevating compliance costs.
- Mid-Range:Standardized spirits and mass-market wines serving urban professional consumption. Maharashtra and Karnataka manufacturing footprints achieve cost control through PLI scheme subsidies for grain neutral alcohol infrastructure.
- Budget:Volume-oriented spirits and beer with simplified flavor profiles. Punjab and Uttar Pradesh feedstock concentration exposes coastal distillers to interstate procurement bottlenecks.
- Super Budget:Entry-level spirits with minimal branding and local distribution. State excise policy fragmentation complicates national pricing strategies for manufacturers attempting cross-territory presence.
Revenue concentration favors Premium; manufacturing scale advantages cluster in Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan consumers absorb premium taxation with minimal volume elasticity, while tier-2 and rural buyers shift decisively toward budget segments when state duties rise. This bifurcation concentrates manufacturing investment in corridors serving affluent urban clusters.
Maharashtra
Mumbai's licensed retail corridor drives premium spirits volume through dense hospitality clustering and ad valorem taxation that rewards higher-proof products. The state excise authority permits supermarket alcohol sales alongside traditional stores, fragmenting distribution channels. Manufacturing capacity concentrates in Nashik and Pune industrial belts where integrated distillers leverage PLI scheme subsidies for grain neutral alcohol infrastructure.
Karnataka
Bengaluru's urban millennials accelerate RTD adoption through experimental consumption patterns in emerging hospitality zones. Specific duty structures compress margins compared to Maharashtra, forcing operators toward volume efficiency. State excise frameworks maintain mandated wholesaler tiers that resist direct-to-retail disintermediation attempts by modern trade formats.
Telangana
Hyderabad's underpenetrated wine segment offers expansion potential through tourism-modeled direct-to-consumer channels. The state excise authority pilots India's most advanced home-delivery aggregator frameworks, restructuring last-mile logistics. Licensed retail network density remains below western corridor standards, creating whitespace for format experimentation.
Punjab
Feedstock processing dominance in grain neutral alcohol supply exposes coastal distillers to interstate procurement bottlenecks and logistics cost inflation. State excise policies favor local manufacturing through licensing preferences that protect incumbent operators. Amritsar and Ludhiana industrial clusters anchor ethanol output for national spirits supply chains.
Uttar Pradesh
Molasses-based distillation capacity serves bulk industrial alcohol demand alongside beverage-grade output for neighboring states. BIS certification requirements for packaging materials vary by destination jurisdiction, forcing redundant testing protocols for cross-border shipments. Kanpur and Lucknow manufacturing zones supply neutral alcohol to bottlers lacking backward integration.
India Alcohol Market Competitive Environment
Capability concentration sits with integrated distillers commanding captive grain neutral alcohol supply; scale advantage sits with multi-state bottlers leveraging distributed manufacturing footprints. The market structures around three tiers: heritage spirits portfolios with deep distributor relationships, contract manufacturers serving private-label demand, and estate-based wine specialists with tourism-anchored distribution. Consolidation pressure intensifies as state licensing frameworks reward multi-territory presence. Dominant competitive moves include backward integration into feedstock processing and absorption of contract distillation capacity previously outsourced.
Within the integrated manufacturing tier, United Spirits Ltd and Radico Khaitan Ltd exemplify players combining multi-state production footprints with controlled alcohol supply chains. Sula Vineyards occupies a distinct position as a wine specialist replicating direct-to-consumer tourism models across underpenetrated territories. These three entities represent contrasting archetypes: the diversified spirits conglomerate, the backward-integrated distiller, and the category-focused estate operator.
| Leading Market Players |
|---|
| Allied Blenders and Distillers Ltd |
| Tilaknagar Industries Ltd |
| United Spirits Ltd |
| Jagatjit Industries |
| Sula Vineyards |
| United Breweries Ltd |
| Som Distilleries & Breweries |
| Piccadilly Sugar & Allied Industries |
| Radico Khaitan Ltd |
| Others |
Value Chain & Pricing Dynamics
Punjab and Uttar Pradesh grain neutral alcohol processing concentration feeds margin pools downstream toward integrated distillers with captive fermentation infrastructure. Coastal bottlers absorbing interstate logistics premiums face persistent cost disadvantages against Nashik and Pune manufacturing belts anchored by PLI scheme subsidies.
Pricing Analysis
Aftermarket service revenue in contract distillation and licensed bottling relationships is compressing as integrated manufacturers internalize previously outsourced capacity. Three-tier pricing structure across premium, standard, and economy levels stratifies by excise jurisdiction complexity and backward integration depth. Pricing pressure stems from FSSAI nutritional labeling compliance costs forcing reformulation investments in premium portfolios with complex flavor matrices. Budget segment buyers exhibit highest price elasticity, while 25-34 year urban millennials in metropolitan corridors absorb premium taxation with minimal volume sensitivity.
Supply Chain Analysis
Upstream feedstock sourcing draws from Punjab molasses distillation clusters and Uttar Pradesh grain alcohol processing zones for national spirits supply. Maharashtra and Karnataka manufacturing belts rest on PLI-subsidized fermentation infrastructure with automated gravity monitoring systems. Single-source vulnerability concentrates in interstate grain neutral alcohol procurement for coastal distillers lacking captive supply. Distribution runs through state-mandated wholesaler tiers resisting disintermediation, though Telangana's pilot aggregator frameworks signal channel restructuring momentum.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract distillation and licensed bottling service layers are expanding faster than standalone manufacturing margins, rewarding integrated players absorbing previously outsourced value chains.
For Market Incumbents: Insulate margin structures through backward integration into grain neutral alcohol production, mirroring Radico Khaitan's captive supply model. Absorb regional contract manufacturers in Karnataka and Telangana before licensing frameworks consolidate multi-state footprints as mandatory scale thresholds. State excise policy fragmentation threatens national pricing coherence; anchor manufacturing in Nashik-Pune and Bengaluru-Hyderabad corridors with divergent tax structures. For New Entrants and Emerging Players: Telangana's underpenetrated wine segment offers whitespace replication of Sula Vineyards' direct-to-consumer tourism architecture. Hyderabad's emerging hospitality clusters lack estate-sourced supply infrastructure present in Maharashtra. RTD flavor experimentation in Bengaluru's 18-24 cohort accepts premium convenience formats absent from traditional retail. Deploy supermarket alcohol pilot partnerships as regulatory relaxation accelerates modern trade authorization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated fermentation infrastructure as PLI scheme subsidies compress equipment deployment thresholds. Five-to-ten year viability favors integrated distillers with multi-state manufacturing licenses and captive alcohol supply chains. Acquisition targets should demonstrate BIS certification breadth across packaging materials and excise jurisdiction testing protocols. Monitor FSSAI labeling compliance timelines as portfolio reformulation cost inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Neutral Alcohol | Captive fermentation infrastructure eliminates interstate procurement premiums for coastal distillers. |
| Multi-State Manufacturing Footprint Expansion | Licensing concentration in Maharashtra, Karnataka, and Telangana hedges excise policy fragmentation risk. |
| Direct-to-Consumer Tourism Channel Development | Estate-sourced wine distribution bypasses state-mandated wholesaler tiers in underpenetrated territories. |
| Automated Saccharification System Deployment | Continuous fermentation technologies collapse batch-cycle durations and working capital requirements. |
| E-Commerce Aggregator Partnership Structuring | Telangana's pilot home-delivery frameworks anticipate regulatory relaxation across additional states. |
Study Parameters
Desk research of state excise policy circulars, FSSAI regulatory filings, and PLI scheme implementation guidelines preceded structured interviews with distillery operations heads, state excise commissioners, licensed retail network operators, and grain neutral alcohol procurement managers. Secondary validation drew from BIS certification databases, customs trade records for packaging materials, and hospitality sector investment disclosures. Bottom-up capacity assessments across Nashik, Pune, Bengaluru, and Hyderabad manufacturing belts were triangulated against top-down excise revenue projections.
Assumptions held fixed include current PLI scheme subsidy rates and FSSAI labeling implementation timelines, while state e-commerce authorization pace and grain alcohol procurement cost trajectories were varied across scenarios. Segmentation dimensions encompassed product type, consumer age cohort, distribution channel modernization stage, and price tier taxation exposure. CAGRs were derived from volume elasticity modeling against ad valorem and specific duty structures, with grain neutral alcohol supply concentration and automated fermentation adoption rates as primary forecast inputs.
Practitioners should monitor state excise policy amendments and FSSAI compliance deadline extensions for early signals of forecast revision. Cross-checking against state excise revenue collection data and licensed retail permit issuance trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Fruit Brandy Market