
 India Lighting Market | 2026-2036
India Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
India Lighting Market Outlook
Traditional electrical wholesale channels in tier-two and tier-three cities is narrowing as direct-to-contractor digital platforms and integrated project solution providers capture specification flow. Havells India Ltd leverages its captive distribution network across 250,000 retail touchpoints to sustain pricing power in residential switchgear and luminaire bundles. Crompton Greaves Consumer Electricals Ltd anchors its position through backward integration into LED chip-on-board modules, while Signify Innovations India Ltd competes on connected lighting platforms for commercial building automation.
India lighting encompasses electrically powered luminaires, lamps, and control systems designed to deliver specified illuminance levels measured in lux and lumens across residential, commercial, and industrial environments. LED products now dominate volume shipments due to lumen-per-watt efficiencies exceeding 130 lm/W and declining phosphor-on-chip manufacturing costs. Solar lighting applications represent the fastest-growing technology segment, driven by off-grid rural electrification and Ministry of New and Renewable Energy capital subsidies. Wireless control systems command premium positioning in commercial retrofit projects, whereas conventional fluorescent installations face accelerated replacement cycles under BEE mandatory standards.
Bureau of Energy Efficiency star ratings and Bureau of Indian Standards IS 16102 compliance define minimum efficacy thresholds and safety testing protocols for domestic market access. The Ministry of Housing and Urban Affairs Smart Cities Mission mandates intelligent street lighting with central management systems across 100 designated urban areas. State electricity distribution companies enforce demand-side management obligations that channel institutional procurement toward certified efficient products. Stakeholders must monitor evolving BEE notification schedules and state-level preferential procurement policies to anticipate specification shifts before tender cycles close.
Market Dynamics
The Bureau of Energy Efficiency's escalating star rating thresholds and state-level LED distribution mandates are compressing replacement cycles while rewiring procurement specifications across residential, municipal, and commercial channels.
Growth Catalysts
- Smart Cities Mission:The Ministry of Housing and Urban Affairs mandates intelligent street lighting with central management systems across 100 designated urban areas, institutionalizing premium product specifications.
- Capital subsidy frameworks:The Ministry of New and Renewable Energy funds off-grid solar lighting deployments in rural electrification zones, expanding addressable market for DC-powered luminaires.
- Phosphor-on-chip cost curves:Declining manufacturing costs for LED chip-on-board modules are enabling lumen-per-watt efficiencies exceeding 130 lm/W at price points accessible to mass-market segments.
Market Restraints
- Import dependency for LED chips:Domestic manufacturing capacity for epitaxial wafers remains concentrated in East Asian supply bases, exposing assemblers to freight cost volatility and currency fluctuation.
- BIS certification timelines:Bureau of Indian Standards IS 16102 testing protocols create 8-12 week approval windows that delay product launches and tie up working capital in inventory.
- Fluorescent stockpiles:Existing installed bases of T8 and CFL installations in legacy commercial buildings extend replacement cycles despite efficacy disadvantages.
Strategic Opportunities
- Uttar Pradesh and Bihar rural electrification gaps:Grid-unreliable districts present concentrated demand for solar-home-system lighting kits with pay-as-you-go financing integration.
- Wireless mesh convergence:Bluetooth Low Energy and Zigbee protocol integration with luminaire hardware creates bundled specification opportunities in commercial building automation retrofits.
- Direct-to-contractor platforms:Digital procurement channels in tier-two and tier-three cities are disintermediating traditional electrical wholesale networks and capturing specification flow.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for connected lighting controls requires skill sets concentrated in Bengaluru and Hyderabad, constraining product development velocity for tier-two manufacturers.
- Legacy electrical infrastructure incompatibility:Existing switchgear and wiring in pre-2010 commercial buildings requires costly rewiring to support smart lighting retrofits, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lighting Market |
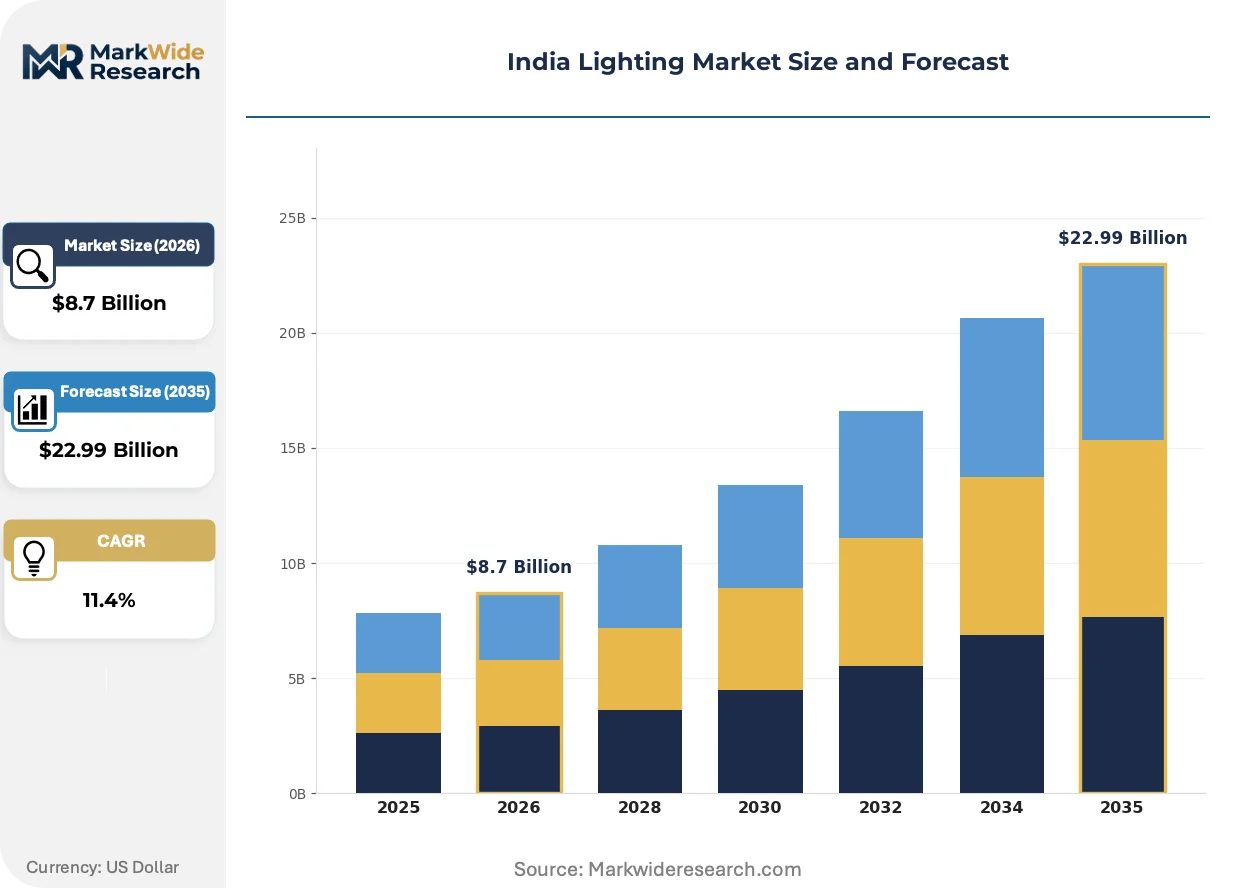
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Incandescent, Halogen Application: Residential, Commercial, Outdoor, Industrial Technology: Smart Lighting, Solar Lighting, Conventional, Wireless End User: Retailers, Manufacturers, Government, Institutions |
| Companies Covered | Havells India Ltd, Crompton Greaves Consumer Electricals Ltd, Signify Innovations India Ltd, Surya Roshni Ltd, Wipro Lighting, Bajaj Electricals Ltd, Syska LED Lights Pvt Ltd, Philips Electronics India Ltd, Polycab India Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lighting Market Strategic Shifts
Human-centric lighting specifications and circadian rhythm optimization are migrating from healthcare and education verticals into premium residential and corporate fit-outs, redefining value propositions beyond energy efficiency.
Human-centric lighting systems that tune correlated color temperature across diurnal cycles are rendering obsolete static white-output specifications in healthcare, education, and premium workplace fit-outs. Hospital chains in Maharashtra and Karnataka are piloting tunable-white installations to support patient recovery protocols. The specification shift is compressing demand for fixed-CCT products and rewarding manufacturers with in-house optical engineering capabilities.
Bureau of Energy Efficiency notification schedules for star rating upgrades are accelerating product obsolescence cycles and forcing R&D pipeline compression. The 2024-2025 efficacy threshold revisions for ceiling luminaires and downlights are disqualifying incumbent product lines from government tender eligibility. Manufacturers are responding with accelerated phosphor formulation investments and thermal management redesigns to maintain certification compliance.
Contractor purchasing behavior is fragmenting across project-scale boundaries, with large infrastructure developers consolidating procurement through integrated solution providers while small residential electricians migrate to mobile-first digital platforms. The channel bifurcation is compressing margin pools for traditional electrical distributors in Gujarat and Tamil Nadu. Specification influence is concentrating with engineering-procurement-construction firms on commercial projects and with platform algorithms on residential repair-and-replace jobs.
India Lighting Market Segmentation
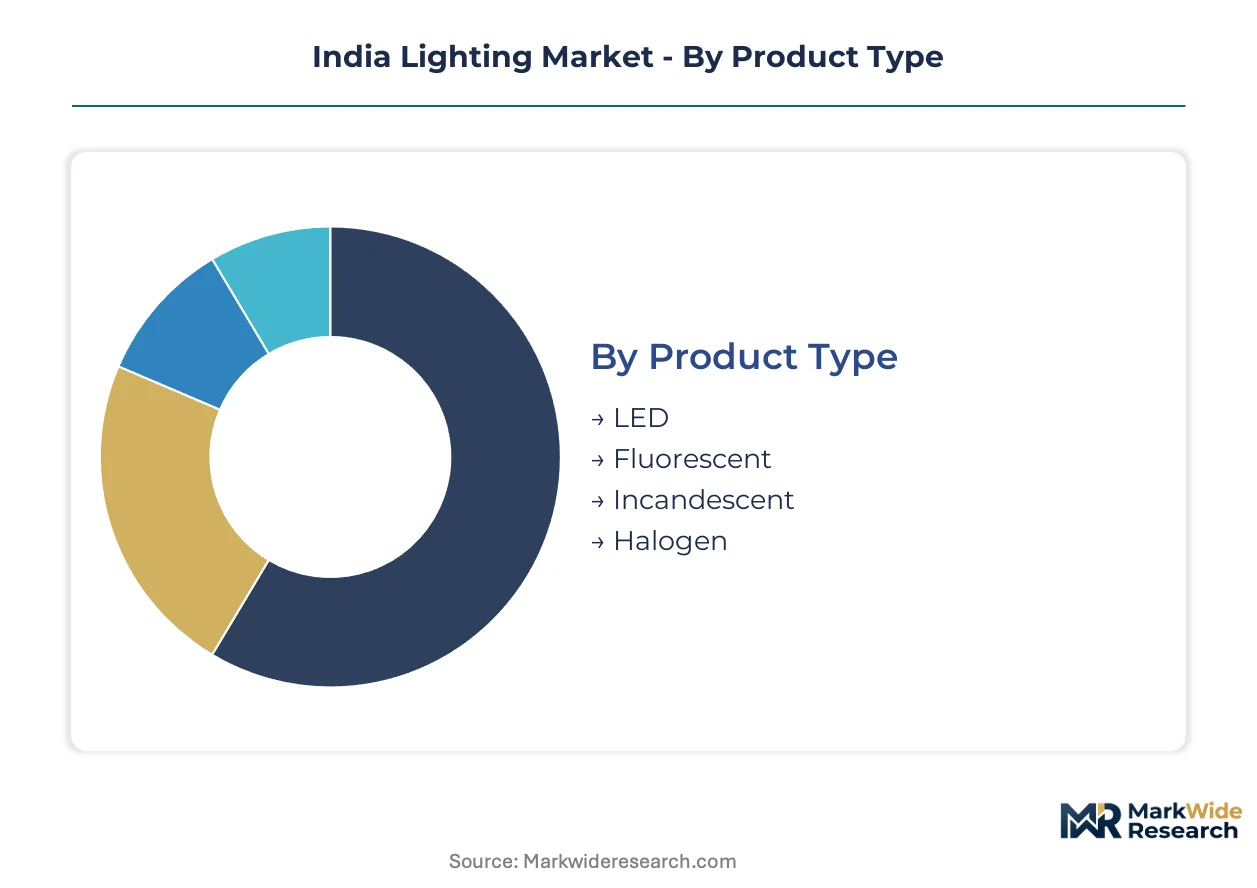
Segmentation reveals how procurement specifications, installation complexity, and regulatory compliance requirements fragment India's lighting landscape. Each dimension carries distinct margin profiles, channel access patterns, and after-sales service intensities that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with LED retrofits demanding minimal maintenance while fluorescent replacements require ongoing ballast servicing.
- LED:Solid-state luminaires with phosphor-on-chip architectures deliver lumen-per-watt efficiencies exceeding 130 lm/W. Maharashtra and Gujarat municipal tenders specify LED street lighting with 50,000-hour rated lifespans, compressing replacement revenue cycles.
- Fluorescent:Linear T8 and compact CFL installations retain residual share in legacy commercial buildings across Tamil Nadu and Karnataka. BEE mandatory standards are accelerating phase-out timelines despite installed base inertia.
- Incandescent:Filament-based sources persist in decorative and heritage lighting applications with minimal regulatory pressure.
- Halogen:Tungsten-halogen reflector lamps serve specialty retail and automotive forward lighting niches requiring precise beam control.
By volume, LED leads. By growth pace, solar-integrated variants are expanding most quickly.
Application:
Cost tier stratification separates premium specification-driven commercial projects from price-sensitive residential replacement cycles.
- Residential:Switchgear-luminaire bundles dominate replacement demand through electrical retail channels in tier-two and tier-three cities. BEE star labeling mandates are reshaping ceiling fixture specifications.
- Commercial:Building automation retrofits in Bengaluru and Hyderabad IT parks specify wireless mesh-enabled tunable-white systems. Human-centric lighting protocols for circadian rhythm optimization command 40-60% price premiums.
- Outdoor:Solar street lighting deployments in Uttar Pradesh and Bihar rural electrification zones absorb Ministry of New and Renewable Energy capital subsidies.
- Industrial:High-bay LED fixtures with IP65 ingress protection serve manufacturing floors in Gujarat chemical corridors and Tamil Nadu automotive clusters.
Commercial applications generate the highest margins. Outdoor installations are climbing the fastest on subsidy tailwinds.
Technology:
Customer type fragmentation splits procurement between government tender committees, EPC firms, and mobile-first contractor platforms.
- Smart Lighting:Bluetooth Low Energy and Zigbee protocol integration enables central management systems mandated by the Smart Cities Mission across 100 urban areas. Firmware development scarcity in tier-two manufacturers constrains supply.
- Solar Lighting:DC-powered luminaires with integrated photovoltaic modules serve off-grid districts. Pay-as-you-go financing integration is unlocking rural household penetration.
- Conventional:Mains-powered fixtures without connectivity features retain share in cost-constrained residential and small commercial segments.
- Wireless:Mesh network architectures for commercial retrofit projects require embedded systems engineering capabilities concentrated in Bengaluru.
Conventional technology retains volume leadership. Smart lighting is gaining share fastest on building automation convergence.
End User:
Supply concentration patterns channel LED chip-on-board modules through vertically integrated manufacturers while fragmenting distribution across divergent procurement workflows.
- Retailers:Electrical wholesale networks in Gujarat and Tamil Nadu face margin compression from direct-to-contractor digital platforms capturing specification flow.
- Manufacturers:OEM assemblers source epitaxial wafers from East Asian supply bases, exposing production to freight cost volatility and currency fluctuation.
- Government:State electricity distribution companies enforce demand-side management obligations that channel institutional procurement toward BEE-certified efficient products.
- Institutions:Hospital chains in Maharashtra and Karnataka pilot tunable-white human-centric lighting for patient recovery protocols.
Government procurement dominates tender volume. Institutional specification influence is expanding most quickly on healthcare verticalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level LED distribution schemes and BEE star labeling mandates are rewiring procurement specifications across municipal, commercial, and residential channels. The Ministry of Housing and Urban Affairs Smart Cities Mission directs capital flows toward intelligent street lighting deployments. Bureau of Indian Standards certification timelines create 8-12 week approval windows that shape product launch cadences.
Maharashtra
Mumbai and Pune municipal corporations drive demand for central management system-enabled street lighting under Smart Cities Mission mandates. The state electricity distribution company enforces demand-side management obligations channeling procurement toward BEE-certified products. Hospital chains in Mumbai pilot tunable-white human-centric lighting for patient recovery protocols.
Gujarat
Ahmedabad and Surat smart city infrastructure projects accelerate LED and solar street lighting procurement with 50,000-hour rated lifespan specifications. State-level preferential procurement policies favor domestically assembled luminaires. Chemical corridor manufacturing clusters in Vadodara and Bharuch absorb high-bay LED fixtures with IP65 ingress protection.
Karnataka
Bengaluru IT parks specify wireless mesh-enabled building automation retrofits with Bluetooth Low Energy protocol integration. The state's electronics manufacturing clusters concentrate firmware development capabilities for connected lighting controls. Hospital chains in Bengaluru expand tunable-white installations beyond pilot phases.
Tamil Nadu
Chennai and Coimbatore automotive manufacturing clusters drive industrial high-bay lighting replacement cycles. Legacy T8 and CFL installations in pre-2010 commercial buildings extend replacement timelines despite BEE mandatory standards. Traditional electrical wholesale networks face margin compression from direct-to-contractor digital platforms.
Uttar Pradesh
Grid-unreliable districts in rural electrification zones absorb Ministry of New and Renewable Energy capital subsidies for solar-home-system lighting kits. Pay-as-you-go financing integration unlocks household penetration for DC-powered luminaires with integrated photovoltaic modules. State tender committees channel institutional procurement toward certified efficient products.
India Lighting Market Competitive Environment
On the supply side, the industry is fragmented across three distinct tiers: vertically integrated electrical conglomerates with captive distribution networks, mid-scale assemblers sourcing epitaxial wafers from East Asian supply bases, and specialist LED chip-on-board module producers. Strategic archetypes include distribution-heavy incumbents leveraging retail touchpoint density, backward-integrated manufacturers controlling phosphor formulation and thermal management, and connected lighting platform providers competing on firmware capabilities. Dominant competitive moves span geographic expansion into tier-two and tier-three cities and portfolio diversification toward solar-integrated and wireless-enabled product lines.
Among India-domiciled electrical conglomerates, Havells India Ltd and Crompton Greaves Consumer Electricals Ltd exemplify the distribution-anchored archetype, with the former leveraging retail network scale and the latter representing backward integration into LED module production. Signify Innovations India Ltd occupies a position within the connected lighting tier, anchoring premium platform positioning for commercial building automation. These three entities collectively illustrate the competitive tension between physical channel control, upstream manufacturing capture, and digital capability investment that defines current market structure.
| Leading Market Players |
|---|
| Havells India Ltd |
| Crompton Greaves Consumer Electricals Ltd |
| Signify Innovations India Ltd |
| Surya Roshni Ltd |
| Wipro Lighting |
| Bajaj Electricals Ltd |
| Syska LED Lights Pvt Ltd |
| Philips Electronics India Ltd |
| Polycab India Ltd |
| Others |
Value Chain & Pricing Dynamics
JNPT-Singapore container freight corridors transmit phosphor and chip-on-board module cost volatility directly into Indian luminaire pricing, concentrating margin pressure on assemblers lacking captive LED die supply while rewarding manufacturers with in-house thermal management and optical engineering capabilities.
Pricing Analysis
Certification level under BEE star ratings and IS 16102 compliance creates the primary spread between premium and mass-market positioning. Three-tier pricing structure separates connected lighting platforms with wireless mesh capability from standard LED retrofits and economy fluorescent replacements. Pricing pressure stems from direct-to-contractor digital platforms disintermediating traditional electrical wholesale networks in Gujarat and Tamil Nadu. Residential replacement cycles through tier-two retail channels exhibit highest price sensitivity, while commercial building automation retrofits in Bengaluru IT parks tolerate premium positioning for human-centric lighting specifications.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning for epitaxial wafer sourcing, with domestic assemblers drawing from East Asian supply bases in Taiwan, South Korea, and China for LED chip-on-board modules. Critical dependencies include phosphor formulations, aluminum heat sink extrusions, and driver electronics from concentrated manufacturing zones. Single-source vulnerability in epitaxial wafer supply exposes production schedules to freight cost volatility and currency fluctuation. Distribution runs through three distinct channels: captive retail networks of electrical conglomerates, direct-to-contractor digital platforms, and integrated project solution providers capturing municipal tender specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where BEE star labeling mandates and Smart Cities Mission procurement specifications create switching costs that institutionalize incumbent relationships with state electricity distribution companies and municipal tender committees.
For Market Incumbents: Build certification moats through accelerated phosphor formulation R&D and thermal management redesigns to maintain BEE compliance ahead of notification schedule revisions. Deepen captive distribution network density in tier-two and tier-three cities to defend against digital platform disintermediation. Threat vector: mid-scale assemblers sourcing from East Asian supply bases undercutting on price in residential replacement segments. For New Entrants and Emerging Players: Build out pay-as-you-go financing integration for solar-home-system lighting kits targeting grid-unreliable districts in Uttar Pradesh and Bihar rural electrification zones. White-space concentration: DC-powered luminaires with integrated photovoltaic modules absorbing Ministry of New and Renewable Energy capital subsidies. Go-to-market angle: direct partnerships with state tender committees bypassing traditional electrical wholesale networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated manufacturers controlling LED chip-on-board module production and optical engineering capabilities. Long-term viability over the projection horizon rests on regulatory compliance velocity rather than pure scale. Acquisition target archetype: specialist firmware developers for connected lighting controls concentrated in Bengaluru and Hyderabad electronics manufacturing clusters. Signal to watch: BEE notification schedule acceleration compressing product obsolescence cycles and forcing R&D pipeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Modules | Captures phosphor-on-chip cost curves and insulates margin from East Asian supply volatility. |
| Wireless Mesh Platform Development | Enables Bluetooth Low Energy and Zigbee specification capture in Bengaluru IT park retrofits. |
| Solar-Integrated Product Line Expansion | Aligns portfolio with Ministry of New and Renewable Energy capital subsidy frameworks. |
| Direct-to-Contractor Digital Channel | Disintermediates traditional electrical wholesale networks in tier-two and tier-three cities. |
| Human-Centric Lighting R&D Investment | Commands 40-60% price premiums through tunable-white circadian optimization protocols. |
Study Parameters
The analysis maps LED luminaire, solar-integrated, and connected lighting sub-sectors, each validated through municipal procurement officers, EPC contractor project managers, electrical wholesale distributors, and BEE certification consultants. Primary interviews with state electricity distribution company demand-side management leads and hospital facilities engineers in Maharashtra and Karnataka were cross-referenced against secondary sources including BEE notification schedules, Smart Cities Mission tender documents, Bureau of Indian Standards IS 16102 testing protocols, and Ministry of New and Renewable Energy subsidy disbursement records. Bottom-up shipment estimates from component suppliers were triangulated against top-down addressable market calculations from rural electrification zone household penetration models.
Assumption sets held BEE star rating escalation timelines and Smart Cities Mission deployment schedules fixed while varying rural electrification subsidy absorption rates and phosphor-on-chip cost curve trajectories across the analysis window. Segmentation modeling incorporated product type, application vertical, technology tier, and end-user procurement workflow dimensions. CAGRs were derived from installed base replacement cycle compression rates and municipal tender award velocity. Industry-specific forecast inputs included LED lumen-per-watt efficiency improvement curves and solar photovoltaic module cost decline assumptions.
Stress conditions across BIS certification timeline delays, East Asian supply base freight cost volatility, and state-level preferential procurement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance velocity and subsidy continuation frameworks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Lamps Market
Lighting
Lighting Product Market
Lighting
Solid-State Lighting Source Market
Lighting
Street Lighting Market
Lighting
North America Smart Lighting Market
Lighting
North America Street Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Studio Lighting Equipment Market
Lighting
Germany Indoor LED Lighting Market
Lighting
Connected Lighting Platform Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Ring Lights Market
Lighting
Xenon Lights Market
Lighting
Global Work Lights Market