
 Silicon Carbide Mosfets Market | 2026-2036
Silicon Carbide Mosfets Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Carbide Mosfets Market Analytics
Software-defined gate-drive tuning is rebalancing what customers pay for across the value chain. STMicroelectronics leverages captive SiC substrate capacity to anchor European automotive supply relationships. Wolfspeed sustains its position through vertical control from crystal growth through device fabrication. Infineon Technologies competes by extending its portfolio across voltage classes and packaging formats.
Silicon carbide MOSFETs are wide-bandgap semiconductor switches fabricated on 4H-SiC polytype substrates, offering breakdown fields above 2 MV/cm and thermal conductivity near 490 W/mK for power conversion above 600 volts. Their primary purpose is to reduce switching losses and enable higher operating temperatures in power electronics versus silicon IGBTs. High voltage MOSFETs dominate where traction inverters and grid-tied converters require blocking capabilities above 1,200 volts, while power MOSFETs occupy the fastest-expanding niche in onboard chargers and DC-DC stages. Electric vehicles represent the most consequential application segment, with industrial automation trailing as a mature but stable demand pool for motor drives and welding equipment.
EPA tailpipe regulations and NHTSA corporate average fuel economy standards in the United States mandate efficiency gains that SiC devices directly address, while EU Green Deal industrial policy and REACH substance controls shape European sourcing and manufacturing requirements. China's GB standards and dual carbon goals from MEE accelerate domestic substitution programs for automotive power electronics. Stakeholders must monitor substrate supply allocation between internal device production and external merchant sales as crystal growth capacity becomes the binding constraint on market expansion.
Market Dynamics
Substrate supply allocation between internal device fabrication and external merchant sales is compressing expansion timelines across the value chain. Crystal growth capacity has emerged as the binding constraint, forcing device manufacturers to secure long-term supply agreements or invest in captive boule production.
Growth Catalysts
- EPA vehicle emissions standards:Tailpipe regulations mandate efficiency gains that silicon carbide power electronics directly enable in traction inverters and onboard chargers.
- China's EV manufacturing clusters:Domestic OEMs accelerate SiC adoption in powertrain systems to meet MEE dual carbon goals and GB standards for automotive efficiency.
- Wide-bandgap thermal performance:Breakdown fields above 2 MV/cm allow higher operating temperatures, reducing cooling system mass and complexity in electric vehicle designs.
Market Restraints
- 6-inch substrate cost volatility:Silicon carbide crystal growth requires specialized furnaces and extended growth cycles, keeping material costs elevated versus silicon alternatives.
- Supply concentration in China and Germany:Crystal growth and epitaxy capacity clusters in specific manufacturing corridors, creating geographic vulnerability to trade policy shifts.
- Defect density limitations:Micropipe and basal plane dislocation densities in 4H-SiC substrates constrain yield rates at voltage ratings above 1,700 volts.
Strategic Opportunities
- Grid-tied energy storage inverters:Utility-scale battery installations require blocking capabilities above 1,200 volts where high-voltage MOSFETs reduce switching losses.
- EU Green Deal industrial policy:REACH substance controls and carbon border adjustments incentivize European-sourced SiC devices for automotive qualification.
- GaN-SiC hybrid module convergence:Combining gallium nitride HEMTs with silicon carbide diodes enables optimized performance across voltage and frequency ranges.
Industry Challenges
- Power electronics packaging expertise shortage:Thermal management and parasitic inductance optimization for wide-bandgap devices requires specialized engineering talent concentrated at a handful of institutions.
- AEC-Q101 qualification timelines:Automotive reliability testing for discrete power semiconductors extends 18-24 months, delaying revenue recognition for new device introductions.
- Legacy IGBT system integration friction:Drop-in replacement of silicon devices requires gate-drive circuit redesign and magnetic component resizing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Carbide Mosfets Market |
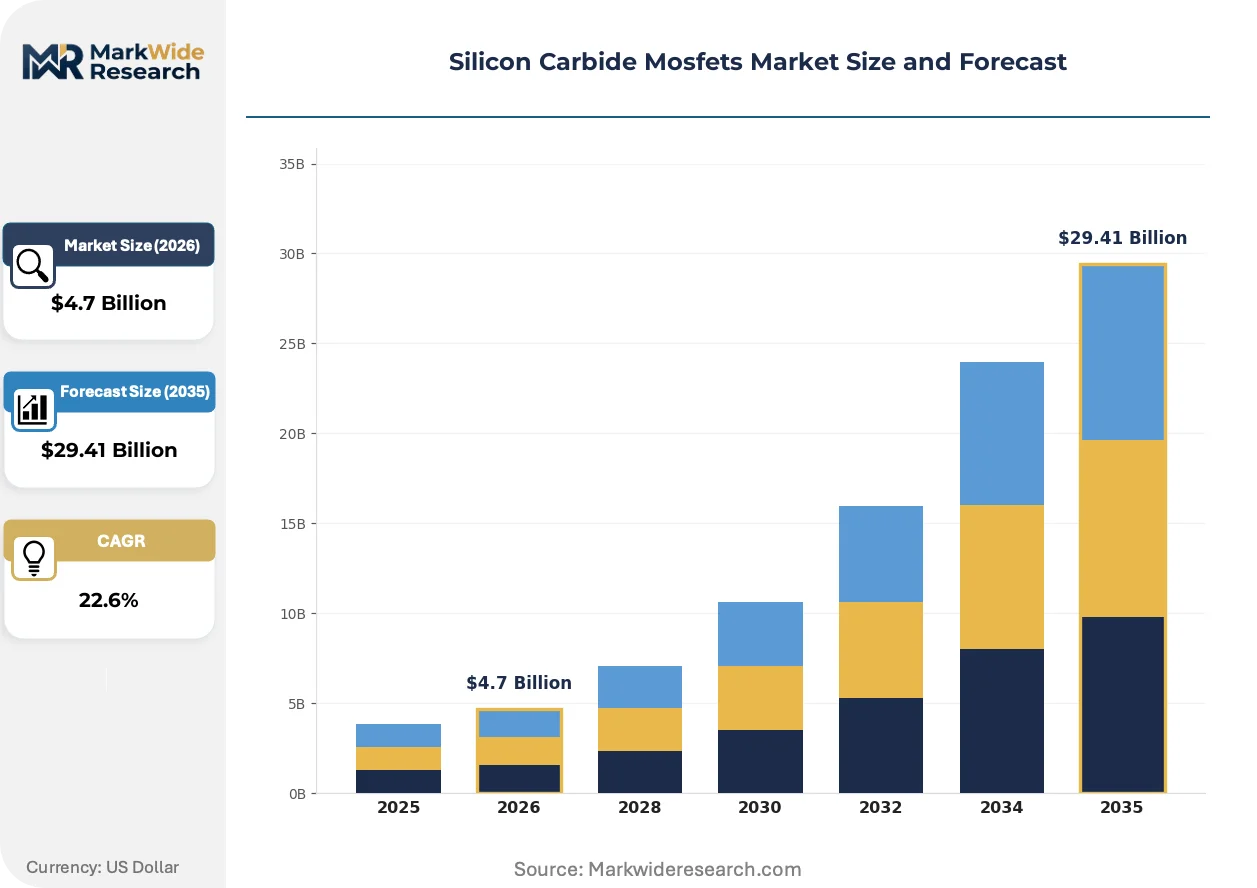
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage MOSFETs, High Voltage MOSFETs, Medium Voltage MOSFETs, Power MOSFETs Application: Energy Storage Systems, Electric Vehicles, Renewable Energy, Industrial Automation End User: Automotive OEMs, Power Electronics Manufacturers, Industrial Equipment Manufacturers, Renewable Energy Providers Technology: Switching Technology, Power Conversion Technology, RF Technology, Analog Technology |
| Companies Covered | STMicroelectronics, Wolfspeed, Infineon Technologies, onsemi, ROHM, Mitsubishi Electric, Toshiba, Fuji Electric, Littelfuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Carbide Mosfets Market Evolving Landscape
Software-defined gate-drive architectures are redistributing value capture across the semiconductor supply chain. These programmable control systems enable real-time switching optimization that was previously locked in hardware designs.
Intelligent gate-driver ICs with adaptive dead-time control is decentralizing switching performance optimization from device manufacturers to system integrators. Tier-1 automotive suppliers now tune switching profiles in firmware rather than selecting fixed-parameter devices. This shift compresses differentiation timelines for bare die suppliers while expanding aftermarket service opportunities.
EU F-Gas Regulation phase-down schedules are accelerating fluorinated greenhouse gas restrictions in semiconductor manufacturing process cooling. Equipment suppliers must transition to alternative heat transfer fluids or closed-loop refrigerant systems. European device fabrication facilities face retrofit investment requirements that favor greenfield capacity additions in jurisdictions with less stringent chemical controls.
Buyer concentration among automotive OEMs has compressed component qualification cycles and intensified price-performance benchmarking. Tier-1 power module suppliers now compete on total system cost rather than discrete device specifications. This pattern is most visible in Germany's industrial automation corridors, where motion control and welding equipment manufacturers demand application-specific co-development agreements.
Silicon Carbide Mosfets Market Segmentation
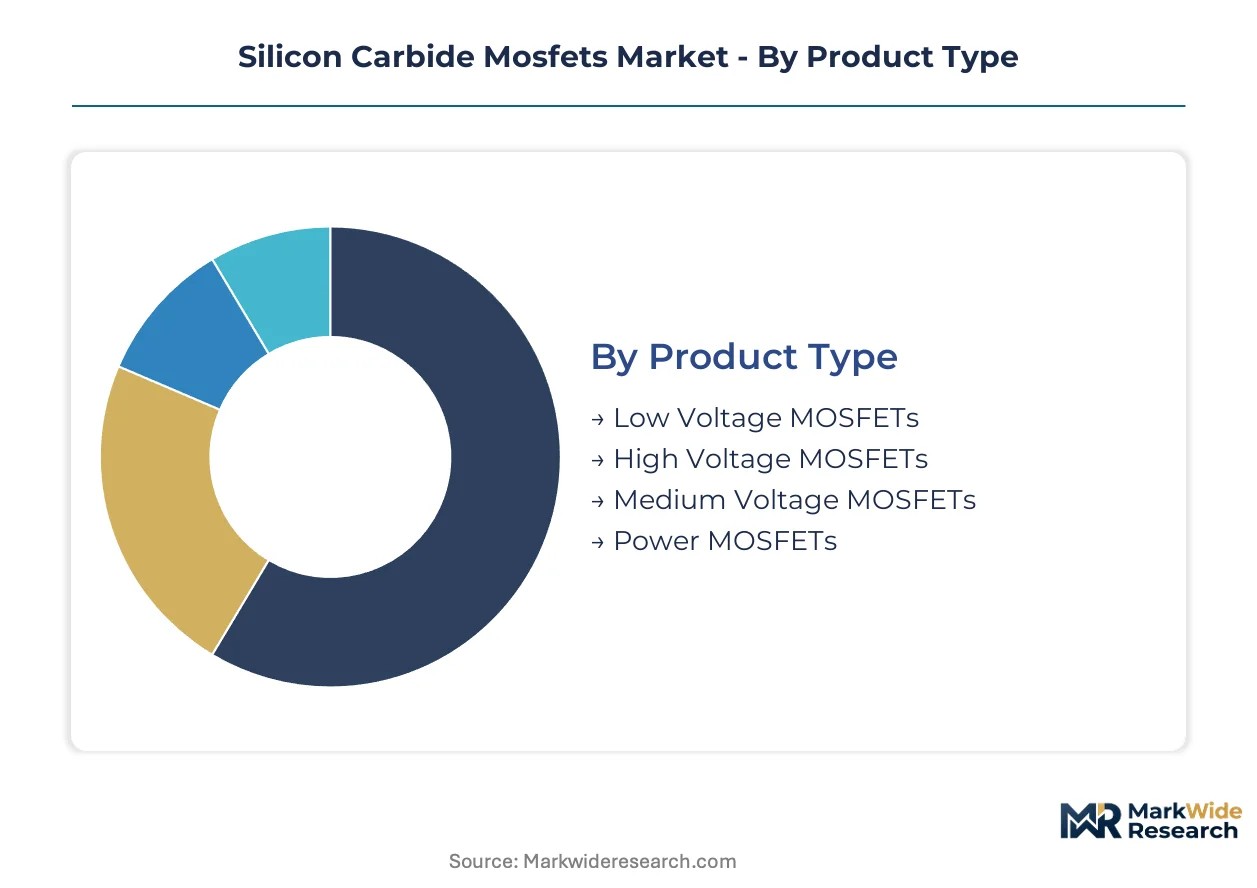
Segmentation in silicon carbide MOSFETs reveals how certification burdens, voltage thresholds, and end-use thermal requirements fragment procurement patterns across the value chain. Device manufacturers configure product roadmaps around distinct qualification timelines and customer integration capabilities.
Product Type:
AEC-Q101 automotive qualification separates segments by testing duration and voltage class, with high-voltage devices facing extended reliability verification cycles.
- High Voltage MOSFETs:Blocking capabilities above 1,200 volts suit traction inverters and grid-tied converters. Demand concentrates in Germany's automotive supply chain as OEMs source 800-volt EV architectures requiring elevated breakdown tolerance.
- Power MOSFETs:Optimized for onboard chargers and DC-DC conversion stages with moderate voltage ratings. China's EV manufacturing clusters absorb the steepest volume ramps as domestic brands accelerate SiC adoption in powertrain subsystems.
- Medium Voltage MOSFETs:Bridge applications between industrial motor drives and automotive auxiliary systems.
- Low Voltage MOSFETs:Serve sub-600-volt applications where silicon MOSFETs still compete on cost.
Leading the category by volume: Power MOSFETs. Growing fastest: High Voltage MOSFETs.
Application:
Application segments diverge by switching frequency requirements and thermal management complexity, with automotive traction systems demanding the most intensive co-development relationships.
- Electric Vehicles:Traction inverters, onboard chargers, and DC-DC converters require AEC-Q101 qualification and ISO 26262 functional safety compliance. Procurement concentrates among vertically integrated OEMs in China and Germany seeking multi-year supply agreements.
- Industrial Automation:Motor drives and welding equipment represent mature demand with stable specifications. Germany's Ruhr industrial corridor anchors European consumption for motion control systems.
- Energy Storage Systems:Utility-scale battery inverters need blocking capabilities above 1,200 volts with extended thermal cycling reliability.
- Renewable Energy:Solar and wind converters prioritize efficiency gains over switching frequency optimization.
Industrial Automation holds the largest installed base. Electric Vehicles commands the steepest expansion trajectory.
End User:
End user categories separate by in-house packaging capability and system-level design authority, determining whether procurement targets bare die or fully qualified modules.
- Automotive OEMs:Direct sourcing of qualified power modules for traction inverters dominates. Volkswagen, BYD, and Tesla negotiate multi-year substrate allocation agreements.
- Power Electronics Manufacturers:Tier-1 suppliers like Infineon and STMicroelectronics integrate bare die into customized modules for specific thermal profiles.
- Industrial Equipment Manufacturers:Source standard catalog devices with established reliability records for motor drives and welding systems.
- Renewable Energy Providers:Procurement emphasizes total cost of ownership over discrete device specifications for utility-scale installations.
Power Electronics Manufacturers intermediate the highest transaction volumes. Automotive OEMs are gaining share fastest through direct sourcing initiatives.
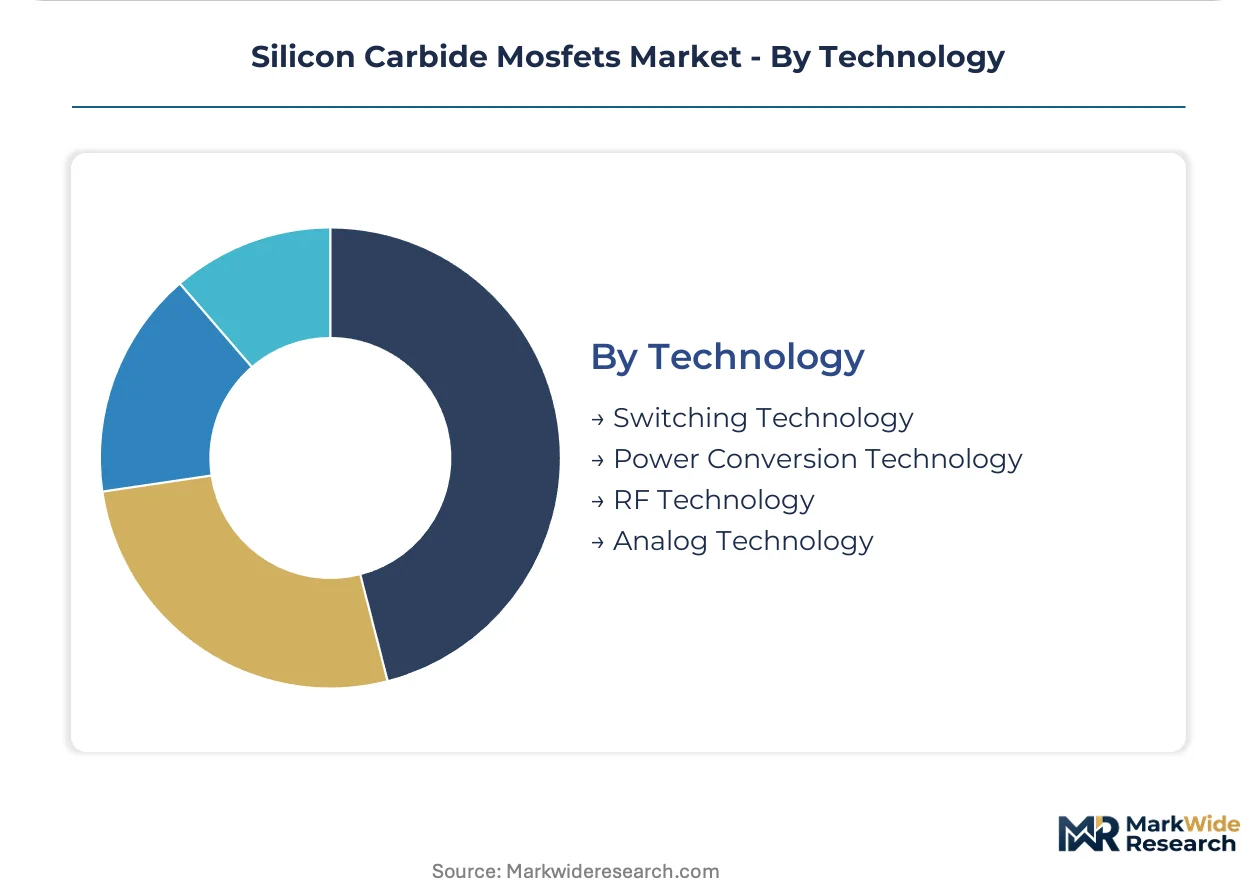
Technology:
Technology segments map to frequency-voltage operating envelopes, with switching technology capturing value from gate-drive optimization trends.
- Switching Technology:Gate-drive integration and adaptive dead-time control enable real-time performance tuning. Software-defined architectures allow Tier-1 suppliers to optimize switching profiles without device replacement.
- Power Conversion Technology:DC-AC and DC-DC topologies for traction inverters and onboard chargers. Efficiency mandates from EPA and NHTSA accelerate displacement of silicon IGBTs.
- RF Technology:High-frequency applications in radar and communications infrastructure.
- Analog Technology:Linear mode operation for protection circuits and sensing applications.
Power Conversion Technology anchors current revenue. Switching Technology is expanding most quickly through intelligent gate-driver integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan anchor the steepest volume ramps as China's EV manufacturing clusters absorb substrate supply faster than crystal growth capacity expands. Regulatory mandates across three continents are compressing silicon displacement timelines and reshaping procurement geography.
United States
Detroit's automotive corridor and Austin's semiconductor fabrication zones drive traction inverter demand for 800-volt EV architectures. EPA tailpipe regulations and NHTSA corporate average fuel economy standards mandate efficiency gains that SiC power electronics directly enable. Wolfspeed's crystal growth operations in North Carolina anchor domestic substrate supply as OEMs negotiate multi-year allocation agreements.
Germany
Munich and Stuttgart house power module integration facilities serving Volkswagen, BMW, and Mercedes-Benz electrification programs. EU Green Deal industrial policy and REACH substance controls incentivize European-sourced devices for automotive qualification. The Ruhr industrial corridor sustains mature demand for motor drives and welding equipment with stable specifications.
China
BYD, NIO, and XPeng accelerate SiC adoption in powertrain subsystems across Shenzhen, Shanghai, and Hefei manufacturing bases. GB standards and MEE dual carbon goals from Beijing accelerate domestic substitution programs for automotive power electronics. Crystal growth capacity clusters in Jiangsu and Shandong provinces face allocation pressure between internal device production and external merchant sales.
Japan
Toyota, Honda, and Nissan electrification roadmaps concentrate procurement in Nagoya and Tokyo metropolitan supply chains. METI technology roadmaps prioritize wide-bandgap semiconductor development for next-generation mobility systems. Yokohama-based power electronics manufacturers source qualified modules for hybrid and battery-electric vehicle platforms.
South Korea
Hyundai Motor Group and Samsung SDI drive demand through Seoul and Gwangju production complexes. MFDS industrial policy coordination and national semiconductor competitiveness initiatives support domestic device qualification. Busan-Ulsan manufacturing corridors integrate SiC modules into battery-electric vehicle export platforms targeting European and North American markets.
Silicon Carbide Mosfets Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent capital intensity models. The vendor base concentrates around substrate manufacturers with captive crystal growth capacity and device fabricators dependent on external supply agreements. Three archetypes dominate: vertically integrated substrate-to-device producers, fabless power semiconductor specialists, and diversified analog-mixed-signal conglomerates with wide-bandgap divisions. Competitive moves center on long-term supply agreements locking crystal growth output and geographic expansion of epitaxy capacity near automotive OEM assembly plants.
Among European-integrated device manufacturers, STMicroelectronics exemplifies the captive substrate archetype through in-house production of SiC boules. Wolfspeed occupies a position representing North American vertical control from crystal growth through device fabrication. Infineon Technologies anchors the diversified conglomerate model with portfolio breadth spanning voltage classes and packaging formats. These three patterns illustrate how substrate supply security has become the primary axis of competitive differentiation as crystal growth capacity constrains market expansion.
| Leading Market Players |
|---|
| STMicroelectronics |
| Wolfspeed |
| Infineon Technologies |
| onsemi |
| ROHM |
| Mitsubishi Electric |
| Toshiba |
| Fuji Electric |
| Littelfuse |
| Others |
Value Network & Pricing Analysis
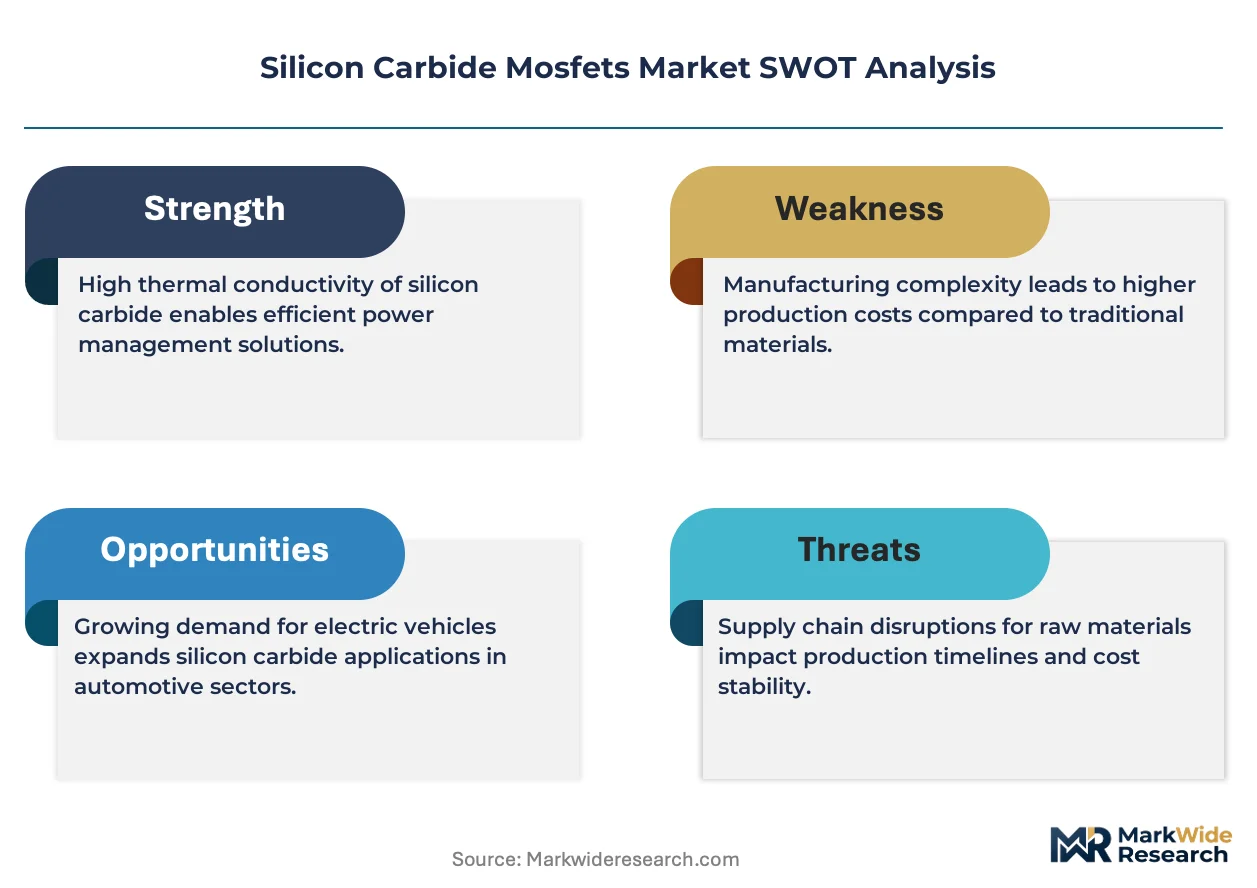
AEC-Q101 certification tiers bifurcate procurement economics between automotive-qualified and industrial-grade supply, compressing margins on standard devices while premium qualified products command allocation priority from substrate manufacturers. This divergence concentrates pricing power with vertically integrated producers possessing captive crystal growth capacity, while fabless competitors absorb volatility through long-term supply agreements.
Pricing Analysis
Price erosion across industrial-grade MOSFETs traces to capacity expansion in China's Jiangsu crystal growth corridors flooding merchant substrate supply. Contract-based long-term offtake dominates automotive procurement, with AEC-Q101 qualification tier and volume scale as primary differentiation drivers. Pricing pressure intensifies in onboard charger segments as BYD and Tesla negotiate direct sourcing agreements. Tier-1 automotive OEMs exhibit lowest price sensitivity; welding equipment manufacturers in Germany's Ruhr corridor remain most exposed to spot-market volatility.
Supply Chain Analysis
EU Green Deal local-content requirements and China's GB standards are reshaping sourcing patterns toward regional epitaxy capacity. Supply concentrates in China, Germany, and the United States for crystal growth and device fabrication. Raw material dependencies center on high-purity silicon carbide powder, specialized graphite crucibles, and argon process gas. Single-source vulnerability in 6-inch substrate supply creates structural risk. Distribution runs through qualified power module integrators for automotive, with direct catalog sales for industrial automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystal growth capacity scarcity is forcing consolidation as substrate allocation agreements determine competitive survival. Device manufacturers without captive boule production face existential margin compression.
For Market Incumbents: Lock in multi-year substrate supply agreements with Jiangsu and Shandong crystal growth facilities before allocation windows close. Prioritize backward integration into epitaxy capacity near Stuttgart and Munich automotive clusters to satisfy EU Green Deal sourcing requirements. GaN-SiC hybrid module development represents the critical R&D lever against pure-play silicon carbide specialists.
For New Entrants and Emerging Players: Tier-2 automotive suppliers in South Korea's Gwangju corridor offer the most penetrable channel partnership pathway. Target energy storage inverter applications where AEC-Q101 timelines do not constrain qualification. White-space exists in grid-tied converter modules above 1,700 volts where defect density limitations exclude established suppliers. A co-development positioning with Busan-Ulsan battery manufacturers enables differentiated entry.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified analog-mixed-signal conglomerates seeking wide-bandgap divisions. Long-term viability hinges on 5-10 year substrate supply security rather than device design differentiation. Prioritize targets with qualified epitaxy capacity and existing AEC-Q101 certification infrastructure. The inflection signal to watch is allocation priority shifts in Wolfspeed and STMicroelectronics merchant substrate sales.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Crystal Growth Investment | North Carolina and Jiangsu boule capacity secures substrate allocation against merchant market volatility. |
| AEC-Q101 Certification Fast-Track | Accelerated automotive qualification compresses 18-24 month timelines for traction inverter supply. |
| Intelligent Gate-Driver Integration | Software-defined architectures shift value capture from bare die to system-level firmware control. |
| GaN-SiC Hybrid Module Development | Combining gallium nitride HEMTs with silicon carbide diodes optimizes frequency-voltage operating envelopes. |
| Regional Epitaxy Capacity Expansion | Greenfield facilities near Stuttgart satisfy EU REACH substance controls and carbon border adjustments. |
Research Methodology
Independent corroboration across semiconductor device engineers, automotive Tier-1 procurement directors, and crystal growth facility managers underwrites the qualitative findings. Primary interviews with power module integration specialists, epitaxy equipment suppliers, and EV platform architects combined with secondary validation from SEC 10-K filings, EPA emissions compliance databases, and IHS Markit vehicle production data. Bottom-up substrate capacity modeling and top-down EV adoption scenarios were triangulated.
Rate-of-change decomposition across voltage class, application thermal profile, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves weighted by OEM platform rollout schedules and grid-scale energy storage deployment pipelines. Forecast inputs included MEE dual carbon goal implementation timelines and NHTSA fuel economy standard phase-in rates.
Caveats apply where EPA regulatory delays or China-Taiwan trade friction could materially shift the outlook. Forecasts reflect assumptions around crystal growth yield improvements and AEC-Q101 qualification timeline compression. Substrate supply concentration in Jiangsu and Shandong provinces, EU F-Gas Regulation retrofit costs, and defect density breakthroughs above 1,700 volts represent specific revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Mosfet Power Transistors Market