
 India Packaging Market | 2026-2036
India Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Packaging Market Foresight
Pharmaceutical packaging demand is hardening as domestic drug formulation output expands and export compliance tightens. Uflex Ltd. leverages its integrated film-to-flexible-packaging operations across multiple Indian states. TCPL Packaging Ltd. anchors the folding carton segment through long-standing relationships with FMCG majors. Time Technoplast competes in the industrial packaging niche with specialized polymer solutions for chemicals and agrochemicals.
Packaging encompasses the design, engineering, and production of protective enclosures using materials such as polyethylene terephthalate, kraft paperboard, and aluminum alloys, typically manufactured through extrusion blow molding, thermoforming, or gravure printing processes. Its primary purpose is to preserve product integrity, enable efficient logistics, and communicate brand identity at the point of sale. Flexible packaging leads volume contribution due to its lightweight properties and cost efficiency in food and personal care applications, while rigid packaging commands premium margins in pharmaceuticals where barrier protection and child-resistance specifications are non-negotiable. Paperboard cartons sustain growth in sustainable packaging transitions as brand owners reduce plastic dependency.
BIS standards govern material specifications for food-contact plastics and paperboard, while FSSAI mandates nutritional labeling and shelf-life declarations that directly influence packaging design cycles. The Plastic Waste Management Rules enforce extended producer responsibility obligations that reshape sourcing decisions for brand owners and converters. Stakeholders must monitor evolving EPR compliance thresholds and state-level plastic ban implementations to align capacity investments with regulatory trajectories.
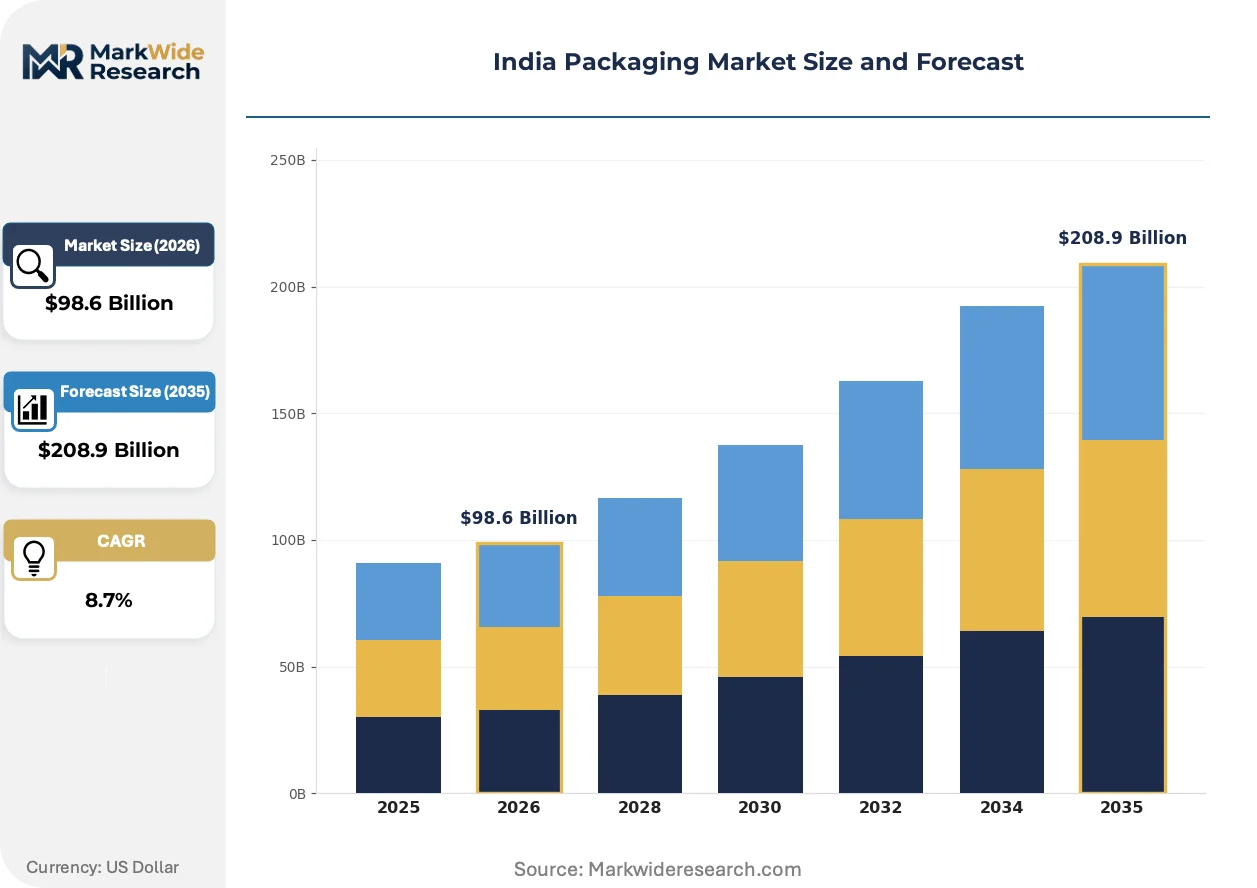
Market Dynamics
Domestic pharmaceutical formulation output is expanding rapidly, tightening export compliance requirements and forcing converters to upgrade barrier specifications and serialization capabilities across Maharashtra and Gujarat production clusters.
Growth Catalysts
- FSSAI Labeling Mandates:Nutritional disclosure rules and shelf-life declaration requirements are accelerating packaging design refresh cycles among food processors.
- Pharmaceutical Export Compliance:CDSCO alignment with WHO prequalification standards is driving demand for high-barrier blister packs and track-and-trace serialization.
- Tier-Two Urbanization:Packaged food penetration is deepening across secondary cities as cold chain infrastructure and modern retail formats reach Satara, Coimbatore, and Ludhiana.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil movements, compressing converter margins on fixed-price FMCG contracts.
- Import Dependency for Specialty Films:Metallized and high-barrier coextruded films rely heavily on suppliers from Germany, Japan, and South Korea, exposing converters to currency and freight cost swings.
- Technical Limitations in Recycling Infrastructure:Multi-layer flexible laminates lack economically viable mechanical recycling pathways, constraining circular economy commitments under Plastic Waste Management Rules.
Strategic Opportunities
- North-Eastern States Penetration:Assam and Manipur present underdeveloped packaged food markets where regional brands can establish distribution before national players consolidate shelf space.
- PLI Scheme for Specialty Chemicals:Production-linked incentives for active pharmaceutical ingredients are expanding domestic drug manufacturing, pulling associated primary and secondary packaging demand.
- Digital Printing Convergence:Combination of inkjet deposition and inline quality inspection is enabling mass customization and variable data printing for regional language labeling.
Industry Challenges
- Skilled Operator Scarcity:Gravure cylinder engraving and blown film die adjustment require specialized technicians that vocational institutes in Gujarat and Maharashtra fail to produce at sufficient scale.
- BIS Certification Timelines:Food-contact material testing and BIS mark approval cycles stretch 8-14 months, delaying new product launches and reformulation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Packaging Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Vacuum Packaging Material: Plastic, Paperboard, Glass, Metal End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Packaging Type: Bottles, Pouches, Cartons, Trays |
| Companies Covered | Time Technoplast, Uflex Ltd., Smurfit WestRock, EPL Ltd., Parksons Packaging Ltd., ITC Limited, TCPL Packaging Ltd., Xolopak, JK Paper Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Packaging Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape converter capabilities, with sustainability mandates and pharmaceutical serialization requirements forcing capital redeployment across the value chain.
Mono-material polyethylene laminates are integrating high-barrier coatings through plasma-enhanced chemical vapor deposition, replacing aluminum foil in snack and personal care sachets. FMCG majors in Mumbai and Bengaluru are piloting these structures for 2025 shelf tests. This substitution is integrating polymer chemistry expertise directly into converter R&D functions, displacing traditional film supplier relationships.
Plastic Waste Management Rules enforcement is tightening extended producer responsibility thresholds, requiring brand owners to document collection and recycling of post-consumer flexible packaging. FSSAI is coordinating with state pollution control boards to verify compliance during facility audits. Small and mid-tier converters in Tamil Nadu and Karnataka are consolidating to share EPR compliance costs and collection infrastructure.
Modern trade and quick commerce platforms are compressing order fulfillment cycles, forcing packers to hold finished goods inventory in city-edge warehouses. Reliance Retail and Blinkit are demanding 24-hour replenishment turns, replacing monthly stockist orders. This velocity concentration is most visible in Delhi-NCR and Bengaluru, where dark store networks require retail-ready case packing and pallet configuration changes.
India Packaging Market Segmentation
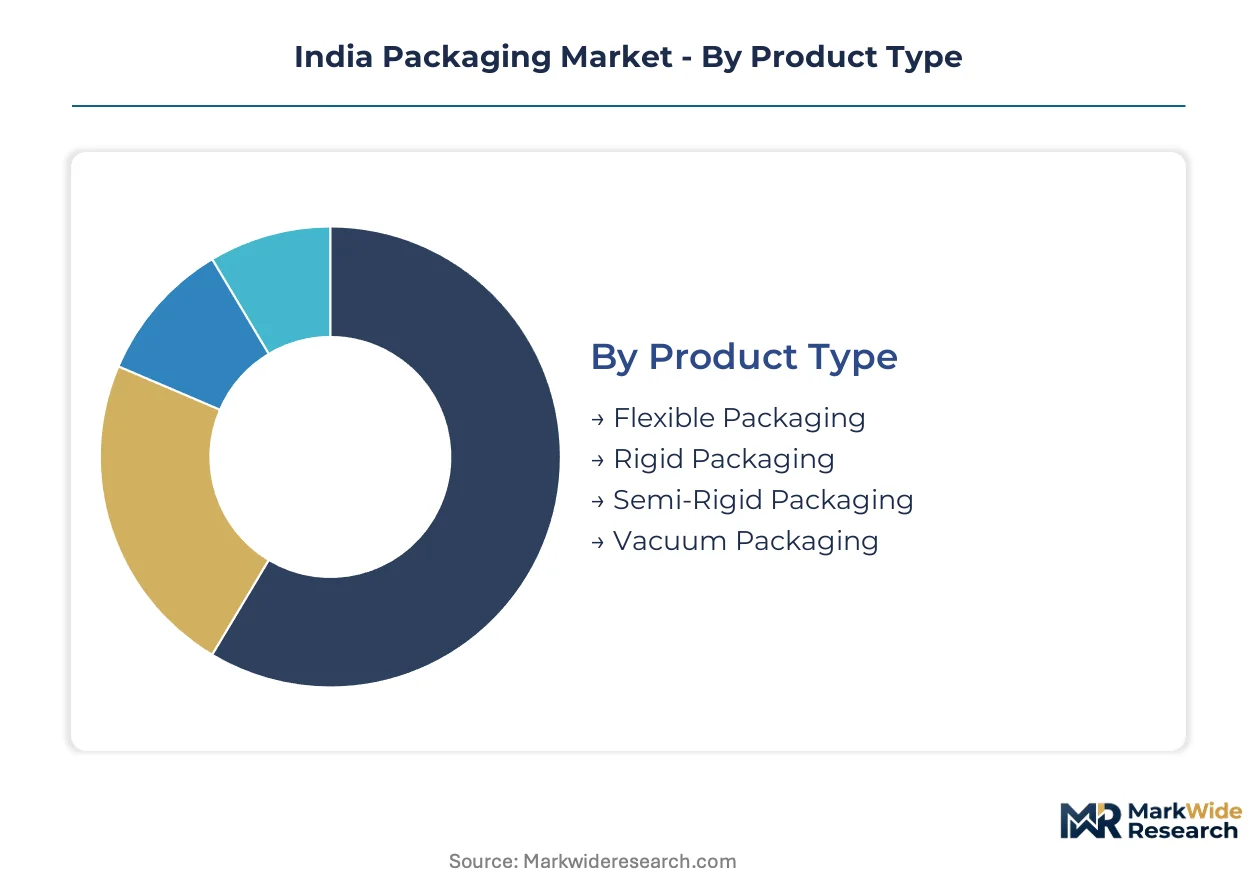
Segmentation reveals how material specifications and end-use compliance requirements fragment converter capabilities across India. Each dimension exposes distinct supply chain pressures, from petrochemical feedstock dependencies to pharmaceutical serialization mandates.
Product Type:
Supply concentration in flexible packaging dominates converter investments across Maharashtra and Gujarat, where film extrusion lines cluster near petrochemical feedstock sources.
- Flexible Packaging:Multi-layer laminates of polyethylene, polypropylene, and polyester films deliver barrier protection at low weight for snacks and personal care sachets. Demand concentrates in Mumbai and Bengaluru, where FMCG majors compress order cycles through quick commerce platforms. BIS certification timelines for food-contact films stretch 8-14 months, delaying new product launches.
- Rigid Packaging:Injection-molded and thermoformed containers of high-density polyethylene and polyethylene terephthalate provide structural integrity for pharmaceuticals and beverages. Gujarat pharmaceutical clusters drive specification upgrades for child-resistance and barrier compliance. CDSCO alignment with WHO prequalification standards forces serialization capability investments.
- Semi-Rigid Packaging:Thermoformed trays and blister packs bridge protection and display functions for electronics and prepared foods.
- Vacuum Packaging:Gas-flushed barrier structures extend shelf life for processed meats and ready meals in modern retail formats.
Flexible packaging absorbs the bulk of installed capacity; rigid packaging is expanding most quickly.
Material:
Cost tier differentiation separates commodity converters from specialty material suppliers, with plastic and paperboard occupying opposite ends of the margin spectrum.
- Plastic:Polyethylene, polypropylene, and polyethylene terephthalate resins constitute the volume foundation, processed through blown film extrusion and injection molding. Petrochemical price volatility compresses margins on fixed-price FMCG contracts, particularly for converters serving Reliance Retail and Blinkit in Delhi-NCR.
- Paperboard:Kraft and solid bleached sulfate boards enable sustainable transitions as brand owners reduce plastic dependency. Folding carton demand anchors in Mumbai and Bengaluru, where TCPL Packaging maintains long-standing FMCG relationships. FSSAI labeling mandates accelerate design refresh cycles for nutritional disclosure compliance.
- Glass:Borosilicate and soda-lime containers serve pharmaceutical and premium beverage segments with inert barrier properties.
- Metal:Aluminum and tinplate cans provide hermetic sealing for processed foods and aerosol applications.
Plastic commands the widest converter base; paperboard is climbing the fastest on sustainability transitions.
End User:
Application-driven specifications fragment converter capabilities, with pharmaceutical and food segments imposing divergent compliance regimes.
- Food & Beverage:Packaging spans flexible laminates for snacks, rigid containers for dairy, and aseptic cartons for beverages. Tier-two urbanization deepens penetration across Satara, Coimbatore, and Ludhiana as cold chain infrastructure expands. FSSAI shelf-life declaration requirements directly influence design cycles.
- Pharmaceuticals:Blister packs, vials, and ampoules demand high-barrier properties and track-and-trace serialization. Domestic formulation output expansion in Maharashtra and Gujarat tightens export compliance requirements. CDSCO mandates alignment with WHO prequalification standards.
- Personal Care:Sachets, tubes, and bottles combine aesthetic differentiation with moisture and oxygen barrier functions.
- Electronics:Anti-static and moisture barrier packaging protects semiconductors and components through distribution.
Food and beverage absorbs the bulk of installed capacity; pharmaceuticals is gaining share fastest on compliance-driven upgrades.
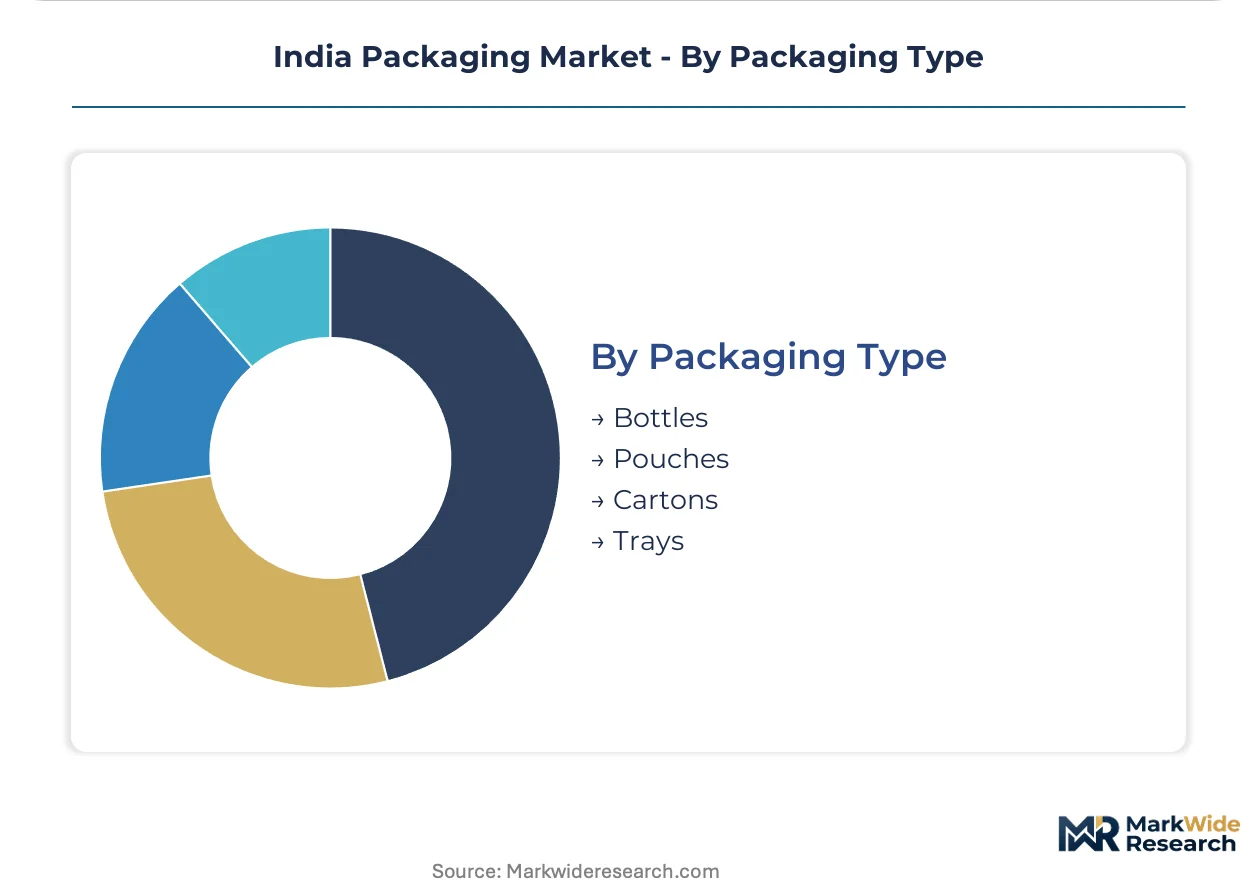
Packaging Type:
Volume concentration in pouches and bottles reflects the dominance of flexible and rigid plastic processing across Indian converter clusters.
- Bottles:Blow-molded polyethylene terephthalate and high-density polyethylene containers serve beverages, pharmaceuticals, and personal care. Demand clusters in Gujarat and Maharashtra near resin supply and formulation facilities.
- Pouches:Stand-up and flat pouches from multi-layer laminates dominate snacks, spices, and personal care sachets. Uflex operates integrated film-to-flexible-packaging lines across multiple states.
- Cartons:Folding and rigid paperboard structures enable retail-ready presentation for FMCG and pharmaceuticals.
- Trays:Thermoformed and molded pulp structures serve fresh produce, ready meals, and electronics protection.
Pouches absorb the bulk of installed capacity; bottles is expanding most quickly on beverage and pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate packaging capacity through tax incentives and petrochemical feedstock proximity. State-level plastic waste regulations and BIS certification mandates reshape investment patterns across Indian sub-regions.
Maharashtra
Pharmaceutical formulation output in Mumbai and Pune drives blister pack and vial demand. CDSCO alignment with WHO prequalification standards forces serialization upgrades. Ambernath and Tarapur industrial corridors host flexible film extrusion clusters serving FMCG majors.
Gujarat
Dahej and Hazira petrochemical complexes supply polyethylene and polypropylene resins to converter networks. FSSAI labeling mandates accelerate design refresh cycles for food-contact materials. Ahmedabad and Vadodara anchor rigid packaging capacity for domestic drug manufacturers.
Karnataka
Bengaluru's quick commerce platforms compress order fulfillment cycles to 24-hour replenishment turns. State pollution control boards enforce Plastic Waste Management Rules through facility audits. Peenya industrial area concentrates folding carton converters serving modern retail formats.
Tamil Nadu
Chennai and Coimbatore cold chain expansion deepens packaged food penetration into tier-two markets. BIS certification timelines for food-contact plastics stretch 8-14 months, delaying launches. Sriperumbudur electronics manufacturing cluster pulls anti-static packaging demand.
Delhi-NCR
Dark store networks for Blinkit and Reliance Retail require retail-ready case packing configurations. Central pollution control oversight intersects with state-level plastic ban implementations. Faridabad and Gurgaon warehouse zones concentrate finished goods inventory for northern distribution.
India Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated film producers commanding premium positions in flexible packaging while regional converters serve price-sensitive industrial accounts. Market structure tilts toward consolidation in pharmaceutical and food-grade segments where BIS and FSSAI compliance costs exclude smaller operators. Three archetypes dominate: integrated resin-to-package conglomerates, specialized folding carton producers, and industrial polymer solution providers. Competitive moves center on backward integration into film extrusion and geographic expansion into underpenetrated north-eastern states.
Among integrated flexible packaging specialists, Uflex Ltd. and EPL Ltd. exemplify the resin-to-package archetype through captive film production capabilities. TCPL Packaging Ltd. anchors the premium folding carton tier through long-standing FMCG relationships. Time Technoplast occupies a distinct position in industrial packaging, supplying specialized polymer solutions for chemical and agrochemical applications where barrier specifications differ from consumer-facing segments.
| Leading Market Players |
|---|
| Time Technoplast |
| Uflex Ltd. |
| Smurfit WestRock |
| EPL Ltd. |
| Parksons Packaging Ltd. |
| ITC Limited |
| TCPL Packaging Ltd. |
| Xolopak |
| JK Paper Ltd. |
| Others |
Supply & Pricing Matrix
Gravure cylinder engravers and blown-film die technicians in Gujarat and Maharashtra command wage premiums that widen pricing spreads between certified pharmaceutical-grade converters and commodity flexible-packaging suppliers serving price-sensitive FMCG accounts.
Pricing Analysis
Lead-time compression commands premium pricing across pharmaceutical and quick-commerce segments, while spot inventory of standard polyethylene laminates trades at discounts to contract rates. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified food-contact specialists from regional converters and unbranded industrial suppliers. Price differentiation hinges on certification grade and volume scale, with FSSAI-compliant folding cartons capturing margin premiums over generic alternatives. Cost compression in commodity flexible packaging is intensifying because petrochemical feedstock volatility squeezes fixed-price FMCG contracts. Brand owners in tier-two cities exhibit highest price sensitivity; pharmaceutical exporters in Maharashtra and Gujarat show least sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Workforce availability constraints in Maharashtra and Gujarat petrochemical corridors limit expansion velocity for film extrusion and gravure printing operations. Supply concentrates in India for flexible and rigid packaging conversion, with critical dependencies on Germany, Japan, and South Korea for metallized and high-barrier coextruded films. Raw material sourcing draws from Dahej and Hazira petrochemical complexes for polyethylene and polypropylene resins, kraft pulp from domestic paper mills, and imported specialty coatings. Single-source vulnerability for high-barrier films exposes converters to currency and freight cost swings. Distribution runs through Mumbai and Bengaluru warehouse zones for quick-commerce fulfillment, with regional stockists serving tier-two penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive film production and in-house barrier-coating capabilities determine margin capture and compliance responsiveness.
For Market Incumbents: Deploy captive extrusion capacity to secure resin supply and compress BIS certification timelines. Consolidate regional converters in Tamil Nadu and Karnataka to share EPR compliance infrastructure and collection networks. Defend against specialty-film import dependency by investing in plasma-enhanced chemical vapor deposition coating lines for mono-material barrier structures.
For New Entrants and Emerging Players: Enter via underdeveloped north-eastern states where Assam and Manipur present first-mover shelf-space opportunities before national brands establish distribution. Target pharmaceutical serialization services as CDSCO mandates tighten track-and-trace requirements across Maharashtra and Gujarat clusters. Pursue digital printing partnerships with quick-commerce platforms for regional-language variable-data labeling.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated film-to-package specialists given PLI scheme expansion for active pharmaceutical ingredients and associated packaging pull-through. Long-term viability favors converters with backward integration into resin compounding and forward integration into EPR-compliant collection infrastructure. Monitor BIS certification queue lengths as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin processing insulates margins from petrochemical volatility and compresses lead times for FMCG accounts. |
| Digital Printing Infrastructure Deployment | Inkjet deposition with inline inspection enables mass customization for quick-commerce regional-language labeling requirements. |
| EPR Compliance Infrastructure Sharing | Consolidated collection networks reduce per-unit compliance costs for mid-tier converters under Plastic Waste Management Rules. |
| North-Eastern Distribution Establishment | Early shelf-space capture in Assam and Manipur precedes national brand consolidation in underpenetrated markets. |
| Pharmaceutical Serialization Capability Investment | Track-and-trace systems align with CDSCO-WHO prequalification standards for export-compliant blister and vial production. |
Research Methodology
Multi-period observation of BIS certification timelines, EPR compliance thresholds, and pharmaceutical export volumes anchored the trend analysis, supplemented by interviews with plant managers at flexible film extrusion facilities, procurement leads at FMCG majors, regulatory affairs officers navigating FSSAI labeling mandates, and distribution channel partners in tier-two cities. Secondary validation drew from CDSCO filings, FSSAI notification registers, state pollution control board audit records, and petrochemical import customs data. Bottom-up capacity assessments across Maharashtra and Gujarat converter clusters were triangulated against top-down demand estimates from food processing and pharmaceutical formulation output.
Input-output matrices mapped resin consumption to finished packaging output across flexible, rigid, and paperboard segments over the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use application, and regional production cluster. CAGRs were derived from trend extrapolation of pharmaceutical formulation growth, tier-two urbanization rates, and regulatory compliance investment cycles. Industry-specific forecast inputs incorporated PLI scheme disbursement trajectories for active pharmaceutical ingredients and quick-commerce order-velocity expansion in Delhi-NCR and Bengaluru.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical price spikes or accelerated state-level plastic ban implementations. Material deviation in BIS certification processing speeds, EPR enforcement intensity, or pharmaceutical export compliance timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Halal Packaging Market