
 India E-Commerce Packaging Market | 2026-2036
India E-Commerce Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India E-Commerce Packaging Market Foresight
BIS IS 15495 certification for food-grade packaging materials is unwinding competitive access across the India e-commerce packaging sector. Huhtamaki India Ltd leverages its integrated pulp-to-box manufacturing footprint to sustain compliance leadership in corrugated food delivery containers. TCPL Packaging Ltd anchors its position through specialized gravure printing capabilities that serve premium fashion and electronics brands. Uflex Limited competes via multilayer film extrusion technology that extends shelf life for grocery shipments in tropical climates.
India e-commerce packaging encompasses protective and containment systems engineered for last-mile distribution of goods ordered through digital retail channels, typically incorporating burst strengths of 200–350 kPa for corrugated boxes and seal temperatures calibrated to 120–180°C for polymeric mailers. Cartons dominate value capture due to established recycling infrastructure, while biodegradable materials represent the fastest-expanding material category as brand sustainability commitments harden. Poly bags retain volume leadership in fashion shipments where dimensional flexibility reduces dimensional weight charges. Same-day delivery formats command premium pricing but require lighter-weight material specifications to control courier costs.
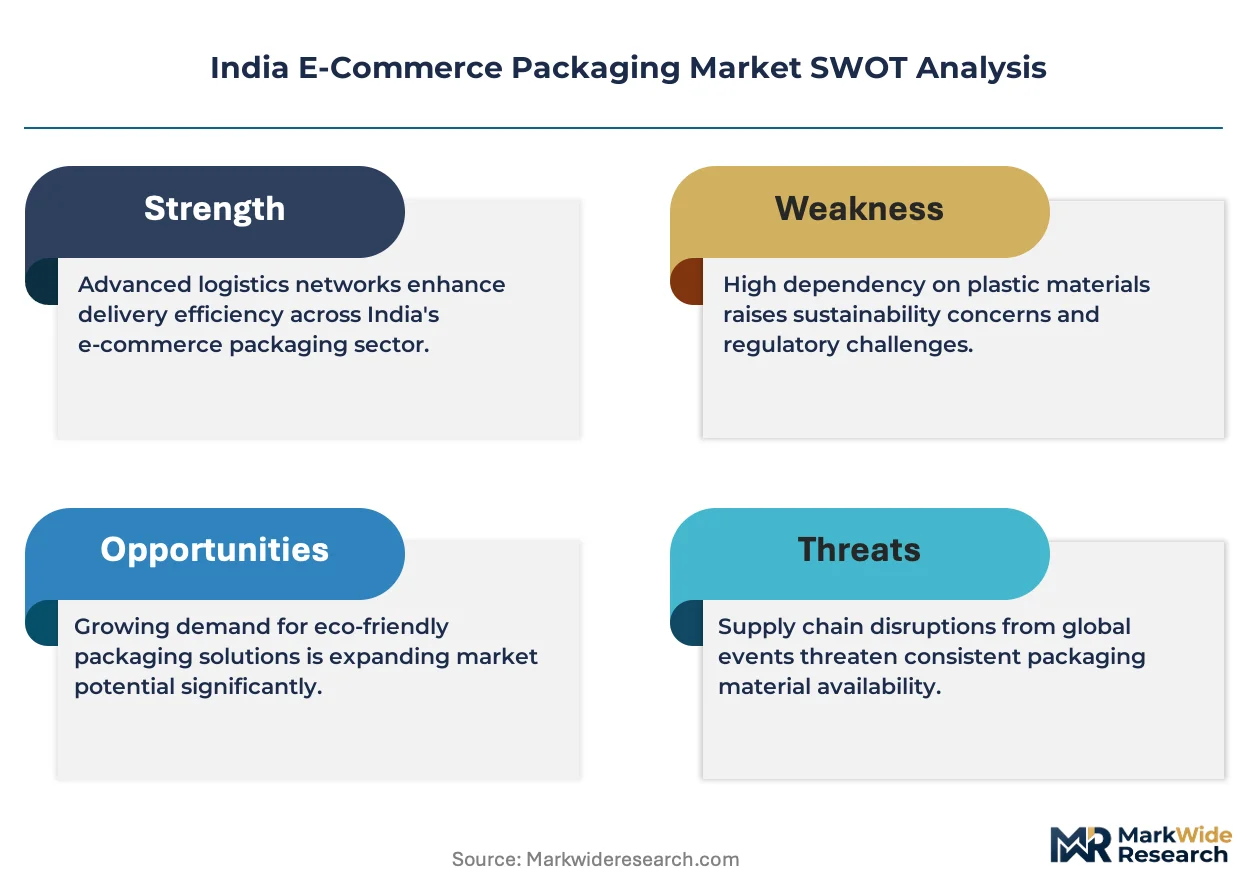
BIS mandates on food-contact safety, Central Pollution Control Board directives on extended producer responsibility for plastic waste, and FSSAI labeling requirements collectively shape product design and material selection across the sector. The PLI scheme for specialty packaging substrates redirects capital toward domestic manufacturing of barrier films and molded fiber alternatives. Stakeholders must monitor how state-level plastic ban enforcement in Maharashtra, Karnataka, and Tamil Nadu fragments material availability and forces rapid formulation pivots.
Market Dynamics
BIS IS 15495 certification mandates for food-contact packaging materials are compressing supplier margins while redistributing market share toward integrated pulp-to-box manufacturers with captive testing laboratories.
Growth Catalysts
- Online grocery expansion:Quick-commerce platforms in Maharashtra and Karnataka are driving demand for temperature-stable corrugated containers with burst strengths exceeding 250 kPa.
- PLI scheme for specialty substrates:The government's production-linked incentive scheme is redirecting domestic capital toward barrier film manufacturing and molded fiber alternatives.
- FSSAI labeling mandates:Stricter nutritional disclosure requirements on food delivery packaging are forcing brand owners to upgrade gravure printing specifications.
Market Restraints
- Kraft paper price volatility:Imported pulp dependency exposes converters to currency fluctuation risks that compress gross margins by 8-12 percentage points during rupee depreciation cycles.
- State-level plastic ban fragmentation:Divergent enforcement timelines across Maharashtra, Karnataka, and Tamil Nadu create formulation uncertainty and inventory stranding risks for polymeric mailer producers.
- Barrier film technical limitations:Current multilayer extrusion technologies cannot achieve oxygen transmission rates below 0.5 cc/m²/day required for premium spice shipments.
Strategic Opportunities
- Telangana fulfillment corridor:Hyderabad's emerging logistics hub status offers first-mover advantages for localized corrugated converting capacity serving southern India.
- Biodegradable material convergence:Integration of agricultural residue pulping with enzymatic coating technologies enables compostable food containers at parity pricing with PE-lined alternatives.
- EPR credit monetization:Central Pollution Control Board's extended producer responsibility framework allows packaging producers to trade compliance credits with e-commerce platforms lacking recycling infrastructure.
Industry Challenges
- Gravure cylinder engraving skill scarcity:The shortage of qualified pre-press technicians capable of 175-line screen reproduction delays premium brand onboarding by 6-8 weeks.
- BIS certification timeline compression:Food-grade testing protocols at NABL-accredited laboratories now require 14-18 weeks, creating working capital strain for mid-scale converters.
- Legacy ERP integration friction:Batch-oriented manufacturing execution systems at established corrugated plants resist real-time integration with e-commerce platform APIs for dynamic carton sizing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India E-Commerce Packaging Market |
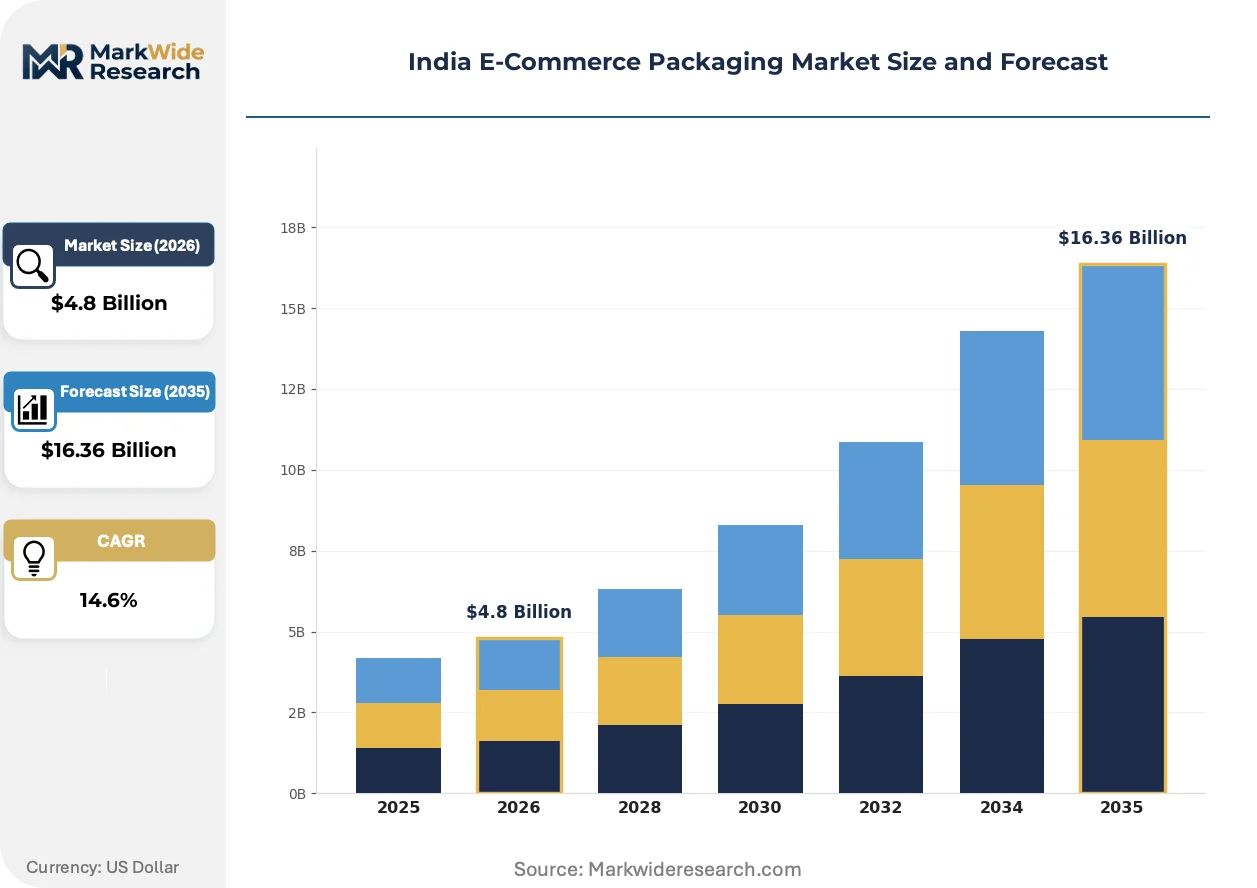
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cartons, Poly Bags, Bubble Wrap, Pallets Material: Cardboard, Plastics, Biodegradable Materials, Kraft Paper End User: Consumer Electronics, Fashion, Grocery, Home Goods Delivery Method: Standard Shipping, Same-Day Delivery, Express Delivery, Drop Shipping |
| Companies Covered | Huhtamaki India Ltd, TCPL Packaging Ltd, Uflex Limited, Jindal Poly Films Limited, ITC Limited, EPL Limited, Parksons Packaging Ltd, Xolopak, Tetra Pak India Pvt. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India E-Commerce Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory compression are converging to redefine performance specifications across India's e-commerce packaging value chain.
Molded fiber technology is fragmenting the protective packaging segment as bagasse and wheat straw pulping achieve drop-test performance parity with expanded polystyrene. Quick-commerce platforms in Bengaluru and Mumbai are piloting these containers for fragile electronics shipments. The technology is fragmenting incumbent foam converter market positions by eliminating import dependency and state plastic ban exposure.
BIS IS 15495 certification requirements for food-contact materials are tightening testing protocols for heavy metal migration and overall migration limits. Converters without captive laboratory capabilities face outsourcing costs of ₹2.5-4 lakh per SKU certification. Maharashtra-based food delivery aggregators are responding by consolidating supplier bases toward integrated manufacturers with in-house BIS testing infrastructure.
Same-day delivery service level agreements are compressing packaging specification cycles from annual reviews to quarterly revisions. Fashion e-commerce platforms are replacing standard poly mailers with right-sized paper-based alternatives to reduce dimensional weight charges. This behavioral shift is most visible in Delhi-NCR and Hyderabad where courier density supports sub-4-hour delivery promises.
India E-Commerce Packaging Market Segmentation
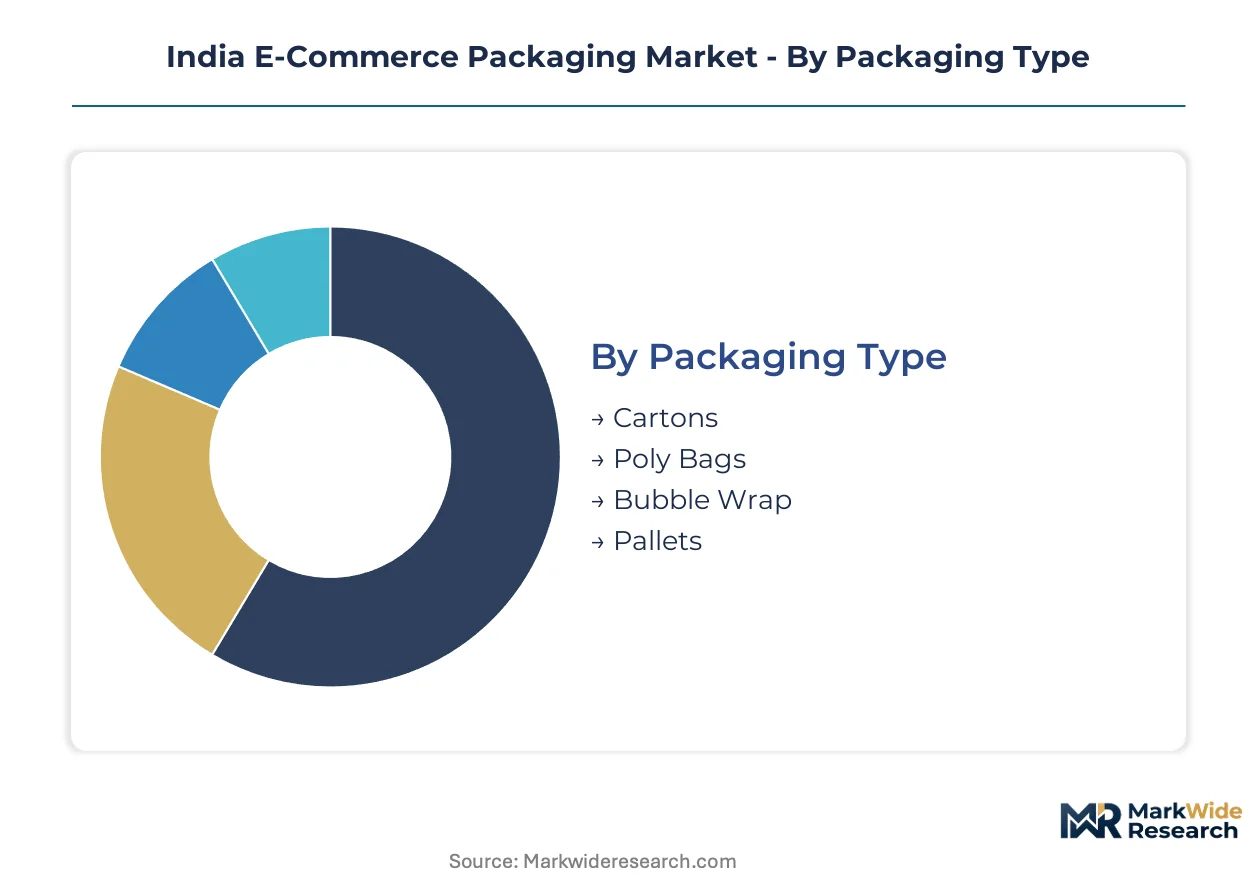
Segmentation in India's e-commerce packaging sector reveals how regulatory pressure and logistics economics split margin pools across material technologies and fulfillment formats. Understanding these divides exposes where capital deployment yields defensible positioning.
Packaging Type:
Margin concentration sits with formats that balance protection density against courier dimensional weight pricing.
- Cartons:Corrugated fiberboard structures with burst strengths of 200–350 kPa dominate value capture due to established recycling infrastructure and BIS compliance pathways. Maharashtra and Karnataka fulfillment centers drive specification upgrades as quick-commerce platforms demand temperature-stable containers for grocery shipments.
- Poly Bags:Polyethylene and polypropylene mailers with seal temperatures calibrated to 120–180°C retain volume leadership in fashion shipments where dimensional flexibility reduces freight charges. State-level plastic ban fragmentation across Tamil Nadu and Maharashtra forces rapid formulation pivots toward biodegradable alternatives.
- Bubble Wrap:Air-cushion protective films face displacement from molded fiber alternatives in Bengaluru and Mumbai electronics corridors.
- Pallets:Wooden and plastic load carriers serve bulk B2B replenishment flows into Telangana fulfillment hubs.
The dominant share belongs to Cartons, while Poly Bags is closing the gap fastest through material innovation.
Material:
Cost tier stratification separates legacy substrates from emerging compliance-driven alternatives.
- Cardboard:Recycled corrugated medium and linerboard combinations anchor the installed base. FSSAI labeling mandates on food delivery packaging force gravure printing specification upgrades across Maharashtra-based converters.
- Plastics:Multilayer film extrusion technologies extend shelf life for grocery shipments in tropical climates but face Central Pollution Control Board extended producer responsibility compliance costs.
- Biodegradable Materials:Bagasse and wheat straw pulping achieve drop-test performance parity with expanded polystyrene, expanding most quickly as quick-commerce platforms pilot compostable containers in Delhi-NCR and Hyderabad.
- Kraft Paper:Unbleached virgin and recycled pulp grades suffer margin compression from imported pulp dependency and rupee depreciation exposure.
Cardboard commands the largest volume position, though Biodegradable Materials gains share fastest through PLI scheme support for agricultural residue processing.
End User:
Application-specific performance requirements fragment procurement specifications across verticals.
- Consumer Electronics:Anti-static and shock-resistant packaging demands concentrate in Bengaluru and Mumbai corridors where molded fiber technology displaces foam converters.
- Fashion:Right-sized paper-based alternatives replace standard poly mailers to reduce dimensional weight charges, with Delhi-NCR and Hyderabad leading specification shifts.
- Grocery:Temperature-stable corrugated containers with burst strengths exceeding 250 kPa dominate quick-commerce procurement in Maharashtra and Karnataka.
- Home Goods:Fragile-item protective systems span carton, molded fiber, and air-cushion formats depending on product density and courier cost structures.
Grocery claims the steepest expansion trajectory as quick-commerce platforms consolidate supplier bases toward integrated BIS-certified manufacturers.
Delivery Method:
Service level agreements compress packaging specification cycles from annual reviews to quarterly revisions.
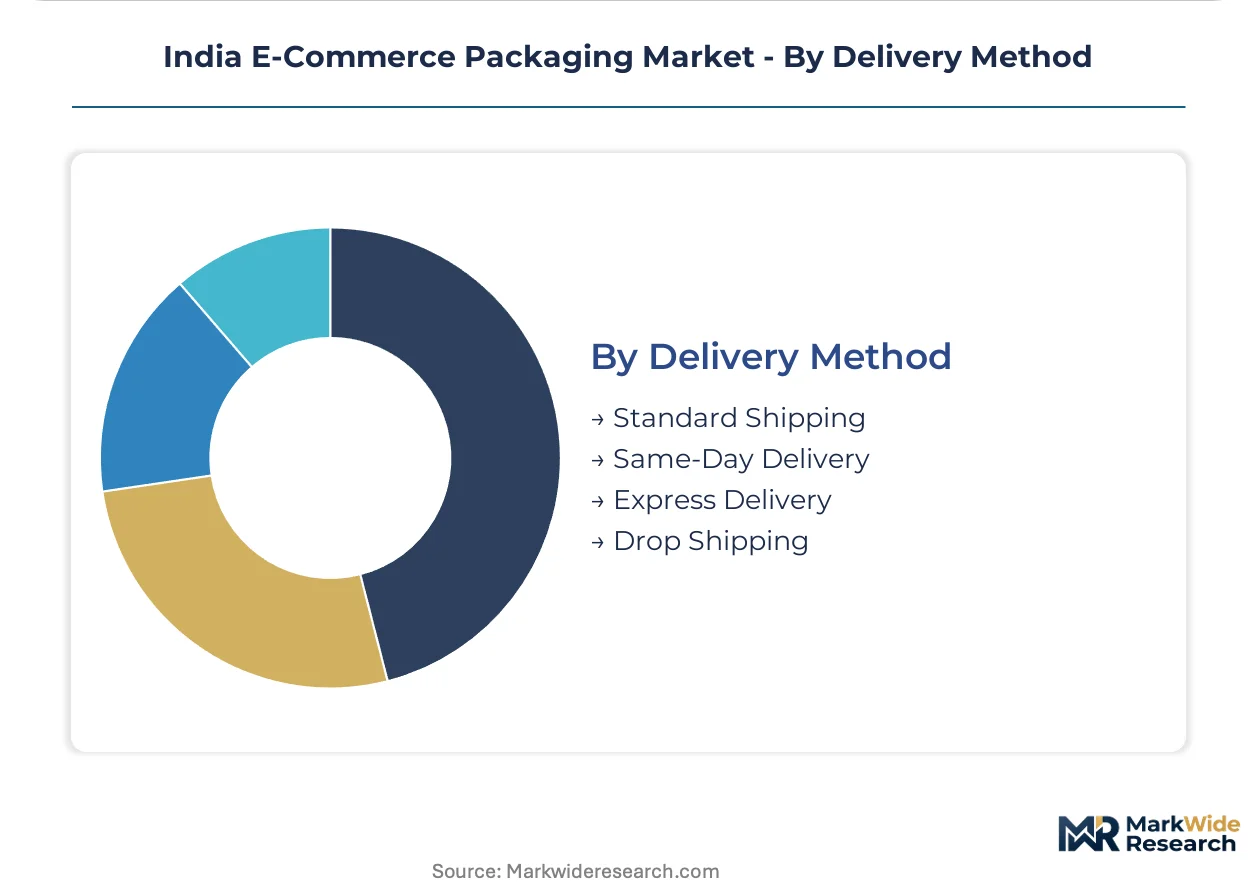
- Standard Shipping:Cost-optimized corrugated and polymeric formats serve 2–5 day delivery promises across Tier-2 and Tier-3 city networks.
- Same-Day Delivery:Lightweight material specifications control courier costs for sub-4-hour fulfillment in Delhi-NCR and Hyderabad where density supports premium service economics.
- Express Delivery:24-hour formats balance protection with weight minimization for high-value electronics and fashion shipments.
- Drop Shipping:Direct-from-manufacturer fulfillment demands neutral branding and variable carton sizing capabilities that resist legacy ERP integration.
Standard Shipping maintains volume dominance, yet Same-Day Delivery climbs fastest as platform service level competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-commerce platforms and third-party logistics providers concentrate procurement decisions in four states that host India's densest fulfillment infrastructure. BIS certification requirements and state-level plastic bans fragment material availability across these jurisdictions.
Maharashtra
Mumbai and Pune corridors drive demand for temperature-stable corrugated containers as quick-commerce platforms expand grocery delivery networks. The state's early enforcement of plastic ban amendments forces polymeric mailer producers toward biodegradable formulation pivots. Bhiwandi's warehousing cluster anchors carton converting capacity serving western India.
Karnataka
Bengaluru's electronics manufacturing corridor generates shock-resistant packaging specifications for consumer devices and components. FSSAI labeling mandates on food delivery packaging push gravure printing upgrades across local converters. The Whitefield logistics zone concentrates same-day delivery fulfillment centers demanding lightweight material specifications.
Telangana
Hyderabad's emerging logistics hub status attracts corrugated converting investments targeting southern India replenishment flows. PLI scheme incentives for specialty substrates redirect capital toward barrier film manufacturing in the state. The Shamshabad air cargo zone supports temperature-controlled pharmaceutical packaging exports.
Tamil Nadu
Chennai's automotive and electronics clusters generate protective packaging demand for fragile component shipments. State-level plastic ban enforcement timelines diverge from neighboring Karnataka, creating inventory stranding risks for multistate suppliers. Sriperumbudur's industrial corridor hosts molded fiber pilot programs displacing expanded polystyrene.
Delhi-NCR
Gurgaon and Noida fulfillment centers lead specification shifts toward right-sized paper-based alternatives reducing dimensional weight charges. Central Pollution Control Board EPR compliance costs concentrate here due to platform headquarters density. The region's courier density supports sub-4-hour delivery promises demanding quarterly packaging specification reviews.
India E-Commerce Packaging Market Competitive Landscape
Player mix skews toward integrated pulp-to-box manufacturers with captive testing laboratories alongside specialized converters and film extrusion specialists. Tier-one positions concentrate with firms controlling BIS certification infrastructure and gravure printing capabilities. Strategic archetypes span integrated food-grade specialists, premium gravure printers, and multilayer film technologists. Competitive moves center on backward integration into pulp processing and rapid formulation pivots responding to state plastic ban fragmentation.
Among integrated manufacturers, Huhtamaki India Ltd represents the pulp-to-box archetype with captive BIS testing infrastructure. TCPL Packaging Ltd and Uflex Limited exemplify specialized positioning—TCPL anchoring gravure printing capabilities for premium brand applications, Uflex occupying multilayer film extrusion technology for tropical climate shelf-life extension. Jindal Poly Films Limited sits within the film substrate tier serving barrier requirements. These four firms illustrate how compliance infrastructure and specialized equipment create defensive positioning against margin compression from certification timeline extension.
| Leading Market Players |
|---|
| Huhtamaki India Ltd |
| TCPL Packaging Ltd |
| Uflex Limited |
| Jindal Poly Films Limited |
| ITC Limited |
| EPL Limited |
| Parksons Packaging Ltd |
| Xolopak |
| Tetra Pak India Pvt. Ltd |
| Others |
Supply & Pricing Matrix
Capacity utilization at Maharashtra and Karnataka corrugated converting clusters anchors price floors across the India e-commerce packaging sector, with 200–350 kPa burst-strength specifications commanding premiums over standard-grade alternatives. Scale economies at integrated pulp-to-box manufacturers compress per-unit costs by 8–12 percentage points against mid-scale converters exposed to imported kraft paper volatility.
Pricing Analysis
Cost-plus contracts with kraft paper indexation dominate procurement between Maharashtra-based food delivery aggregators and integrated carton manufacturers. Price differentiation separates BIS IS 15495-certified food-grade containers from standard corrugated grades, with gravure printing capabilities for FSSAI-mandated labeling commanding additional premiums. Cost compression in polymeric mailers is intensifying because state-level plastic ban fragmentation across Tamil Nadu and Karnataka forces rapid formulation pivots toward biodegradable alternatives. Quick-commerce platforms in Delhi-NCR and Hyderabad demonstrate lowest price sensitivity due to same-day delivery service economics, while Tier-2 city distributors remain most sensitive to per-unit packaging costs.
Supply Chain Analysis
Inventory cycles extending 14–18 weeks for BIS certification at NABL-accredited laboratories strain working capital across mid-scale converters lacking captive testing infrastructure. Geographic supply concentration centers on India for corrugated medium and linerboard, with imported pulp dependency drawing from Indonesia, Brazil, and Canada. Raw material inputs hinge on virgin and recycled kraft grades, multilayer polyethylene films, and agricultural residues for molded fiber alternatives. Single-source vulnerability sits with imported barrier film substrates unable to achieve oxygen transmission rates below 0.5 cc/m²/day for premium spice shipments. Distribution runs through Bhiwandi, Whitefield, and Shamshabad fulfillment corridors serving western, southern, and export markets respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India e-commerce packaging represents an early-cycle expansion story as quick-commerce penetration in grocery and fashion verticals accelerates specification upgrade cycles from annual to quarterly reviews.
For Market Incumbents: Shield margin pools by deepening backward integration into agricultural residue pulping for molded fiber alternatives, eliminating import dependency and state plastic ban exposure. Prioritize captive BIS laboratory investments to compress certification timelines from 18 weeks toward 10 weeks, capturing working capital-constrained competitors. The threat of enzymatic coating technologies achieving cost parity with PE-lined containers demands rapid formulation patent positioning. For New Entrants and Emerging Players: Differentiate on Telangana fulfillment corridor localization, where Hyderabad's emerging logistics hub status offers first-mover advantages for corrugated converting capacity serving southern India replenishment flows. Target quick-commerce grocery platforms in Maharashtra and Karnataka with temperature-stable containers exceeding 250 kPa burst strength, where BIS certification requirements have consolidated supplier bases toward integrated manufacturers. A go-to-market angle anchored in EPR credit monetization with e-commerce platforms lacking recycling infrastructure unlocks compliance-driven procurement relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pulp-to-box manufacturers with captive BIS testing infrastructure and gravure printing capabilities serving premium brand applications. Long-term viability over a 5–10 year window favors firms controlling both barrier film extrusion technology for tropical climate shelf-life extension and molded fiber pilot programs displacing expanded polystyrene in electronics corridors. The signal to watch is PLI scheme incentive disbursement velocity for specialty substrate manufacturing, which will redirect domestic capital toward agricultural residue processing and compress returns for imported-pulp-dependent converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Pulping | Captive bagasse and wheat straw supply eliminates import dependency and state plastic ban exposure for molded fiber containers. |
| Captive BIS Laboratory Investment | In-house IS 15495 certification capability compresses testing timelines and captures working capital-constrained mid-scale competitors. |
| EPR Credit Monetization Partnership | Extended producer responsibility framework compliance trading with e-commerce platforms lacking recycling infrastructure unlocks recurring revenue streams. |
| Gravure Cylinder Engraving Capability Expansion | 175-line screen reproduction capacity addresses pre-press technician scarcity delaying premium fashion and electronics brand onboarding. |
| Quick-Commerce Corrugated Specification Upgrade | Temperature-stable containers exceeding 250 kPa burst strength capture grocery platform procurement consolidation toward integrated manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from corrugated plant managers, quick-commerce supply chain heads, gravure printing pre-press technicians, and Central Pollution Control Board compliance officers and refined through secondary validation. Primary interviews combined with BIS certification records, FSSAI labeling mandate filings, PLI scheme disbursement disclosures, and customs data on imported kraft pulp volumes. Bottom-up capacity assessments at Maharashtra, Karnataka, and Telangana converting facilities triangulated against top-down e-commerce GMV projections across grocery, fashion, and electronics verticals.
Variance decomposition across packaging type, material technology, end-use vertical, and delivery method segmentation dimensions anchored the analytical framework throughout the projection horizon. CAGRs derived from modeled unit economics at quick-commerce fulfillment centers, gravure printing specification upgrade cycles, and biodegradable material cost-parity trajectories. Industry-specific forecast inputs incorporated state-level plastic ban enforcement timelines and BIS certification queue lengths at NABL-accredited laboratories.
Material uncertainties — kraft paper currency fluctuation cycles, state plastic ban enforcement divergence, and barrier film oxygen transmission rate breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions on PLI scheme incentive continuity and quick-commerce platform service level competition intensity. Revision becomes warranted when BIS certification timeline compression or enzymatic coating cost-parity achievement crosses thresholds that restructure competitive access patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Airless Packaging Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Panel Level Packaging Market