
 Anti-Counterfeit Clothing Packaging Market | 2026-2036
Anti-Counterfeit Clothing Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Counterfeit Clothing Packaging Market Outlook
Software-defined authentication is decoupling physical packaging from verification value, turning tags into subscription-managed data endpoints. Avery Dennison Corporation leverages connected-product platforms to extend its influence beyond label manufacturing into cloud-based traceability. 3M Company anchors its position through advanced optical film technologies that resist replication at scale. Zebra Technologies Corporation competes by integrating RFID hardware with enterprise software for real-time inventory authentication.
Anti-counterfeit clothing packaging encompasses tamper-evident and traceable enclosures—incorporating holographic substrates, serialized QR matrices, and near-field communication inlays—designed to verify garment authenticity from factory floor to point of sale. Manufacturing employs hot-stamping for holograms and semiconductor bonding for NFC chips, with read-range and environmental durability as critical performance parameters. Hologram-based tags retain dominance in luxury segments where visual verification carries brand weight, while RFID-enabled labels represent the fastest-expanding technology category as apparel manufacturers automate supply-chain tracking. E-commerce platforms now drive disproportionate demand growth for tamper-evident pouches that protect against return fraud and substitution during last-mile delivery.
The EU Green Deal and Digital Product Passport framework mandate granular material disclosure and chain-of-custody documentation, compelling packaging suppliers to embed traceability at the substrate level. REACH compliance restricts certain adhesive chemistries used in label bonding, redirecting R&D toward bio-based alternatives that maintain tamper-evidence performance. Stakeholders must decide whether to build in-house authentication-cloud capabilities or partner with specialized platform providers before regulatory deadlines harden competitive barriers.
Market Dynamics
The EU Digital Product Passport initiative is compressing adoption timelines across apparel supply chains, forcing packaging converters to embed serialized traceability at the substrate level rather than treating authentication as an add-on label function.
Growth Catalysts
- REACH compliance deadlines:ECHA restrictions on conventional adhesive chemistries are accelerating R&D investment in bio-based tamper-evidence formulations that maintain bond strength under variable humidity.
- E-commerce return fraud:Online apparel retailers in Germany and France are mandating tamper-evident pouches for high-value shipments to block wardrobing and substitution schemes.
- NFC semiconductor bonding:Automated semiconductor attachment lines are reducing unit costs for RFID-enabled labels, enabling mid-market denim and activewear brands to adopt serialized tracking.
Market Restraints
- Optical film supply concentration:Holographic substrate production clusters in South Korea and Japan, exposing converters to freight cost volatility and currency fluctuation risk.
- Hot-stamping equipment capex:Precision hologram application requires vacuum metallization lines costing substantially more than conventional flexographic presses, limiting supplier entry.
- Adhesive chemistry restrictions:REACH Annex XVII limitations on certain solvent-based bonding agents force reformulation cycles that extend qualification timelines by 8-14 months.
Strategic Opportunities
- Italian luxury leather goods:Tuscan manufacturers remain underpenetrated by cloud-connected authentication platforms, presenting first-mover advantage for integrated hardware-software providers.
- Blockchain-NFC convergence:Combining near-field communication inlays with distributed ledger verification creates immutable chain-of-custody records for vintage and resale markets.
- Direct-to-consumer authentication apps:Brand-owned mobile verification interfaces bypass third-party platform fees while capturing first-party consumer behavior data.
Industry Challenges
- Semiconductor packaging engineering talent:The intersection of RFID antenna design, environmental durability testing, and apparel workflow integration requires hybrid skill sets in short supply across European packaging hubs.
- Legacy ERP integration:Enterprise resource planning systems at established apparel manufacturers lack native serialization modules, forcing middleware development for track-and-trace data handoffs.
- Multi-jurisdiction certification sequencing:Labels requiring both ECHA REACH compliance and CE marking for electronic components face overlapping but non-identical documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Counterfeit Clothing Packaging Market |
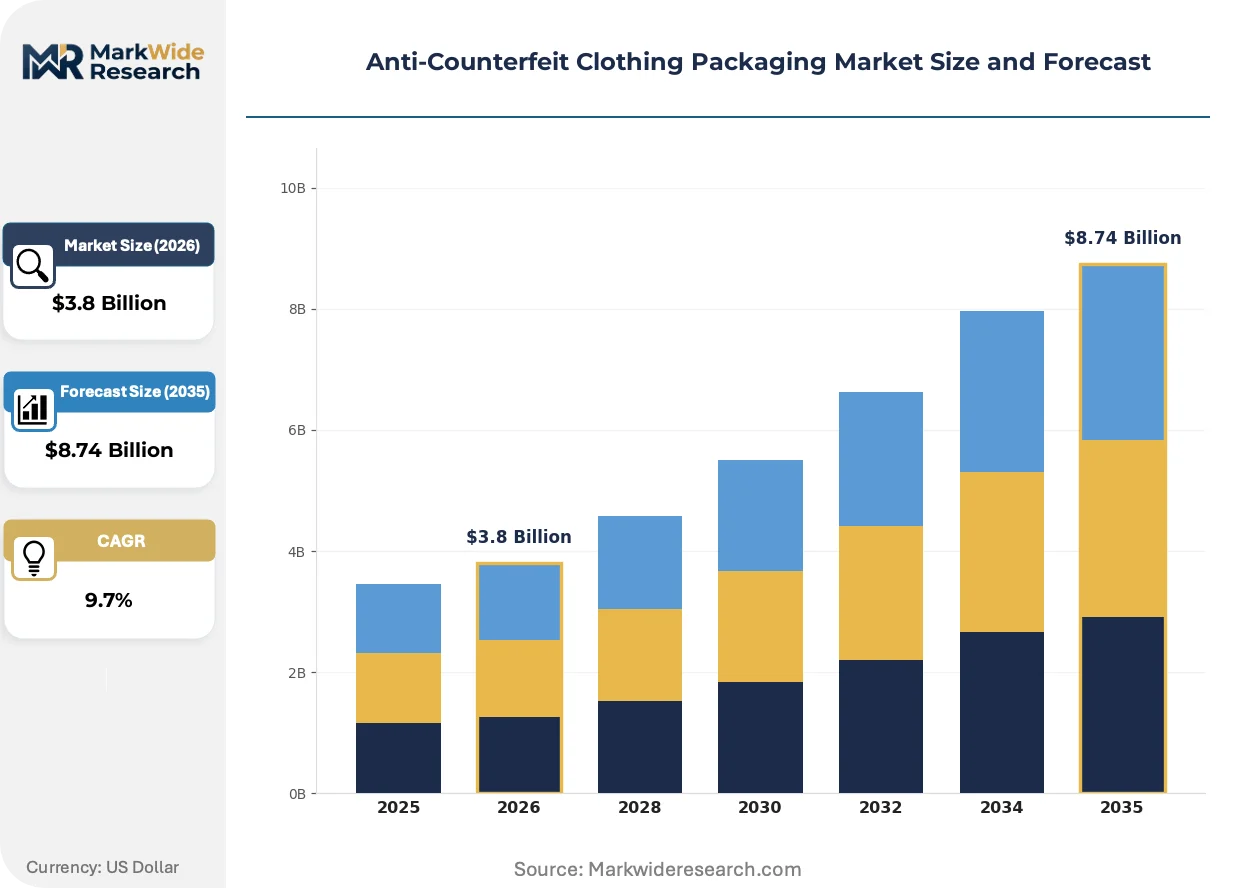
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tags, Labels, Stickers, Pouches Technology: QR Codes, RFID, Holograms, NFC End User: Apparel Manufacturers, Retailers, E-commerce Platforms, Wholesalers Packaging Material: Plastic, Paper, Cardboard, Composite |
| Companies Covered | Avery Dennison Corporation, 3M Company, Zebra Technologies Corporation, CCL Industries Inc., SATO Holdings Corporation, SICPA Holding SA, Authentix Inc., De La Rue, Holostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Counterfeit Clothing Packaging Market Strategic Shifts
Authentication hardware is dissolving into software-managed data layers, with physical tags becoming interchangeable endpoints for cloud-based verification platforms rather than fixed security features.
Serialized QR matrices paired with AI-generated unique visual fingerprints are absorbing verification workload from dedicated hardware readers. Fast-fashion retailers in Spain and Poland are deploying these at carton level to enable consumer-grade authentication without NFC-enabled smartphones. The technology is absorbing margin from holographic suppliers by collapsing the cost differential between visible and covert security features.
EU Green Deal implementation through the Digital Product Passport framework mandates granular material disclosure and chain-of-custody documentation. Packaging converters must now embed traceability metadata at the substrate manufacturing stage rather than applying labels post-production. French and Italian luxury houses are responding by qualifying suppliers with integrated cloud-platform capabilities before substrate procurement contracts renew.
Brand procurement teams are consolidating authentication spend with packaging suppliers offering integrated hardware-software-substrate bundles. This displaces the previous model of separate vendor relationships for holograms, RFID inlays, and verification platforms. German sporting goods manufacturers are most advanced in this consolidation, using authentication procurement as leverage for broader packaging category management.
Anti-Counterfeit Clothing Packaging Market Segmentation
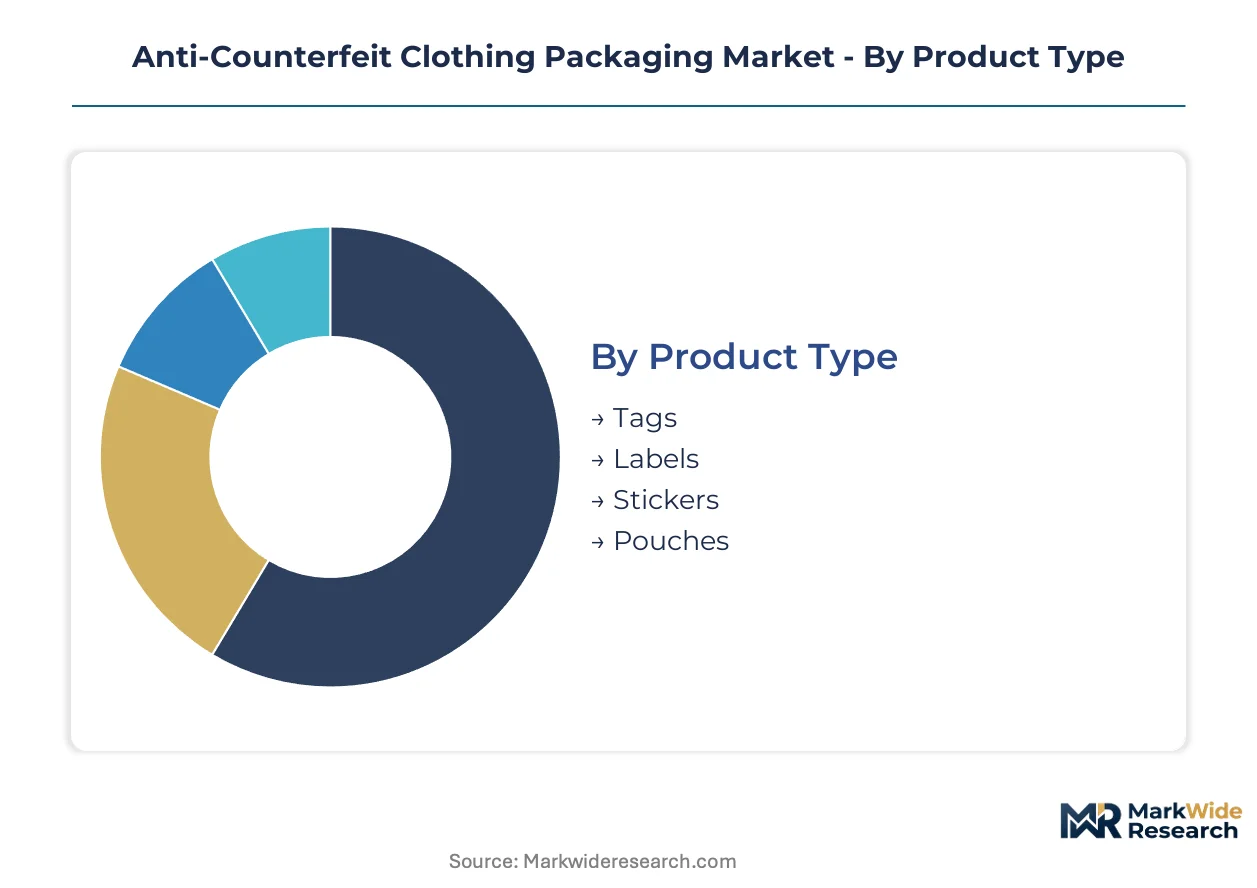
Anti-counterfeit clothing packaging segments along four intersecting dimensions that determine both technical specification and procurement economics. Technology choices lock in manufacturing partnerships, while end-user channel dictates volume scale and margin structure. Material selection increasingly carries compliance weight under EU substrate disclosure rules.
Product Type:
Supply concentration among holographic substrate producers in South Korea and Japan directly shapes converter economics across tag and label categories, with equipment-intensive formats commanding premium positioning.
- Tags:Suspended garment attachments incorporating serialized QR matrices or NFC inlays for consumer-facing verification. Italian luxury houses in Milan and Florence are consolidating tag procurement with integrated hardware-software providers ahead of Digital Product Passport deadlines. Demand concentrates in high-value leather goods where visual authentication carries brand equity weight.
- Labels:Adhesive-backed substrates applied directly to garments or packaging, spanning holographic security films to RFID-enabled woven constructions. German sporting goods manufacturers are driving fastest adoption of RFID-integrated labels for automated inventory authentication across their European retail networks. REACH-compliant adhesive reformulation is extending qualification timelines by 8-14 months.
- Stickers:Pressure-sensitive authentication markers for secondary verification points on packaging or care labels. Spanish fast-fashion retailers deploy these at carton level for consumer-grade authentication without dedicated hardware.
- Pouches:Tamper-evident enclosures protecting garments during last-mile delivery, incorporating void-release adhesives and tear-indicating films. E-commerce platforms in France mandate these for high-value shipments to block wardrobing fraud.
Today's leader: Labels. Tomorrow's challenger: Pouches.
Technology:
Cost tiers separate hardware-dependent verification from software-managed authentication, with semiconductor-based formats carrying higher unit economics but collapsing in price through automated bonding lines.
- QR Codes:Serialized matrix patterns paired with AI-generated unique visual fingerprints, readable by standard smartphones without dedicated hardware. Polish and Spanish retailers are absorbing verification workload from holographic suppliers by deploying these at scale. The technology is collapsing cost differentials between visible and covert security features.
- RFID:Radio-frequency identification inlays enabling non-line-of-sight tracking and automated inventory authentication. German apparel manufacturers are expanding fastest into serialized RFID adoption for supply-chain automation. Automated semiconductor attachment lines are reducing unit costs and enabling mid-market brand adoption.
- Holograms:Optical diffraction substrates produced through vacuum metallization and embossing, offering visual verification without electronic components. Hot-stamping equipment capex requirements limit supplier entry and maintain margin concentration among established converters.
- NFC:Near-field communication chips enabling encrypted, smartphone-tap verification with cloud-based authentication. Blockchain-NFC convergence is creating immutable chain-of-custody records for vintage and resale markets.
Today's leader: Holograms. Tomorrow's challenger: RFID.
End User:
Application requirements diverge sharply between manufacturing-stage integration and point-of-sale deployment, with channel-specific fraud vectors driving format selection.
- Apparel Manufacturers:Brand owners embedding authentication at production origin, requiring substrate-level traceability integration. Tuscan leather goods manufacturers remain underpenetrated by cloud-connected platforms.
- Retailers:Multi-brand and flagship stores demanding inventory authentication and consumer verification touchpoints. German sporting goods retailers are most advanced in consolidating authentication spend with integrated suppliers.
- E-commerce Platforms:Online marketplaces mandating tamper-evident packaging to combat return fraud and substitution schemes. French platforms are driving disproportionate demand growth for serialized pouches.
- Wholesalers:Distribution intermediaries requiring bulk authentication for B2B chain-of-custody documentation. Legacy ERP integration challenges are forcing middleware development for track-and-trace data handoffs.
Today's leader: Apparel Manufacturers. Tomorrow's challenger: E-commerce Platforms.
Packaging Material:
Customer type stratification separates premium substrate providers from commodity converters, with EU Green Deal disclosure rules elevating material provenance to competitive differentiator status.
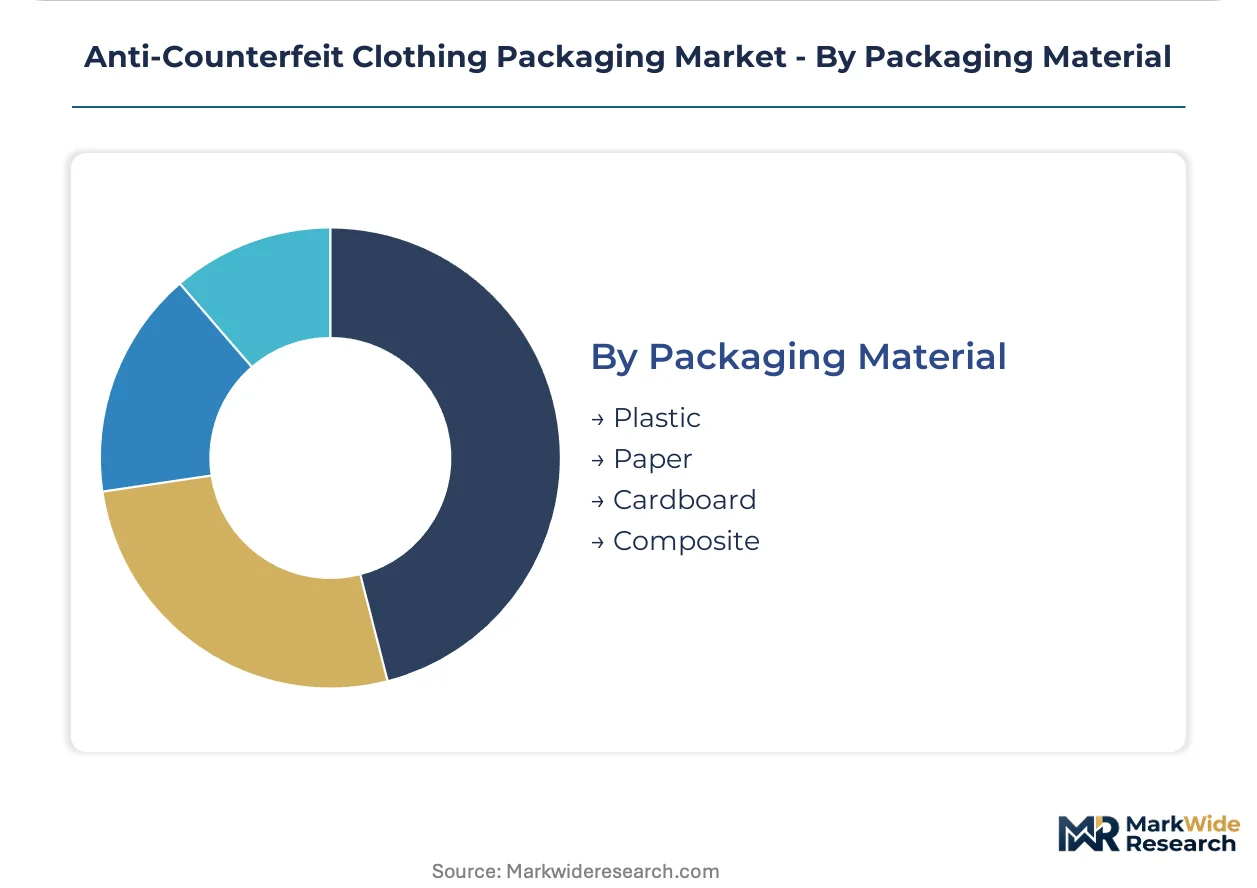
- Plastic:Polymer films and laminates offering durability and moisture resistance for RFID inlay protection. ECHA restrictions on conventional adhesive chemistries are redirecting R&D toward bio-based bonding alternatives.
- Paper:Cellulosic substrates with integrated security fibers and watermarks for holographic and QR code applications. French luxury houses are qualifying paper suppliers with integrated cloud-platform capabilities.
- Cardboard:Rigid board constructions for secondary packaging authentication and carton-level serialization. Polish fast-fashion retailers deploy serialized QR matrices on cardboard for cost-effective verification.
- Composite:Multi-layer constructions combining barrier properties with authentication features, such as metallized films bonded to paper cores. REACH Annex XVII compliance is extending qualification timelines for solvent-based bonding agents.
Today's leader: Plastic. Tomorrow's challenger: Paper.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate authentication substrate fabrication toward jurisdictions with lower cost-of-compliance structures. The EU Digital Product Passport framework imposes the strictest traceability mandates, creating divergence between European converter economics and Asian manufacturing alternatives.
Germany
E-commerce return fraud and automated inventory authentication drive German demand for RFID-enabled labels and tamper-evident pouches. ECHA REACH Annex XVII restrictions on solvent-based adhesives extend supplier qualification timelines by 8-14 months. Bavarian sporting goods manufacturers consolidate authentication procurement with integrated hardware-software providers.
France
French luxury houses mandate cloud-connected verification platforms ahead of Digital Product Passport deadlines. ANSM and CNIL oversight of consumer data handling shapes NFC authentication app deployment. Paris-based leather goods brands qualify paper substrate suppliers with integrated traceability capabilities before contract renewals.
Italy
Tuscan leather goods manufacturers remain underpenetrated by serialized authentication platforms, creating first-mover opportunities for integrated providers. EU Green Deal substrate disclosure rules elevate material provenance requirements. Milan and Florence luxury houses consolidate tag procurement with cloud-platform-integrated suppliers.
United States
FDA and FTC enforcement against counterfeit apparel imports elevates brand investment in verification infrastructure. California and New York Metro e-commerce platforms drive demand for tamper-evident pouches blocking wardrobing fraud. Pacific Northwest technology retailers deploy NFC-enabled authentication for resale market verification.
China
Domestic apparel manufacturers adopt serialized QR matrices for cost-effective consumer-grade authentication. MIIT and SAMR oversight of electronic component standards shapes RFID inlay import requirements. Yangtze River Delta packaging converters expand holographic substrate production for European luxury brand supply chains.
Anti-Counterfeit Clothing Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing premium positioning in luxury apparel while commodity converters serve high-volume fast-fashion procurement. Market structure tilts toward consolidation among holographic substrate producers due to vacuum metallization equipment barriers, while RFID label assembly remains fragmented across automated bonding line operators. Three archetypes dominate: optical security specialists with captive film production, connected-product platform operators bundling hardware-software-substrate offerings, and regional contract converters serving mid-market denim and activewear brands. Competitive moves center on strategic partnerships for cloud-platform integration and backward integration into semiconductor attachment capabilities.
Within the connected-product platform tier, Avery Dennison Corporation exemplifies the hardware-software bundling archetype, while 3M Company anchors the optical security specialist position through advanced film technologies. Zebra Technologies Corporation occupies a position bridging RFID hardware integration with enterprise software deployment. These three represent the dominant competitive vectors shaping procurement consolidation patterns across European and North American apparel supply chains.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M Company |
| Zebra Technologies Corporation |
| CCL Industries Inc. |
| SATO Holdings Corporation |
| SICPA Holding SA |
| Authentix Inc. |
| De La Rue |
| Holostik |
| Others |
Value Chain & Pricing Dynamics
EU Digital Product Passport mandates for serialized substrate traceability are compressing procurement timelines and forcing apparel brands to absorb premium qualification costs from integrated hardware-software suppliers. This demand-side specification tightening grants pricing power to converters with captive cloud-platform capabilities while squeezing commodity label assemblers.
Pricing Analysis
Distributor margins on holographic substrates absorb freight volatility from South Korean and Japanese optical film producers. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected NFC-enabled labels from basic QR matrix tags and commodity hologram stickers. Price differentiation hinges on REACH-compliant adhesive certification and semiconductor bonding automation depth. Cost compression in economy-tier QR deployments is intensifying because Polish and Spanish fast-fashion retailers are absorbing verification workload from hardware-dependent formats. E-commerce platforms remain least price-sensitive due to wardrobing fraud exposure.
Supply Chain Analysis
Ocean freight rate fluctuations on Asia-Europe routes directly impact holographic substrate landed costs for European converters. Supply concentrates in South Korea and Japan for optical diffraction films, Germany and Italy for precision hot-stamping equipment, and China for semiconductor inlay assembly. Raw material dependencies span metallized PET films, NFC antenna substrates, and bio-based adhesive polymers. Single-source vulnerability in vacuum metallization equipment exposes converters to 8-14 month lead time extensions. Distribution runs through brand-direct procurement consolidation rather than fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Anti-Counterfeit Clothing Packaging Market functions as a stable compounder, with regulatory mandates for Digital Product Passports creating irreversible demand for serialized traceability infrastructure across European apparel supply chains.
For Market Incumbents: Deploy cloud-platform integration capabilities to defend against hardware-commoditization pressure from AI-generated QR matrices. Capture Tuscan leather goods manufacturers through substrate-level traceability partnerships before contract renewal cycles complete. Cement relationships with German sporting goods brands by consolidating authentication spend into integrated hardware-software-substrate bundles. For New Entrants and Emerging Players: Launch via direct-to-consumer authentication app development for mid-market denim and activewear brands seeking first-party data capture. Target Italian luxury leather goods manufacturers in Milan and Florence, where cloud-connected platform penetration remains underdeveloped. Enter through blockchain-NFC convergence for vintage and resale market verification, bypassing established holographic supplier relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with connected-product platform operators possessing captive semiconductor attachment capabilities and REACH-compliant adhesive formulation expertise. Five-to-ten year viability rests on regulatory deadline enforcement rather than discretionary brand marketing budgets. Watch for E-commerce platform mandates on tamper-evident pouches as inflection signal for mid-market RFID adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Platform Integration | Extends converter influence beyond label manufacturing into subscription-managed authentication services for EU Digital Product Passport compliance. |
| Semiconductor Attachment Capacity | Captures margin from automated NFC inlay production as mid-market brands adopt serialized tracking for supply-chain automation. |
| Bio-Based Adhesive Reformulation | Secures REACH Annex XVII compliance for tamper-evidence bonding without 8-14 month qualification timeline penalties. |
| Direct-to-Consumer App Development | Bypasses third-party platform fees while capturing first-party consumer behavior data for French and Italian luxury houses. |
| Blockchain-NFC Convergence | Creates immutable chain-of-custody records for vintage and resale markets, opening new revenue streams beyond primary garment sales. |
Study Parameters
Coverage spans Germany, France, Italy, the United States, and China, with primary inputs from each market informing demand-side validation. Interviews with packaging procurement directors at apparel manufacturers, authentication technology R&D leads, E-commerce platform supply chain managers, and regulatory compliance officers combined with secondary sources including ECHA REACH filings, EU Digital Product Passport framework documents, SEC 10-K disclosures from listed packaging converters, and customs trade data for holographic substrate flows. Bottom-up volume modeling triangulated against top-down market sizing from industry association aggregates.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion through technology mix shifts and premium format adoption. Segmentation dimensions modeled include product type, authentication technology, end-user channel, packaging material substrate, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to E-commerce penetration rates and Digital Product Passport implementation timelines. Industry-specific inputs incorporated semiconductor bonding cost decline trajectories and bio-based adhesive qualification success rates.
Several conditions sit outside the modeled scope, including potential delays in EU Digital Product Passport enforcement, breakthroughs in AI-generated authentication eliminating hardware dependencies, and trade policy disruptions affecting South Korean optical film exports. Forecasts reflect assumptions about regulatory deadline adherence and technology cost curves. Stakeholders should weight assumptions against their own operating context and supply chain exposure to REACH compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Patisserie Packaging Market