
 Europe Modified Atmosphere Packaging Market | 2026-2036
Europe Modified Atmosphere Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Modified Atmosphere Packaging Market Foresight
Market Context
The EU Packaging and Packaging Waste Regulation is broadening the cost-of-entry calculus for substrate suppliers across Europe. Amcor Plc leverages its continental manufacturing footprint to navigate evolving compliance tiers. Mondi Group anchors its position through vertically integrated paper-based barrier solutions. Sealed Air Corporation differentiates via proprietary equipment-film bundled offerings that lock in processor loyalty.
Technical Definition and Segment Structure
Modified Atmosphere Packaging refers to the technique of altering the gaseous composition inside a sealed package—typically substituting ambient air with calibrated blends of nitrogen, carbon dioxide, and oxygen—to retard microbial proliferation and oxidative degradation of perishable goods. Flexible packaging dominates European volume due to its compatibility with high-speed form-fill-seal equipment and lower material intensity versus rigid alternatives. Gas flushing technology leads installed capacity, though active packaging segments incorporating oxygen scavengers and moisture regulators are capturing margin pools in premium pharmaceutical and ready-to-eat meal applications. Polyethylene retains the largest material share, yet polypropylene is displacing it in retort-compatible and extended-shelf-life formats where thermal resistance commands price premiums.
Regulatory Framework
EMA, EFSA, and REACH collectively govern material safety, migration limits, and chemical compliance for MAP substrates contacting food and pharmaceutical products across Europe. EFSA's ongoing evaluations of recycled content thresholds in food-contact materials are forcing converters to validate new barrier constructions. Stakeholders must monitor how the EU Green Deal's packaging minimization mandates interact with national extended producer responsibility schemes to determine whether lightweighting or reuse infrastructure delivers superior compliance economics.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing substrate choice sets across European food processors, forcing simultaneous investments in barrier performance and recyclability compliance that reshape converter-processor contracting terms.
Growth Catalysts
- EU Green Deal packaging minimization mandates:Germany's meat processing corridor is retrofitting automated lines with inline gas analysis to meet dual sustainability and shelf-life targets.
- Fresh produce retail chain expansion:French and Dutch supermarket networks are standardizing MAP specifications to reduce food waste metrics reported under CSRD disclosure rules.
- High-barrier paper substrates:Fiber-based barrier solutions are capturing volume from multilayer plastics in ready-to-eat meal segments where EFSA migration limits favor non-petroleum contact layers.
Market Restraints
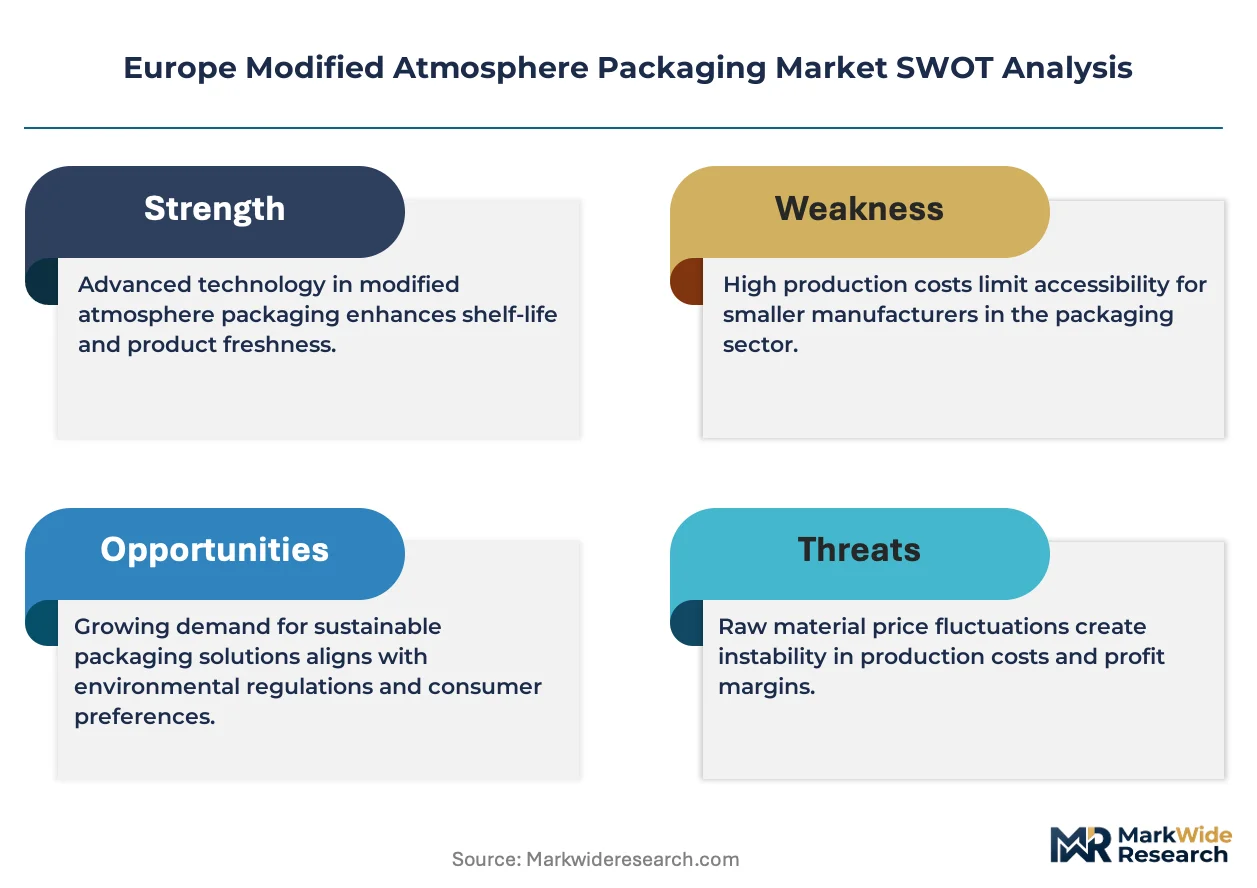
- Ethylene and propylene feedstock volatility:Polyolefin price swings compress converter margins and complicate long-term pricing contracts with protein processors.
- Barrier coating supply concentration:Specialized EVOH and PVDC resin production clusters in Belgium and Germany create single-source exposure for continental film extruders.
- Retort-compatibility limitations:Current bio-based barrier constructions fail thermal stability thresholds required for ambient-stable prepared meals, locking out sustainable alternatives.
Strategic Opportunities
- Poland and Romania fresh protein modernization:Underpenetrated Central European processing capacity offers first-mover positioning as retail consolidation accelerates MAP specification adoption.
- Active packaging convergence:Oxygen scavenger integration with intelligent freshness indicators creates premium positioning in pharmaceutical cold chain applications.
- Extended producer responsibility alignment:France's national EPR scheme rewards mono-material PP constructions, incentivizing equipment upgrades that accept simplified substrate portfolios.
Industry Challenges
- Gas analysis technician scarcity:Inline QA systems require specialized calibration expertise that outpaces vocational training output in Eastern European packaging hubs.
- Legacy form-fill-seal retrofit complexity:Older Dutch and Danish installed bases face mechanical incompatibility with thinner-gauge films demanded by lightweighting targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Modified Atmosphere Packaging Market |
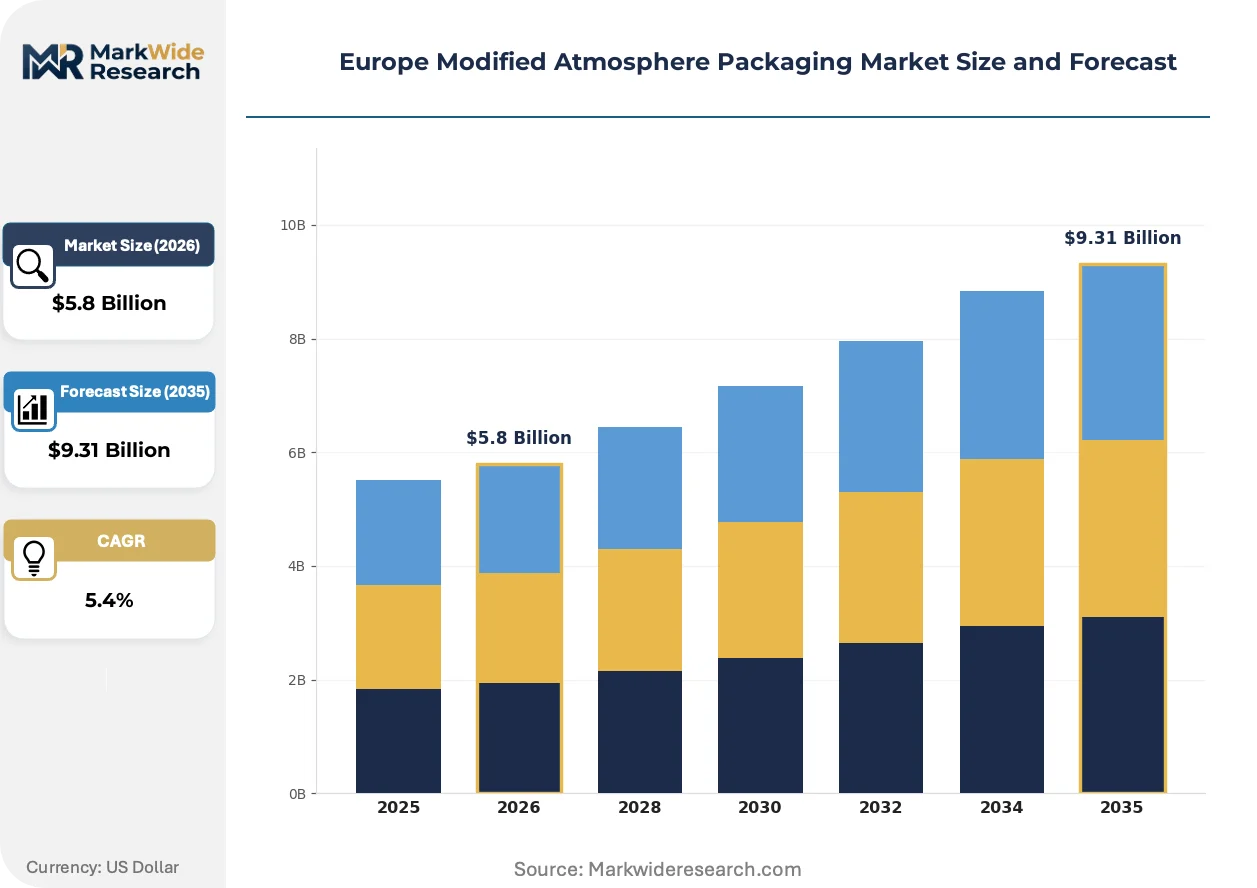
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Bags, Containers Material: Polyethylene, Polypropylene, Paper, Aluminum End User: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Technology: Gas Flushing, Vacuum Packaging, Active Packaging, Barrier Packaging |
| Companies Covered | Air Products and Chemicals, ProAmpac, Amcor Plc, Linde AG, Graphic Packaging International, Mondi Group, Winpak Ltd, Berry Global, Sealed Air Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Modified Atmosphere Packaging Market Shifts & Advancements
Inline sensing and substrate simplification are compressing the traditional separation between packaging equipment and materials suppliers, creating bundled procurement patterns that favor integrated solution architectures over component sourcing.
Laser-based headspace gas analysis is automating quality assurance throughput in German meatpacking facilities, where processors are adopting real-time CO2 and O2 verification to replace batch-based laboratory testing. This shift is automating compliance documentation for EFSA-registered establishments while reducing manual sampling labor by enabling continuous seal integrity verification at line speeds exceeding 200 units per minute.
REACH substance restriction evaluations are accelerating substitution timelines for per- and polyfluoroalkyl substances in barrier coatings, forcing converters to validate silicone- and clay-based alternatives ahead of formal authorization deadlines. Protein processors in the Netherlands are responding by qualifying new film constructions through accelerated shelf-life protocols that compress traditional 18-month validation cycles.
Retail procurement consolidation is concentrating specification authority among German and French buying cooperatives, displacing decentralized plant-level packaging decisions with centralized category management. This concentration is compressing supplier rosters and mandating pan-European service capabilities that smaller regional converters cannot sustain without distribution partnerships.
Europe Modified Atmosphere Packaging Market Segmentation
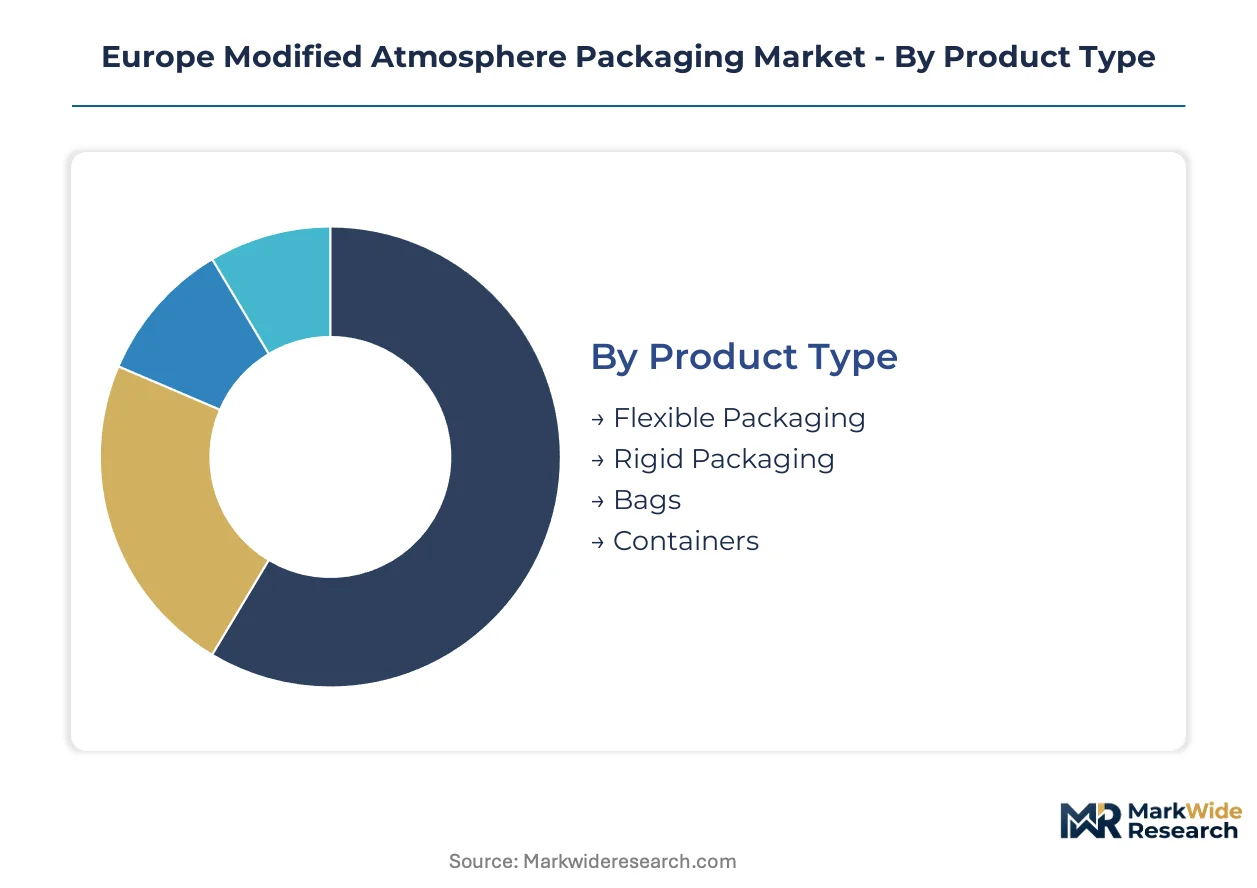
Segmentation in the Europe Modified Atmosphere Packaging Market reveals how substrate specifications diverge across protein processors, pharmaceutical cold chains, and fresh produce retail networks. Equipment compatibility, barrier performance tiers, and recyclability compliance create distinct procurement clusters that reshape converter-processor contracting dynamics.
Product Type:
Customization concentrates in high-speed automated lines across Germany's meat processing corridor, while standardization dominates manual packing stations in smaller Central European facilities.
- Flexible Packaging:Polyethylene and polypropylene films dominate high-speed form-fill-seal operations across Dutch and Danish protein processing plants. German retail chains specify mono-material PP constructions to align with France's EPR scheme incentives for recyclability compliance.
- Rigid Packaging:Thermoformed trays and lidded containers serve premium ready-to-eat meal segments where shelf-life extension justifies higher material intensity. French supermarket networks are standardizing rigid specifications to reduce food waste metrics reported under CSRD disclosure rules.
- Bags:Vertical form-fill-seal compatible pouches capture volume in fresh produce applications across Netherlands retail consolidation.
- Containers:Injection-molded and thermoformed rigid formats serve prepared meal segments requiring retort compatibility in Belgium and Germany.
Leading the category by volume: Flexible Packaging. Growing fastest: Rigid Packaging.
Material:
Cost tiers separate commodity polyolefins from premium barrier substrates, with paper-based solutions commanding margin premiums in EFSA-constrained food-contact applications.
- Polyethylene:Retains the largest material share across European volume, though thermal limitations restrict penetration in retort-compatible formats. Polyolefin price swings compress converter margins and complicate long-term pricing contracts with protein processors.
- Polypropylene:Displacing polyethylene in extended-shelf-life formats where thermal resistance commands price premiums. France's national EPR scheme rewards mono-material PP constructions, incentivizing equipment upgrades that accept simplified substrate portfolios.
- Paper:Fiber-based barrier solutions capture volume from multilayer plastics in ready-to-eat meal segments where EFSA migration limits favor non-petroleum contact layers.
- Aluminum:Ultra-high-barrier foils serve pharmaceutical cold chain applications requiring absolute oxygen and moisture exclusion.
Highest volume concentration: Polyethylene. Steepest expansion trajectory: Polypropylene.
End User:
Application maturity separates established food processing specifications from emerging pharmaceutical and electronics requirements that demand validated barrier performance documentation.
- Food & Beverage:Protein processors, fresh produce distributors, and ready-to-eal meal manufacturers constitute the demand core across German, French, and Dutch retail networks. Fresh produce retail chains across Germany, France, and the Netherlands are expanding MAP adoption to combat food waste.
- Pharmaceuticals:Oxygen scavenger integration with intelligent freshness indicators creates premium positioning in cold chain applications where EMA stability requirements govern packaging validation.
- Electronics:Moisture-sensitive component protection drives barrier specifications in semiconductor and precision instrument distribution.
- Consumer Goods:Cosmetic and personal care applications adopt MAP for oxidation-sensitive formulations in premium positioning segments.
Dominant demand source: Food & Beverage. Climbing the fastest: Pharmaceuticals.
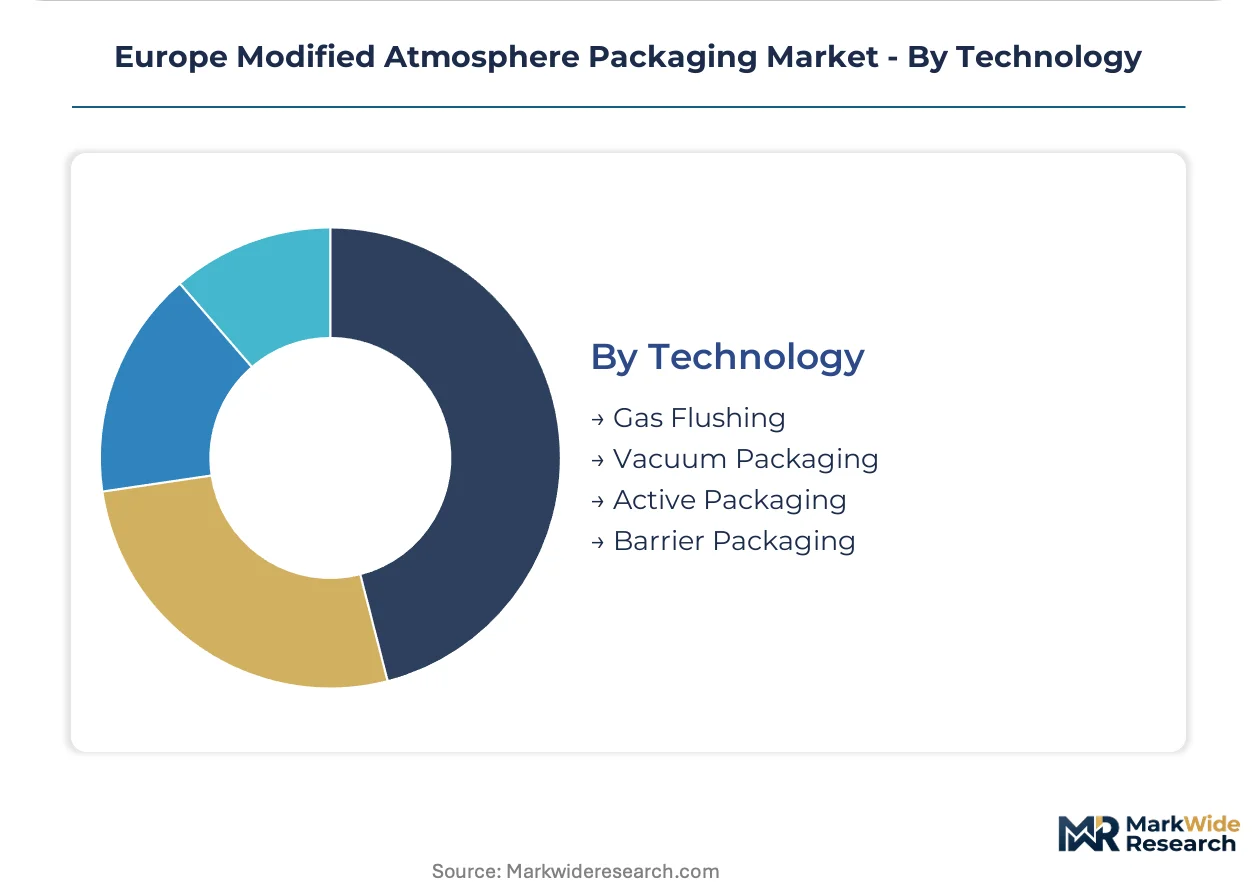
Technology:
Supply concentration clusters gas flushing equipment manufacturers in Germany and Italy, while active packaging innovation concentrates in Belgian and Dutch specialty chemical converters.
- Gas Flushing:Nitrogen and carbon dioxide displacement systems lead installed capacity across European protein processing. German meatpacking facilities are adopting laser-based headspace gas analysis to automate quality assurance throughput and enable continuous seal integrity verification.
- Vacuum Packaging:Complete oxygen exclusion serves cured meat and hard cheese segments where anaerobic preservation extends shelf life without gas mixture complexity.
- Active Packaging:Oxygen scavengers and moisture regulators capture margin pools in premium pharmaceutical and ready-to-eat meal applications. Active packaging segments incorporating these features are capturing margin pools in premium pharmaceutical and ready-to-eat meal applications.
- Barrier Packaging:Multi-layer coextrusions and metallized films provide passive protection without active agent integration.
Widest installed base: Gas Flushing. Gaining share fastest: Active Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across Central and Eastern Europe are concentrating MAP equipment investments through tax-incentive programs targeting food processing modernization. The EU Green Deal's packaging mandates are reshaping substrate specifications from Iberia to the Baltics.
Germany
Meat processing automation drives demand for inline gas analysis systems across Bavaria and North Rhine-Westphalia. EFSA migration limit evaluations are forcing converters to validate new barrier constructions ahead of formal deadlines. Stuttgart's packaging machinery cluster hosts laser-based headspace verification equipment manufacturers serving pan-European protein processors.
France
Retail buying cooperatives are centralizing MAP specifications to reduce food waste metrics reported under CSRD disclosure rules. The national extended producer responsibility scheme rewards mono-material polypropylene constructions with preferential fee structures. Lyon and Paris basin converters are upgrading extrusion lines to meet centralized supermarket chain procurement standards.
Netherlands
Fresh produce distribution networks are standardizing MAP adoption to combat spoilage in Rotterdam's port-centric logistics hub. REACH substance restriction timelines are accelerating substitution away from fluorinated barrier coatings. Eindhoven's equipment manufacturers are shipping gas flushing systems to underpenetrated Central European markets.
Poland
Protein processing modernization programs are attracting MAP equipment vendors to Warsaw and Krakow industrial zones. EU structural funds are co-financing packaging line automation in meatpacking facilities. Poznan's converter base is expanding capacity to supply German retail chains with simplified substrate portfolios.
Belgium
Specialized EVOH and PVDC resin production clusters create single-source exposure for continental film extruders seeking barrier coating supply security. The Flanders packaging research corridor is validating silicone-based alternatives to perfluorinated substances. Antwerp's chemical industry concentration supports rapid prototyping of new multilayer constructions.
Europe Modified Atmosphere Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate, equipment, and gas supply verticals. Market structure tilts toward consolidation at the materials layer while equipment manufacturing retains fragmentation. Three archetypes dominate: integrated packaging-converter conglomerates, industrial gas suppliers with bundled equipment offerings, and specialized film extruders with regional service footprints. Capacity expansion and strategic partnerships constitute the primary competitive vectors as processors demand pan-European service capabilities.
Among Australia-based multinational packaging groups, Amcor Plc occupies a position exemplifying continental manufacturing footprint scale. Austrian-headquartered Mondi Group represents vertically integrated paper-based barrier specialization. North Carolina-incorporated Sealed Air Corporation anchors the equipment-film bundled offering archetype that locks in processor loyalty through integrated solution architectures.
| Leading Market Players |
|---|
| Air Products and Chemicals |
| ProAmpac |
| Amcor Plc |
| Linde AG |
| Graphic Packaging International |
| Mondi Group |
| Winpak Ltd |
| Berry Global |
| Sealed Air Corporation |
| Others |
Supply & Pricing Matrix
The EU Green Deal's packaging minimization mandates gate qualified supply and premium-tier pricing access across European MAP substrate markets. Processors seeking EFSA-compliant barrier constructions face extended qualification timelines that compress spot inventory availability and widen price spreads between certified and uncertified supply tiers.
Pricing Analysis
Short lead-time premiums dominate pricing dynamics as German meat processors pay substantial markups for validated mono-material PP films available within compressed delivery windows. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-registered barrier substrates from commodity polyolefins and spot-import alternatives. Price differentiation hinges on migration limit certification status and volume commitment scale, with Dutch retail cooperatives leveraging consolidated procurement to extract standard-tier pricing at premium-tier volumes. Cost compression in commodity polyethylene runs through volatile ethylene feedstock exposure, while protein processors in Central Europe exhibit highest price sensitivity due to limited specification authority.
Supply Chain Analysis
Workforce availability constraints in Belgium and Germany's chemical manufacturing corridors limit EVOH and PVDC resin production expansion despite surging barrier coating demand. Supply concentrates in German extrusion clusters, Belgian specialty chemical production, and Dutch equipment manufacturing hubs that feed continental processor networks. Raw material dependencies on ethylene and propylene feedstocks, metallized film substrates, and laser-based gas analysis components create multi-point exposure. Single-source vulnerability in barrier coating supply chains amplifies disruption risk from REACH substance restriction timelines. Distribution runs through Rotterdam's port-centric logistics hub and overland freight networks serving Bavaria and Paris basin processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European MAP markets represent a consolidation play as EU Packaging and Packaging Waste Regulation compliance costs force sub-scale converters toward acquisition or exit. Retail procurement centralization accelerates this pressure by mandating pan-European service capabilities.
For Market Incumbents: Anticipate REACH substance restriction deadlines by accelerating silicone-based barrier coating validation ahead of formal authorization timelines. Acquire specialized EVOH resin production capacity in Belgium or Germany to secure supply chain control against single-source exposure. Capture stranded Central European processor relationships as retail consolidation displaces regional converters lacking distribution partnerships.
For New Entrants and Emerging Players: Launch via equipment-film bundled offerings targeting Poland and Romania's underpenetrated protein processing modernization programs. Penetrate the pharmaceutical cold chain segment where oxygen scavenger integration with intelligent freshness indicators commands premium positioning and lower incumbent concentration. Qualify paper-based barrier solutions for French ready-to-eat meal specifications where EFSA migration limits favor non-petroleum contact layers.
For Investors and Strategic Acquirers: France's national EPR scheme fee restructuring is the leading indicator that mono-material PP substrate specialists will command acquisition premiums as equipment upgrade cycles synchronize with simplified portfolio demand. Five-to-ten year viability favors converters with backward integration into resin production or captive barrier coating supply. Watch for laser-based headspace gas analysis equipment manufacturers achieving scale in German meatpacking facilities as the signal that inline QA automation is crossing from early adoption to mainstream specification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating Production | Captive EVOH supply secures margin control against Belgian and German resin concentration. |
| Mono-Material PP Portfolio Expansion | France's EPR scheme rewards simplified substrates with preferential fee structures. |
| Laser-Based Gas Analysis Equipment Deployment | German meatpackers adopt inline QA to replace batch laboratory testing at line speeds. |
| Central European Distribution Partnership | Poland and Romania modernization programs demand local service footprints. |
| Active Packaging Convergence R&D | Oxygen scavenger integration with freshness indicators captures pharmaceutical cold chain premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with packaging machinery engineers, protein processor procurement leads, film extrusion plant managers, and retail category buyers validated substrate specification trends and equipment adoption timelines. EFSA migration limit evaluations, REACH substance restriction proposals, and EU Green Deal implementation guidance provided regulatory boundary conditions. Bottom-up demand modeling across processor segments triangulated against top-down converter capacity assessments.
Granularity-level framing applied country-specific substrate adoption curves, technology penetration rates by end-use segment, and material substitution dynamics across the projection horizon. Segmentation dimensions included product type, material composition, end-use application, and gas technology category. CAGRs derived from fitted adoption curves incorporating equipment replacement cycles and regulatory compliance deadlines. Forecast inputs incorporated EPR scheme fee structures and retail procurement consolidation patterns.
The model assumes a particular technology adoption path; alternative pathways for bio-based barrier constructions achieving retort compatibility would alter the outlook. Forecasts reflect assumptions regarding REACH authorization timelines and EFSA recycled content threshold evaluations. Feedstock volatility, barrier coating supply disruptions, and technician training output gaps constitute specific revision triggers. A small set of regulatory implementation schedules and retail procurement centralization milestones warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Airless Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market