
 Global Packaging Market | 2026-2036
Global Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Packaging Market Outlook
Subscription-based packaging design and replenishment services is realigning how brand owners procure protective formats. Amcor Plc leverages its global film and fiber network to anchor long-term supply contracts with multinational food processors. WestRock competes through integrated containerboard-to-box operations across the southeastern United States and Latin America. Oji Holdings dominates Asian corrugated demand with massive pulp self-sufficiency and regional mill scale.
Packaging encompasses engineered enclosures, barriers, and containment systems fabricated from substrates including polyethylene terephthalate, kraft linerboard, aluminum alloys, and soda-lime glass, designed to preserve product integrity through distribution, storage, and retail display. Flexible formats lead volume in food preservation applications where barrier films reduce perishable spoilage, while rigid paperboard captures premium positioning in personal care and electronics unboxing experiences. E-commerce channels represent the fastest-growing distribution dimension, demanding crush-resistant structures that survive automated sortation and last-mile handling.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recycled content minimums that reshape material sourcing across European converters. FDA food contact substance notifications and China's GB standards for plastic food packaging govern export market access for Asia-Pacific manufacturers. California's SB 54 mandates source reduction and recyclability thresholds that cascade through North American supply chains. Stakeholders must monitor regulatory divergence between jurisdictions that fragments compliance costs and determines which material platforms achieve scalable adoption.
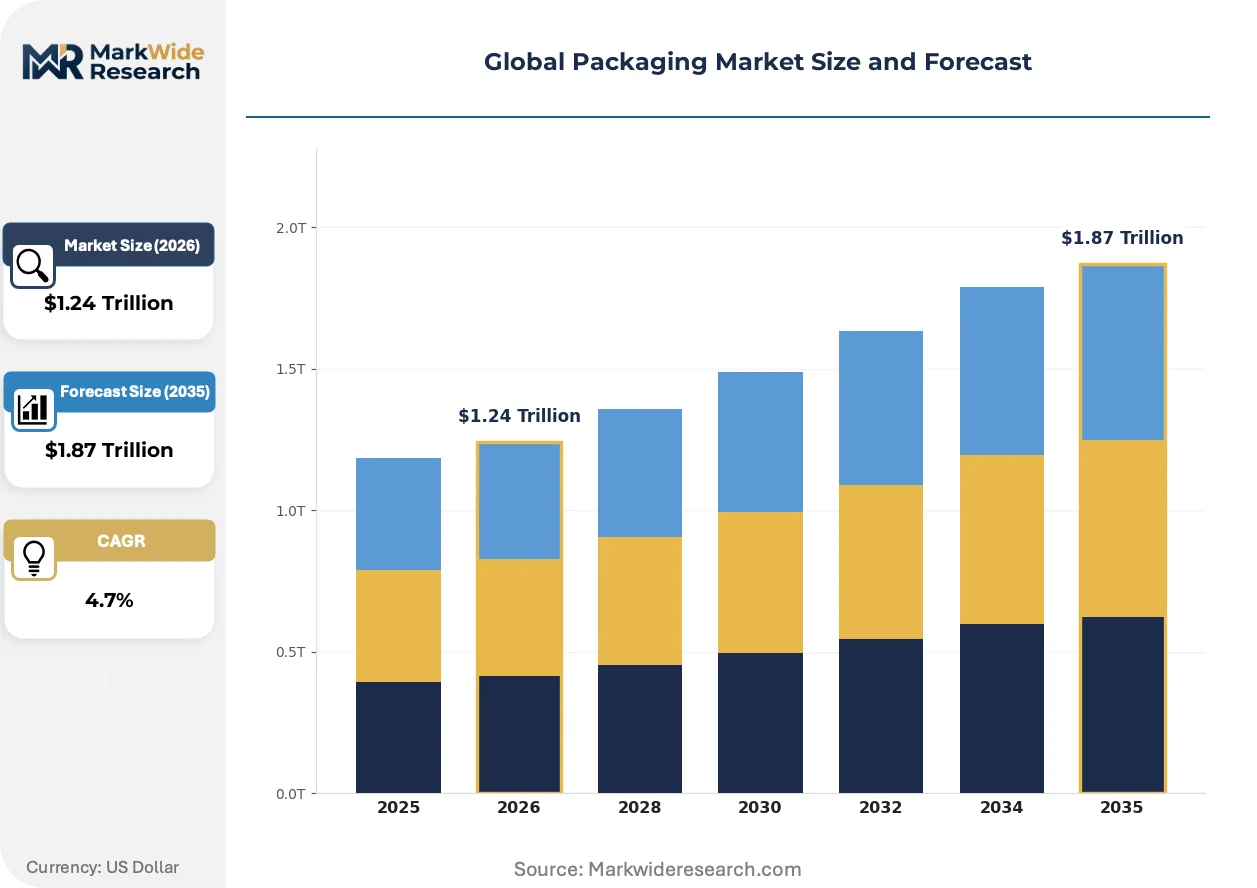
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material substitution timelines, forcing converters to requalify fiber-based barrier coatings at unprecedented speed while legacy plastic formats face phasedown deadlines across member states.
Growth Catalysts
- E-commerce fulfillment density:Automated sortation networks in Germany and the United States require crush-resistant corrugated structures that withstand robotic handling. Protective format specifications now prioritize dimensional stability over lightweighting.
- REACH chemical restrictions:ECHA's expanding Substances of Very High Concern list is blocking conventional plasticizers in food-contact films. Brand owners accelerate migration to bio-based barrier coatings to preempt compliance exposure.
- Dual carbon targets:China's MIIT mandates for carbon intensity reduction in manufacturing clusters are pushing export-oriented consumer goods brands toward lower-emission packaging substrates. Domestic pulp integration offers Scope 3 advantages.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import policy shifts. North American mills face margin compression when Asian buyers re-enter spot markets.
- Barrier performance gaps:Fiber-based grease and moisture resistance remains inferior to multilayer plastic laminates for wet food applications. Technical limitations constrain full material substitution in protein packaging.
- Extended producer responsibility fees:Germany's Verpackungsgesetz imposes escalating participation costs on non-compliant importers. Small brand owners face disproportionate administrative burden relative to volume.
Strategic Opportunities
- Returnable transport packaging:Closed-loop pooling systems for automotive and electronics components remain underdeveloped in Southeast Asian manufacturing corridors. Asset-tracking IoT integration enables pay-per-use commercialization.
- Pharmaceutical serialization convergence:EU Falsified Medicines Directive and US DSCSA deadlines are unifying track-and-trace requirements with primary packaging design. Contract packagers can capture compliance bundling value.
- Reusable foodservice formats:France's anti-gaspillage law mandates progressive reduction of single-use tableware. Deposit-return infrastructure for institutional catering creates white space for standardized container platforms.
Industry Challenges
- Barrier coating requalification:Migrating from polyethylene extrusion to aqueous coatings requires 18-24 month FDA food contact notification cycles. Product development timelines misalign with regulatory deadlines.
- Legacy asset stranding:Converters with sunk investment in solvent-based printing and extrusion laminating face write-down pressure. Retraining press operators for water-based systems extends downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Packaging Market |
| Market Size in 2026 | $1.24 Trillion |
| Market Size in 2035 | $1.87 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Glass Packaging Format: Flexible, Rigid, Semi-Rigid, Containment End User Industry: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale |
| Companies Covered | WestRock, Crown Holdings, Amcor Plc, Mondi Group, Berry Global, International Paper, Ball Corporation, Oji Holdings, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Packaging Market Strategic Shifts
Digital printing and smart packaging integration are collapsing minimum order quantities while enabling batch-level traceability. Material science advances in nanocellulose barriers promise to bridge performance gaps between fiber and plastic formats.
Mono-material polyethylene structures are unifying recyclability claims with functional barrier requirements. European dairy and personal care brand owners are adopting these formats ahead of 2025 EPR reporting deadlines. The technology is unifying formerly incompatible sorting stream compatibility with oxygen and moisture protection.
California's SB 54 mandates 30% source reduction and full recyclability by 2032. This statute cascades through North American supply chains as national brands standardize to California-compliant formats. Food processors serving multi-state distribution are reformulating multilayer flexible packaging to meet the strictest jurisdictional threshold.
Subscription replenishment models are compressing packaging specification cycles from annual to quarterly reviews. Direct-to-consumer beauty and supplement brands in the United States demand rapid graphic versioning for limited releases. Contract designers in Chicago and Los Angeles are restructuring retainers around velocity-based fee structures rather than per-project billing.
Global Packaging Market Segmentation
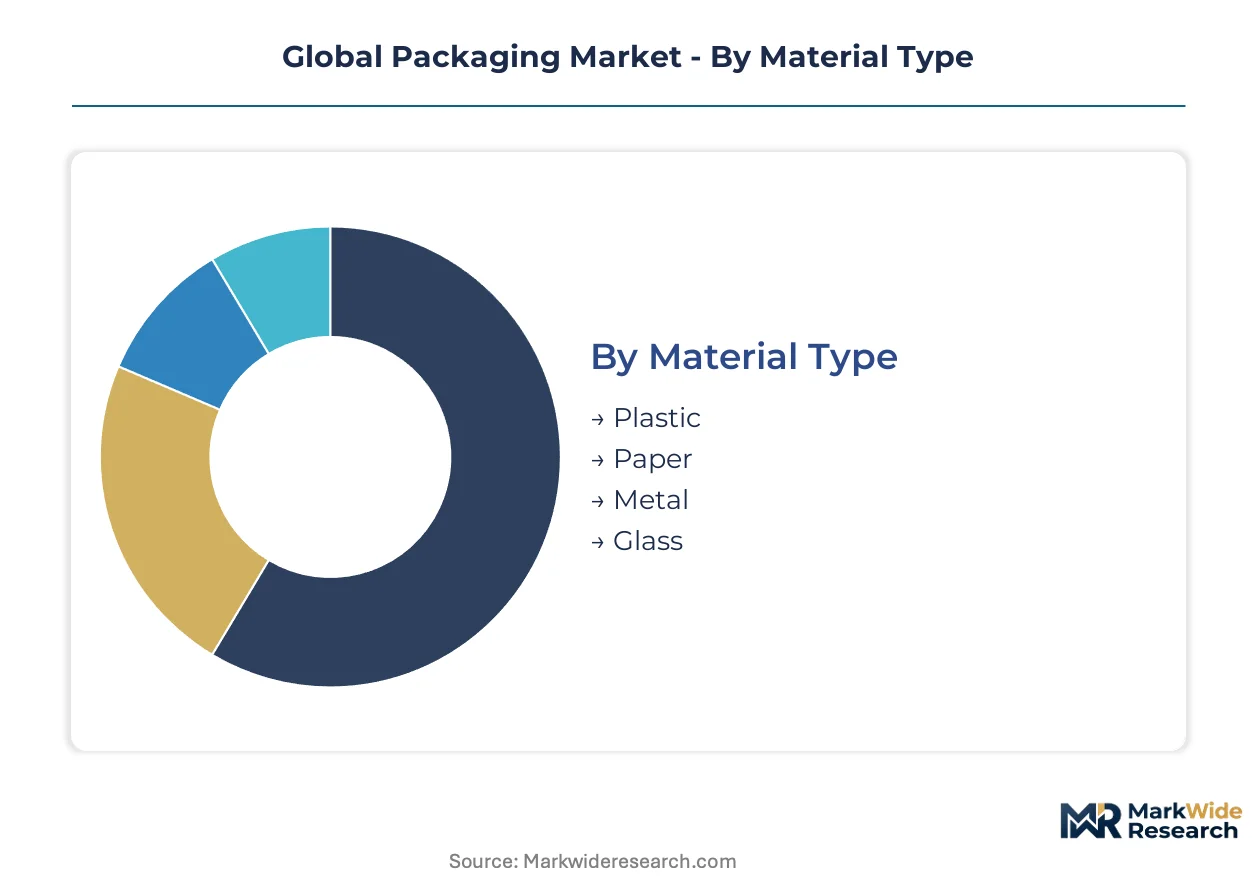
Packaging procurement decisions cascade through material selection, format engineering, and channel-specific performance requirements. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape converter investment priorities.
Material Type:
Resin and fiber supply concentration determines regional cost competitiveness and carbon accounting methodologies for brand owners.
- Plastic:Polyethylene terephthalate and polypropylene formulations dominate barrier-sensitive food applications. German automotive suppliers specify thermoformed polyethylene trays for component logistics to satisfy ECHA REACH compliance on plasticizer content.
- Paper:Kraft linerboard and recycled corrugated medium constitute the largest volume substrate for e-commerce protective formats. China's MIIT dual carbon mandates accelerate domestic pulp integration for export-oriented consumer goods brands seeking Scope 3 reductions.
- Metal:Aluminum alloys and tinplate provide oxygen barrier performance for shelf-stable protein packaging.
- Glass:Soda-lime silica compositions retain premium positioning in spirits and pharmaceutical applications.
Paper absorbs the bulk of installed capacity; plastic is expanding most quickly in barrier coating substitutions.
Packaging Format:
Format selection governs automated handling compatibility and end-of-life recovery economics across sorting infrastructure.
- Flexible:Multilayer films and stand-up pouches minimize material weight for snack and frozen food distribution. California SB 54 recyclability thresholds force reformulation of polyethylene-nylon laminates toward mono-material structures.
- Rigid:Injection-molded containers and thermoformed trays provide dimensional stability for retail shelf presence. Electronics unboxing experiences in the United States specify rigid paperboard with aqueous coatings to preempt EPR fee escalation.
- Semi-Rigid:Folding cartons and blister packs bridge protection and display functions for over-the-counter pharmaceuticals.
- Containment:Drums, intermediate bulk containers, and pails serve industrial chemical logistics.
Flexible formats command the highest throughput velocities; rigid formats are climbing the fastest on e-commerce damage reduction specifications.
End User Industry:
Industry-specific regulatory deadlines compress qualification timelines and determine barrier performance premiums.
- Food & Beverage:Modified atmosphere packaging and aseptic cartons extend perishable shelf life. FDA food contact substance notifications govern migration limits for polyethylene coatings in US dairy applications.
- Pharmaceuticals:Blister foils and vial containment must satisfy EU Falsified Medicines Directive serialization requirements. Contract packagers in Germany bundle track-and-trace compliance with primary packaging design.
- Personal Care:Premium unboxing aesthetics drive specification of embossed rigid boxes and metallized films.
- Electronics:Electrostatic discharge protection and crush resistance dominate protective format design.
Food and beverage absorbs the bulk of installed capacity; pharmaceuticals is gaining share fastest on serialization convergence investments.
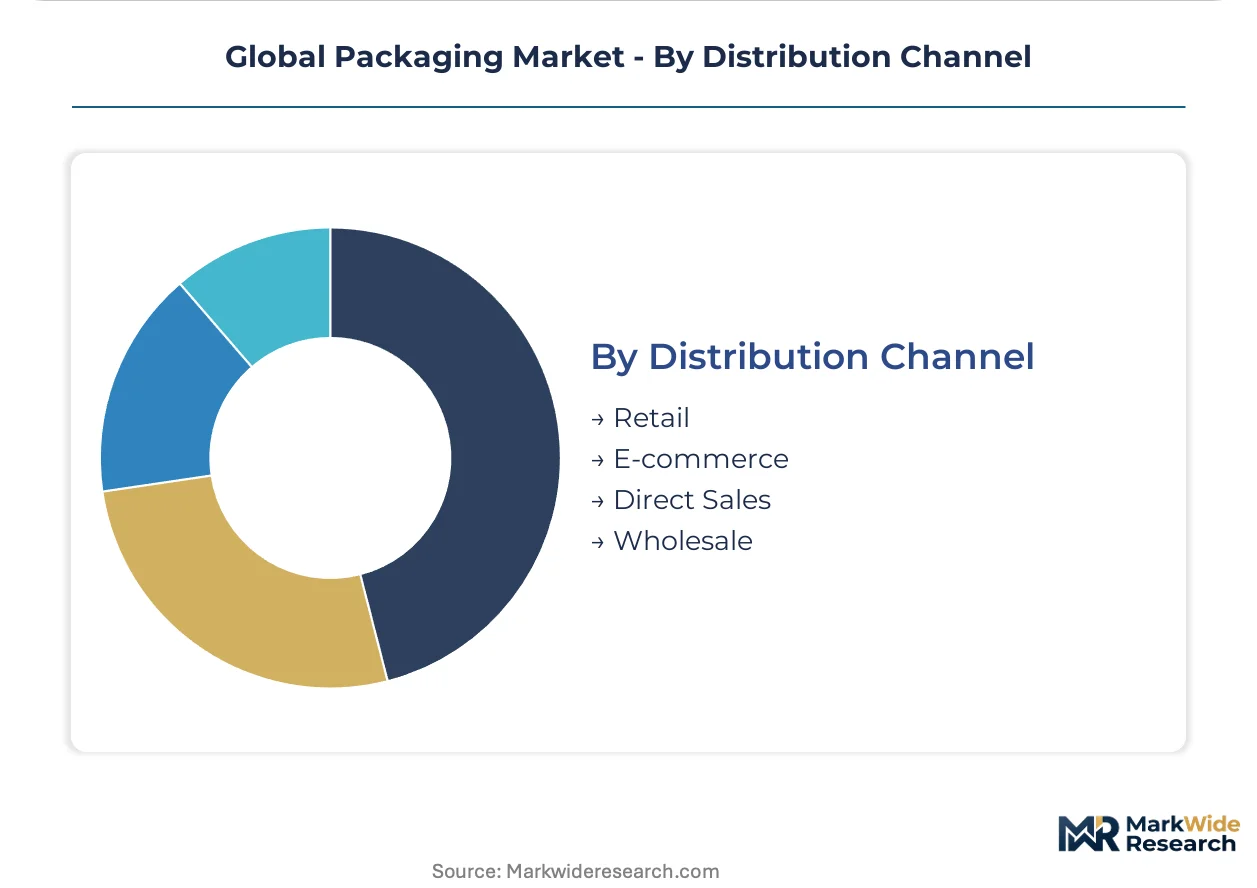
Distribution Channel:
Channel-specific handling intensity determines structural specifications and graphic versioning frequency.
- Retail:Shelf-ready packaging and point-of-sale display compatibility govern secondary format dimensions. Walmart and Target compliance standards dictate case-stacking strength requirements.
- E-commerce:Automated sortation survivability and last-mile crush resistance prioritize corrugated flute profiles. Amazon's Frustration-Free Packaging program mandates dimensional optimization to reduce void fill.
- Direct Sales:Subscription replenishment models compress specification cycles to quarterly reviews.
- Wholesale:Pallet-level unitization and warehouse stacking height determine bulk container specifications.
Retail absorbs the bulk of installed capacity; e-commerce is expanding most quickly on fulfillment network densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of export-oriented packaging while Germany and the United States absorb premium protective formats for e-commerce fulfillment. This production-consumption divide shapes material flows and regulatory compliance costs across converter networks.
United States
Amazon's Frustration-Free Packaging program drives dimensional optimization standards for corrugated shippers. California's SB 54 mandates 30% source reduction and full recyclability by 2032, forcing national brands to standardize compliant formats. Chicago and Los Angeles contract design studios now structure retainers around quarterly specification reviews for direct-to-consumer beauty brands.
Germany
Automated sortation networks in Bavaria and North Rhine-Westphalia demand crush-resistant flute profiles for robotic handling. The Verpackungsgesetz imposes escalating extended producer responsibility fees on non-compliant importers. Hamburg-based converters accelerate fiber-based barrier coating requalification to meet EU Packaging and Packaging Waste Regulation deadlines.
China
Manufacturing clusters in the Yangtze River Delta and Pearl River Delta serve export-oriented consumer goods brands with integrated pulp-to-box operations. MIIT dual carbon mandates push domestic mills toward captive pulp integration for Scope 3 advantages. Shenzhen and Shanghai converters face compressed development cycles as subscription replenishment models demand quarterly graphic versioning.
Japan
Electronics unboxing experiences in Tokyo-Osaka corridors specify rigid paperboard with aqueous coatings for premium positioning. METI guidance on circular economy implementation accelerates material substitution toward mono-material polyethylene structures. Nagoya-area automotive suppliers specify thermoformed trays for component logistics to satisfy REACH compliance on plasticizer content.
India
E-commerce fulfillment densification in Mumbai and Delhi-NCR drives adoption of crush-resistant corrugated for last-mile survivability. BIS standards for plastic food packaging govern domestic market access while GB standard alignment supports export-oriented production. Gujarat and Maharashtra converter clusters invest in water-based printing system conversions to preempt solvent-based asset stranding.
Global Packaging Market Competitive Environment
Top-tier vendors anchor integrated containerboard-to-box operations, while mid-tier specialists compete on regional mill scale and pulp self-sufficiency. The market structure concentrates around three strategic archetypes: global film and fiber network operators, integrated North American containerboard producers, and Asian pulp-integrated corrugated specialists. Dominant competitive moves include backward integration into pulp supply and geographic expansion through regional mill acquisitions.
Within the global network tier, Amcor Plc and Mondi Group exemplify multinational converters leveraging cross-regional supply contracts. WestRock anchors integrated operations across the southeastern United States and Latin America. Oji Holdings occupies a position as the dominant Asian corrugated producer through massive pulp self-sufficiency and regional mill scale.
| Leading Market Players |
|---|
| WestRock |
| Crown Holdings |
| Amcor Plc |
| Mondi Group |
| Berry Global |
| International Paper |
| Ball Corporation |
| Oji Holdings |
| Smurfit Kappa |
| Others |
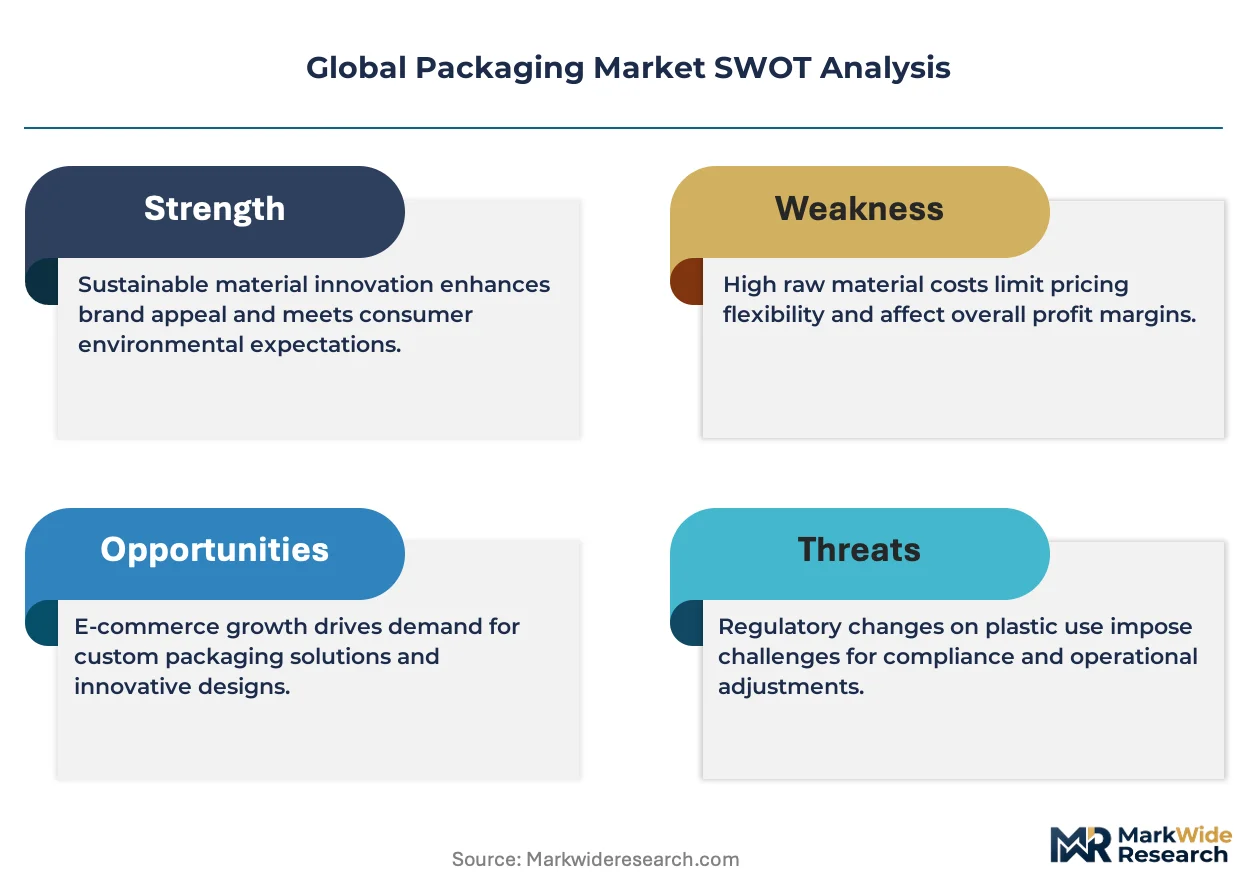
Value Chain & Pricing Dynamics
Multinational food processors and e-commerce fulfillment operators concentrate procurement volume, anchoring contract-based long-term offtake structures that reward scale and certification compliance over spot-market flexibility.
Pricing Analysis
Cost-down pressure on mid-tier converters accelerates because OCC feedstock volatility and EPR fee escalation compress operating margins. Three-tier pricing structure across premium barrier-coated formats, standard corrugated shippers, and economy recycled medium separates performance tiers. Pricing pressure stems from Chinese import policy shifts in recovered fiber markets. Small brand owners exhibit highest price sensitivity; multinational CPGs absorb compliance premiums for supply security.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta and Pearl River Delta manufacturing clusters tether capacity expansion to automation investment cycles. Supply concentrates in China, Germany, and the United States for integrated pulp-to-box operations. Raw material flows draw from Brazilian eucalyptus pulp, North American OCC collections, and European kraft linerboard. Single-source vulnerability in barrier coating chemistry creates chokepoint exposure. Distribution runs through regional converter networks serving last-mile fulfillment densification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation constructs a cost-of-compliance moat that favors incumbents with existing pulp integration and requalification capital.
For Market Incumbents: Anchor backward integration into captive pulp supply to insulate margin structures from OCC spot volatility. Accelerate aqueous barrier coating capacity ahead of phasedown deadlines to strand competitor assets invested in solvent-based systems. Defend position against emerging fiber-tech specialists by locking multi-year supply contracts with multinational food processors. For New Entrants and Emerging Players: Contract packagers serving pharmaceutical serialization convergence represent the most penetrable channel partner type for compliance-bundled entry. Target Southeast Asian returnable transport packaging corridors where asset-tracking IoT integration remains underdeveloped. Pursue white-label manufacturing partnerships with direct-to-consumer beauty brands demanding quarterly graphic versioning velocity. For Investors and Strategic Acquirers: The window for entry favors mid-tier converters with water-based printing conversion progress and established FDA food contact notification track records. Acquisition candidates with regional mill scale and MIIT carbon compliance positioning offer longest viability through tightening regulatory windows. Watch ECHA SVHC list expansion velocity as inflection signal for bio-based barrier coating substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber sourcing insulates German and US converters from Chinese OCC import policy swings. |
| Aqueous Barrier Coating Capacity Expansion | Water-based systems preempt EU Packaging and Packaging Waste Regulation phasedown deadlines for plastic formats. |
| Pharmaceutical Serialization Compliance Bundling | EU Falsified Medicines Directive convergence creates service-layer value for contract packagers. |
| Returnable Transport Packaging IoT Integration | Asset-tracking technology enables pay-per-use commercialization in Southeast Asian manufacturing corridors. |
| Direct-to-Consumer Design Velocity Retainers | Quarterly specification cycles align Chicago and Los Angeles studios with subscription replenishment models. |
Study Parameters
Trade flow databases, mill capacity registries, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews involving corrugated plant managers, CPG procurement directors, regulatory affairs leads at converters, and e-commerce fulfillment operations heads. Bottom-up and top-down triangulation validated volume estimates across material type and format dimensions.
Bottom-up modeling anchored projections in disclosed capacity expansions and announced mill conversions, while top-down analysis tested aggregate demand against macro consumption indicators across the projection horizon. Segmentation dimensions included material substrate, packaging format rigidity, end-use industry regulatory cluster, and channel handling intensity. CAGRs derived from regression against historical substitution elasticities and regulatory deadline pacing, with specific inputs from EPR fee schedules and MIIT carbon intensity trajectories.
Several conditions sit outside the modeled scope, including unannounced merger activity, abrupt tariff reconfigurations, and breakthrough nanocellulose barrier commercialization timelines. Forecasts reflect assumptions about regulatory enforcement consistency and pulp feedstock trade flow stability. Material deviation in ECHA SVHC expansion velocity or Chinese recovered fiber import policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
FMCG Packaging Market