
 Saudi Arabia Packaging Market | 2026-2036
Saudi Arabia Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Packaging Market Insights
Smart packaging integration with QR-enabled traceability and active freshness monitoring is reconfiguring how Saudi food producers manage cold chain integrity and consumer engagement. Napco National leverages its vertically integrated paper and plastics operations to supply major dairy and beverage brands across the GCC. Zamil Plastics anchors the rigid container segment through high-volume blow molding capacity serving the Kingdom's carbonated soft drink bottlers. Tetra Pak Arabia dominates aseptic carton technology for ambient milk and juice distribution in arid climate conditions where refrigeration infrastructure remains uneven.
Packaging in Saudi Arabia encompasses engineered containment systems—ranging from multilayer polymer films to corrugated fiberboard and aluminum cans—designed to protect, preserve, and communicate product value through specified barrier properties, tensile strength, and shelf-life extension parameters. The material dimension reveals plastic sustaining volume leadership due to its cost efficiency in bottled water and edible oils, while paper formats gain structural momentum from e-commerce shipping box demand and quick-service restaurant packaging substitution. Pouches represent the fastest-growing product type as snack food manufacturers and personal care brands adopt stand-up flexible formats for portion control and shelf differentiation.
SFDA mandates govern direct food contact materials and pharmaceutical primary packaging standards, compelling converters to maintain migration testing protocols and GMP-aligned production environments. SASO technical regulations enforce labeling, recyclability claims, and product safety certifications that shape market access for imported substrates and finished containers. MOF and SDAIA circular economy directives are beginning to influence procurement specifications across state-affiliated retail and foodservice operators. Stakeholders must track how domestic resin pricing, Sabic feedstock allocation policies, and evolving extended producer responsibility frameworks reshape total cost of ownership for packaging decisions.
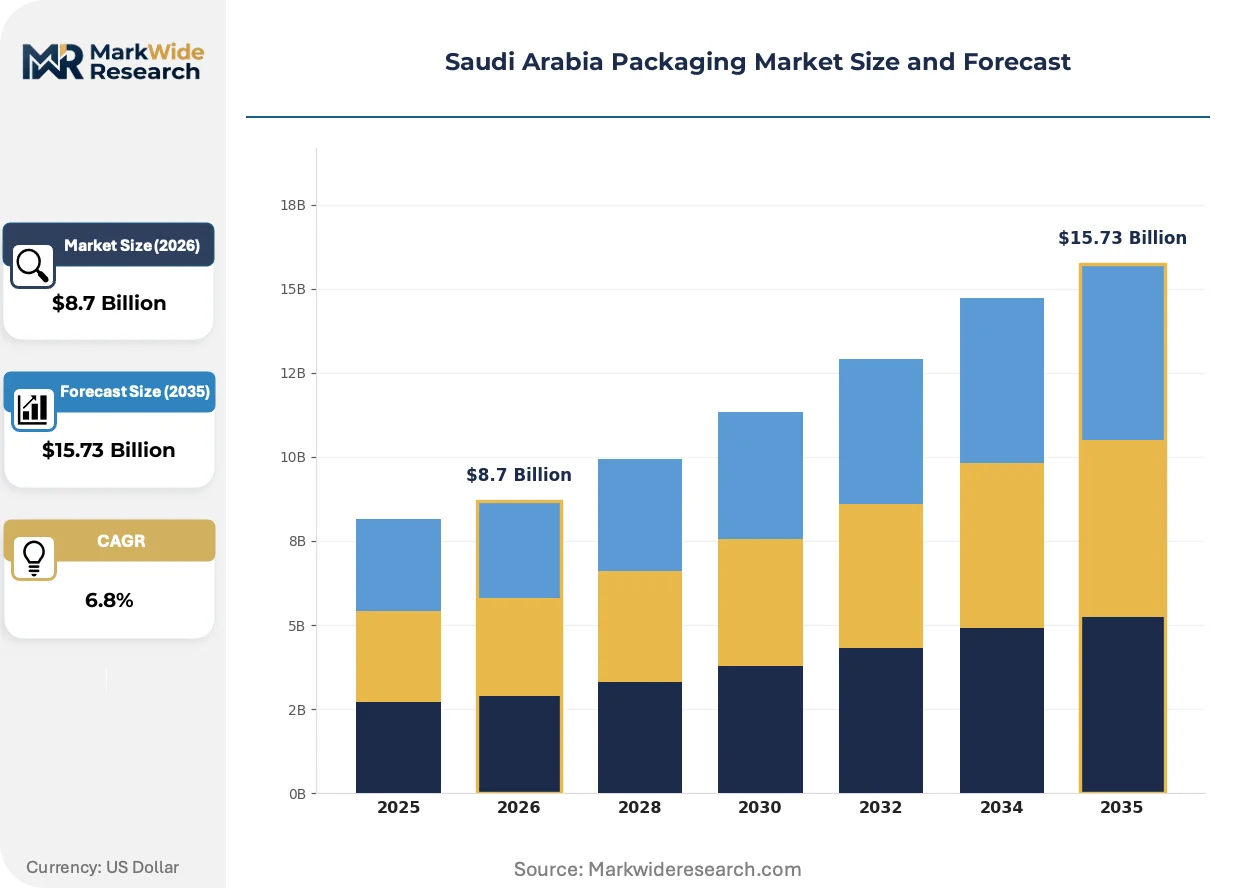
Market Dynamics
Saudi Vision 2030 industrial localization mandates are compressing import dependency for packaging substrates while redirecting state procurement toward domestic converters with captive resin supply.
Growth Catalysts
- SFDA food contact compliance:Migration testing protocols for direct food contact materials are compelling brand owners to source from GMP-certified domestic converters rather than speculative imports.
- E-commerce shipping box demand:Quick-commerce fulfillment networks in Riyadh and Jeddah are consuming corrugated fiberboard at rates that outpace traditional retail replenishment cycles.
- Biodegradable substrate manufacturing:MOF circular economy directives are creating procurement preference for locally produced compostable films in state-affiliated foodservice operations.
Market Restraints
- Sabic feedstock allocation concentration:Domestic resin pricing volatility tracks state-owned petrochemical allocation policies that prioritize industrial sectors over packaging converters during supply crunches.
- Arid climate infrastructure gaps:Uneven cold chain coverage outside Riyadh and Jeddah limits aseptic carton distribution reach for ambient-sensitive dairy products.
- Aluminum can import dependency:Beverage can body stock relies on rolling mill capacity concentrated in Bahrain and UAE, exposing bottlers to cross-border tariff friction.
Strategic Opportunities
- Eastern Province dairy clusters:Al-Ahsa and Dammam processing corridors remain underserved by flexible pouch converters despite expanding UHT milk output.
- SDAIA smart packaging integration:QR-enabled traceability mandates for pharmaceutical serialization are creating demand for printed electronics expertise that domestic printers currently lack.
- Quick-service restaurant substitution:Paper-based foodservice packaging is displacing expanded polystyrene in Jeddah's coastal tourism zones ahead of national bans.
Industry Challenges
- Printed electronics skill scarcity:Active freshness monitoring and NFC-enabled authentication require converter capabilities in conductive ink deposition that Saudi technical institutes have not yet standardized.
- Extended producer responsibility compliance:SASO recyclability certification timelines lag behind EU and US precedent, forcing exporters to maintain dual specification inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Cans, Boxes, Pouches Material: Plastic, Paper, Metal, Glass End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Shape: Rectangular, Cylindrical, Square, Oval |
| Companies Covered | Napco National, Zamil Plastics, Tetra Pak Arabia, Sabic Packaging Solutions, Al Obeikan Packaging, ASPCO, Middle East Packaging Company, National Plastic Factory, Obeikan Investment Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Packaging Market Trends and Innovations
Digital layer integration is reconfiguring packaging from passive containment to active data infrastructure, with implications for traceability, authentication, and consumer engagement across the Kingdom's food and pharmaceutical supply chains.
Smart packaging with embedded sensors and blockchain-verified QR codes is virtualizing quality assurance documentation for Saudi dairy exporters targeting EU and Gulf markets. Major processors in Al-Kharj and Sudair are piloting temperature-logging labels that transmit cold chain integrity data directly to retailer receiving systems. This virtualization compresses dispute resolution timelines and reduces manual inspection overhead at port-of-entry checkpoints.
SASO technical regulations on recyclability claims and labeling standards are tightening enforcement against greenwashing in imported substrates. The regulation compels converters to substantiate biodegradation timelines through third-party laboratory certification rather than unverified marketing assertions. Food and beverage brands with pan-GCC distribution are reformulating multilayer films to meet the Kingdom's stricter separation and sorting requirements.
Quick-commerce procurement patterns are fragmenting order quantities while compressing delivery windows for corrugated shippers serving Riyadh's dark store networks. Traditional pallet-scale shipments to hypermarkets are giving way to carton-level replenishment cycles synchronized with real-time inventory telemetry. This behavioral shift is most visible in snack food and personal care categories where impulse replenishment drives frequency over volume.
Saudi Arabia Packaging Market Segmentation
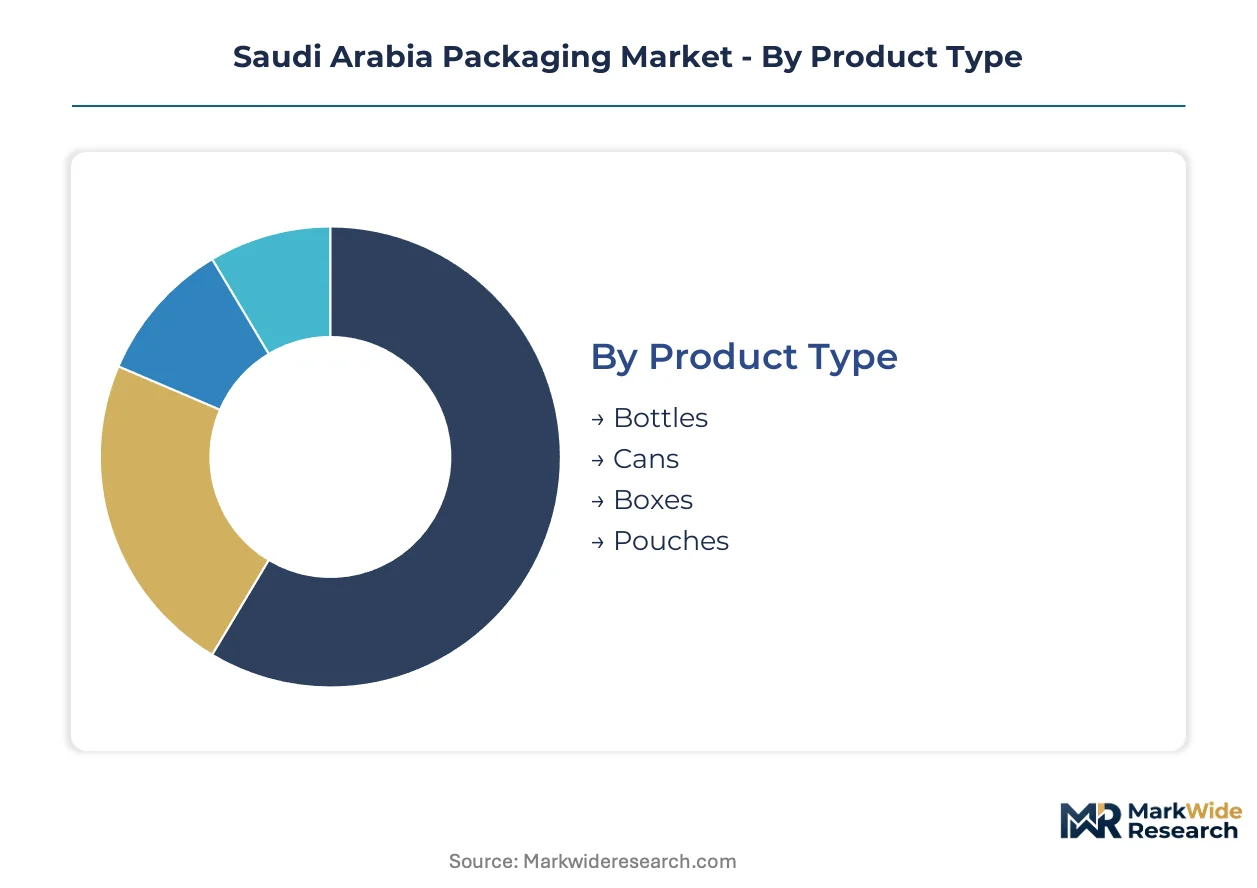
Packaging purchasing decisions in the Kingdom diverge sharply by product velocity and shelf-life requirements, with ambient-stable formats commanding longer production cycles than perishable-guarding alternatives. Understanding segment turnover dynamics helps converters align capacity planning with the contrasting rhythm of dairy bottling versus e-commerce fulfillment.
Product Type:
Bottles turn over fastest in dairy and beverage bottling corridors, while pouches accelerate on snack food lines and boxes lag behind in corrugated production scheduling.
- Bottles:High-density polyethylene and PET formats dominate the Kingdom's bottled water and edible oil sectors with standardized neck finishes and barrier specifications. Riyadh's mega-bottlers consume HDPE at volumes that compress mold-change intervals to weekly cycles during peak summer demand.
- Pouches:Multilayer flexible laminates with resealable zipper functionality are displacing rigid formats in Saudi snack food and personal care aisles. Jeddah's quick-commerce dark stores favor stand-up pouches for portion-controlled confectionery and shampoo sachets that minimize dimensional weight in last-mile delivery.
- Boxes:Corrugated fiberboard with variable flute profiles serves the Kingdom's e-commerce shipping and retail-ready display requirements.
- Cans:Two-piece aluminum and three-piece steel formats preserve carbonated beverages and processed foods across arid distribution conditions.
Bottles anchor the volume base while pouches gain share at the steepest rate.
Material:
Cost tier stratification separates commodity resin from specialty substrates, with virgin polyethylene commanding premium over recycled fiber and aluminum body stock pricing above both.
- Plastic:Polyethylene terephthalate and polypropylene films deliver cost-efficient barrier properties for bottled water, edible oils, and flexible snack packaging. Sabic feedstock allocation policies directly shape converter margins for polyethylene grades serving Riyadh's dairy cluster.
- Paper:Kraft linerboard and medium fluting grades are expanding corrugated output for quick-commerce shipping boxes and quick-service restaurant disposables. Jeddah's coastal tourism zones are accelerating paper substitution ahead of expanded polystyrene restrictions.
- Metal:Aluminum can body stock and tinplate steel provide impermeable containment for carbonated beverages and processed meat products.
- Glass:Borosilicate and soda-lime formulations preserve premium sauces, fragrances, and pharmaceutical liquids with inert contact surfaces.
Plastic dominates tonnage throughput while paper climbs fastest on e-commerce and foodservice substitution demand.
End User:
Application-driven specifications create divergent certification burdens, with pharmaceutical serialization mandates exceeding food contact compliance complexity.
- Food & Beverage:Migration-tested polymers and aseptic carton formats preserve product integrity across Saudi Arabia's uneven cold chain infrastructure. SFDA food contact protocols compel dairy processors in Al-Kharj to source exclusively from GMP-certified domestic converters.
- Pharmaceuticals:Blister foil, vial glass, and serialization-ready folding cartons meet SFDA primary packaging standards for temperature-sensitive biologics. SDAIA traceability mandates are driving QR-enabled authentication adoption that domestic printers currently struggle to execute.
- Personal Care:Dispensing pumps, airless bottles, and flexible tubes protect formulation stability for humidity-exposed products.
- Household:Trigger sprayers, rigid pails, and laminated pouches contain cleaning chemicals and detergent concentrates.
Food and beverage commands absolute volume while pharmaceuticals posts the steepest specification upgrade trajectory.
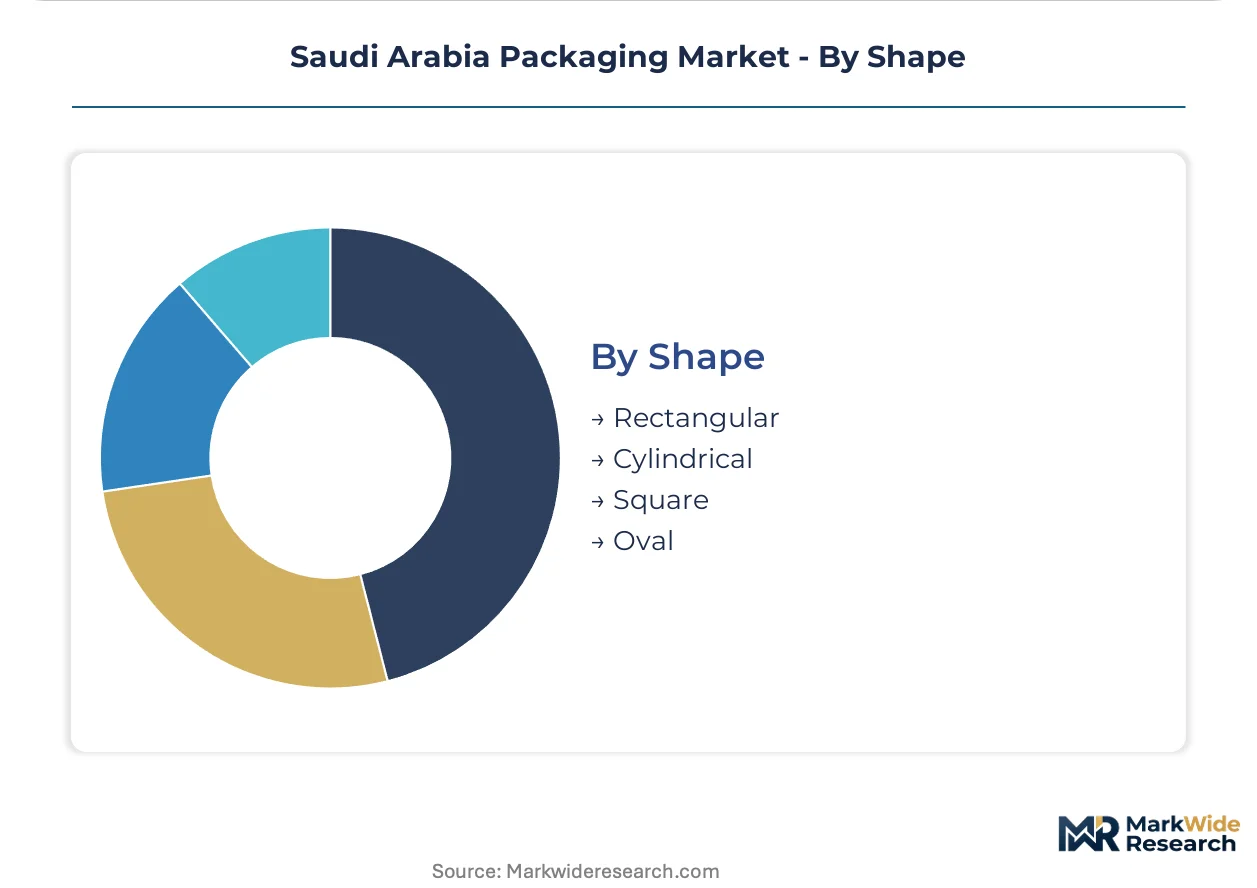
Shape:
Geometry selection tracks handling efficiency and shelf differentiation, with rectangular formats optimizing pallet utilization and cylindrical profiles maximizing label real estate.
- Rectangular:Corrugated RSC boxes and folding cartons maximize cube efficiency in Riyadh's automated fulfillment centers and Jeddah's port consolidation facilities.
- Cylindrical:Bottles and cans present continuous label surfaces for beverage branding and 360-degree graphic treatment.
- Square:Dairy cartons and rigid containers optimize shelf-facing density in refrigerated retail cases.
- Oval:Differentiated profiles in personal care and premium food segments create tactile distinction at point of purchase.
Rectangular formats dominate logistics efficiency while cylindrical shapes retain brand communication advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's packaging trade balance tilts toward domestic production as Vision 2030 localization mandates redirect procurement from Gulf imports toward Kingdom-based converters with captive resin supply.
Riyadh
Mega-bottlers of bottled water and edible oils consume high-density polyethylene at volumes that compress mold-change cycles to weekly intervals during peak summer months. SFDA food contact compliance protocols compel dairy processors in Al-Kharj to source exclusively from GMP-certified domestic converters rather than speculative imports. The Sudair industrial city anchors flexible pouch pilot programs for UHT milk producers testing temperature-logging labels.
Eastern Province
Al-Ahsa and Dammam dairy processing corridors expand UHT milk output yet remain underserved by flexible pouch converters despite growing demand. Sabic feedstock allocation policies from nearby Jubail petrochemical complexes shape polyethylene pricing volatility for packaging converters. The King Fahd Industrial Port facilitates resin import flows that supply rigid container blow molders serving carbonated soft drink bottlers.
Western Region
Jeddah's coastal tourism zones accelerate paper-based foodservice packaging substitution ahead of national expanded polystyrene restrictions. Quick-commerce dark stores in the city favor stand-up pouches for portion-controlled confectionery to minimize dimensional weight in last-mile delivery. The King Abdulaziz Port consolidates corrugated fiberboard imports for e-commerce shipping box demand.
NEOM Northwest
The giga-project's construction phase generates bulk packaging demand for cement, chemicals, and construction materials that outpaces local converter capacity. MOF circular economy directives influence procurement specifications for compostable films in planned foodservice operations. The Trojena and Oxagon zones will test smart packaging integration with QR-enabled traceability for pharmaceutical and food distribution.
Saudi Arabia Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated resin-to-film operators and specialized rigid container fabricators with captive blow molding capacity. Domestic converters with Sabic feedstock access command procurement preference from state-affiliated retail operators. Two strategic archetypes dominate: petrochemical-backed integrated producers and regional specialists with GCC distribution networks. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure resin allocation and logistics infrastructure.
Within the integrated producer tier, Napco National and Zamil Plastics exemplify archetypes of vertically structured supply. Napco National occupies a position spanning paper and plastics operations that serve dairy and beverage brands across Gulf markets. Zamil Plastics anchors the rigid container segment through high-volume blow molding capacity. Tetra Pak Arabia represents the technology-licensing archetype, dominating aseptic carton distribution for ambient milk and juice in arid conditions where refrigeration infrastructure remains uneven.
| Leading Market Players |
|---|
| Napco National |
| Zamil Plastics |
| Tetra Pak Arabia |
| Sabic Packaging Solutions |
| Al Obeikan Packaging |
| ASPCO |
| Middle East Packaging Company |
| National Plastic Factory |
| Obeikan Investment Group |
| Others |
Pricing and Supply Chain Analysis
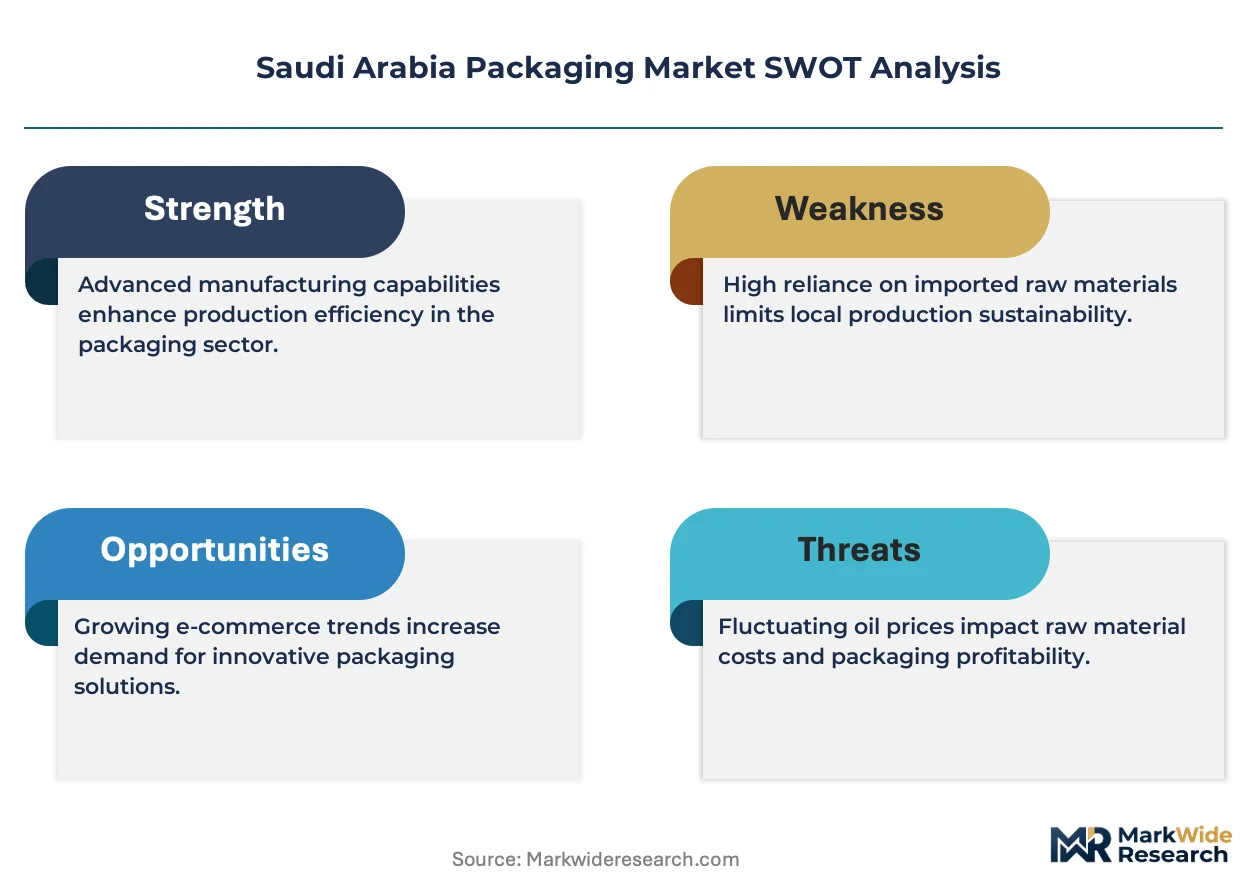
Jubail's petrochemical complexes anchor polyethylene resin supply for domestic packaging converters, concentrating feedstock pricing power among state-allocated producers while downstream buyers face margin compression during allocation crunches. This geographic concentration shapes how Sabic feedstock policies transmit volatility through bottle and film pricing tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Kingdom's packaging procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified converters from uncertified competitors and commodity resin traders. Cost compression in standard-grade polyethylene is intensifying because Sabic prioritizes industrial sector allocations during supply crunches. Quick-commerce dark stores exhibit highest price sensitivity due to fragmented order quantities, while pharmaceutical serialization mandates render premium-tier buyers least elastic.
Supply Chain Analysis
Upstream polyethylene feedstock draws from Saudi Arabia's Jubail and Yanbu complexes, with supplemental resin flows from UAE and Bahrain rolling mill capacity for aluminum body stock. Raw material dependencies center on Sabic ethylene output, imported tinplate steel, and kraft linerboard from Asian pulp sources. Single-source vulnerability concentrates in beverage can body stock where regional rolling mill capacity crosses tariff-exposed borders. Distribution runs through Riyadh and Jeddah mega-logistics hubs consolidating converter output for domestic retail and GCC re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as Vision 2030 localization mandates redirect state procurement toward domestic converters with captive resin access, accelerating import substitution across food and pharmaceutical packaging tiers.
For Market Incumbents: Pre-empt emerging flexible pouch competitors by securing Sabic feedstock allocation commitments for Eastern Province dairy corridors before capacity shortages materialize. Backward integration into multilayer film extrusion preserves margin position against resin price volatility. SFDA compliance certification investments create switching costs that lock in Al-Kharj dairy processor relationships.
For New Entrants and Emerging Players: Establish a beachhead in smart packaging integration where SDAIA pharmaceutical serialization mandates outpace domestic printed electronics capabilities. The most penetrable white-space sits in QR-enabled traceability solutions for temperature-sensitive biologics. Partner with European conductive ink specialists to bypass technical institute capability gaps.
For Investors and Strategic Acquirers: Long-term, this sits as a localization-tariff-hedge play because Gulf trade friction and carbon border adjustments will progressively penalize imported substrate dependence. Acquisition targets should exhibit vertically integrated resin-to-film operations with state procurement relationships. Monitor Sabic feedstock allocation policy announcements as the critical inflection signal for converter margin trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Extrusion | Captive polyethylene supply from Jubail complexes insulates margins from Sabic allocation volatility. |
| Smart Packaging Technology Licensing | Printed electronics partnerships with European specialists address SDAIA pharmaceutical traceability mandates. |
| Eastern Province Capacity Expansion | Al-Ahsa and Dammam dairy corridors remain underserved by flexible pouch converters despite growing UHT output. |
| GMP Certification Investment | SFDA food contact compliance creates procurement preference from state-affiliated retail operators. |
| Quick-Commerce Distribution Partnership | Riyadh dark store networks fragment order quantities while compressing delivery windows for corrugated shippers. |
Research Methodology
Cross-validation between converter production data and customs import records anchors the qualitative findings across the Saudi packaging landscape. Primary interviews with plant managers at dairy processing facilities, procurement leads at quick-commerce operators, regulatory affairs specialists at SFDA, and distribution channel partners at Jeddah port operators combined with secondary validation from SASO technical filings, Sabic feedstock allocation disclosures, and SEC 10-K filings of regional petrochemical parents. Bottom-up capacity surveys and top-down trade flow analysis triangulate volume estimates.
Calibration against historical resin pricing cycles and dairy processing capacity buildouts shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-user industry, and regional production cluster. CAGRs derive from trend extrapolation adjusted for Vision 2030 localization policy intensity and SFDA regulatory phase-in schedules. Forecast inputs incorporate Sabic ethylene allocation ratios and quick-commerce order frequency telemetry.
Sensitivities concentrate around Sabic feedstock reallocation decisions, SFDA compliance timeline acceleration, and GCC tariff friction escalation. Cross-checking against customs import volume benchmarks and regional petrochemical margin disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market