
 Europe Temperature Controlled Packaging Solutions Market | 2026-2036
Europe Temperature Controlled Packaging Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Temperature Controlled Packaging Solutions Market Foresight
Germany is narrowing its position as the dominant production hub for advanced thermal packaging systems in Europe. Sofrigam SA leverages its French manufacturing base to sustain specialized capacity in phase change material assemblies. va-Q-tec AG anchors German engineering leadership through vacuum insulation panel technology for ultra-low temperature shipments. Pelican BioThermal competes across the continent with reusable parcel and bulk thermal container platforms designed for pharmaceutical lane validation.
Temperature controlled packaging solutions comprise engineered thermal management systems—incorporating expanded polystyrene, polyurethane foam, vacuum insulation panels, and eutectic plates—that maintain product-specific temperature bands between minus eighty degrees Celsius and plus twenty-five degrees Celsius during transit and storage. These systems serve primarily to protect temperature-sensitive biologics, vaccines, and perishable food products against thermal excursions that compromise efficacy or safety. Insulated containers occupy the largest product category due to their versatility across parcel and bulk shipment formats, while active packaging systems represent the fastest-growing segment as cell and gene therapies require precise electronic cooling rather than passive phase change materials. Within end users, pharmaceuticals commands the deepest margin pools because validation protocols and GDP documentation requirements create substantial switching costs for qualified suppliers.
The European Medicines Agency enforces Good Distribution Practice standards that mandate documented temperature control across all pharmaceutical supply chain nodes, directly elevating demand for qualified packaging configurations with embedded data loggers. REACH and the EU F-Gas Regulation constrain refrigerant selections and material chemistries, pushing manufacturers toward natural phase change materials and hydrocarbon-based cooling systems. The EU AI Act introduces emerging traceability requirements that will eventually extend to autonomous cold chain monitoring devices. Stakeholders must decide whether to prioritize reusable system investments against single-use alternatives as carbon accounting rules under the Corporate Sustainability Reporting Directive reshape total cost of ownership calculations.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choices across Europe's temperature controlled packaging supply base, forcing manufacturers toward hydrocarbon cooling systems and natural phase change materials while simultaneously elevating compliance costs for insulated container producers.
Growth Catalysts
- EMA GDP enforcement:The European Medicines Agency mandates documented temperature control across pharmaceutical distribution nodes, creating qualified demand for validated thermal packaging with embedded data loggers.
- Cell therapy expansion:Advanced therapy medicinal products require ultra-low temperature stability between minus eighty and minus one hundred fifty degrees Celsius, driving adoption of active electronic cooling over passive systems.
- German manufacturing concentration:Vaccine production clusters in Bavaria and North Rhine-Westphalia generate concentrated demand for lane-validated bulk thermal containers with centralized distribution hub requirements.
Market Restraints
- Vacuum insulation panel supply concentration:Core material production for ultra-low temperature shipments concentrates among German and Austrian specialty manufacturers, creating input bottlenecks during demand surges.
- REACH chemical compliance:The European Chemicals Agency restricts phase change material chemistries, eliminating certain salt hydrate formulations and forcing reformulation cycles that extend product development timelines.
- Reusable system economics:Reverse logistics infrastructure for returnable thermal containers remains underdeveloped across Eastern European markets, limiting total cost of ownership advantages against single-use alternatives.
Strategic Opportunities
- Poland and Czech Republic distribution hubs:Central European logistics realignment creates greenfield demand for qualified cold chain infrastructure serving both EU and non-EU pharmaceutical corridors.
- EU AI Act traceability mandates:Emerging autonomous monitoring device requirements will eventually mandate connected temperature loggers, opening retrofit markets for existing installed base systems.
- CSRD carbon accounting:The Corporate Sustainability Reporting Directive forces pharmaceutical shippers to quantify packaging emissions, advantaging reusable container platforms with verified lifecycle data.
Industry Challenges
- Thermal engineer scarcity:Specialized expertise in phase change material formulation and vacuum insulation panel engineering concentrates among retiring German technical workforces, constraining R&D expansion.
- GDP qualification timelines:European Medicines Agency validation protocols for new packaging configurations require twelve to eighteen month documentation cycles, delaying revenue recognition for innovative product launches.
- Legacy system integration:Pharmaceutical warehouse management systems often lack API connectivity to modern temperature monitoring platforms, creating middleware complexity for cold chain digitization projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Temperature Controlled Packaging Solutions Market |
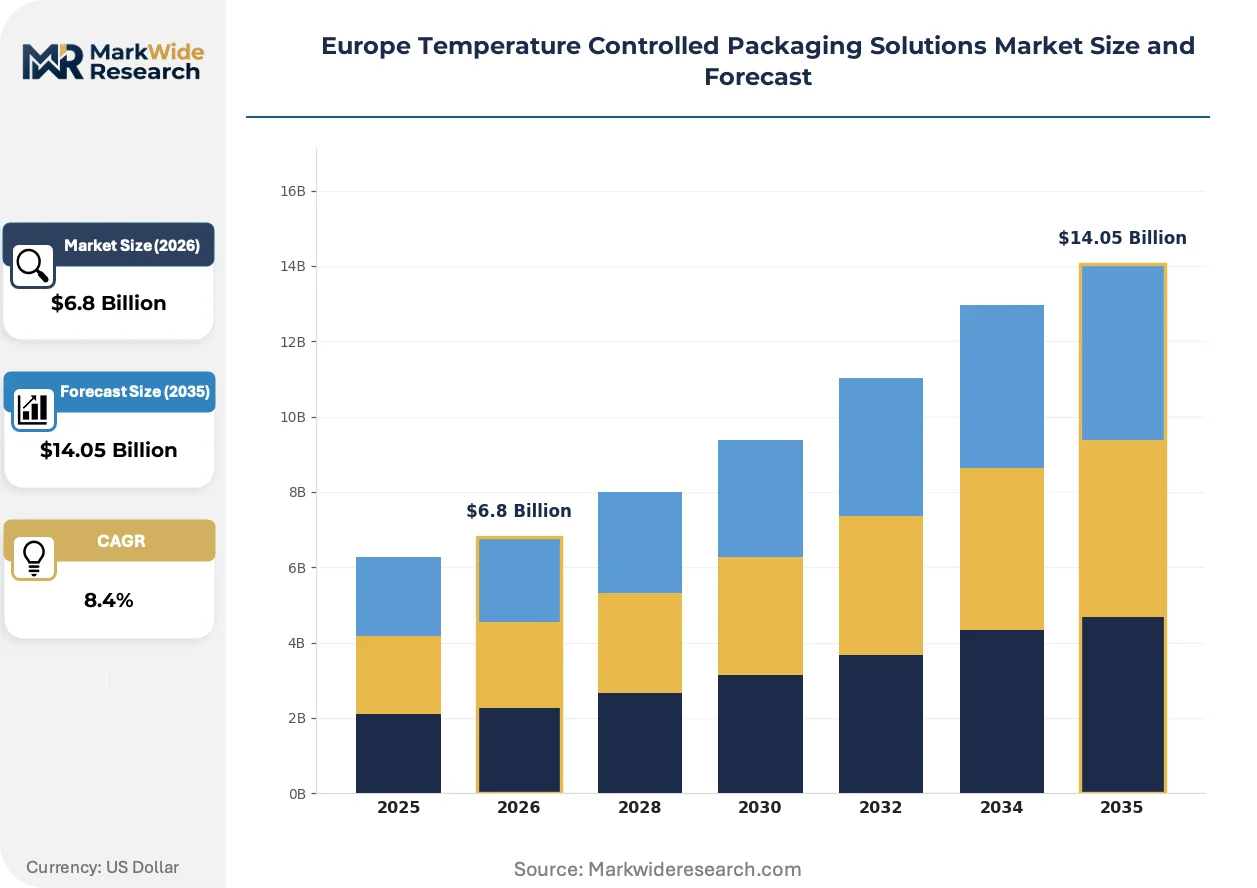
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Containers, Refrigerated Pallets, Active Packaging, Phase Change Materials End User: Healthcare, Food & Beverage, Pharmaceuticals, Biotechnology Technology: Thermal Insulation, Refrigeration, Vacuum Insulation, Active System Application: Transport, Storage, Distribution, Cold Chain Management |
| Companies Covered | Softbox Systems, Intelsius, Sonoco ThermoSafe, Sofrigam SA, Envirotainer, Pelican BioThermal, va-Q-tec AG, Tempack Packaging Solutions, Cold Chain Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Temperature Controlled Packaging Solutions Market Shifts & Advancements
Active electronic cooling systems are displacing passive phase change materials across Europe's highest-value pharmaceutical lanes, while regulatory pressure on synthetic refrigerants accelerates material science investment in bio-based thermal management solutions.
Vacuum insulation panel technology is collapsing the dimensional footprint required for ultra-low temperature shipments, enabling pharmaceutical distributors to maximize payload density in air freight configurations. Cell and gene therapy manufacturers in Germany and Switzerland are adopting these systems at accelerating rates for international clinical trial material movements. The structural consequence is compressing competitive differentiation around thermal performance per unit volume rather than absolute temperature maintenance duration.
The EU F-Gas Regulation is eliminating hydrofluorocarbon refrigerants from active cooling systems by 2030, forcing manufacturers toward hydrocarbon and carbon dioxide-based alternatives with modified safety protocols. Industrial consequence includes elevated engineering costs for explosion-proof compressor designs and recertification of existing product platforms. Ultra-low temperature container segments serving mRNA vaccine distribution are most affected, with German and Dutch manufacturers accelerating R&D spending on natural refrigerant architectures.
Pharmaceutical procurement functions are consolidating supplier relationships around full-service cold chain partners capable of lane validation, data analytics, and carbon reporting. Third-party logistics providers with integrated packaging and monitoring capabilities are displacing standalone container vendors across high-volume vaccine distribution contracts. This concentration is most visible in German and Belgian hub operations where integrated service contracts now dominate tender processes for temperature-sensitive biologics.
Europe Temperature Controlled Packaging Solutions Market Segmentation
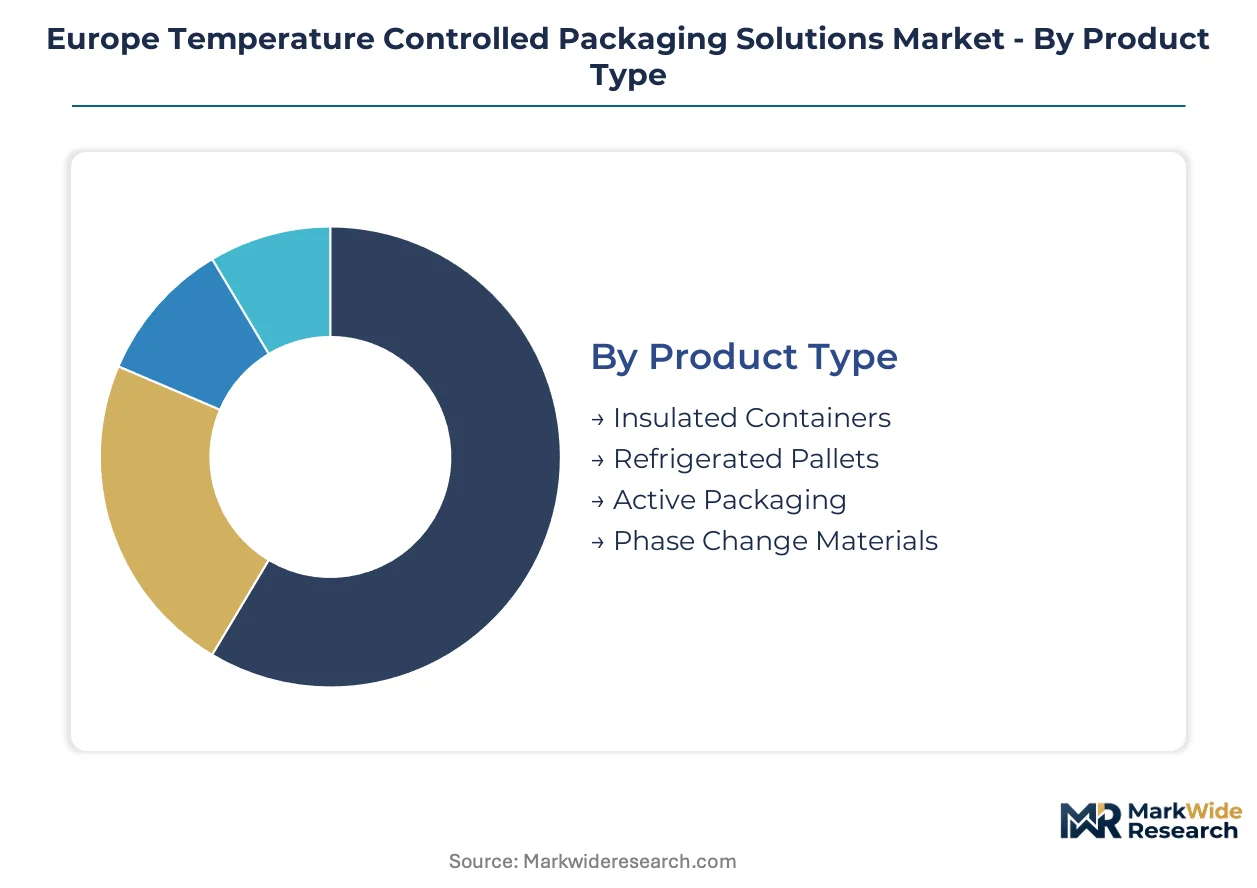
Temperature controlled packaging solutions fragment across multiple technical and commercial dimensions. Each segmentation axis carries distinct qualification requirements, margin profiles, and regulatory touchpoints that reshape supplier positioning across European pharmaceutical corridors.
Product Type:
After-sales service intensity varies sharply across product categories, with active systems demanding continuous calibration support while passive containers require minimal field intervention.
- Insulated Containers:Expanded polystyrene and polyurethane foam assemblies provide passive thermal protection for parcel and bulk shipments. German vaccine distribution hubs in Bavaria drive concentrated demand for lane-validated configurations with embedded data loggers.
- Active Packaging:Electronic cooling systems with compressor-based or thermoelectric refrigeration maintain precise temperature bands without phase change material limitations. Cell and gene therapy manufacturers in Switzerland and Germany are adopting these platforms for ultra-low temperature stability requirements.
- Refrigerated Pallets:Bulk thermal management platforms for high-volume pharmaceutical movements between centralized distribution nodes.
- Phase Change Materials:Eutectic salt hydrate and paraffin formulations that absorb or release latent heat at specific temperature setpoints.
Insulated containers holds the largest share; momentum sits with active packaging.
End User:
Margin concentration aligns with validation burden, where GDP documentation requirements create substantial switching costs for qualified suppliers.
- Pharmaceuticals:Vaccine and biologic manufacturers require validated thermal systems with complete temperature documentation across distribution nodes. EMA GDP enforcement mandates embedded monitoring, elevating demand for qualified packaging configurations in German and Belgian hub operations.
- Biotechnology:Cell and gene therapy developers need ultra-low temperature stability between minus eighty and minus one hundred fifty degrees Celsius. Swiss and German advanced therapy medicinal product manufacturers drive adoption of vacuum insulation panel systems for international clinical trial material movements.
- Healthcare:Hospital and clinical laboratory networks requiring temperature-assured specimen transport.
- Food & Beverage:Perishable logistics operators with less stringent documentation requirements than pharmaceutical corridors.
Pharmaceuticals commands the deepest margin pools; biotechnology is climbing the fastest.
Technology:
Supply concentration for core materials creates divergent scaling economics across thermal management approaches.
- Vacuum Insulation:Fumed silica or glass fiber cores sealed in metallized polymer barriers deliver exceptional thermal resistance per unit thickness. German and Austrian specialty manufacturers control core material production, creating input bottlenecks during demand surges for ultra-low temperature shipments.
- Thermal Insulation:Expanded polystyrene and polyurethane foam barriers provide cost-effective passive protection for standard pharmaceutical lanes.
- Refrigeration:Vapor-compression or absorption cooling systems for active temperature maintenance.
- Active System:Integrated electronic cooling with autonomous power management and telemetry connectivity.
Vacuum insulation leads on performance density; active systems are gaining share fastest.
Application:
Operational intensity and asset utilization patterns reshape total cost of ownership calculations across deployment modes.
- Cold Chain Management:Integrated temperature assurance across pharmaceutical supply chain nodes with continuous monitoring and intervention protocols. Third-party logistics providers in Germany and Belgium consolidate procurement around full-service partners capable of lane validation and carbon reporting under CSRD requirements.
- Distribution:Hub-to-hub bulk movements requiring qualified bulk thermal containers with centralized documentation.
- Transport:Parcel and freight configurations for last-mile and international lane movements.
- Storage:Stationary thermal protection for inventory holding and staging operations.
Cold chain management captures the highest service attach rates; distribution shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in temperature-sensitive logistics, connecting Bavarian vaccine production zones to North Sea and Mediterranean distribution gateways.
Germany
Bavarian mRNA manufacturing clusters and North Rhine-Westphalian distribution hubs generate concentrated demand for lane-validated bulk thermal containers. EMA GDP enforcement mandates embedded data loggers across all pharmaceutical nodes. Frankfurt and Cologne anchor continental cold chain operations with direct air freight connectivity to global clinical trial networks.
France
Parisian biopharma headquarters and Lyon-based logistics providers sustain demand for qualified passive packaging systems. REACH chemical compliance from ECHA restricts certain phase change material formulations, forcing supplier reformulation. The Île-de-France region concentrates procurement decisions for multinational vaccine distribution contracts.
Switzerland
Basel's pharmaceutical headquarters and Geneva's international organizations drive premium demand for ultra-low temperature stability systems. Swissmedic maintains stringent validation protocols exceeding baseline EMA requirements. Zürich and Basel host specialized engineering talent for vacuum insulation panel development serving cell therapy shipments.
Netherlands
Rotterdam's port infrastructure and Schiphol's air cargo hub position the country as a continental consolidation point for temperature-sensitive imports. EU F-Gas Regulation compliance deadlines accelerate hydrocarbon cooling system adoption among Dutch equipment lessors. The Randstad logistics corridor integrates packaging, monitoring, and customs clearance for pharmaceutical re-exports.
Belgium
Brussels' regulatory proximity to EMA headquarters elevates demand for GDP-qualified configurations with complete documentation trails. The country's dense pharmaceutical warehousing infrastructure supports hub-and-spoke distribution across Western Europe. Antwerp and Liège host third-party logistics providers consolidating procurement around integrated cold chain service contracts.
Europe Temperature Controlled Packaging Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying insulation cores, phase change materials, and electronic cooling modules. The vendor base stratifies between full-service cold chain partners capable of lane validation and standalone container fabricators competing on unit economics. Three archetypes dominate: German engineering-led vacuum insulation panel developers, French passive system specialists, and multinational active cooling platform providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as pharmaceutical procurement consolidates around integrated service providers.
Among Germany-based engineering specialists, va-Q-tec AG exemplifies vacuum insulation panel leadership for ultra-low temperature applications. Sofrigam SA occupies a position within the French passive system tier, representing specialized capacity in phase change material assemblies. Pelican BioThermal anchors the multinational active cooling segment, exemplifying reusable platform strategies across European pharmaceutical corridors.
| Leading Market Players |
|---|
| Softbox Systems |
| Intelsius |
| Sonoco ThermoSafe |
| Sofrigam SA |
| Envirotainer |
| Pelican BioThermal |
| va-Q-tec AG |
| Tempack Packaging Solutions |
| Cold Chain Technologies |
| Others |
Supply & Pricing Matrix
The Rhine-Main-Danube corridor's freight cost dynamics compress margins for German vacuum insulation panel manufacturers while elevating price differentiation between lane-validated and commodity thermal packaging tiers across Bavarian vaccine distribution hubs.
Pricing Analysis
Volume-discount tiering structures separate GDP-qualified configurations with embedded data loggers from standard insulated containers, with certification grade and after-sales calibration bundling as primary price differentiation drivers. Cost compression in passive foam systems intensifies because REACH-compliant phase change material reformulations extend R&D cycles. Pharmaceutical procurement teams show lowest price sensitivity due to switching costs from EMA validation documentation, while food and beverage logistics operators prioritize unit economics over qualification depth.
Supply Chain Analysis
Contract manufacturing for vacuum insulation panel cores concentrates among German and Austrian specialty producers, with fumed silica supply and metallized polymer barrier films as critical input dependencies. Single-source vulnerability runs through Bavarian VIP core production during demand surges for ultra-low temperature cell therapy shipments. Distribution runs through third-party logistics providers in Belgium and the Netherlands consolidating procurement around integrated cold chain service contracts with lane validation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Temperature controlled packaging solutions represent a service-attach opportunity where lane validation and carbon reporting under CSRD expand faster than hardware unit sales, creating recurring revenue layers with superior margin profiles.
For Market Incumbents: Entrench GDP-qualified market positions by deepening backward integration into phase change material formulation to offset REACH-driven supply disruption, while expanding calibration service networks across Eastern European distribution corridors to capture CSRD carbon accounting attach revenue from pharmaceutical shippers facing documentation mandates. For New Entrants and Emerging Players: Establish a beachhead in Polish and Czech Republic greenfield distribution hubs where qualified cold chain infrastructure remains underdeveloped, targeting mid-size biotech firms with hybrid active-passive thermal platforms that bypass the twelve-to-eighteen-month EMA validation timelines encumbering incumbent systems. For Investors and Strategic Acquirers: Component specialists with captive vacuum insulation panel technology and embedded data logger integration capabilities offer the strongest acquisition profile for platform consolidation, with thermal engineer scarcity in retiring German workforces serving as the critical inflection signal for R&D capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Lane Validation Service Expansion | Captures CSRD-driven carbon reporting attach revenue from Belgian pharmaceutical shippers. |
| Natural Refrigerant R&D Investment | Positions Dutch active cooling manufacturers ahead of EU F-Gas Regulation elimination deadlines. |
| Central European Hub Development | Addresses underdeveloped reverse logistics infrastructure for reusable containers in Poland. |
| Vacuum Insulation Panel Capacity Addition | Relieves input bottlenecks for ultra-low temperature cell therapy shipments from Swiss manufacturers. |
| Autonomous Monitoring Device Integration | Aligns with EU AI Act traceability mandates for retrofit markets across German vaccine distribution networks. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with cold chain operations directors, pharmaceutical procurement leads, EMA regulatory affairs specialists, and thermal packaging R&D engineers; and secondary validation through EMA GDP guidance documents, EU F-Gas Regulation compliance filings, REACH substance restriction updates, and customs trade data for insulated container imports. Bottom-up shipment volume modeling and top-down pharmaceutical logistics expenditure estimates were cross-referenced to establish market sizing boundaries.
Forecast inputs considered product type segmentation across passive and active thermal systems, technology tiers from expanded polystyrene through vacuum insulation panels, and end-use concentration in pharmaceutical versus biotechnology corridors across the analysis window. CAGRs were derived from regression analysis against biopharmaceutical cold chain expenditure trends and vaccine production capacity expansion in German manufacturing clusters, with scenario weighting for F-Gas Regulation compliance cost trajectories.
Sensitivities concentrate around EMA GDP enforcement intensity, REACH chemical restriction scope expansion, and vacuum insulation panel supply concentration disruption. Forecasts reflect documented assumptions regarding cell therapy commercialization rates and pharmaceutical procurement consolidation timelines. Quarterly review of EMA qualification protocol updates, thermal engineer workforce demographics, and CSRD implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Cohesive Packaging Solutions Market