
 Corrugated Packaging Software Market | 2026-2036
Corrugated Packaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Packaging Software Market Analysis
EU Packaging and Packaging Waste Regulation is recalibrating compliance costs for converters serving cross-border retail chains. Esko-Graphics B.V. leverages prepress automation to anchor its position among European corrugated designers. Amtech Software Inc. specializes in estimating modules that sustain margin visibility for mid-tier independent box plants. Aicomp Group competes through ERP-native architectures that reduce implementation friction for packaging converters.
Corrugated packaging software encompasses design, production planning, inventory management, and order processing applications that optimize fiber-based container manufacturing through automated nesting, die-line generation, and real-time equipment scheduling. These systems typically interface with CAD/CAM workflows and corrugator controls to minimize trim waste while enforcing burst-strength and edge-crush specifications for load-bearing performance. Cloud-based deployment is expanding fastest among multi-plant distributors seeking centralized visibility without on-premises infrastructure overhead. Production planning modules concentrate margin pools where just-in-time grocery replenishment demands sub-four-hour turnaround windows.
FDA traceability mandates for food-contact packaging and EPA fiber sourcing documentation requirements shape software feature roadmaps for US-facing suppliers. REACH compliance obligations in Europe and China's GB standards for recycled content labeling further fragment specification engines across export corridors. Stakeholders must weigh modular SaaS architectures against deep ERP integration as regulatory granularity intensifies.
Market Dynamics
Automated box-sizing algorithms are compressing turnaround windows for e-commerce fulfillment centers, forcing converters to restructure production planning modules around sub-four-hour delivery commitments rather than traditional batch optimization.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Documentation mandates for recyclability credentials are pulling traceability software into converter workflows across Germany, France, and the Netherlands.
- Automotive supply contracts:ISO-compliant nesting optimization requirements from German folding carton exporters are accelerating CAD/CAM integration investments.
- Cloud deployment:Multi-plant distributors are abandoning on-premises infrastructure for centralized visibility, expanding SaaS subscription pools.
Market Restraints
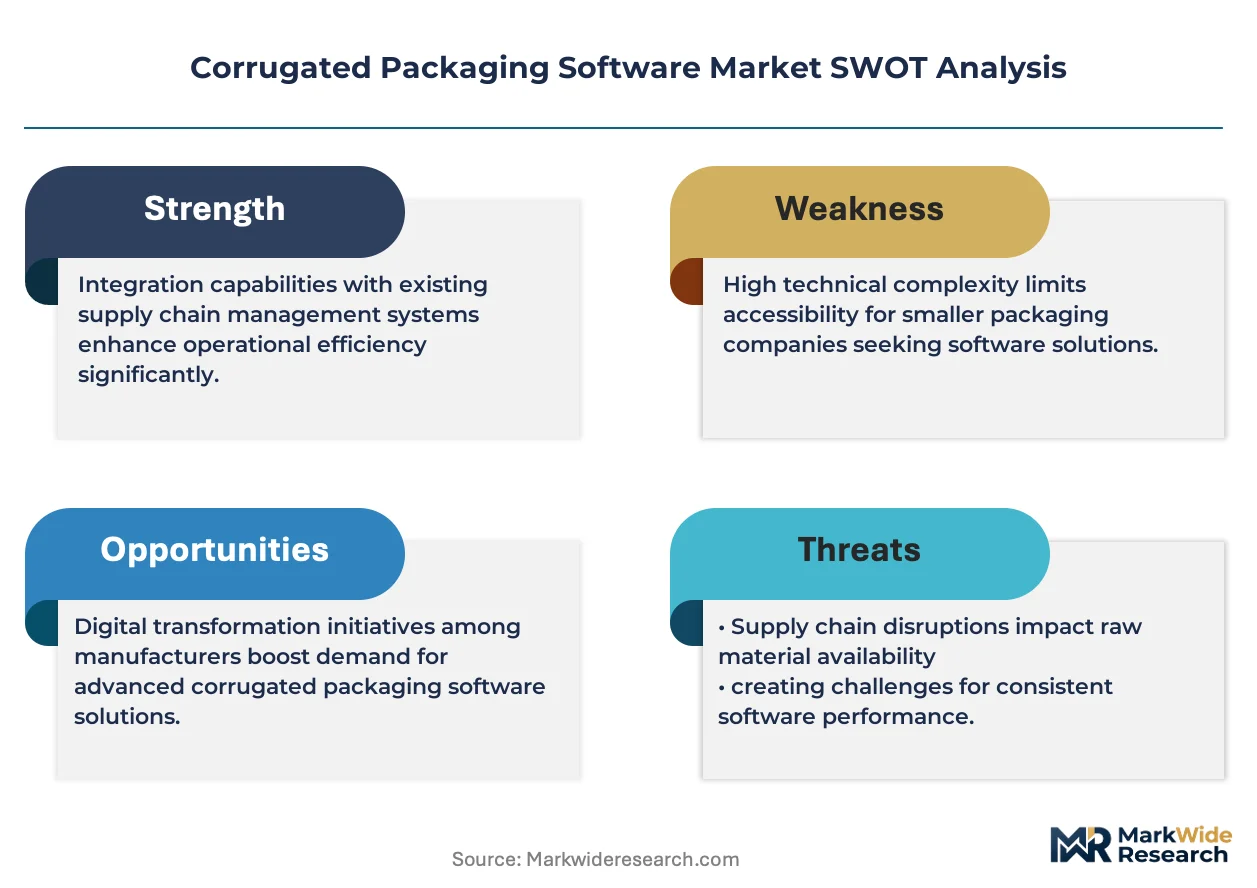
- Corrugator control integration costs:Retrofitting legacy production lines with real-time scheduling interfaces demands capital outlays that mid-tier independents struggle to absorb.
- Regulatory fragmentation:REACH compliance in Europe, FDA traceability for US food-contact packaging, and China's GB standards for recycled content labeling force parallel specification engines.
- Substitute materials:Rigid plastic containers and molded fiber alternatives are capturing share in temperature-sensitive pharmaceutical logistics.
Strategic Opportunities
- India's e-commerce logistics:Underpenetrated fulfillment infrastructure in tier-2 cities creates whitespace for automated box-sizing deployments.
- CE marking convergence:The EU AI Act is creating compliance software demand for quality-control algorithms in corrugator vision systems.
- Pharmaceutical cold chain:Temperature-validated corrugated designs are opening subscription revenue for thermal-performance simulation modules.
Industry Challenges
- CAD/CAM specialist scarcity:Die-line automation engineers command premium wages, constraining rollout velocity for nesting optimization tools.
- ERP integration complexity:Packaging converters running legacy SAP or Oracle instances face 12-18 month implementation timelines for modular SaaS overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Packaging Software Market |
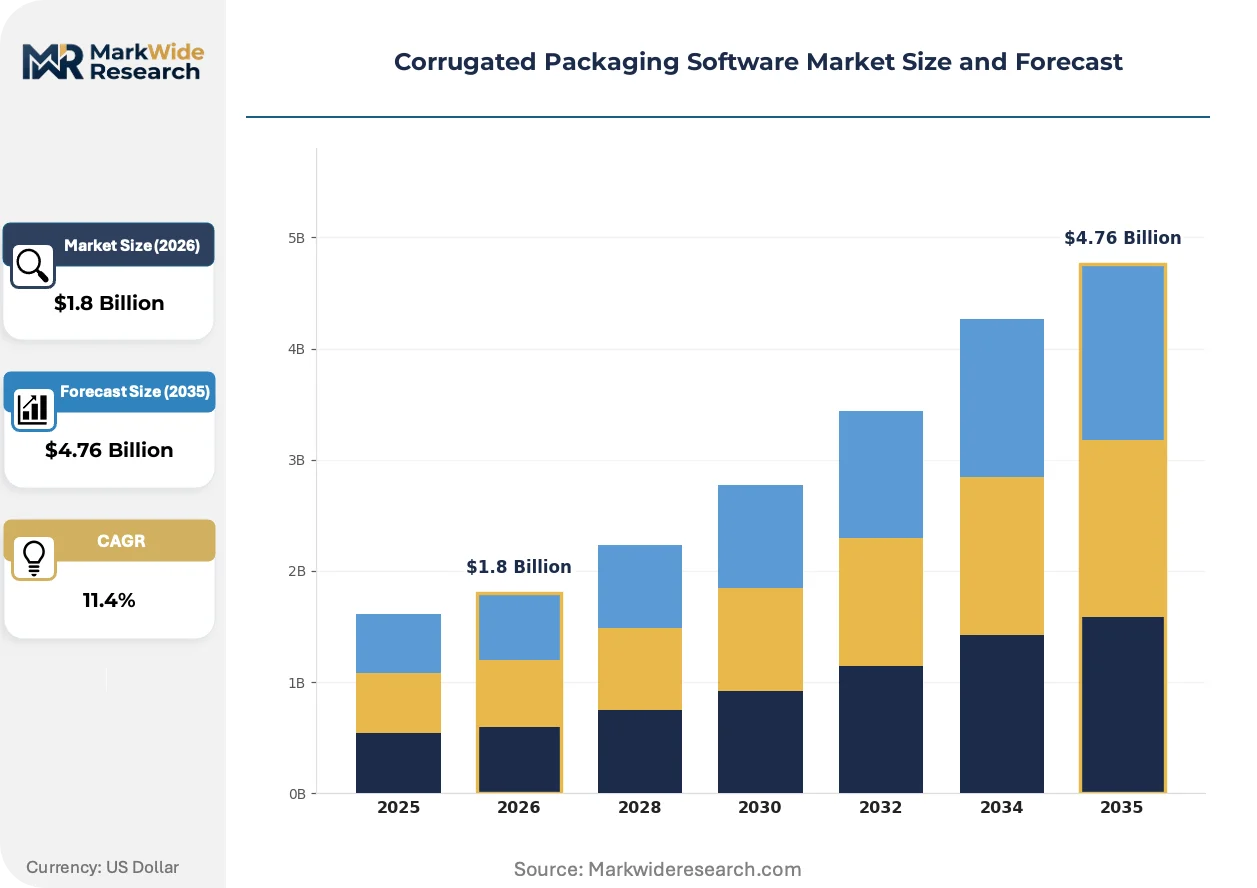
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Inventory Management, Order Processing, Production Planning End User: Manufacturers, Distributors, Retailers, Wholesalers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Integration Level: ERP, CRM, Supply Chain Management, Retail Systems |
| Companies Covered | Abaca Systems Ltd., Aicomp Group, Amtech Software Inc., Arden Software Ltd., Electronics for Imaging, Inc., Esko-Graphics B.V., Kiwiplan, Inc., Sistrade Software Consulting, SA, theurer.com GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Packaging Software Market Emerging Trajectories
Machine learning is penetrating corrugated design workflows, compressing the gap between structural simulation and live production feedback. Three developments are restructuring competitive capability.
Generative design algorithms for flute optimization are converging with cloud-based finite element analysis. E-commerce fulfillment centers in Germany and the Netherlands are deploying these tools within six-month procurement cycles. The technology is converging with automated quoting engines, collapsing the traditional 48-hour estimate window to under four hours.
REACH substance-of-very-high-concern screening is forcing reformulation of adhesives and coatings used in food-contact corrugated. Converters serving EU retail chains must now document SVHC-free credentials through software traceability layers. German automotive suppliers are responding by mandating ISO-compliant nesting certificates from folding carton vendors.
Subscription pricing for production planning modules is displacing perpetual license models among mid-tier independent box plants. Tier-2 distributors in India and Southeast Asia are adopting monthly SaaS arrangements to avoid upfront capital deployment. The shift is most visible in grocery replenishment networks where volume volatility makes fixed-cost software ownership uneconomical.
Corrugated Packaging Software Market Segmentation
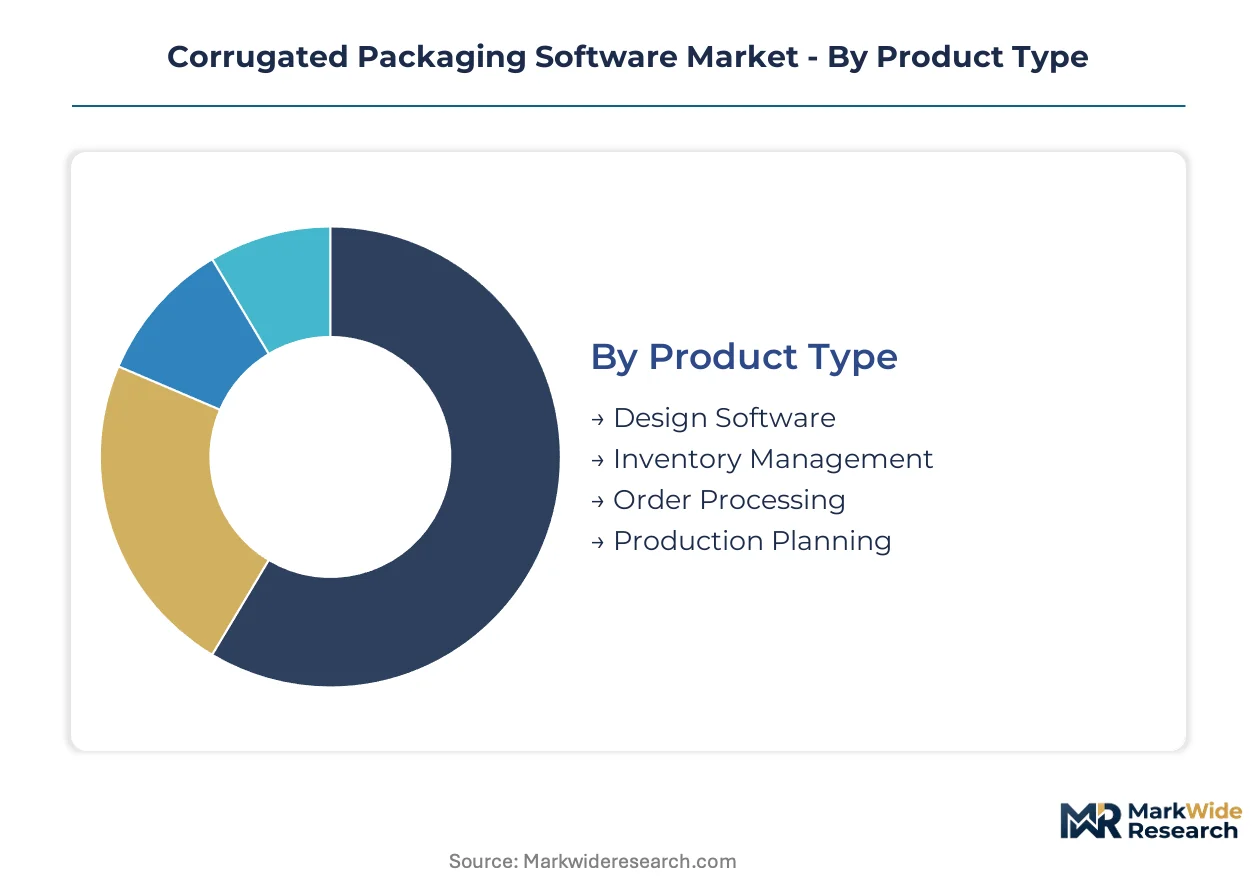
Corrugated packaging software buyers segment their procurement decisions around deployment risk tolerance, integration complexity, and the cadence of their order-to-delivery cycles. Each dimension carries distinct vendor selection criteria and implementation timelines.
Product Type:
Purchase decisions hinge on whether the buyer seeks point solutions or integrated suites spanning the manufacturing workflow.
- Production Planning:Real-time corrugator scheduling algorithms synchronize machine availability with die-line requirements. German automotive suppliers demand sub-four-hour turnaround commitments from folding carton vendors, compressing batch optimization into continuous flow logic.
- Design Software:CAD/CAM modules generate flute-optimized structures validated through finite element analysis. E-commerce fulfillment centers in the Netherlands deploy generative algorithms within accelerated procurement cycles to collapse traditional 48-hour estimate windows.
- Inventory Management:Fiber stock visibility tools track reel consumption against burst-strength specifications. Mid-tier independent box plants adopt these modules to sustain margin visibility during volatile linerboard pricing cycles.
- Order Processing:Automated quoting engines interface with customer portals to translate structural requirements into production-ready specifications. Tier-2 distributors in India favor monthly SaaS arrangements to avoid upfront capital deployment.
Production Planning leads on scale; Design Software leads on momentum.
End User:
Volume concentration and technical sophistication vary sharply across buyer categories, shaping vendor pricing architectures and support commitments.
- Manufacturers:Converters require deep ERP-native architectures that reduce implementation friction across multi-plant operations. REACH compliance obligations force parallel specification engines for EU-facing production lines.
- Distributors:Multi-plant operators abandon on-premises infrastructure for centralized cloud visibility. Grocery replenishment networks drive subscription revenue where volume volatility makes fixed-cost ownership uneconomical.
- Retailers:Cross-border retail chains demand software traceability layers documenting recyclability credentials under EU Packaging and Packaging Waste Regulation.
- Wholesalers:Volume aggregators prioritize modular SaaS overlays compatible with legacy SAP or Oracle instances despite 12-18 month implementation timelines.
Manufacturers anchor revenue concentration; Distributors are expanding most quickly.
Deployment:
Capital constraints and IT maturity determine whether buyers absorb infrastructure costs or shift risk to subscription models.
- Cloud-Based:Centralized deployment eliminates on-premises infrastructure overhead for multi-plant distributors. FDA traceability mandates for food-contact packaging shape feature roadmaps for US-facing cloud vendors.
- SaaS:Monthly subscription pools expand fastest among mid-tier independent box plants seeking to avoid corrugator control integration capital outlays. Tier-2 cities in India present whitespace for automated box-sizing deployments.
- On-Premises:Legacy installations persist where data sovereignty requirements or specialized equipment interfaces demand local control. Retrofitting costs constrain adoption among capital-constrained independents.
- Hybrid:Split architectures accommodate sensitive production data on-site while leveraging cloud analytics for demand forecasting. CE marking convergence under EU AI Act creates compliance software demand for quality-control algorithms.
Cloud-Based deployment leads on scale; SaaS shows the steepest expansion trajectory.
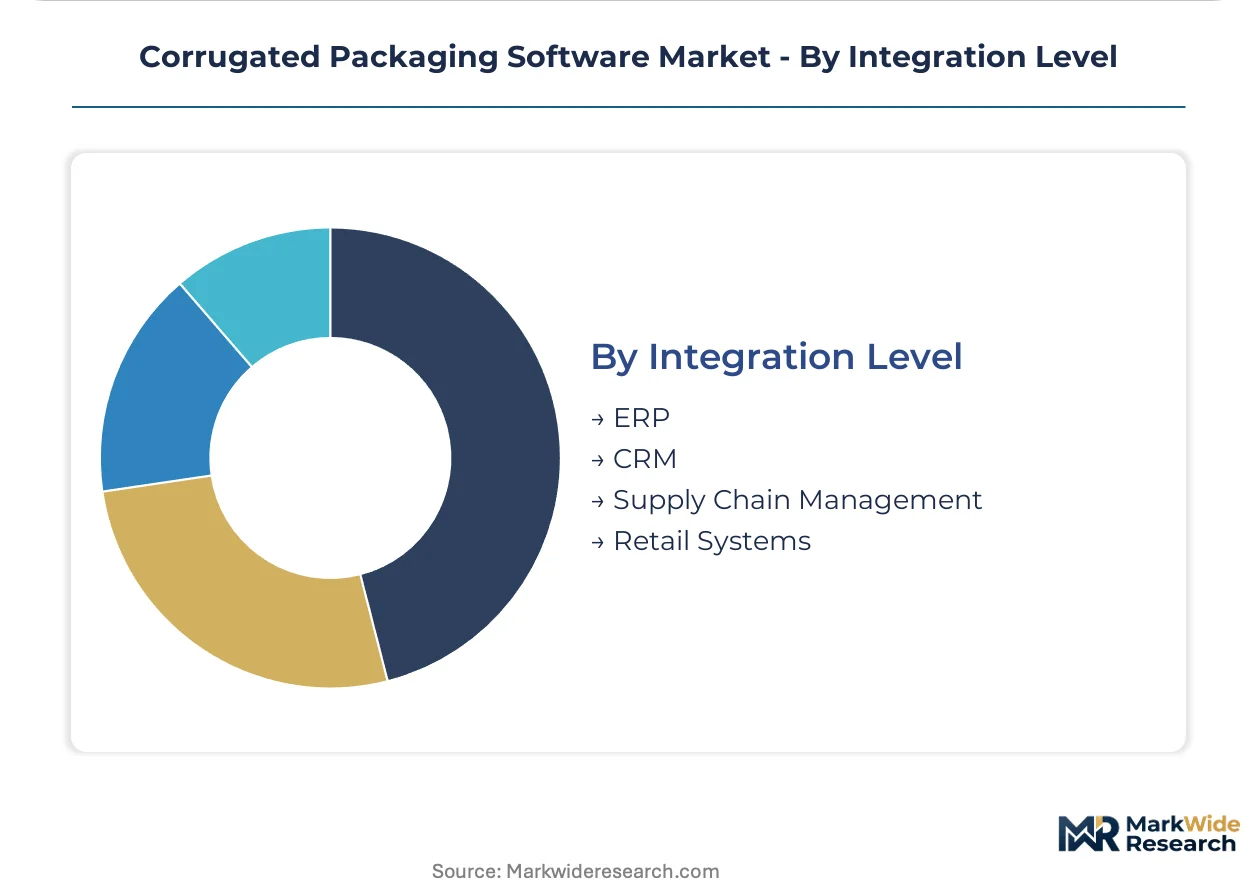
Integration Level:
System interoperability requirements escalate with buyer scale and supply chain complexity.
- ERP:Native integration with SAP or Oracle instances dominates large converter procurement. ISO-compliant nesting optimization requirements from German automotive suppliers accelerate CAD/CAM integration investments.
- Supply Chain Management:End-to-end visibility modules connect corrugator outputs with downstream logistics. Temperature-validated corrugated designs open subscription revenue for thermal-performance simulation in pharmaceutical cold chains.
- CRM:Customer-facing modules align quoting engines with account-specific die-line libraries. Die-line automation engineer scarcity constrains rollout velocity for nesting optimization tools.
- Retail Systems:Direct integration with retailer procurement platforms enables automated replenishment triggers. EPA fiber sourcing documentation requirements shape feature roadmaps for US-facing suppliers.
ERP integration leads on scale; Supply Chain Management gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging automation engineers concentrate in Germany's industrial belt, India's software corridors, and the US Midwest manufacturing triangle. These talent pools anchor regional capability clusters that shape procurement patterns for corrugated packaging software.
Germany
Automotive supply contracts from Stuttgart and Munich drive ISO-compliant nesting optimization demand. REACH substance-of-very-high-concern screening forces adhesive documentation through software traceability layers. The Baden-Württemberg converter cluster around Heilbronn deploys generative design algorithms within compressed procurement cycles.
United States
FDA traceability mandates for food-contact packaging accelerate cloud feature roadmaps among Midwest distributors. EPA fiber sourcing documentation requirements shape specification engines for export-facing suppliers. Chicago-area fulfillment centers compress turnaround windows below four hours through automated box-sizing deployments.
India
Tier-2 city e-commerce logistics create whitespace for automated quoting engines in Bangalore and Hyderabad corridors. BIS standards for recycled content labeling force parallel specification engines for domestic versus export production. Maharashtra's folding carton exporters adopt monthly SaaS arrangements to avoid upfront capital deployment.
Netherlands
E-commerce fulfillment centers in Rotterdam port zones deploy cloud-based finite element analysis within six-month cycles. EU Packaging and Packaging Waste Regulation documentation mandates pull traceability software into converter workflows across the Randstad. Eindhoven-region distributors abandon on-premises infrastructure for centralized visibility.
China
GB standards for recycled content labeling fragment specification engines across Pearl River Delta export corridors. MIIT dual carbon goals pressure converters to document energy-efficient production through software layers. Shenzhen-area fulfillment infrastructure drives automated box-sizing adoption among cross-border retail suppliers.
Corrugated Packaging Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments. The vendor base organizes around three strategic archetypes: ERP-native platform providers, CAD/CAM workflow specialists, and estimating module developers. Consolidation pressure intensifies as mid-tier independents seek integrated suites over point solutions. Dominant competitive moves include strategic partnerships with corrugator control vendors and geographic expansion through SaaS subscription models.
Among European prepress automation specialists, Esko-Graphics B.V. occupies a position exemplifying CAD/CAM workflow integration, while theurer.com GmbH represents German engineering-focused platform development. Amtech Software Inc. anchors the North American estimating module tier. These three entities illustrate how geographic origin and company structure correlate with strategic positioning across the ERP-native, design-specialist, and margin-visibility archetypes.
| Leading Market Players |
|---|
| Abaca Systems Ltd. |
| Aicomp Group |
| Amtech Software Inc. |
| Arden Software Ltd. |
| Electronics for Imaging, Inc. |
| Esko-Graphics B.V. |
| Kiwiplan, Inc. |
| Sistrade Software Consulting, SA |
| theurer.com GmbH |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up CAD/CAM specialists anchor supply discipline across Germany and the Netherlands, compressing pricing power for modular SaaS entrants while sustaining premium tiers for ERP-native incumbents serving automotive supply chains. This ownership concentration tightens margin visibility for mid-tier independent box plants forced to choose between perpetual license absorption and subscription flexibility.
Pricing Analysis
Bundled ERP-native suites command premium positioning against unbundled point solutions. Subscription SaaS tiers separate enterprise-grade corrugator integration from standard design modules. Pricing pressure stems from tier-2 distributors in India adopting monthly arrangements to bypass upfront capital deployment. Mid-tier independent box plants exhibit highest price sensitivity; German automotive suppliers demonstrate lowest sensitivity due to ISO-compliant nesting mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke fulfillment patterns for cloud-based software delivery. Supply concentrates in Germany, the Netherlands, and India. Raw material dependencies include linerboard pricing cycles, die-line automation engineering talent, and corrugator control hardware. Single-source vulnerability around CAD/CAM specialist scarcity elevates implementation timelines. Distribution runs through direct vendor relationships and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrugated packaging software market functions as a regulatory compounder where EU Packaging and Packaging Waste Regulation documentation mandates continuously expand addressable demand for traceability layers.
For Market Incumbents: Deepen ERP-native integration architectures to defend against modular SaaS disintermediation. Prioritize backward integration into corrugator control interfaces to capture scheduling algorithm revenue pools. Certify ISO-compliant nesting engines to retain German automotive supplier contracts against REACH-driven adhesive reformulation pressures. For New Entrants and Emerging Players: Tier-2 city e-commerce logistics operators in India represent the most penetrable buyer archetype. Deploy automated quoting engines through monthly SaaS arrangements to bypass capital constraints. Target pharmaceutical cold chain thermal-performance simulation as a subscription wedge against established production planning incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among estimating module developers lacking CAD/CAM workflow integration. Long-term viability favors ERP-native platforms with multi-plant distributor footprints. Watch CE marking convergence under EU AI Act as the inflection signal for quality-control algorithm compliance software demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-native architectures reduce 12-18 month implementation friction for legacy SAP converters. |
| Geographic Expansion | SaaS subscription models penetrate tier-2 Indian cities without upfront infrastructure deployment. |
| Strategic Partnership | Corrugator control vendor alliances anchor real-time scheduling algorithm distribution. |
| Acquisition of Specialist Firm | Die-line automation engineering talent scarcity favors CAD/CAM capability roll-ups. |
| Product Launch | Thermal-performance simulation modules capture pharmaceutical cold chain subscription revenue. |
Methodological Framework
Multiple input streams — converter operations directors, ERP implementation specialists, corrugator control engineers, and SaaS procurement officers — were reconciled against trade association filings, customs software export data, and EU regulatory documentation databases. Secondary validation drew from ECHA REACH substance databases, FDA food-contact packaging guidance, and BIS recycled content standards. Bottom-up deployment estimates and top-down market sizing were triangulated across the analysis window.
Data-stream reconciliation anchored volume and value outputs across deployment model, integration complexity, end-user scale, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic fiber demand indicators. Industry-specific forecast inputs included e-commerce fulfillment center buildout pipelines and automotive supply contract renewal cycles.
Inputs from primary stakeholder interviews were available through the study window; gaps in privately-held mid-tier independent box plant financial disclosure introduce uncertainty bands around SaaS adoption trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and corrugator control hardware refresh cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Decoys and Dispensers Market