
 Europe Contract Packaging Market | 2026-2036
Europe Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Contract Packaging Market Foresight
Pharma-grade serialization compliance is collapsing the gap between commodity packagers and certified specialists. Budelpack Poortvliet BV leverages its Netherlands-based pharma infrastructure to capture EU-wide serialization contracts. Smurfit Kappa anchors the corrugated segment through integrated paper-to-box manufacturing across multiple European countries. Mondi Group differentiates via sustainable flexible packaging R&D aligned with EU Green Deal targets.
Europe contract packaging encompasses third-party execution of primary and secondary packaging operations, including bottle filling, blister sealing, cartoning, and aggregation for track-and-trace, performed under client specifications and quality agreements. The process demands ISO 15378-compliant cleanroom environments for pharmaceutical work and HACCP-certified lines for food contact materials. Flexible packaging leads in volume terms due to lightweighting trends in food and personal care, while rigid packaging commands premium margins in pharmaceutical applications requiring child-resistant and senior-friendly closures. Assembly services within the service type category represent the fastest-expanding segment as brands outsource complex kitting and promotional bundling to reduce fixed labor costs.
EMA serialization mandates under the Falsified Medicines Directive and REACH chemical disclosure requirements reshape material selection and line-validation protocols for contract packagers. EU Packaging and Packaging Waste Regulation recycling targets force converters to verify post-consumer content claims through accredited third-party certification. Stakeholders must weigh serialization capital expenditure against the risk of losing pharma contracts to competitors with pre-validated EU hub operations.
Market Dynamics
EMA serialization mandates under the Falsified Medicines Directive are compressing the supplier base by disqualifying uncertified packagers from pharmaceutical contracts. This regulatory pressure is accelerating capital deployment toward EU hub operations with pre-validated aggregation lines.
Growth Catalysts
- REACH chemical disclosure:Brand owners outsource material compliance verification to contract packagers with accredited testing laboratories and documented substance inventories.
- Germany's industrial packaging clusters:Central European distribution networks concentrate demand around Rhine-Ruhr and Bavarian logistics corridors, creating density economies for secondary packaging operations.
- EU Green Deal packaging targets:Post-consumer recycled content mandates drive converters to partner with specialized flex-pack innovators capable of certified circular material sourcing.
Market Restraints
- Resin price volatility:Polypropylene and polyethylene input costs swing with naphtha-cracker margins, compressing flexible packaging contract profitability during upstream spikes.
- Equipment supplier concentration:German and Italian serialization line manufacturers command 18-24 month delivery backlogs, constraining packager expansion timelines.
- Pharma-grade cleanroom capex:ISO 15378-compliant facility construction requires €15-25 million per greenfield site, erecting barriers to tier-2 packager upgrading.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated CEE markets offer first-mover positioning for pharma serialization hubs serving eastward EU distribution corridors.
- Reusable packaging systems:E-commerce return-loop logistics create demand for durable tertiary packaging with embedded RFID tracking and automated sortation compatibility.
- CSRD supply-chain disclosure:Corporate sustainability reporting mandates position contract packagers as Scope 3 data aggregators for brand-owner carbon accounting.
Industry Challenges
- Serialization engineer scarcity:Qualified validation specialists for EU hub aggregation systems command 40% wage premiums, stretching mid-cap packager payroll structures.
- Legacy MES integration:Pharmaceutical clients demand seamless data handoffs between contract packager line-execution systems and their own ERP platforms, requiring costly middleware development.
- Multi-site certification stagger:Achieving synchronized EU-wide GMP approvals across distributed packaging networks extends contract onboarding timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Contract Packaging Market |
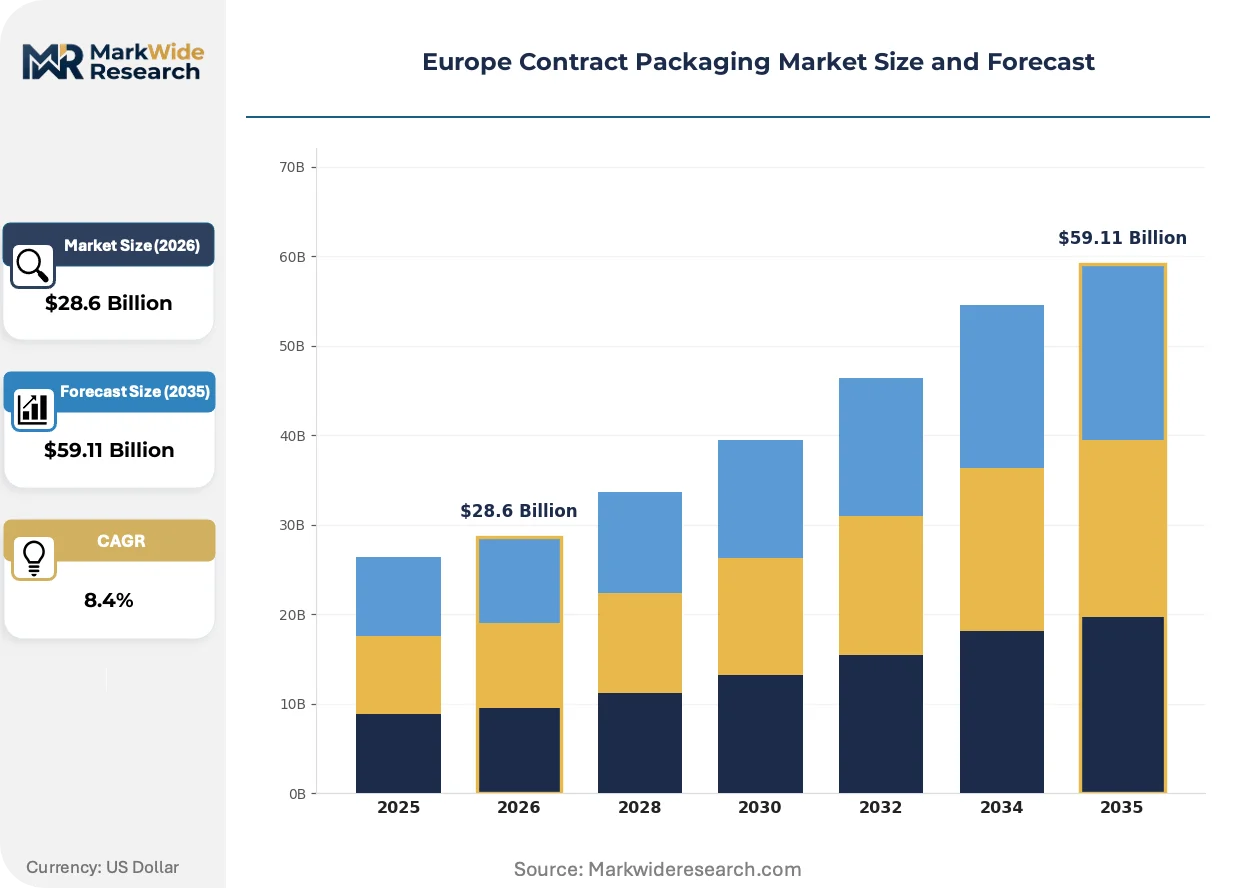
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Labels, Shrink Sleeves End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Service Type: Assembly, Filling, Cartoning, Labeling Packaging Material: Plastic, Glass, Metal, Paper |
| Companies Covered | Budelpack Poortvliet BV, Complete Co-Packaging Services Ltd., Driessen United Blenders, Harke Packserve GMBH, Cygnia Logistics Ltd, Kompak Co-Making & Co-Packing, Marvinpac SA, Mondi Group, Smurfit Kappa, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Contract Packaging Market Shifts & Advancements
Digital watermarking and blockchain-enabled provenance tracking are reconfiguring how brand owners verify packaging authenticity across fragmented EU supply chains. These technologies compress the window between detection and response for counterfeit infiltration.
Monolayer polyethylene films with embedded digital watermarks are supplanting multi-material laminates in food contact applications. Retailers in France and the Netherlands are mandating adoption for private-label dry goods. This shift enables single-stream mechanical recycling without separation infrastructure, collapsing sorting costs for municipal waste operators.
EU Packaging and Packaging Waste Regulation recycling targets are forcing converters to verify post-consumer content claims through accredited third-party certification. Packagers must now maintain chain-of-custody documentation from flake sourcing through finished film. Pharmaceutical and personal care segments face the steepest compliance ramps due to stringent migration testing requirements for recycled polymers.
Brand-owner procurement teams are consolidating vendor panels around full-service contract packagers with integrated design-to-distribution capabilities. This pattern displaces fragmented sourcing across specialized primary, secondary, and logistics providers. German automotive and industrial chemical sectors exhibit the most advanced consolidation, with three-year framework agreements replacing spot contracting for seasonal promotional cycles.
Europe Contract Packaging Market Segmentation
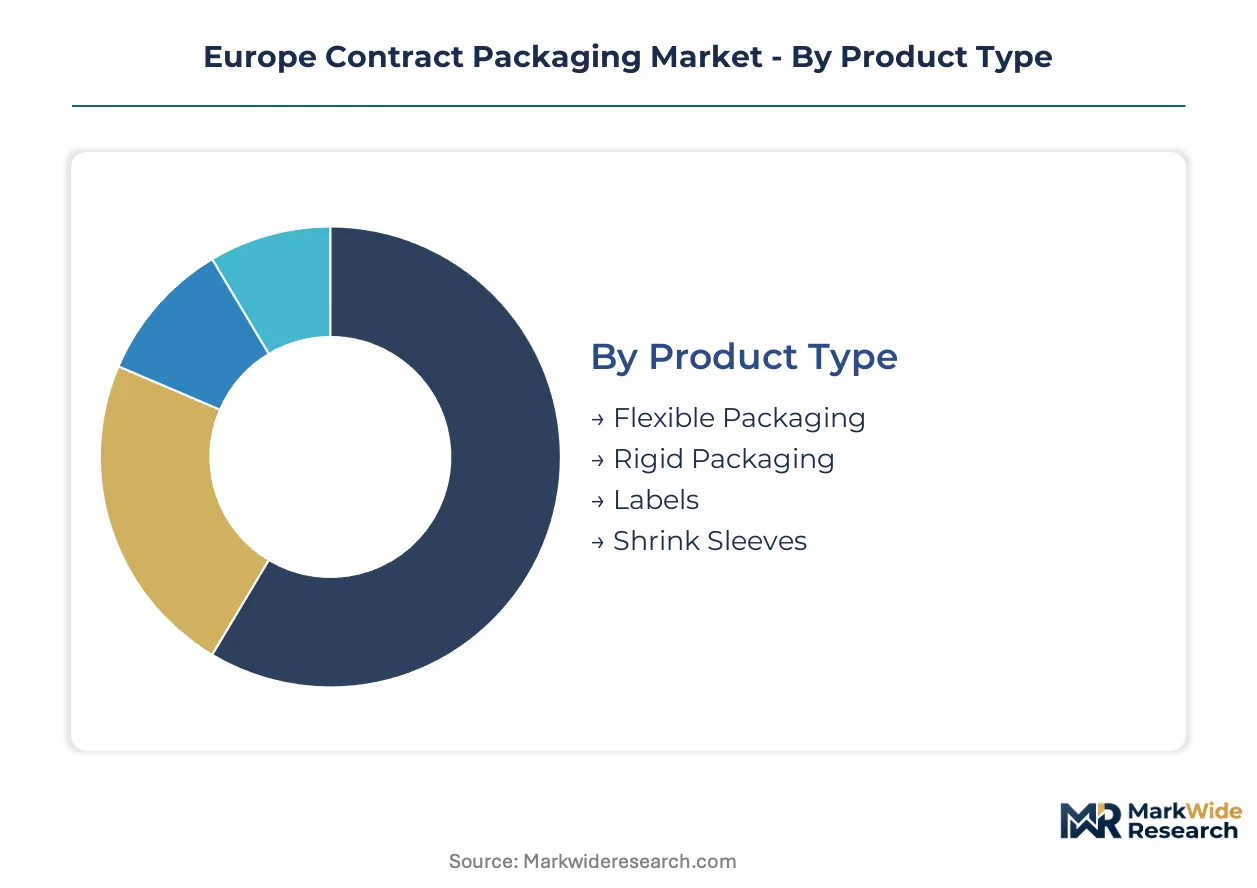
Packaging format selection in Europe hinges on EMA serialization mandates, REACH substance restrictions, and EU Packaging and Packaging Waste Regulation recycling targets. Each segment faces distinct substitution pressures from sustainable alternatives and regulatory compliance costs.
Product Type:
Flexible packaging faces the most acute substitution pressure as monolayer polyethylene films with digital watermarks displace multi-material laminates in French and Dutch retail private-label programs.
- Flexible Packaging:Lightweight polyethylene and polypropylene films dominate food and personal care applications. German discount retailers and Dutch supermarket chains are mandating single-material formats to enable mechanical recycling without separation infrastructure, collapsing municipal sorting costs.
- Rigid Packaging:Polyethylene terephthalate bottles, polypropylene jars, and polystyrene containers command premium margins in pharmaceutical applications requiring child-resistant and senior-friendly closures. REACH chemical disclosure requirements favor packagers with accredited testing laboratories and documented substance inventories.
- Labels:Pressure-sensitive and in-mold varieties carry serialization data and anti-counterfeiting features for EU track-and-trace compliance.
- Shrink Sleeves:Polyethylene terephthalate glycol and polylactic acid films provide 360-degree branding coverage with tamper-evident properties for beverage and cosmetics applications.
Flexible packaging retains volume leadership; assembly services within broader contract offerings hold the steepest expansion curve.
End User:
Cost tier stratification separates pharma-grade serialization operations from commodity food and beverage packaging, with certification grade determining contract pricing bands.
- Food & Beverage:The largest demand pool by unit volume, spanning ambient, chilled, and frozen supply chains. HACCP-certified lines are mandatory for EU food contact materials, with German and French brand owners consolidating vendor panels around full-service packagers with integrated design-to-distribution capabilities.
- Pharmaceuticals:ISO 15378-compliant cleanroom environments and pre-validated aggregation lines for Falsified Medicines Directive compliance. Budelpack Poortvliet BV and similar Netherlands-based operators capture EU-wide serialization contracts through hub-and-spoke validation networks.
- Cosmetics:Premium positioning demands sustainable material sourcing aligned with EU Green Deal targets, including post-consumer recycled content verification through accredited third-party certification.
- Electronics:Anti-static and moisture-barrier protection for sensitive components, with ESD-safe handling protocols required for Central European manufacturing supply chains.
Food and beverage commands absolute volume; pharmaceuticals deliver the highest margin per unit.
Service Type:
Application complexity determines outsourcing depth, with brands retaining strategic control over formulation while delegating execution to certified operators.
- Assembly:Complex kitting, promotional bundling, and multi-component product configuration. This segment is expanding most quickly as brands seek to reduce fixed labor costs and eliminate seasonal hiring cycles.
- Filling:Liquid, powder, and semi-solid dispensing into primary containers under GMP or food-grade protocols. German industrial packaging clusters around Rhine-Ruhr and Bavarian logistics corridors concentrate demand for high-throughput automated lines.
- Cartoning:Secondary packaging into folded carton or corrugated cases with leaflet insertion and coding for aggregation.
- Labeling:Application of primary, secondary, and tertiary labels with variable data printing for lot tracking and regulatory compliance.
Assembly services gain share fastest; filling operations anchor revenue stability through long-term pharmaceutical contracts.
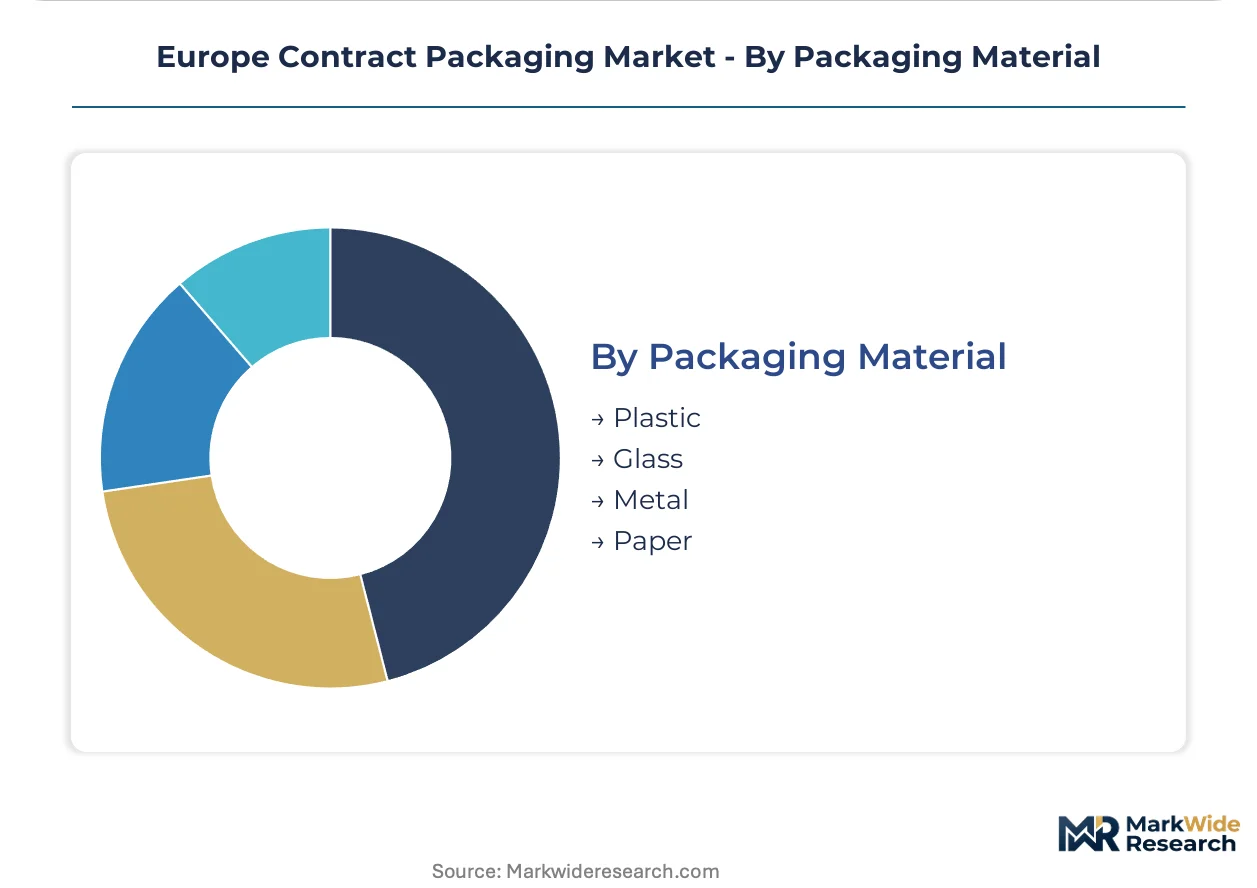
Packaging Material:
Supply concentration in petrochemical feedstocks and recycled flake markets shapes material substitution economics across converter networks.
- Plastic:Polyolefins and polyethylene terephthalate dominate flexible and rigid formats. Resin price volatility tied to naphtha-cracker margins compresses contract profitability during upstream spikes.
- Glass:Pharmaceutical and premium cosmetics applications requiring inert, impermeable barriers with established recycling infrastructure in Germany and France.
- Metal:Aluminum and steel for aerosols, tins, and barrier protection in food and industrial chemical segments.
- Paper:Corrugated and folding carton from integrated paper-to-box manufacturing networks. Smurfit Kappa anchors this segment across multiple European countries.
Plastic maintains volume dominance; paper formats climb fastest on e-commerce and sustainability tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports contract packaging services throughout Central and Eastern Europe, with Rhine-Ruhr and Bavarian logistics corridors serving as primary distribution nodes for pharmaceutical and industrial chemical clients.
Germany
Industrial packaging clusters around Rhine-Ruhr and Bavaria concentrate demand for high-throughput automated lines serving automotive and chemical sectors. REACH compliance verification requirements push brand owners toward packagers with accredited ECHA-aligned testing laboratories. Stuttgart-based operations anchor premium pharmaceutical serialization contracts under Falsified Medicines Directive mandates.
Netherlands
Rotterdam-Antwerp port logistics create density economies for secondary packaging operations targeting Benelux and North Sea distribution networks. EU Green Deal packaging targets accelerate adoption of monolayer polyethylene formats with digital watermarks for mechanical recycling. Budelpack Poortvliet BV leverages pharma infrastructure to capture EU-wide serialization hub contracts.
France
Paris Basin and Lyon corridor demand concentrates around cosmetics and luxury goods requiring sustainable material sourcing with post-consumer recycled content verification. ANSM pharmaceutical regulations align with EMA serialization mandates for track-and-trace compliance. French retailers mandate digital watermark adoption for private-label dry goods, collapsing municipal sorting costs.
Poland
Warsaw and Krakow industrial zones offer underpenetrated CEE positioning for pharma serialization hubs serving eastward EU distribution corridors. Lower labor costs attract assembly and kitting operations seeking to reduce fixed overhead structures. Polish converters develop certified circular material sourcing partnerships to meet EU Packaging and Packaging Waste Regulation recycling targets.
United Kingdom
London-Southeast corridor and Midlands manufacturing bases sustain demand for food-grade HACCP-certified lines and corrugated e-commerce packaging. Post-Brexit regulatory divergence from EMA creates parallel validation requirements for pharmaceutical contract packagers. Smurfit Kappa anchors integrated paper-to-box manufacturing networks across British industrial zones.
Europe Contract Packaging Market Competitive Landscape
Listed leaders compete with private specialists across capital access and regulatory certification dimensions, producing a tiered structure where scale advantages concentrate in paper-based formats while pharma-grade operations fragment across national validation networks. Three archetypes dominate: integrated paper converters with captive fiber supply, pharma-certified cleanroom operators with pre-validated aggregation lines, and regional flex-pack innovators with circular material sourcing capabilities. Competitive moves center on M&A for geographic hub expansion and strategic partnerships for recycled content certification.
Within the pharma-certified tier, Budelpack Poortvliet BV and Marvinpac SA exemplify operators leveraging Netherlands and Swiss infrastructure for EU-wide serialization contracts. Among integrated paper converters, Smurfit Kappa and Mondi Group occupy positions spanning corrugated and flexible formats with sustainability-aligned R&D capabilities. These named entities represent archetypal strategies rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Budelpack Poortvliet BV |
| Complete Co-Packaging Services Ltd. |
| Driessen United Blenders |
| Harke Packserve GMBH |
| Cygnia Logistics Ltd |
| Kompak Co-Making & Co-Packing |
| Marvinpac SA |
| Mondi Group |
| Smurfit Kappa |
| Others |
Supply & Pricing Matrix
Long-term framework agreements with pharmaceutical brand owners lock in multi-year serialization capacity reservations and insulate certified packagers from resin price volatility. These contracts tether pricing visibility to EMA compliance timelines and aggregate volume commitments across Germany, the Netherlands, and France.
Pricing Analysis
Current-generation monolayer polyethylene formats with digital watermarks command modest premiums over prior-generation multi-material laminates, while next-generation bio-based barrier films remain pre-commercial. Three-tier pricing structure across pharma-grade, food-grade, and industrial-grade certification levels separates contract bands. Cost compression in flexible packaging is intensifying because German discount retailers are consolidating vendor panels around full-service operators. Food and beverage brand owners exhibit highest price sensitivity due to thin margins and seasonal volume swings, whereas pharmaceutical clients prioritize compliance assurance over unit cost.
Supply Chain Analysis
Rotterdam-Antwerp port throughput serves as the critical chokepoint for European resin imports and recycled flake distribution, with congestion rippling through converter networks within 48 hours. Supply concentrates in Germany for pharmaceutical-grade cleanroom equipment, Italy for serialization line manufacturing, and Belgium for masterbatch compounding. Raw material dependencies span polypropylene from naphtha crackers, post-consumer PET flake from German bottle-to-bottle recyclers, and specialty adhesives from Swiss chemical suppliers. Single-source vulnerability sits with German and Italian equipment manufacturers commanding 18-24 month delivery backlogs. Distribution runs through Rhine-Ruhr logistics corridors for Central European pharmaceutical clients and Benelux port networks for North Sea export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national validation networks creates acquisition opportunities as EMA serialization mandates force brand owners to diversify supplier bases beyond incumbent hubs.
For Market Incumbents: Secure pre-validated aggregation capacity in Poland and Czech Republic before serialization engineer wage premiums spread eastward. Consolidate regional flex-pack innovators with accredited circular material certification to defend against Smurfit Kappa and Mondi Group sustainability positioning. Backward integration into post-consumer flake sourcing insulates margin structures from resin volatility. For New Entrants and Emerging Players: EMA hub certification fast-track through Netherlands-based partnership models collapses validation timelines for CEE market entry. Target pharmaceutical serialization contracts in Warsaw and Krakow industrial zones where incumbent presence remains thin. Position around reusable packaging systems with embedded RFID tracking for e-commerce return-loop logistics as the go-to-market wedge. For Investors and Strategic Acquirers: Pharma-certified cleanroom operators with EU-wide aggregation networks represent the priority acquisition archetype for platform roll-up strategies. Long-term viability hinges on serialization compliance permanence and CSRD supply-chain disclosure mandates expanding contract packager data-aggregator roles. Watch for Polish converter certification acceleration as the inflection signal for CEE market maturation.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Hub Certification Expansion | Pre-validated aggregation lines in Poland capture eastward pharma distribution corridors before competitor saturation. |
| Backward Integration into Recycled Flake | Captive post-consumer PET sourcing from German bottle-to-bottle recyclers locks in EU Green Deal compliance margins. |
| Serialization Engineer Talent Acquisition | Qualified validation specialists for EU hub systems command wage premiums that strain mid-cap payroll structures. |
| Reusable Packaging System Development | Durable tertiary formats with RFID tracking align with e-commerce return-loop logistics and automated sortation requirements. |
| CSRD Data Aggregator Positioning | Contract packagers capture Scope 3 carbon accounting roles as brand-owner sustainability reporting mandates expand. |
Research Methodology
Operator-level perspectives from pharmaceutical packaging directors, serialization validation engineers, brand-owner procurement leads, and corrugated plant managers anchored the qualitative base. These primary interviews combined with secondary validation from EMA regulatory filings, REACH substance inventory databases, EU Packaging and Packaging Waste Regulation implementation guidance, and customs trade data for resin and recycled flake flows. Bottom-up capacity modeling across converter networks triangulated against top-down demand aggregation from pharmaceutical, food, and cosmetics end-use sectors.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios, serialization compliance deadline shifts, and CEE market penetration rates. Segmentation dimensions spanned packaging format, service type, end-use industry, and regional regulatory cluster. CAGRs derived from unit volume trajectories and value-per-unit compression curves across the analysis window. Industry-specific inputs included EMA aggregation line installation timelines and post-consumer recycled content verification throughput rates.
The analysis sits within stated boundaries; outcomes outside sustained EMA enforcement intensity or abrupt REACH substance restriction expansions would require recalibration. Forecasts reflect assumptions about serialization capital deployment continuity and German industrial packaging cluster density persistence. Revision becomes warranted when Polish pharma serialization hub certification velocity crosses thresholds indicating CEE market tipping point acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Sterilized Packaging Market