
 Custom Packaging Market | 2026-2036
Custom Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Packaging Market Analytics
Subscription-based packaging design services is restructuring how converters monetize client relationships beyond unit sales. Smurfit Kappa Group leverages its integrated paper and recycling network to control fiber supply costs. ProAmpac specializes in flexible packaging for perishable goods, anchoring its position in food safety applications. Huhtamaki competes through regional manufacturing density that reduces logistics spend for multinational brands.
Custom packaging denotes engineered containers, wraps, and protective structures manufactured to dimensional, graphic, and functional specifications set by individual brand owners, typically involving substrates between 0.2 mm and 6 mm caliper with print resolutions of 150–300 lpi. Flexible packaging leads volume across pharmaceutical blister films and snack pouch formats where barrier properties and lightweighting reduce material intensity. Rigid packaging dominates cosmetics and premium spirits where structural embossing and weighted closures signal quality positioning. Sustainable packaging commands margin premiums as paper-based alternatives displace multi-layer plastics in electronics and personal care channels.
FDA food contact substance notifications govern barrier coatings in U.S. food packaging, while EPA hazardous waste rules shape solvent-based ink disposal practices for domestic converters. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that shift recycling costs to brand owners, altering procurement specifications. REACH chemical restrictions limit certain adhesive chemistries in European supply chains. Stakeholders must monitor how state-level recycled content mandates in California and Washington propagate through national brand packaging briefs.
Market Dynamics
Subscription-based packaging design services are restructuring converter monetization beyond unit sales, while the EU Packaging and Packaging Waste Regulation tightens material recovery targets that reshape procurement specifications across brand owner relationships.
Growth Catalysts
- E-commerce fulfillment expansion:Protective packaging formats gain traction in United States distribution centers handling fragile electronics and cosmetics. Demand concentrates in automated sortation hubs requiring dimensional optimization.
- REACH chemical restrictions:European adhesive chemistry limitations accelerate migration toward water-based and bio-derived alternatives. Converters reformulate barrier coatings to maintain food contact compliance under EFSA frameworks.
- Dual carbon goals:China's MEE enforcement drives paper-based substitution in coastal export manufacturing clusters. Brand owners specify renewable substrates to satisfy procurement mandates from multinational headquarters.
Market Restraints
- Recycled fiber cost volatility:OCC price swings compress converter margins during demand surges from corrugated competitors. Smurfit Kappa's integrated recycling network insulates against spot market exposure.
- Multi-layer plastic technical lock-in:High-barrier pharmaceutical blister films resist paper substitution due to moisture and oxygen ingress requirements. FDA notification timelines extend reformulation cycles.
- California recycled content mandates:State-level compliance costs propagate through national brand packaging briefs, forcing dual specification tracks. Washington's parallel requirements compound procurement complexity.
Strategic Opportunities
- India PLI scheme alignment:Electronics manufacturing incentives in Gujarat and Tamil Nadu create packaging demand from smartphone and component exporters. Local converter capacity remains underdeveloped against import substitution targets.
- Smart packaging convergence:NFC-enabled and temperature-indicating formats merge with flexible substrates for pharmaceutical cold chain verification. Early adoption centers on insulin and biologic distribution networks.
- Extended producer responsibility tailwinds:EU member state EPR schemes shift recycling cost accountability to brand owners, creating design-for-recyclability consulting revenue streams for technical converters.
Industry Challenges
- Structural embossing talent scarcity:Skilled die-making and tooling design for premium spirits closures concentrates in aging workforce pockets across Bavaria and Emilia-Romagna. Knowledge transfer gaps threaten quality consistency.
- Digital print capex intensity:Single-pass inkjet systems for 150–300 lpi food packaging require eight-figure investments with extended payback periods. Mid-cap converters face financing constraints against integrated multinational competitors.
- FDA food contact substance notification timelines:Barrier coating approvals stretch 18–24 months, delaying new product launches and locking formulations to legacy chemistries. Parallel EPA hazardous waste rules complicate solvent-based ink transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Packaging Market |
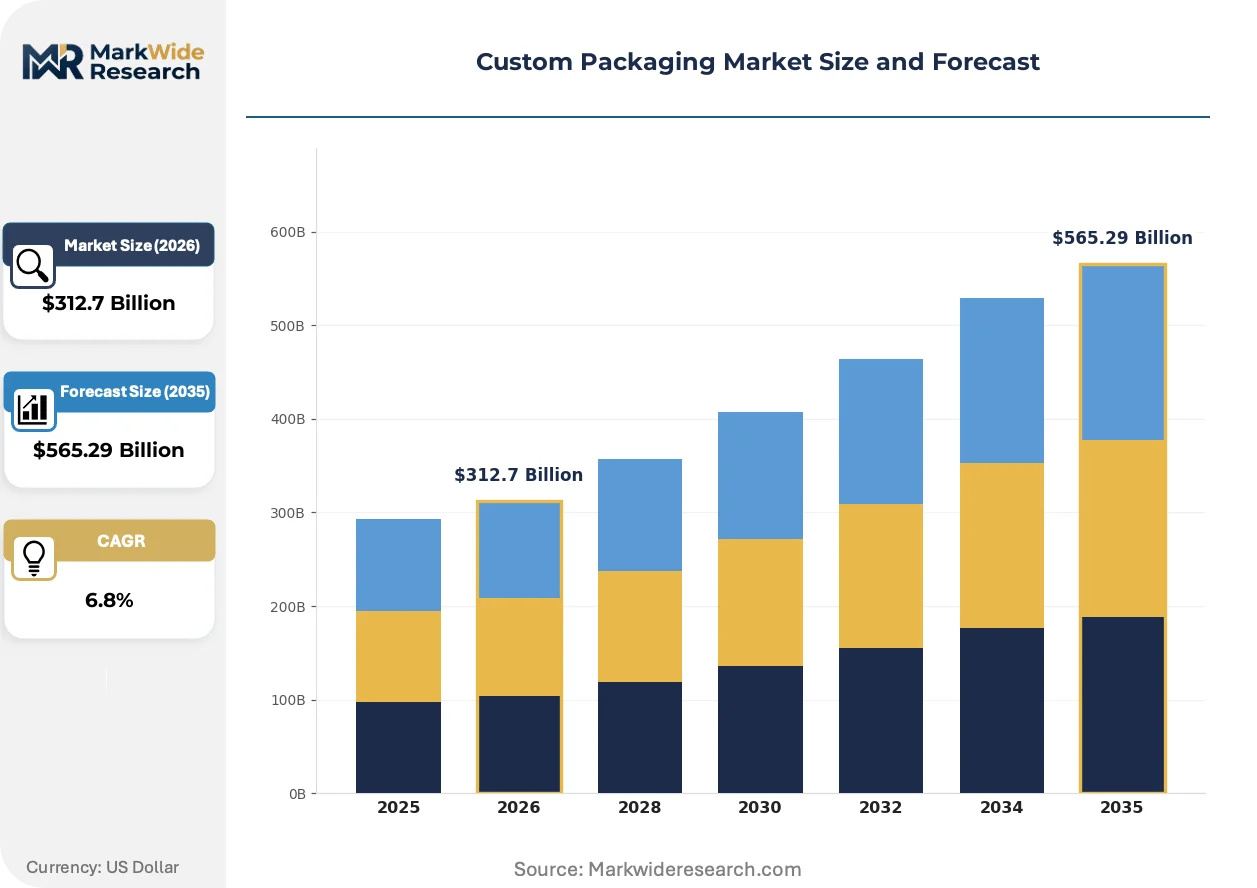
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Packaging, Protective Packaging, Sustainable Packaging Material: Plastic, Glass, Metal, Paper End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Distribution Channel: Online Sales, Retail Outlets, Direct Sales, Wholesale |
| Companies Covered | Smurfit Kappa Group, ProAmpac, Huhtamaki, DS Smith, Amcor plc, Westrock Company, Sonoco Products Company, International Paper, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Packaging Market Evolving Landscape
Digital print workflows and smart substrate integration are compressing design-to-delivery cycles while regulatory chemical restrictions force material science reinvention across barrier and adhesive layers.
Water-based flexographic ink systems are overtaking solvent-based alternatives in snack pouch and pharmaceutical blister applications. Mid-sized converters serving perishable goods segments adopt these platforms to eliminate EPA hazardous waste disposal liabilities. The transition compresses regulatory compliance costs while enabling faster job changeovers for shorter-run customization.
EU Packaging and Packaging Waste Regulation extended producer responsibility schemes reallocate recycling infrastructure financing to brand owners rather than municipal systems. This shifts procurement specifications toward mono-material and readily separable multi-layer constructions. Premium cosmetics and personal care channels in Germany and France lead specification changes ahead of enforcement deadlines.
Direct-to-brand design platforms are fragmenting traditional agency-converter relationships. Subscription-based packaging services let mid-market brands access structural engineering and print production without minimum volume commitments. This model concentrates initial uptake among direct-to-consumer startups in California and New York metro corridors seeking rapid iteration cycles.
Custom Packaging Market Segmentation
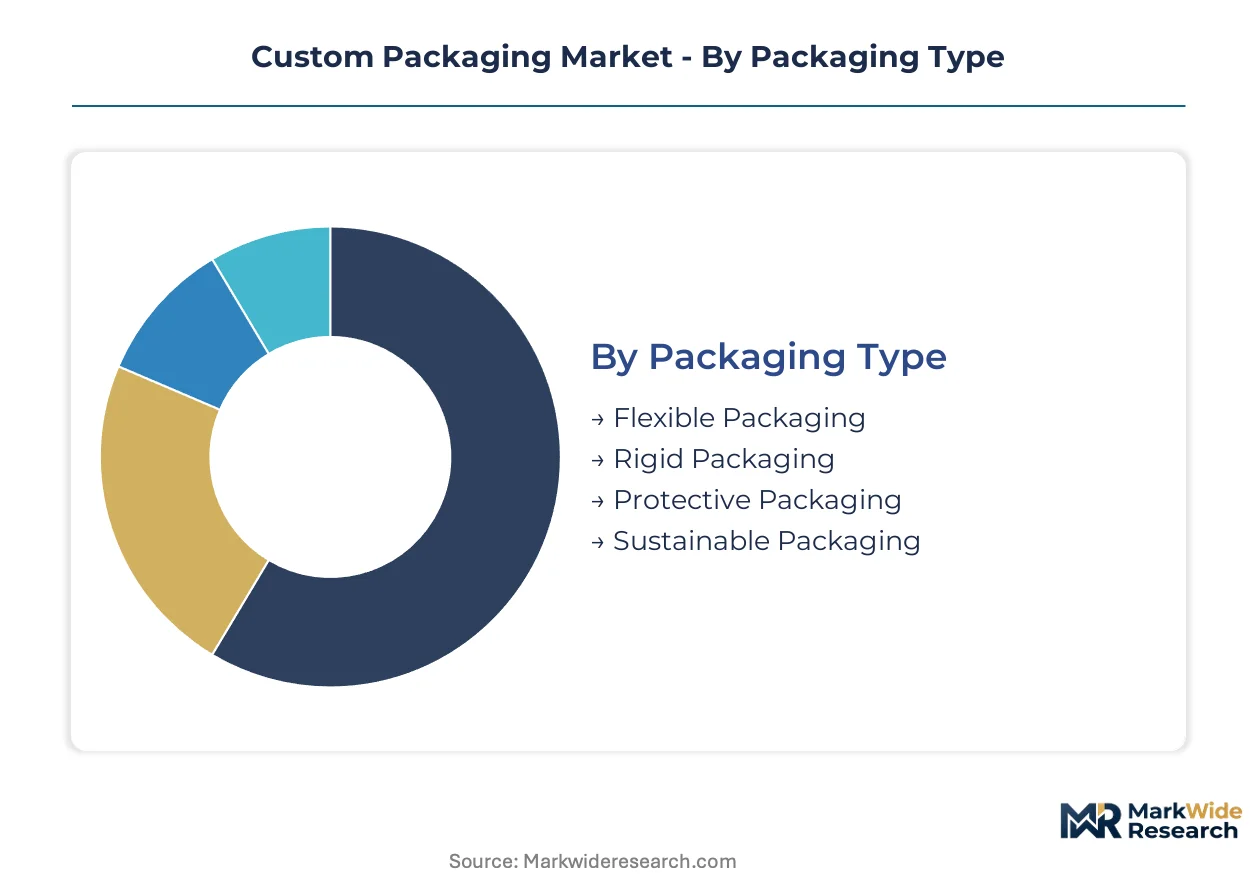
Segmentation in custom packaging reveals how specification depth, material selection, and channel configuration determine margin capture. Brand owners prioritize dimensional precision and graphic fidelity differently across end-use categories, forcing converters to align equipment investments with demand concentration patterns.
Packaging Type:
Customization intensity varies sharply across this category, from engineered structural specifications to surface graphic adaptation only.
- Flexible Packaging:Multi-layer films and pouches manufactured with 150–300 lpi print resolution for barrier-sensitive applications. Demand concentrates in pharmaceutical blister films and snack pouch formats where oxygen and moisture ingress control drives specification. REACH chemical restrictions accelerate water-based adhesive migration in European supply chains.
- Rigid Packaging:Structural containers with caliper ranges of 0.2–6 mm supporting embossing, weighted closures, and dimensional stability. Cosmetics and premium spirits sectors specify these formats where tactile quality signals brand positioning. Structural embossing talent scarcity in Bavaria and Emilia-Romagna constrains capacity expansion for high-end applications.
- Protective Packaging:Engineered cushioning and void-fill structures for fragile goods distribution. E-commerce fulfillment centers in the United States specify dimensional-optimized formats for automated sortation compatibility.
- Sustainable Packaging:Paper-based and mono-material alternatives displacing multi-layer plastics. Electronics and personal care channels command margin premiums for renewable substrates meeting procurement mandates from multinational headquarters.
Most installed capacity flows through Flexible Packaging. Expansion is steepest in Sustainable Packaging.
Material:
Cost tier alignment determines material selection, with premium specifications tolerating higher substrate expense for performance or aesthetic outcomes.
- Plastic:Dominates flexible formats through coextruded and oriented films with tunable barrier properties. High-barrier pharmaceutical applications resist substitution due to FDA notification timelines extending reformulation cycles.
- Paper:Expanding fastest in corrugated and folding carton applications where China's MEE enforcement drives substitution in coastal export manufacturing clusters. Recycled fiber cost volatility compresses converter margins during OCC demand surges.
- Glass:Retains premium spirits and cosmetics positioning where clarity and heft communicate quality. Weight penalties limit expansion in e-commerce distribution.
- Metal:Concentrated in aerosol and high-barrier food applications. Aluminum specifications face dual carbon goal pressure in Chinese manufacturing provinces.
Volume concentrates in Plastic substrates. Paper is climbing the fastest as brand owners specify renewable alternatives.
End User:
Application requirements dictate specification complexity, with regulated sectors demanding traceable compliance documentation.
- Food & Beverage:Largest demand pool spanning fresh, frozen, and shelf-stable applications. FDA food contact substance notifications govern barrier coatings while EPA hazardous waste rules shape solvent-based ink disposal for domestic converters.
- Pharmaceuticals:Stringent barrier and serialization requirements drive specification depth. Smart packaging convergence with NFC-enabled formats centers on insulin and biologic cold chain verification networks.
- Cosmetics:Premium positioning emphasizes structural differentiation and surface finish quality. EU extended producer responsibility schemes shift German and French procurement toward mono-material constructions.
- Electronics:Protective and anti-static specifications for component and finished goods distribution. India's PLI scheme alignment in Gujarat and Tamil Nadu creates demand from smartphone exporters.
Food & Beverage captures the greatest specification volume. Pharmaceuticals shows the steepest specification complexity escalation.
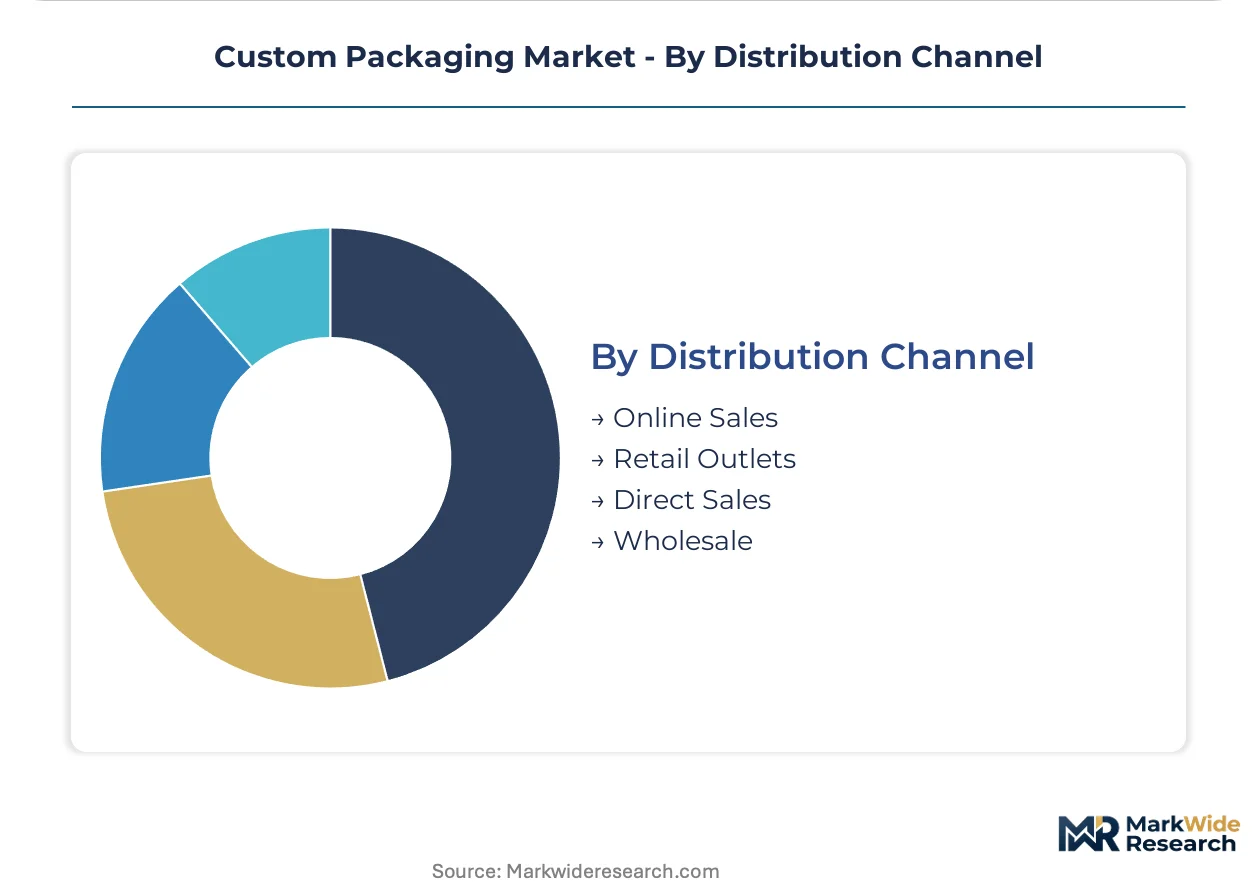
Distribution Channel:
Customer type and order scale determine channel economics, with direct relationships enabling co-development of proprietary formats.
- Direct Sales:Brand owner relationships involving collaborative design and volume commitments. Subscription-based packaging design services are restructuring how converters monetize these relationships beyond unit sales.
- Wholesale:Intermediary-led procurement for mid-market brands with standardized specification needs. California and New York metro corridors concentrate direct-to-consumer startup demand for rapid iteration cycles.
- Online Sales:Digital platforms enabling specification comparison and transactional procurement. Smaller order quantities favor converters with digital print workflow capabilities.
- Retail Outlets:Limited to stock packaging with surface customization only. Channel share contracts as brand owners prioritize bespoke structural development.
Direct Sales channels carry the highest margin profile. Online Sales is gaining share fastest among emerging brand entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates specification volume from e-commerce fulfillment automation, while China drives paper-based substitution through enforcement actions in coastal manufacturing zones.
United States
FDA food contact substance notifications govern barrier coatings in domestic food packaging applications. EPA hazardous waste rules shape solvent-based ink disposal practices for converters operating in Ohio and Wisconsin industrial corridors. California's recycled content mandates propagate through national brand packaging briefs, forcing dual specification tracks across Midwest distribution networks.
China
Dual carbon goals enforced by MEE accelerate paper-based substrate substitution in export-oriented production. GB standards govern packaging material specifications for electronics and personal care channels. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces specify renewable substrates to satisfy procurement mandates from multinational headquarters.
Germany
EU Packaging and Packaging Waste Regulation extended producer responsibility schemes shift recycling cost accountability to brand owners. REACH chemical restrictions limit adhesive chemistries in Bavarian and North Rhine-Westphalian supply chains. Premium cosmetics manufacturers in Hamburg and Berlin metro corridors lead specification changes toward mono-material constructions.
India
PLI scheme alignment for electronics manufacturing generates packaging demand from smartphone exporters in Gujarat and Tamil Nadu. FSSAI regulations govern food contact specifications for domestic and export-oriented production. Component manufacturing clusters in Tamil Nadu's Sriperumbudur and Gujarat's Sanand sub-regions create import substitution opportunities for local converter capacity.
Japan
METI industrial policy supports smart packaging convergence with NFC-enabled formats for pharmaceutical cold chain verification. PMDA serialization requirements drive specification depth in insulin and biologic distribution networks. Kanto region manufacturing density around Tokyo and Yokohama reduces logistics spend for multinational brand operations.
Custom Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated paper networks controlling fiber supply costs while flexible packaging specialists anchor food safety applications. The vendor base organizes around three strategic archetypes: integrated fiber-to-box operators, barrier-focused flexible film converters, and regional manufacturing density players. Consolidation pressure concentrates among corrugated competitors seeking OCC supply security. Technology licensing agreements and capacity expansion in digital print workflows represent the dominant competitive moves reshaping converter monetization models.
Among integrated European operators, Smurfit Kappa Group exemplifies the fiber supply control archetype through its captive recycling network. ProAmpac and Huhtamaki occupy positions within the flexible and food safety specialization tier, with the former representing barrier-focused converters and the latter illustrating regional manufacturing density strategies that reduce logistics spend for multinational brand procurement.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| ProAmpac |
| Huhtamaki |
| DS Smith |
| Amcor plc |
| Westrock Company |
| Sonoco Products Company |
| International Paper |
| Graphic Packaging International |
| Others |
Value Network & Pricing Analysis
OCC price index volatility cascades through corrugated converter networks into three-tier pricing structures across premium, standard, and economy levels, with integrated fiber operators capturing margin insulation unavailable to spot-market-dependent competitors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for paper-based substrates as MEE enforcement accelerates renewable material substitution. Pricing stratifies across premium, standard, and economy tiers driven by customization depth and certification grade, with FDA food contact compliance commanding tier premiums. Cost compression in standard corrugated runs through recycled fiber demand surges from e-commerce fulfillment networks. Mid-market brand owners exhibit highest price sensitivity, while premium cosmetics and pharmaceutical channels tolerate specification premiums for barrier performance.
Supply Chain Analysis
Single-source vulnerability sits with Bavarian and Emilia-Romagna structural embossing tooling suppliers where aging workforce concentrations threaten knowledge transfer. Raw material flows draw from Swedish and Finnish pulp networks, Chinese OCC recovery streams, and German adhesive chemical suppliers. Tariff exposure compounds procurement complexity for North American converters sourcing European specialty substrates. Distribution runs through direct sales relationships with multinational brand procurement teams, supplemented by digital platforms serving emerging direct-to-consumer entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in sustainable substrate substitution where brand procurement mandates validate premium pricing, and in digital print workflow adoption that compresses job changeover costs for shorter-run customization.
For Market Incumbents: Anchor fiber supply security through backward integration into OCC recovery networks or long-term offtake agreements with integrated operators. Smurfit Kappa's captive recycling model demonstrates margin insulation against spot market volatility. Defend position by accelerating water-based ink platform transitions ahead of EPA hazardous waste enforcement escalation. Certification investment in FDA food contact substance notification capabilities locks in pharmaceutical barrier coating relationships resistant to price competition. For New Entrants and Emerging Players: Direct-to-consumer brand partnerships in California and New York metro corridors offer lowest penetration resistance for subscription-based packaging design services. India's PLI scheme alignment in Gujarat and Tamil Nadu electronics clusters presents import substitution white space where local converter capacity lags demand. Target smart packaging convergence applications—NFC-enabled pharmaceutical cold chain verification—where technical differentiation overrides incumbent scale advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with flexible packaging specialists possessing barrier coating formulation libraries and EFSA-compliant adhesive platforms. Five-to-ten year viability favors converters with regional manufacturing density reducing logistics spend for multinational brand procurement. Watch EU member state EPR scheme implementation pace as inflection indicator for design-for-recyclability consulting revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Recovery | Captive fiber supply insulates margin against spot market volatility in corrugated segments. |
| Water-Based Ink Platform Transition | Eliminates EPA hazardous waste disposal liabilities while enabling faster job changeovers. |
| Digital Print Workflow Deployment | Compresses design-to-delivery cycles for direct-to-consumer brand rapid iteration demands. |
| Smart Packaging Capability Buildout | NFC-enabled formats penetrate pharmaceutical cold chain verification networks. |
| Design-for-Recyclability Consulting Launch | EU EPR schemes shift recycling cost accountability to brand owners, creating advisory revenue. |
Research Methodology
Direct dialogue with packaging converters, brand procurement managers, and regulatory compliance officers combined with secondary validation from FDA food contact substance notification databases, EU ECHA REACH restriction updates, and customs trade flow records. Primary fieldwork encompassed corrugated plant managers, flexible film technical directors, and sustainability leads at multinational consumer goods companies. Bottom-up volume estimates triangulated against top-down market sizing from industry association capacity disclosures.
Segment-level outputs across packaging type, material substrate, end-use application, and distribution channel dimensions were generated through the projection horizon. CAGRs derived from regression analysis against e-commerce fulfillment center expansion rates, recycled content mandate propagation timelines, and dual carbon goal enforcement intensity. Industry-specific inputs included pharmaceutical blister film barrier specification trajectories and digital print adoption curves among mid-cap converters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Packaging and Packaging Waste Regulation enforcement variability, OCC price volatility amplitude, and FDA notification timeline extensions. Assumptions reflect current regulatory trajectories and technology adoption patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Transport Packaging Market