
 India Personal Care Packaging Market | 2026-2036
India Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Personal Care Packaging Market Foresight
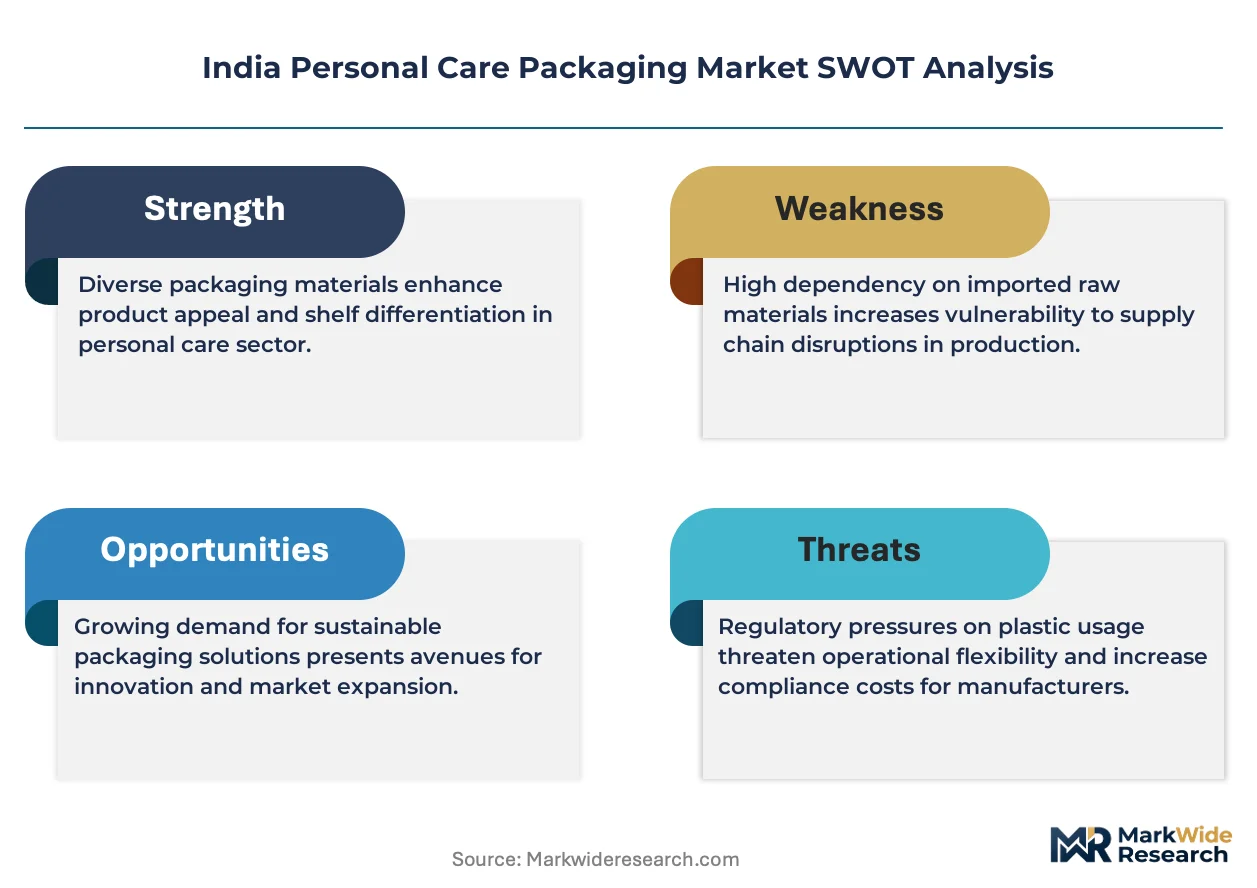
Premium-grade barrier specifications is bifurcating the India personal care packaging landscape into export-compliant and mass-market supply chains. EPL Limited anchors the laminated tube segment through backward integration into polymer compounding. UFlex Limited competes on flexible packaging scale with dedicated lines for sachet-to-pouch conversions. Manjushree Technopack Ltd dominates blow-molded bottle supply to hair care multinationals operating in South India.
India personal care packaging encompasses primary and secondary containment systems engineered from polymers, glass, metal alloys, or fiber substrates to protect cosmetic and hygiene formulations from oxidation, microbial ingress, and mechanical damage during distribution. Multi-layer coextrusion and hot-fill compatibility represent core technical thresholds for tropical climate stability. Tubes and pumps lead value capture due to dosing precision and brand differentiation potential, while pouches represent the fastest-growing format as refill economics reshape consumer purchase patterns. Plastic retains volume dominance though paper-based alternatives are carving share in premium skin care gift sets.
The Bureau of Indian Standards mandates migration testing for food-contact-grade polymers repurposed into cosmetic applications, while the Central Pollution Control Board enforces extended producer responsibility targets that reshape material selection at the design stage. The Plastic Waste Management Rules and forthcoming FSSAI-adjacent cosmetic packaging guidelines are forcing converters to validate recyclability claims through third-party certification. Stakeholders must decide whether to absorb compliance costs through material downgauging or pass them through via premium positioning before regulatory deadlines harden.
Market Dynamics
Refill-format adoption is compressing primary packaging volumes while forcing converters to redesign closure systems for multi-use compatibility across Maharashtra and Gujarat manufacturing clusters.
Growth Catalysts
- PLI scheme incentives:The government's production-linked incentive scheme for specialty chemicals is lowering polymer feedstock costs for domestic tube and bottle manufacturers.
- Airless pump penetration:Premium skin care brands operating in South India are specifying high-barrier pump systems to extend serum shelf life in tropical humidity conditions.
- E-commerce fulfillment requirements:Direct-to-consumer beauty brands demand drop-test-certified secondary packaging, driving corrugated-laminate hybrid investments in tier-two cities.
Market Restraints
- Recycled polymer contamination thresholds:BIS migration testing limits for post-consumer recycled content in cosmetic contact layers cap sustainable material adoption at 30% for most converters.
- Masterbatch supply concentration:Three Gujarat-based compounders control 60% of UV-stabilized additive supply, creating input bottlenecks during monsoon logistics disruptions.
- Glass substitution economics:Premium fragrance brands are reverting to molded glass bottles as PCR-plastic aesthetic limitations persist for luxury positioning.
Strategic Opportunities
- Tamil Nadu and Karnataka underpenetration:Blow-molded bottle capacity serving hair care multinationals remains 40% below Maharashtra levels, creating greenfield expansion potential.
- Extended producer responsibility credits:The Plastic Waste Management Rules' EPR trading mechanism rewards mono-material format adoption with compliance cost offsets.
- Digital printing-flexible pouch convergence:Short-run variable decoration enables regional language customization for sachet-to-pouch upgrades in tier-three urban centers.
Industry Challenges
- Hot-fill validation timelines:BIS certification for tropical-climate stability testing extends new product qualification cycles by 8-12 weeks versus ambient-fill formats.
- Multi-layer delamination detection:Quality control systems for coextruded tube barrier integrity require capital investment beyond mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Personal Care Packaging Market |
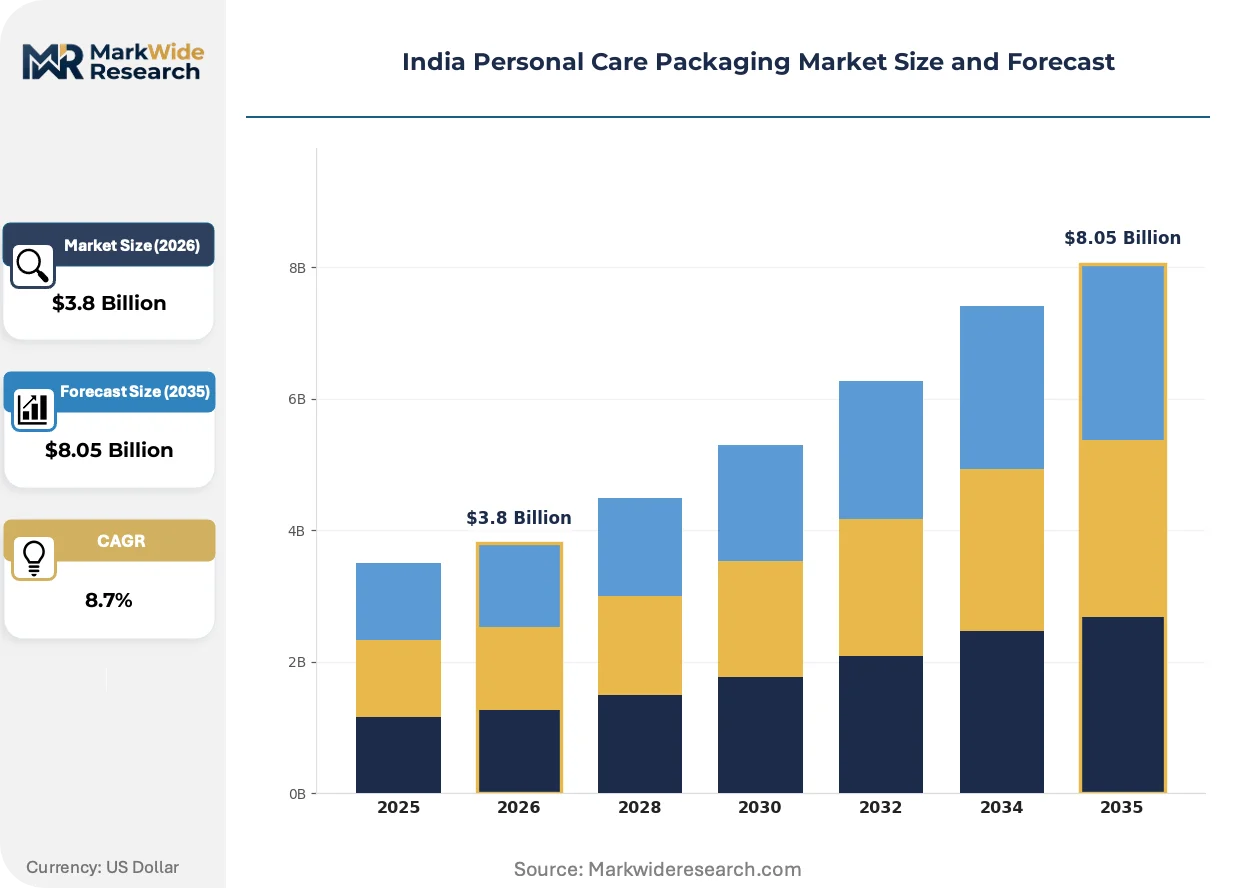
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Jars, Tubes, Pouches Material Type: Plastic, Glass, Metal, Paper End User: Skin Care, Hair Care, Oral Care, Fragrance Closure Type: Screw Caps, Flip Tops, Pumps, Droppers |
| Companies Covered | Huhtamaki PPL, Silgan Holdings Inc., Amcor PLC, EPL Limited, Sonoco Products Company, AptarGroup, Manjushree Technopack Ltd, Essel Propack Limited, UFlex Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Personal Care Packaging Market Shifts & Advancements
Material science advances and regulatory compliance automation are converging to reshape specification workflows between brand owners and packaging converters across Indian personal care supply chains.
Mono-material polyethylene tubes are decomposing the traditional aluminum-barrier laminate standard by simplifying post-consumer sorting streams. Hair care brands in Gujarat are piloting all-PE formats at 15% of new SKU launches. This technology is decomposing established recycling infrastructure requirements, allowing smaller municipalities to process personal care packaging without specialized separation equipment.
The Plastic Waste Management Rules' EPR notification is mandating third-party recyclability validation for all plastic primary packaging above 50ml volume. Converters must now submit test reports to CPCB-authorized agencies before commercial shipment. Premium skin care segments are responding fastest, integrating QR-code traceability systems to document compliance for brand-owned retail channels.
Refill-station retail formats are compressing single-use primary packaging demand in metropolitan beauty retail. Specialty stores in Mumbai and Delhi are replacing stocked inventory with bulk dispensing systems for shampoo and body wash. This pattern is most visible among millennial-targeting indie brands seeking differentiation from multinational shelf-presence strategies.
India Personal Care Packaging Market Segmentation
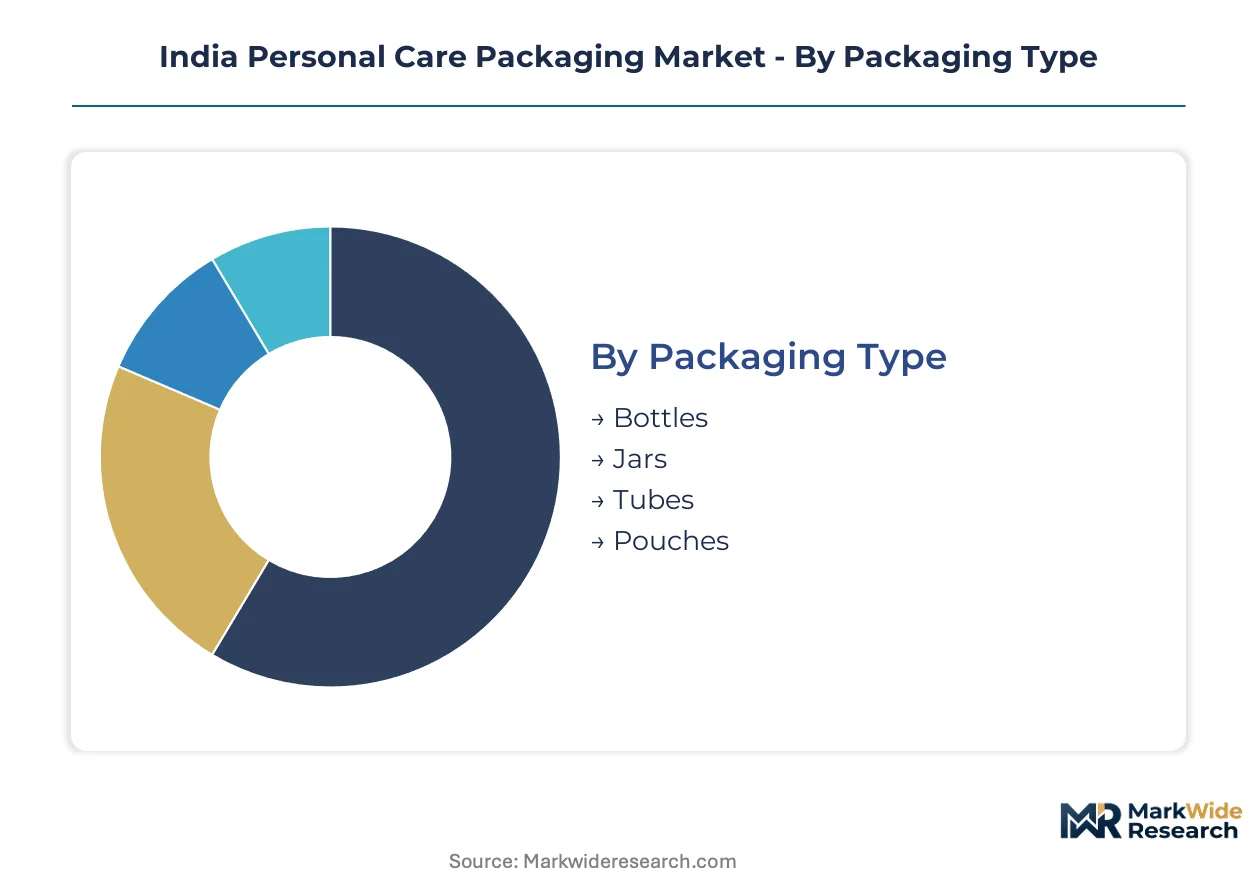
Packaging format selection in India personal care directly shapes unit economics and regulatory compliance paths. Material and closure specifications determine which converters qualify for multinational supply contracts versus domestic brand tiers.
Packaging Type:
Pump bottles and laminated tubes command the widest margin spreads due to precision dosing requirements and barrier complexity.
- Bottles:Blow-molded HDPE and PET formats dominate hair care and body wash volumes. Maharashtra and Gujarat manufacturing clusters serve multinational brand owners with hot-fill-compatible specifications. BIS migration testing for tropical climate stability extends qualification timelines for new bottle designs.
- Tubes:Multi-layer coextruded laminates with aluminum barriers anchor premium skin care dispensing. EPL Limited's backward integration into polymer compounding secures supply security for laminated tube converters serving South India brand headquarters.
- Jars:Wide-mouth PP and glass formats concentrate in premium cream and mask applications. Double-wall construction for thermal insulation adds 20-30% material cost premium over single-wall alternatives.
- Pouches:Flexible stand-up and flat formats are climbing fastest as refill economics reshape Maharashtra and Delhi retail. Mono-material PE constructions simplify CPCB extended producer responsibility compliance.
Bottles hold installed capacity. Pouches are rotating up the share rankings.
Material Type:
Polymer selection determines recyclability certification paths under Plastic Waste Management Rules.
- Plastic:HDPE, PP, and PET retain volume dominance across all format categories. Post-consumer recycled content caps at 30% for cosmetic contact layers per BIS contamination thresholds, constraining sustainability claims.
- Glass:Molded fragrance bottles are resurging as PCR-plastic aesthetic limitations persist for luxury positioning. Gujarat-based glassworks serve premium domestic brands with decorative coating capabilities.
- Metal:Aluminum tubes and aerosol cans concentrate in deodorant and shaving foam applications. Lightweighting drives gauge reduction to 0.35mm wall thickness in standard formats.
- Paper:Fiber-based cartons and rigid boxes carve share in premium skin care gift sets. Lamination requirements for moisture resistance complicate pure paper claims in tropical distribution.
Plastic holds installed capacity. Paper is rotating up the share rankings.
End User:
Skin care and hair care applications absorb the highest packaging specification investments.
- Skin Care:Airless pump systems and high-barrier tubes dominate serum and cream containment. Premium brands operating in South India specify tropical-humidity stability validation for all primary packaging.
- Hair Care:Blow-molded bottles with flip-top closures serve mass-market shampoo and conditioner volumes. Tamil Nadu and Karnataka manufacturing capacity remains 40% below Maharashtra levels.
- Oral Care:Laminated tubes with crimped metal tails anchor toothpaste packaging. Mono-material PE tube pilots are expanding at 15% of new SKU launches in Gujarat.
- Fragrance:Molded glass bottles with pump or cap closures concentrate in premium and luxury tiers. E-commerce fulfillment requirements drive corrugated-laminate hybrid secondary packaging investments.
Skin care holds installed capacity. Oral care is rotating up the share rankings.
Closure Type:
Dosing precision requirements separate premium closure specifications from commodity alternatives.
- Pumps:Airless and standard lotion pumps command premium positioning in skin care and hair care. UV-stabilized masterbatch supply concentration in Gujarat creates input bottlenecks during monsoon logistics disruptions.
- Screw Caps:Standard threaded closures serve mass-market bottles and jars across all end-use categories. Tamper-evident band integration adds minimal cost for regulatory compliance.
- Flip Tops:Hinged PP closures dominate shampoo and body wash bottles for single-hand dispensing. Living hinge fatigue testing extends product qualification cycles.
- Droppers:Glass and plastic pipette systems concentrate in serum and oil applications. Bulb material compatibility with formulation chemistry requires validation per BIS guidelines.
Screw caps hold installed capacity. Droppers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states, with Maharashtra and Gujarat buyers absorbing premium specifications while tier-two city procurement prioritizes unit cost minimization over barrier performance.
Maharashtra
Premium skin care brands headquartered in Mumbai drive specifications for airless pump bottles and high-barrier laminated tubes. The state's Plastic Waste Management Rules enforcement through the Maharashtra Pollution Control Board mandates EPR registration for all primary packaging above 50ml. Manufacturing clusters in Thane and Pune host blow-molded bottle capacity serving hair care multinationals with hot-fill-compatible designs.
Gujarat
Flexible pouch adoption accelerates fastest here as oral care brands pilot mono-material PE tube formats at 15% of new SKU launches. The Bureau of Indian Standards operates its Western Regional Laboratory in Ahmedabad, streamlining migration testing certification for polymer converters. Three Gujarat-based masterbatch compounders control 60% of UV-stabilized additive supply, creating input bottlenecks during monsoon logistics disruptions.
Tamil Nadu
Blow-molded bottle capacity serving hair care multinationals remains 40% below Maharashtra levels, creating greenfield expansion potential. The Tamil Nadu Pollution Control Board enforces Plastic Waste Management Rules with state-specific EPR implementation guidelines. Chennai and Coimbatore industrial corridors attract converters targeting South India brand headquarters with tropical-humidity stability validation capabilities.
Karnataka
Digital printing-flexible pouch convergence enables regional language customization for sachet-to-pouch upgrades in Bangalore and Mysuru retail networks. The Karnataka State Pollution Control Board mandates third-party recyclability validation for plastic packaging under central Plastic Waste Management Rules. Bengaluru's specialty stores are replacing stocked inventory with bulk dispensing refill stations for shampoo and body wash.
Delhi-NCR
E-commerce fulfillment requirements from direct-to-consumer beauty brands concentrate demand for drop-test-certified secondary packaging in corrugated-laminate hybrid formats. The Central Pollution Control Board headquarters enforces national EPR trading mechanisms rewarding mono-material format adoption with compliance cost offsets. Noida and Faridabad manufacturing zones supply tier-three urban centers with short-run variable decoration capabilities.
India Personal Care Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the India personal care packaging landscape. The market structure bifurcates between multinational converters with proprietary barrier technologies and domestic specialists competing on flexible packaging scale. Three strategic archetypes dominate: backward-integrated tube specialists, flexible packaging scale operators, and blow-molded bottle regional champions. Competitive moves concentrate on capacity expansion in underpenetrated southern states and portfolio diversification into mono-material recyclable formats.
Among the named players, EPL Limited and UFlex Limited occupy distinct positions within the converter ecosystem. EPL Limited anchors the laminated tube segment through captive polymer compounding capabilities. UFlex Limited exemplifies the flexible packaging scale archetype with dedicated sachet-to-pouch conversion lines. Manjushree Technopack Ltd represents regional manufacturing concentration serving South India hair care supply chains. These three entities illustrate how geographic specialization and format focus separate premium-tier positioning from mass-market cost competition.
| Leading Market Players |
|---|
| Huhtamaki PPL |
| Silgan Holdings Inc. |
| Amcor PLC |
| EPL Limited |
| Sonoco Products Company |
| AptarGroup |
| Manjushree Technopack Ltd |
| Essel Propack Limited |
| UFlex Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Maharashtra-based blow-molded bottle manufacturers lock in polymer feedstock access and price visibility for hair care multinationals navigating BIS migration testing timelines. These arrangements insulate brand owners from monsoon-season logistics disruptions while compressing margin buffers for mid-tier converters lacking backward integration into compounding.
Pricing Analysis
The Plastic Waste Management Rules dictate the pricing tier structure across the India personal care packaging landscape. Pricing stratifies across premium, standard, and economy tiers based on barrier certification grade and volume commitment scale. Cost compression in mono-material PE formats is intensifying because EPR credit arbitrage rewards recyclability validation investments. Mass-market shampoo brands in Gujarat exhibit highest price sensitivity, while South India skin care headquarters absorb 20-30% premiums for tropical-humidity stability validation.
Supply Chain Analysis
Jamnagar polymer port throughput underwrites raw material security for Gujarat-based masterbatch compounders controlling UV-stabilized additive supply. Manufacturing concentration rests on Maharashtra, Gujarat, and Tamil Nadu, with the latter operating at 40% capacity deficit versus western hubs. HDPE resin, aluminum barrier foil, and UV masterbatch constitute critical input dependencies. Single-source vulnerability concentrates in monsoon-disrupted Gujarat additive supply. Distribution runs through brand-owned regional warehouses serving tier-two and tier-three urban retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refill-system aftermarket services expand faster than primary packaging hardware as Mumbai and Delhi specialty stores replace stocked inventory with bulk dispensing infrastructure. This service-attach dynamic repositions converter economics toward recurring closure and dispenser replacement revenue.
For Market Incumbents: Shield laminated tube margins through captive polymer compounding capabilities that neutralize masterbatch supply bottlenecks. Deepen backward integration into barrier film extrusion to offset emerging all-PE tube substitution threats from Gujarat oral care pilots. Prioritize certification investment for BIS tropical-climate validation to maintain South India brand headquarters relationships. For New Entrants and Emerging Players: BIS fast-track certification for hot-fill-compatible blow-molded bottles opens Tamil Nadu and Karnataka greenfield capacity deployment. Target hair care multinationals underserved by Maharashtra supply concentration. Pursue digital printing-flexible pouch convergence for regional language customization in tier-three urban centers as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated tube specialists with captive compounding and EPR credit generation capabilities. Long-term viability centers on recyclability validation infrastructure ownership rather than commodity format conversion. Monitor mono-material PE tube pilot conversion rates in Gujarat as the inflection signal for laminate displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | EPL Limited's captive supply of barrier resins neutralizes Gujarat masterbatch concentration risk. |
| Mono-Material Format Certification | CPCB-authorized recyclability validation unlocks EPR trading mechanism compliance cost offsets. |
| Digital Printing-Flexible Pouch Convergence | UFlex Limited's short-run capabilities enable regional language customization for tier-three retail. |
| Tropical-Humidity Stability Validation | BIS certification for hot-fill compatibility extends qualification timelines but secures South India brand contracts. |
| Refill Station Infrastructure Partnership | Mumbai and Delhi specialty store bulk dispensing systems compress single-use primary packaging demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging converters, brand procurement managers, and BIS certification officers; and secondary validation through Plastic Waste Management Rules notifications, CPCB EPR registry data, and Maharashtra Pollution Control Board enforcement records. Bottom-up capacity modeling across Maharashtra, Gujarat, and Tamil Nadu manufacturing clusters triangulated against top-down brand owner procurement spend patterns.
Across the analysis window, forecasts incorporate packaging format substitution elasticities, regulatory compliance cost pass-through coefficients, and regional manufacturing capacity utilization differentials. Segmentation dimensions span material type, barrier specification tier, end-use application, and state-level regulatory enforcement intensity. CAGRs derive from polymer feedstock cost trajectory modeling and brand owner SKU launch pipeline analysis.
Underlying assumptions cover stable BIS migration testing protocols and monsoon logistics disruption frequency, with deviation risk concentrated in EPR credit market liquidity and PCR-plastic aesthetic acceptance for premium fragrance positioning. Practitioners should keep alternative scenarios live as Plastic Waste Management Rules enforcement intensity and refill-format retail penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market