
 Service Packaging Market | 2026-2036
Service Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Service Packaging Market Outlook
Modular service bundling is pivoting how buyers procure packaging support, shifting from discrete transactions to integrated logistics-plus-consulting contracts. Sealed Air leverages its equipment-installation network to embed itself inside customer fulfillment lines. Mondi Group anchors its position through captive paper and film supply that sustains cost predictability for long-term service agreements. Smurfit Kappa competes by controlling corrugated container availability across European recycling loops, extending its influence from material supply through final pack-station operation.
Service packaging encompasses the outsourced design, assembly, management, and logistics coordination of protective and presentation materials for finished goods distribution, typically employing corrugated fiberboard, flexible films, foams, and molded pulp selected against transit-stress parameters and shelf-display requirements. Its primary commercial purpose is to transfer inventory damage risk and packaging labor from product manufacturers to specialized third-party operators. The subscription delivery model captures the most durable revenue streams as multi-year retainer contracts lock in volume commitments and reduce customer procurement overhead. On-demand services represent the fastest-expanding segment as e-commerce platforms require surge-capacity access during peak seasons without fixed-cost burden. Project-based engagements retain importance for product launches and geographic expansions where standardized packaging templates do not yet exist.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks shape material selection and recovery obligations for service packaging operators across Europe, while ECHA substance restrictions limit certain adhesive and coating chemistries used in protective formats. FDA food-contact standards govern service packaging deployed for US pharmaceutical and nutritional product distribution, creating dual-jurisdiction compliance complexity for multinational providers. Stakeholders must monitor how extended producer responsibility schemes alter cost allocation between packaging service vendors and their end customers across divergent national implementation timelines.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing service providers to reconfigure collection workflows and material recovery infrastructure, compressing margins while creating compliance-driven consolidation pressure across European operators.
Growth Catalysts
- E-commerce fulfillment surge:Third-party logistics providers in Germany and the Netherlands are embedding packaging stations directly inside customer distribution centers to eliminate handling steps and accelerate last-mile delivery velocity.
- REACH chemical compliance:Restrictions on adhesive and coating chemistries are pushing converters toward water-based barrier systems that service packaging operators can deploy without downstream liability exposure.
- Automotive export clustering:Industrial packaging service hubs around Düsseldorf and Hamburg are capturing volume from battery and component manufacturers requiring specialized on-site protective assembly for cross-border shipment.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container price swings in European spot markets compress service contract margins when long-term agreements lock in fixed unit economics.
- German supplier concentration:Captive paper mill networks controlled by integrated packaging groups limit independent service providers' access to cost-predictable substrate supply.
- Flexible film technical limitations:Current mono-material barrier structures fail to match multi-layer performance for moisture-sensitive pharmaceutical distribution, constraining circular design options.
Strategic Opportunities
- France underpenetration:Industrial packaging service density remains below German levels around Lyon and Toulouse manufacturing corridors, creating whitespace for on-site operations targeting aerospace and specialty chemical exporters.
- EU Green Deal procurement incentives:Public sector tender preferences for verified circular packaging systems are opening institutional revenue streams for operators with certified closed-loop collection infrastructure.
- Digital-print convergence:Integration of inline variable-data printing with automated pack-stations enables batch-size-one customization for direct-to-consumer pharmaceutical and nutritional product fulfillment.
Industry Challenges
- Automation engineering talent scarcity:Pack-station robotics integration and line optimization require mechatronics specialists that European technical institutes are not producing at replacement rates.
- Extended producer responsibility timeline compression:Divergent national implementation schedules for packaging fee structures across EU member states force service providers to maintain parallel accounting systems and compliance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Packaging Market |
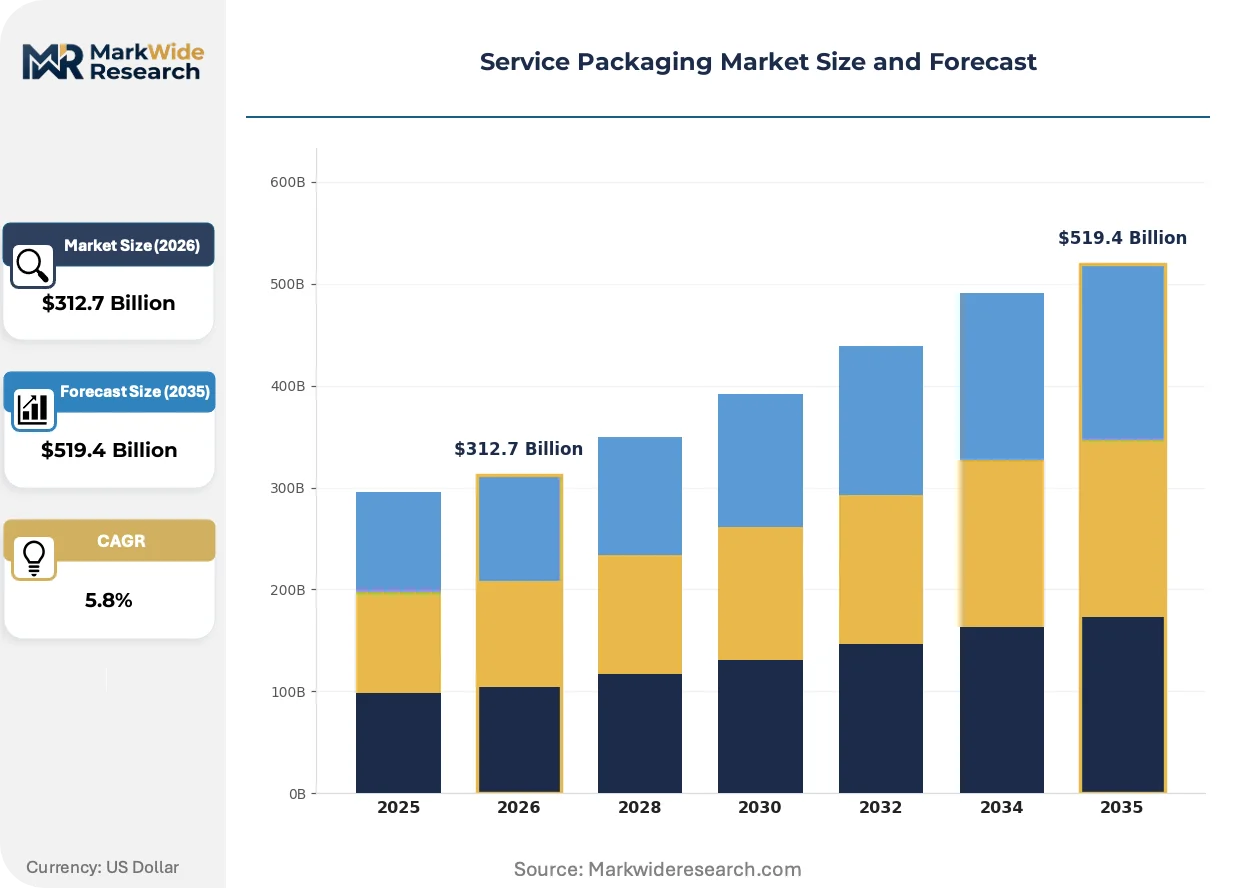
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $519.4 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Logistics, Management, Consulting, Branding Delivery Model: On-Demand, Subscription, Project-Based, Retainer Customer Type: SMEs, Enterprises, Startups, Nonprofits Industry Vertical: Retail, Healthcare, Technology, Education |
| Companies Covered | Sealed Air, Mondi Group, Amcor, Smurfit Kappa, WestRock, DS Smith, International Paper, Sonoco Products, Graphic Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Packaging Market Strategic Shifts
Active transformation in service packaging centers on three vectors: material-system evolution under regulatory pressure, workflow digitization, and procurement-model restructuring that collapses traditional vendor boundaries.
Molded pulp protective formats are expanding into electronics and appliance fulfillment channels as fiber-based alternatives to expanded polystyrene. Consumer durable manufacturers in Italy and Poland are adopting these structures for domestic e-commerce distribution. The technology is expanding into premium unboxing experiences previously dominated by plastic-intensive presentation packaging, compressing the addressable market for conventional foam fabricators.
EU Packaging and Packaging Waste Regulation material recovery targets are mandating redesign of collection and sorting infrastructure across member states. Service providers must now integrate reverse logistics capabilities that were historically outside their operational perimeter. German operators are responding fastest, building dedicated recovery fleets that parallel their forward distribution networks to capture packaging waste at customer dock doors.
Subscription-based service contracts are displacing transactional project engagements among mid-market manufacturers seeking to transfer inventory damage risk and eliminate procurement overhead. Industrial buyers in Belgium and Austria are consolidating vendor relationships around multi-year retainers that bundle design, material supply, and pack-station operation. This concentration is most visible in automotive component supply chains, where tier-one suppliers demand integrated packaging-plus-logistics accountability from single-source partners.
Service Packaging Market Segmentation
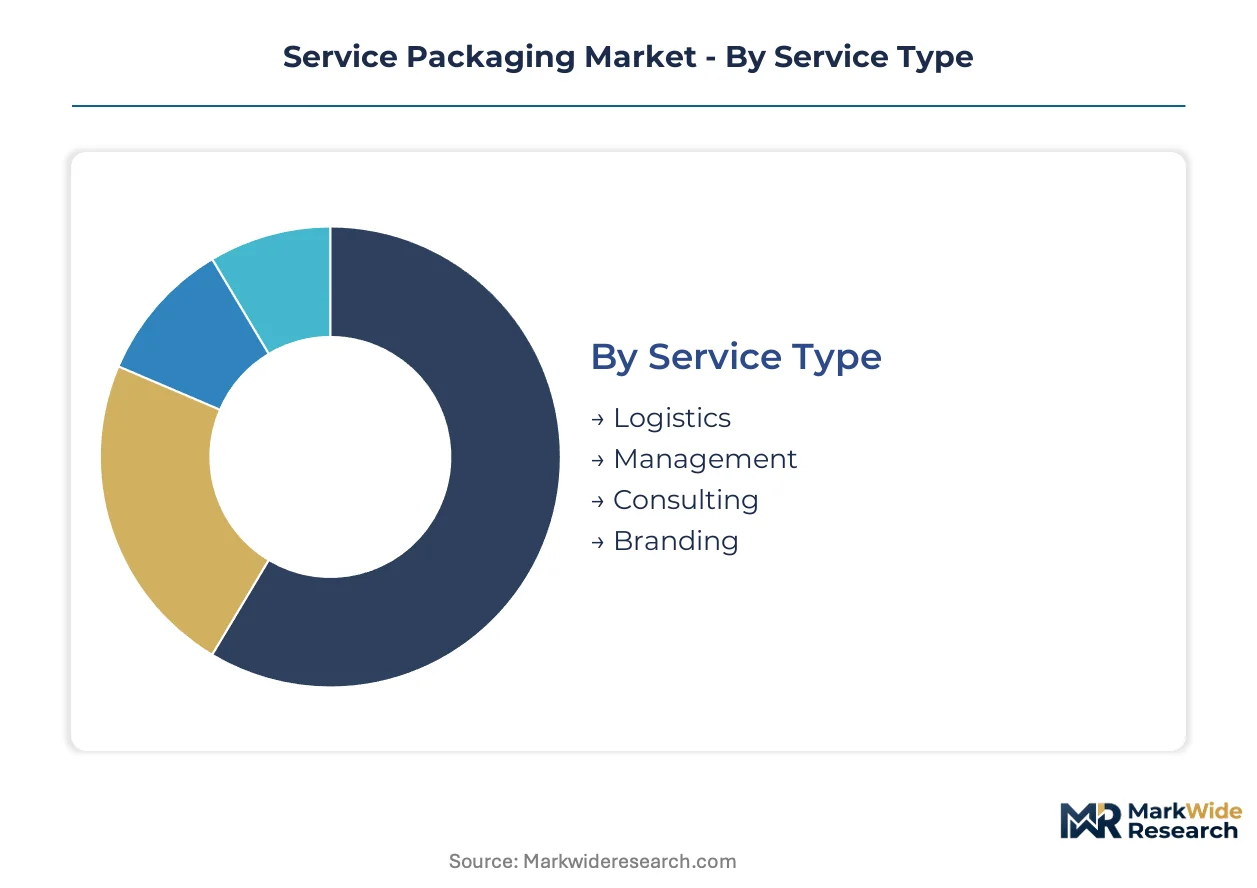
Service packaging procurement patterns diverge sharply across customer scale and engagement structure. Segment-specific capital requirements and contract duration preferences reshape how providers configure their asset bases and talent deployment.
Service Type:
Capital intensity peaks in logistics services requiring fleet and warehouse infrastructure, while consulting demands minimal fixed assets but premium labor costs.
- Logistics:End-to-end coordination of material flow, inventory positioning, and final-mile delivery execution. German automotive exporters around Stuttgart and Wolfsburg concentrate demand here, driven by just-in-sequence assembly line requirements that tolerate zero packaging failure. Most installed capacity flows through Logistics. Expansion is steepest in Consulting.
- Management:Ongoing oversight of packaging operations including supplier coordination, quality auditing, and cost optimization. Healthcare distributors in the Netherlands prioritize this segment to maintain FDA and EMA compliance without building internal expertise.
- Consulting:Advisory engagements on material selection, regulatory pathway navigation, and pack-station design. French aerospace suppliers near Toulouse engage consultants to map REACH-compliant protective formats for export markets.
- Branding:Design and production of presentation-layer packaging that carries marketing messaging. Italian consumer durable manufacturers use these services for premium unboxing experiences in domestic e-commerce channels.
Logistics commands the largest asset footprint. Consulting climbs fastest as regulatory complexity deepens.
Delivery Model:
Contract duration and revenue predictability separate these segments, with subscription models locking in multi-year cash flows against project volatility.
- Subscription:Recurring retainer agreements covering continuous packaging service provision. Belgian automotive tier-one suppliers favor this structure to transfer damage risk and eliminate procurement overhead.
- On-Demand:Surge-capacity access triggered by volume spikes without fixed-cost commitment. E-commerce platforms in Poland deploy this model for peak-season fulfillment scaling.
- Project-Based:Discrete engagements tied to product launches, geographic expansions, or facility buildouts. Austrian specialty chemical exporters use project structures when standardized templates do not yet exist.
- Retainer:Pre-committed capacity blocks with priority access guarantees. German battery manufacturers retain packaging capacity to secure specialized protective assembly for cross-border shipment.
Subscription locks in the most durable revenue streams. On-Demand scales most rapidly with e-commerce seasonality.
Customer Type:
Procurement sophistication and contract scale vary dramatically across organizational maturity, from startup flexibility to enterprise compliance rigor.
- Enterprises:Large manufacturers and distributors with complex multi-site packaging requirements. These buyers consolidate vendor relationships around integrated service bundles in automotive and chemical supply chains.
- SMEs:Mid-market manufacturers seeking to outsource packaging labor without building internal capabilities. Italian appliance producers in this tier adopt molded pulp protective formats for domestic e-commerce distribution.
- Startups:Early-stage companies requiring flexible, low-commitment packaging support. Direct-to-consumer nutritional brands use on-demand services to test market response before scaling operations.
- Nonprofits:Institutional buyers with mission-driven procurement criteria and constrained budgets. EU Green Deal procurement incentives are opening institutional revenue streams for operators with certified closed-loop infrastructure.
Enterprises generate the highest contract values. SMEs represent the largest addressable population.
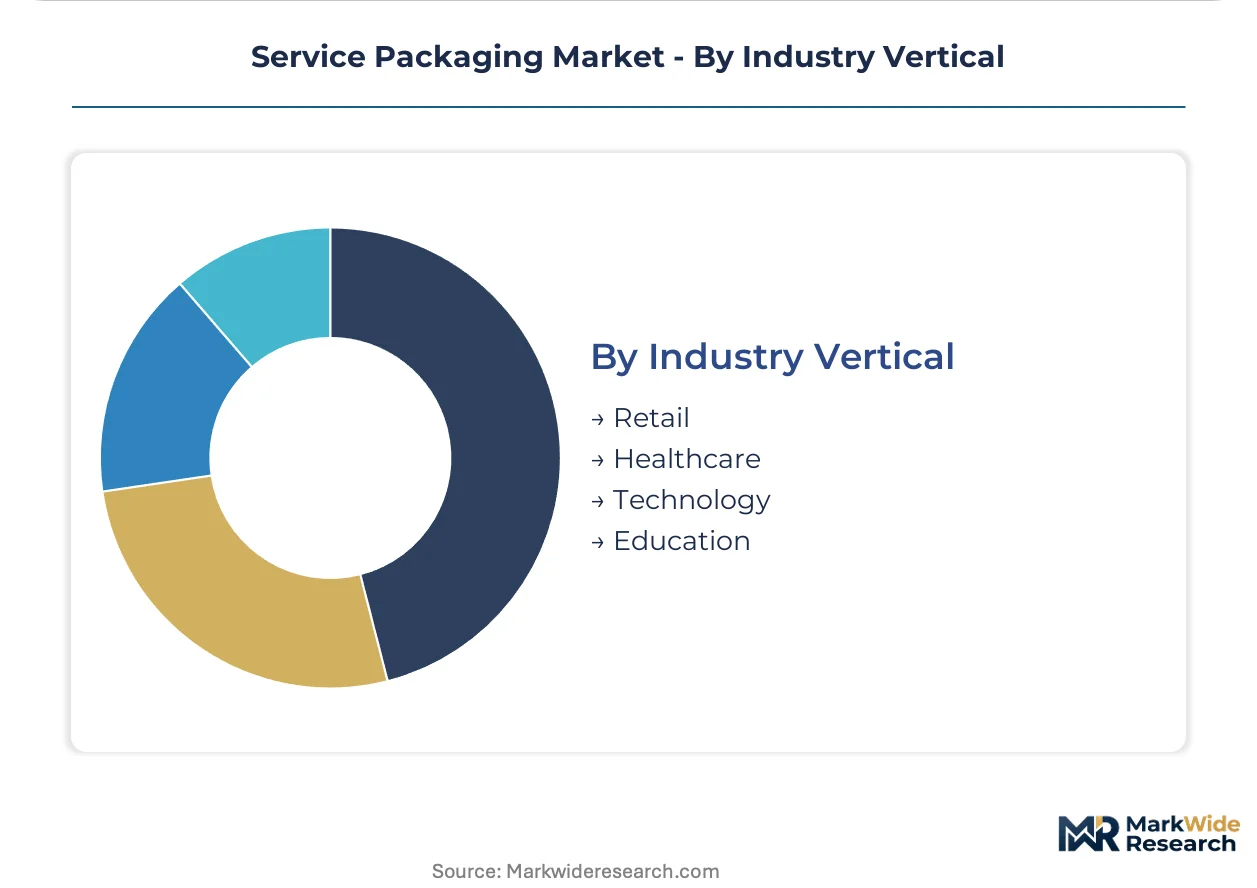
Industry Vertical:
Regulatory exposure and damage-risk tolerance create distinct packaging specifications across end-use sectors.
- Retail:Consumer-facing distribution requiring shelf-display optimization and last-mile durability. E-commerce fulfillment surge drives embedding of packaging stations inside distribution centers.
- Healthcare:Pharmaceutical and medical device distribution governed by FDA food-contact standards and EMA quality protocols. Moisture-sensitive drug distribution constrains circular design options due to flexible film technical limitations.
- Technology:Electronics fulfillment demanding electrostatic discharge protection and precision-fit cushioning. Molded pulp formats are expanding into this channel as fiber-based alternatives to expanded polystyrene.
- Education:Institutional procurement of packaging for equipment, supplies, and research material distribution. Public sector tender preferences for verified circular systems shape supplier selection.
Retail absorbs the highest transaction volume. Healthcare sustains the strictest compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial packaging services first scaled in German manufacturing corridors during the post-war automotive export boom. This foundation established operational templates that now diffuse across European logistics networks. Geographic expansion patterns reflect regulatory alignment and industrial clustering rather than pure market size.
Germany
Automotive battery and component manufacturers around Düsseldorf and Hamburg drive demand for specialized on-site protective assembly. The EU Packaging and Packaging Waste Regulation mandates material recovery targets that German operators meet through dedicated reverse logistics fleets. Stuttgart and Wolfsburg clusters anchor just-in-sequence packaging operations for tier-one automotive suppliers.
France
Aerospace and specialty chemical exporters near Lyon and Toulouse generate underpenetrated demand for industrial packaging services. ANSM pharmaceutical compliance requirements shape protective format selection for drug distribution. The Île-de-France corridor concentrates branding and presentation-layer packaging for luxury consumer goods.
Netherlands
Healthcare distributors prioritize packaging management services to maintain EMA quality protocols without internal expertise buildup. Rotterdam port logistics integrate packaging stations directly into pharmaceutical cold-chain operations. Eindhoven's technology manufacturing base demands electrostatic discharge protection for electronics fulfillment.
Italy
Consumer durable manufacturers adopt molded pulp protective formats for domestic e-commerce distribution channels. Milan and Turin industrial zones sustain premium unboxing experience design for luxury appliance brands. Italian operators face REACH chemical compliance through water-based barrier system conversions.
Belgium
Automotive tier-one suppliers favor subscription-based service contracts to transfer damage risk and eliminate procurement overhead. Brussels-based institutional buyers respond to EU Green Deal procurement incentives for verified circular packaging systems. Antwerp chemical exporters require specialized hazardous material packaging compliance.
Service Packaging Market Competitive Environment
The competitive structure tilts toward integrated material-service bundling rather than pure-play logistics operators. European markets concentrate around paper-based packaging groups with captive fiber supply, while North American players emphasize equipment-embedded service models. Three archetypes dominate: vertically integrated paperboard producers, equipment-leasing service networks, and specialized protective design consultants. Consolidation pressure intensifies as EPR compliance costs favor scale, with M&A activity targeting regional logistics networks and technology licensing partnerships proliferating for automated pack-station integration.
Among integrated paper and film suppliers, Mondi Group and Smurfit Kappa exemplify the captive substrate archetype that sustains cost predictability for long-term agreements. Sealed Air occupies the equipment-embedded service position, leveraging installation networks to integrate directly inside customer fulfillment lines. These three anchors demonstrate how material control, logistics infrastructure, and automation technology constitute distinct competitive vectors that rarely converge in single operators.
| Leading Market Players |
|---|
| Sealed Air |
| Mondi Group |
| Amcor |
| Smurfit Kappa |
| WestRock |
| DS Smith |
| International Paper |
| Sonoco Products |
| Graphic Packaging |
| Others |
Value Chain & Pricing Dynamics
Mechatronics engineering talent scarcity in Stuttgart and Wolfsburg widens labor-cost spreads between premium automated pack-station operators and economy-tier manual assembly providers. REACH compliance investments and recycled fiber price volatility further stratify contract economics across service tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts in the Service Packaging Market. Premium tiers command spreads through ISO-certified circular systems and dedicated on-site engineering teams, while economy tiers compete on per-unit transactional rates for seasonal surge capacity. Cost compression in standard tiers intensifies because German paper mill networks limit independent converters' substrate access. SMEs exhibit highest price sensitivity, whereas automotive tier-one suppliers prioritize damage-risk transfer over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Belgium anchor hub-and-spoke fulfillment patterns for industrial packaging services. Captive paper and film supply from integrated producers feeds corrugated and flexible substrate demand, while specialized molded pulp draws from Italian and Polish fiber processing clusters. Single-source vulnerability concentrates around Düsseldorf-area automotive packaging hubs serving cross-border battery shipments. Distribution runs through forward-reverse logistics fleets that parallel collection and recovery workflows mandated by EU Packaging and Packaging Waste Regulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Service Packaging Market functions as a stable compounder where e-commerce fulfillment infrastructure buildouts generate recurring subscription revenues with low churn. Regulatory compliance burdens create durable moats for operators with certified closed-loop systems.
For Market Incumbents: Extend automation engineering capabilities through acquisition of specialized robotics integrators in Benelux manufacturing corridors. Consolidate regional logistics networks before EPR fee structures compress mid-tier margins, leveraging captive fiber supply to lock in multi-year retainer contracts with automotive exporters. For New Entrants and Emerging Players: The premium-to-economy pricing gap in French aerospace corridors near Toulouse offers white-space entry for REACH-compliant protective design consultants. Target on-demand service models for Polish e-commerce platforms seeking peak-season surge capacity without fixed-cost commitment, positioning around water-based barrier system expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among equipment-leasing service networks lacking captive material supply. Long-term viability hinges on automation technology licensing partnerships and pack-station integration capabilities. Watch for divergent national EPR implementation timelines as the signal indicating consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Supply | Captive OCC sourcing insulates German operators from spot market volatility. |
| Automation Technology Licensing | Pack-station robotics partnerships address mechatronics talent scarcity in Stuttgart clusters. |
| Reverse Logistics Fleet Buildout | Dedicated recovery networks satisfy EU Packaging and Packaging Waste Regulation mandates. |
| Multi-Year Retainer Contract Expansion | Subscription models transfer damage risk from Belgian automotive tier-one suppliers. |
| REACH-Compliant Barrier System Conversion | Water-based coatings eliminate downstream liability exposure for pharmaceutical distribution. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged packaging operations directors at automotive OEMs, procurement leads at chemical exporters, logistics managers at third-party fulfillment providers, and regulatory compliance officers at healthcare distributors. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA substance restriction updates, SEC disclosures by integrated paperboard groups, and customs data on corrugated container trade flows. Bottom-up service contract analysis and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across subscription, on-demand, and project-based delivery models, with further stratification by logistics, management, consulting, and branding service types. Modeled dimensions included customer scale tier, industry vertical exposure, and geographic regulatory cluster. CAGRs derived from trend extrapolation of e-commerce fulfillment penetration and EPR compliance cost trajectories. Forecast inputs incorporated automotive export volume projections and molded pulp technology adoption curves.
Caveats apply where recycled fiber price spikes or accelerated EPR timeline compression could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation consistency and automation engineering labor availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Recycled Materials Packaging Solutions Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
CBD Product Packaging Market