
 Australia Contract Packaging Market | 2026-2036
Australia Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Contract Packaging Market Insights
New South Wales is reshaping competitive dynamics through expanded pharmaceutical and food-grade packaging corridors near Sydney. Carewell Group leverages integrated labeling and secondary packaging capabilities to anchor its position in healthcare logistics. Probiotec Limited differentiates through specialized blister packaging and bottling services for pharmaceutical clients. Ultra Pak (Australia) Pty Ltd dominates shrink wrapping and flow-wrapping segments for fast-moving consumer goods.
Contract packaging encompasses outsourced primary, secondary, and tertiary packaging execution performed by third-party specialists on behalf of product owners, typically involving automated filling, sealing, labeling, and cartoning processes under client specifications. Blister packaging and carton packaging command structural priority due to pharmaceutical serialization mandates and food safety traceability requirements. Plastic and paper materials lead volume throughput, though metal packaging sustains premium positioning in cosmetics and specialty food segments where barrier integrity determines shelf-life performance.
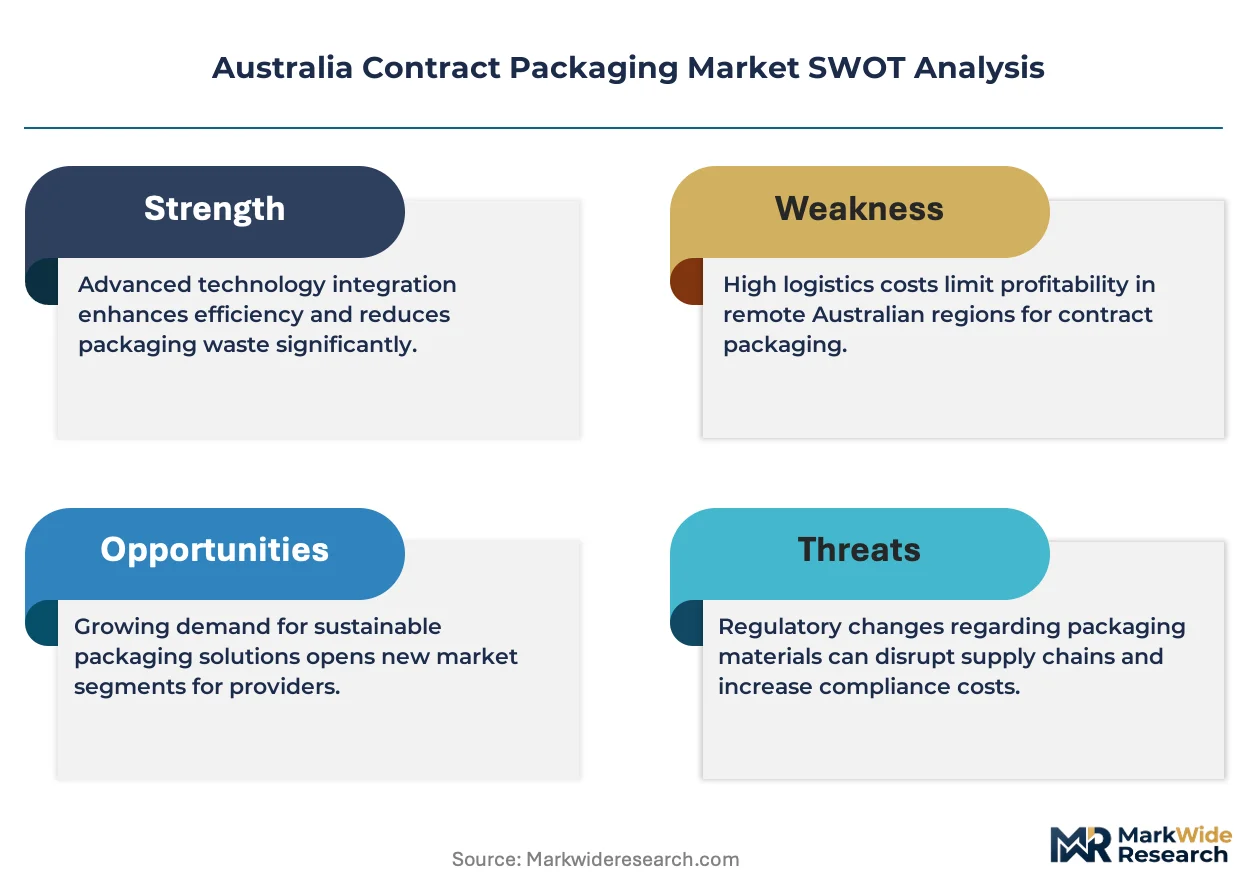
TGA standards, the Australian Packaging Covenant Organisation sustainability framework, and Food Standards Australia New Zealand labeling regulations collectively dictate material compliance, waste reduction targets, and nutritional disclosure formats across the sector. These requirements elevate capital thresholds for new entrants while creating recurring revenue streams for established operators with validated quality systems. Stakeholders must monitor evolving extended producer responsibility obligations and bioplastics certification pathways to anticipate procurement specification shifts.
Market Dynamics
Pharmaceutical serialization mandates under TGA standards are compressing packaging timelines and forcing contract manufacturers to integrate track-and-trace infrastructure ahead of enforcement deadlines.
Growth Catalysts
- TGA serialization requirements:Regulatory deadlines for unit-level traceability are compelling pharmaceutical sponsors to outsource packaging execution to validated third-party operators with established verification systems.
- Bioplastics certification pathways:The Australian Packaging Covenant Organisation's 2025 recycled content targets are redirecting procurement specifications toward certified compostable films and fiber-based alternatives.
- Victoria manufacturing corridor:Concentrated pharmaceutical and food processing clusters near Melbourne are generating sustained demand for integrated secondary and tertiary packaging services.
Market Restraints
- Capital intensity of serialization infrastructure:Line-level aggregation and verification equipment requires substantial upfront investment, elevating break-even thresholds for mid-scale operators.
- Resin price volatility:Polypropylene and polyethylene input costs fluctuate with global petrochemical feedstock markets, compressing margin predictability for plastic-dominant packaging formats.
- Specialized talent scarcity:Qualified technicians for automated cartoning and blister sealing systems remain concentrated among established Melbourne and Sydney operators.
Strategic Opportunities
- Queensland underpenetration:Brisbane-Gold Coast pharmaceutical manufacturing growth outpaces local contract packaging capacity, creating whitespace for regional facility investment.
- Extended producer responsibility frameworks:Pending federal packaging stewardship legislation will mandate producer-funded collection and recycling, advantaging operators with pre-established reverse logistics partnerships.
- Cold-chain biologics packaging:Temperature-sensitive cell and gene therapy products require validated thermal packaging solutions that few Australian contract packers currently offer.
Industry Challenges
- Validation timeline compression:TGA's abbreviated approval pathways for critical medicines shorten packaging process qualification windows, straining quality documentation capacity.
- Legacy equipment retrofit costs:Existing cartoners and labelers require hardware and software upgrades to achieve aggregation compliance, diverting capital from capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Contract Packaging Market |
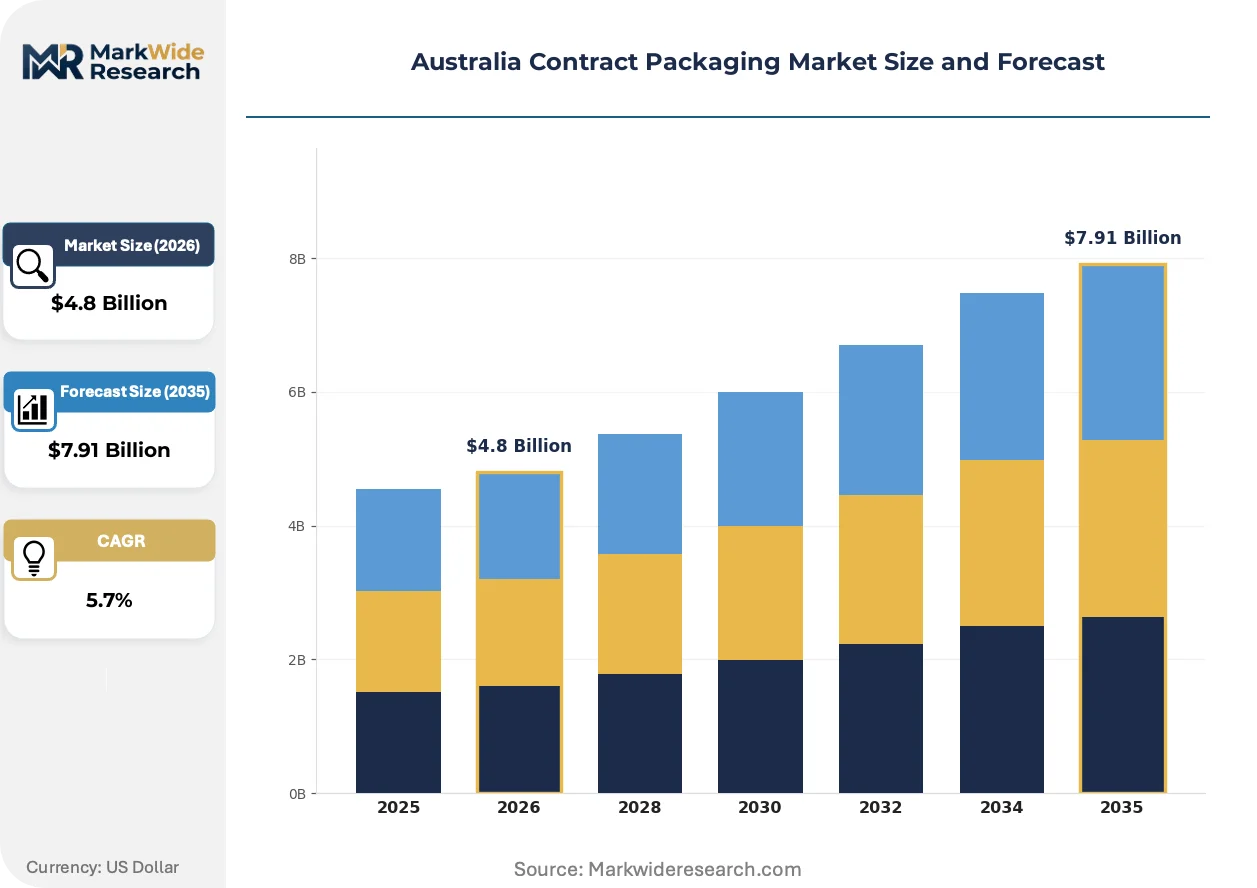
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Labeling, Blister Packaging, Shrink Wrapping, Carton Packaging Product Type: Food, Pharmaceuticals, Cosmetics, Electronics End User: Retailers, Manufacturers, Distributors, E-commerce Packaging Material: Plastic, Glass, Metal, Paper |
| Companies Covered | Carewell Group, Assemco Outsourcing Melbourne Australia, Ultra Pak (Australia) Pty Ltd, Probiotec Limited, Rapid Pak, Finishing Services, Packcentre Marketing Services Pty Ltd, CMTP, Outsource Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Contract Packaging Market Trends and Innovations
Digital integration across packaging execution is collapsing traditional boundaries between production, quality assurance, and supply chain visibility. Three developments are restructuring competitive requirements.
Serialization software platforms are virtualizing quality documentation workflows by embedding electronic batch records directly into line control systems. Pharmaceutical sponsors adopting these integrated stacks compress release timelines from days to hours. The technology is virtualizing the role of standalone quality management systems in mid-tier contract packaging operations.
TGA's pending adoption of EU-aligned Unique Device Identification standards for therapeutic goods will extend serialization requirements beyond pharmaceuticals into medical devices and combination products. This regulatory expansion forces contract packers to validate additional label formats and data matrix configurations. Device manufacturers in New South Wales are pre-qualifying packaging partners with demonstrated UDI implementation experience.
Direct sourcing from contract packers is displacing traditional distributor-mediated procurement in mid-sized pharmaceutical companies. Sponsors now negotiate master service agreements spanning primary through tertiary packaging, consolidating vendor relationships. This pattern concentrates most visibly among generic medicine marketers seeking cost transparency across their Melbourne and Sydney supply bases.
Australia Contract Packaging Market Segmentation
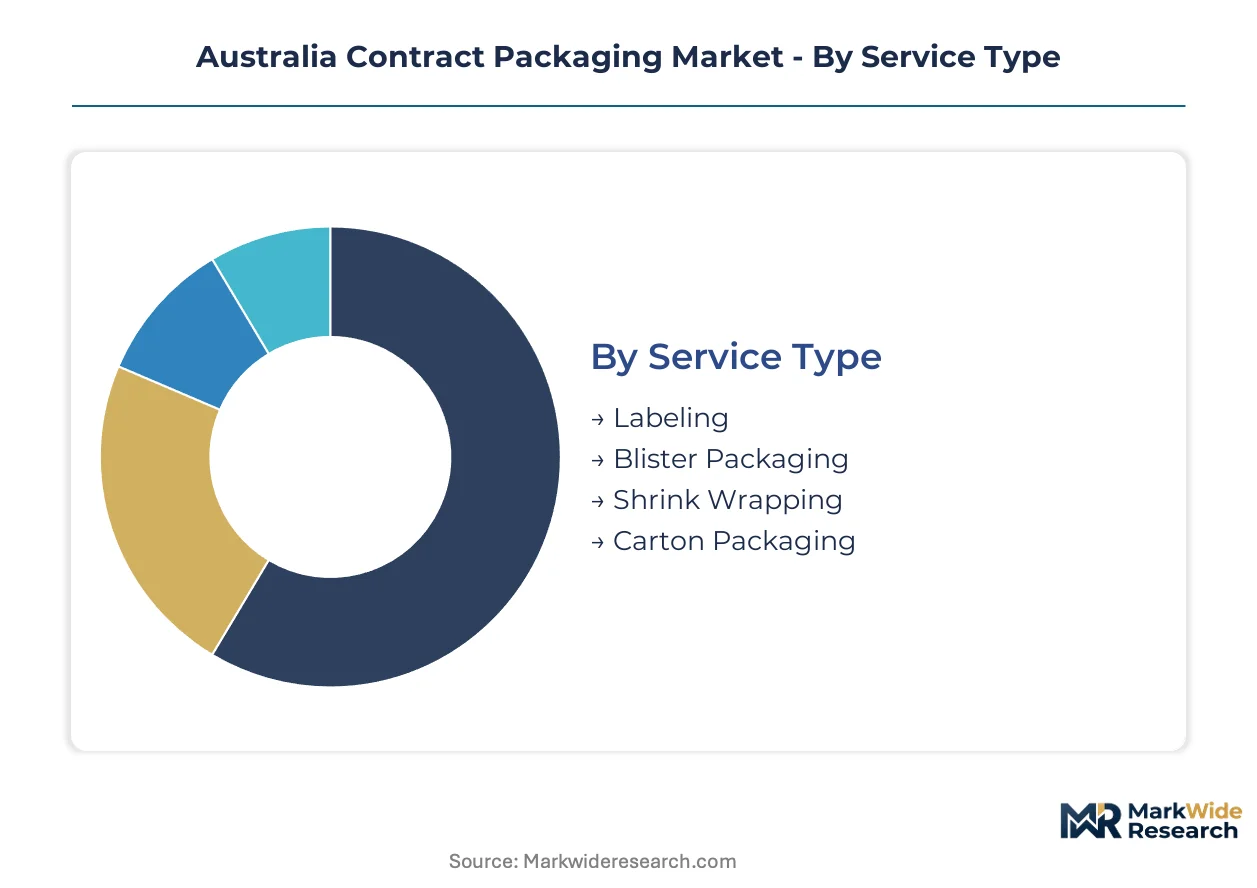
Service specialization determines supplier selection criteria across Australia's contract packaging sector. Pharmaceutical serialization mandates and food safety traceability requirements are compressing vendor qualification timelines. Material compliance with TGA standards and Australian Packaging Covenant Organisation frameworks now precedes commercial negotiations.
Service Type:
Technical complexity and regulatory validation requirements separate premium service tiers from commodity execution.
- Labeling:Integrated primary and secondary labeling systems incorporate TGA-mandated serialization codes and variable data printing. Melbourne pharmaceutical clusters are driving demand for validated label application with electronic batch record integration.
- Blister Packaging:Thermoformed cavity sealing with aluminum lidding provides tamper-evident unit-dose protection for solid oral dosages. Sydney pharmaceutical corridors require cold-form aluminum and PVC/PVDC configurations to meet stability protocols for moisture-sensitive actives.
- Shrink Wrapping:Heat-activated polymer film consolidation for multi-unit retail bundling serves fast-moving consumer goods distribution.
- Carton Packaging:Automated erecting, filling, and sealing of paperboard containers supports secondary packaging workflows across food and cosmetics segments.
Blister packaging commands the established base. The steepest expansion runs through labeling services driven by serialization mandates.
Product Type:
End-use regulatory intensity shapes capital deployment patterns and margin structures across service providers.
- Pharmaceuticals:TGA serialization requirements mandate unit-level traceability with aggregation hierarchy through tertiary packaging. Victoria's manufacturing corridor concentrates validated capacity for prescription medicines and over-the-counter products.
- Food:Modified atmosphere packaging and allergen segregation protocols dominate fresh and processed food segments. New South Wales processors near Sydney are specifying compostable film alternatives under Australian Packaging Covenant Organisation targets.
- Cosmetics:Premium barrier packaging for skincare and fragrance products utilizes glass and metal substrates with decorative finishing requirements.
- Electronics:Anti-static and moisture barrier bags protect sensitive components through distribution channels with ESD compliance specifications.
Food applications anchor volume throughput. Pharmaceuticals are climbing the fastest on regulatory-driven outsourcing.
End User:
Procurement scale and technical specification authority differentiate customer segments for contract packer targeting.
- Manufacturers:Brand owners outsourcing primary through tertiary packaging execution to reduce capital intensity and accelerate time-to-market for new product launches.
- Retailers:Private label programs requiring compliant packaging for house-brand pharmaceuticals, food, and cosmetics with standardized quality systems.
- Distributors:Repackaging and relabeling services for import compliance and local market adaptation with TGA registration requirements.
- E-commerce:Ship-ready tertiary packaging with dimensional optimization for parcel freight efficiency and damage reduction.
Manufacturers represent the core revenue base. E-commerce is gaining share fastest on direct-to-consumer fulfillment demands.
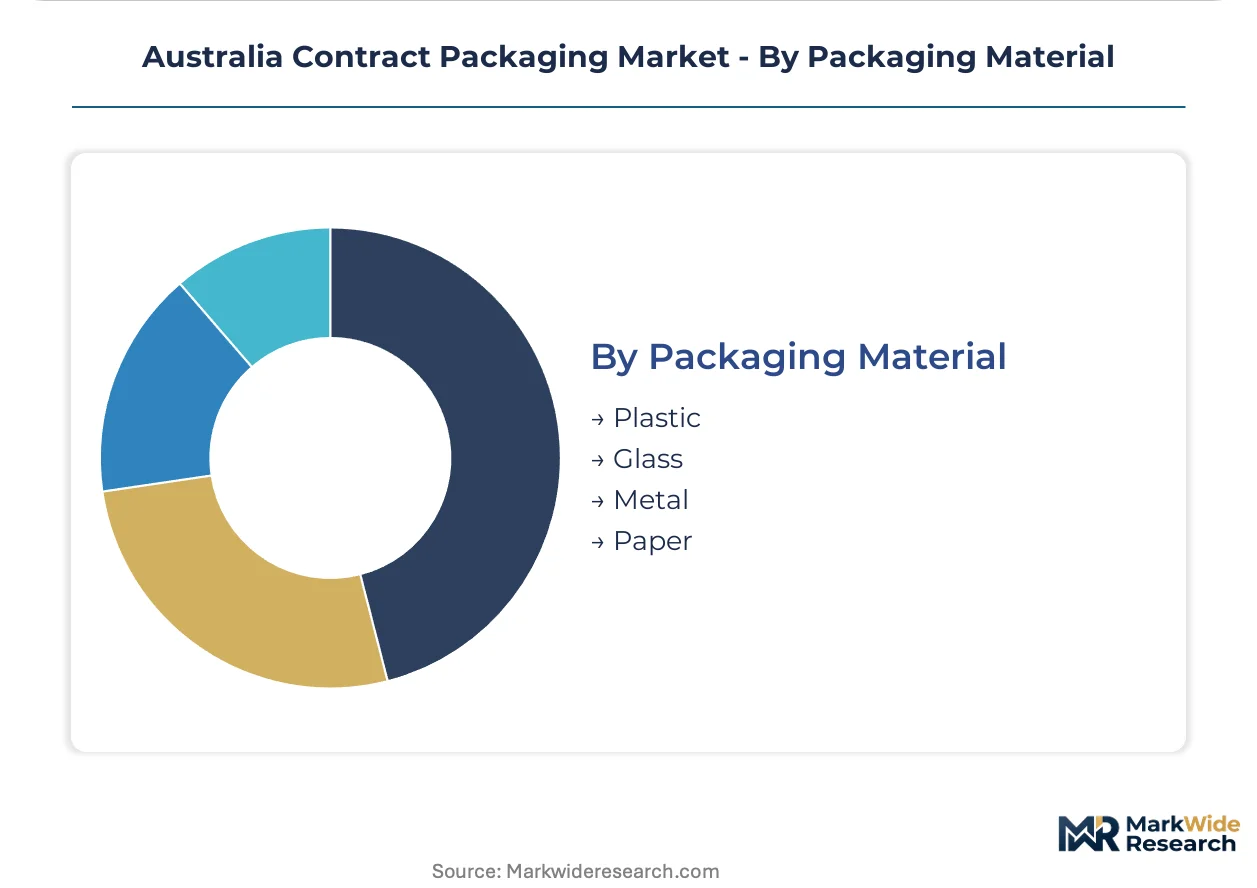
Packaging Material:
Material selection determines barrier performance, sustainability credentials, and compliance pathway complexity.
- Plastic:Polypropylene and polyethylene films dominate flexible packaging with thermoforming and flow-wrapping applications. Resin price volatility linked to global petrochemical feedstock markets compresses margin predictability for converters.
- Paper:Fiber-based cartons and corrugated cases serve secondary and tertiary packaging with recyclability advantages under extended producer responsibility frameworks.
- Glass:Premium barrier integrity for cosmetics and specialty food segments where inert contact surface and shelf-life extension justify higher unit costs.
- Metal:Aluminum blister lidding and aerosol containers provide absolute moisture and oxygen barrier for pharmaceutical and personal care applications.
Plastic maintains volume leadership. Paper is expanding most quickly on sustainability specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract packaging capacity clusters along Australia's southeastern manufacturing belt, with Victoria and New South Wales hosting the majority of validated pharmaceutical and food-grade facilities. Queensland and Western Australia present expansion corridors where local demand outpaces established service infrastructure.
New South Wales
Pharmaceutical serialization mandates and food safety traceability requirements are compressing vendor qualification timelines in Sydney's manufacturing corridor. TGA standards and Australian Packaging Covenant Organisation frameworks dictate material compliance and waste reduction targets. The Parramatta-Western Sydney industrial zone concentrates secondary packaging capacity for generic medicine distributors.
Victoria
Cold-form aluminum blister packaging and automated cartoning services dominate demand from Melbourne's pharmaceutical clusters. The state's manufacturing precincts near Dandenong and Laverton host integrated primary-through-tertiary packaging operations. Bioplastics certification pathways are redirecting procurement specifications toward compostable films among food processors.
Queensland
Brisbane-Gold Coast pharmaceutical manufacturing growth is outpacing local contract packaging capacity, creating whitespace for regional facility investment. Extended producer responsibility frameworks pending at federal level will mandate producer-funded collection and recycling. The Port of Brisbane logistics corridor is attracting tertiary packaging specialists serving e-commerce fulfillment.
Western Australia
Mining equipment and specialty chemical packaging requirements sustain niche contract packaging demand in Perth's industrial suburbs. The state's distance from eastern manufacturing centers elevates freight costs for time-sensitive pharmaceutical serialization. Local operators are retrofitting legacy cartoners with aggregation compliance hardware to capture medical device packaging work.
South Australia
Wine and premium food packaging segments leverage Adelaide's proximity to Barossa Valley and McLaren Vale production zones. Modified atmosphere packaging and allergen segregation protocols dominate processor specifications. The Tonsley Innovation District is incubating sustainable packaging material startups targeting Australian Packaging Covenant Organisation targets.
Australia Contract Packaging Market Competitive Landscape
Integrated healthcare logistics specialists and FMCG-focused wrapping operators split the market between regulated pharmaceutical execution and high-volume commodity throughput. The vendor base concentrates among Melbourne and Sydney operators with validated quality systems, while mid-scale regional players struggle to fund serialization infrastructure. Two strategic archetypes dominate: TGA-validated pharmaceutical packagers with electronic batch record integration, and flow-wrapping specialists serving retail bundling. Competitive moves center on M&A to acquire serialization capabilities and strategic partnerships with bioplastics suppliers to preempt procurement specification shifts.
Among healthcare-focused operators, Carewell Group and Probiotec Limited exemplify the validated pharmaceutical archetype, anchoring positions through specialized blister packaging and bottling services. Ultra Pak (Australia) Pty Ltd occupies the FMCG wrapping tier with shrink and flow-wrapping dominance for retail distribution. These three entities represent the structural split between regulated pharmaceutical execution and high-throughput consumer goods packaging across Australia's contract packaging sector.
| Leading Market Players |
|---|
| Carewell Group |
| Assemco Outsourcing Melbourne Australia |
| Ultra Pak (Australia) Pty Ltd |
| Probiotec Limited |
| Rapid Pak |
| Finishing Services |
| Packcentre Marketing Services Pty Ltd |
| CMTP |
| Outsource Packaging |
| Others |
Pricing and Supply Chain Analysis
The Port of Melbourne logistics corridor anchors national distribution cost dynamics, concentrating supply-side leverage among validated pharmaceutical packers while forcing price differentiation between TGA-certified operators and commodity wrapping services.
Pricing Analysis
TGA serialization requirements dictate the pricing tier structure across Australia's contract packaging sector. Three-tier pricing separates validated pharmaceutical execution with electronic batch record integration from standard food-grade services and economy FMCG bundling. Certification level and volume scale drive price differentiation, with mid-scale generic medicine sponsors exhibiting highest price sensitivity. Cost compression in plastic-dominant formats is intensifying because resin price volatility linked to global petrochemical feedstocks compresses margin predictability.
Supply Chain Analysis
Extended payment terms from pharmaceutical sponsors are restructuring supplier-financing requirements across the sector. Raw material supply draws from China for polypropylene and polyethylene films, India for aluminum blister lidding, and domestic sources for fiber-based cartons. Single-source vulnerability concentrates in imported resin supply, with distribution running through Melbourne and Sydney manufacturing corridors to national retail and hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Contract Packaging Market functions as a regulatory-moat industry where TGA validation entrenchment creates switching costs that protect incumbent revenue streams from price-based competition.
For Market Incumbents: Entrench serialization capabilities through hardware upgrades to aggregation-compliant cartoners and labelers, defending against emerging regional entrants in Queensland. Prioritize certification investment in bioplastics handling to preempt Australian Packaging Covenant Organisation procurement shifts. For New Entrants and Emerging Players: Establish a beachhead in Brisbane-Gold Coast pharmaceutical manufacturing growth zones where local contract packaging capacity lags demand expansion. Target cold-chain biologics packaging as the most penetrable segment, leveraging partnerships with temperature-controlled logistics providers as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming packaging divisions lacking TGA validation infrastructure. Long-term viability centers on regulatory entrenchment durability across a decade horizon. Watch for federal extended producer responsibility legislation passage as the inflection signal mandating producer-funded collection and recycling systems.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Investment | TGA compliance deadlines force line-level aggregation hardware deployment ahead of enforcement. |
| Bioplastics Certification Pathway | Australian Packaging Covenant Organisation targets redirect procurement toward compostable films. |
| Queensland Facility Expansion | Brisbane-Gold Coast pharmaceutical growth outpaces local validated packaging capacity. |
| Cold-Chain Biologics Capability | Temperature-sensitive cell and gene therapy products require validated thermal packaging solutions. |
| Reverse Logistics Partnership | Pending federal stewardship legislation mandates producer-funded collection and recycling infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical manufacturing executives, contract packaging operations managers, TGA regulatory affairs specialists, and bioplastics procurement leads, and refined through secondary validation against TGA guidance documents, Australian Packaging Covenant Organisation reporting frameworks, Food Standards Australia New Zealand labeling regulations, and customs trade flow data. Bottom-up facility capacity assessments and top-down market sizing were triangulated to establish volume and value estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across service type, product category, end-user archetype, and packaging material composition. CAGRs were derived from trend extrapolation of validated capacity expansion, regulatory-driven outsourcing intensity, and sustainability specification shifts. Industry-specific inputs included pharmaceutical serialization mandate timelines and bioplastics certification adoption curves.
Stress conditions across resin price volatility, TGA enforcement acceleration, and Queensland manufacturing corridor expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and sustainability target adherence. Macroeconomic contraction, regulatory delay, or technological disruption in serialization platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Strawless Lids Market