
 North America Child Resistant Packaging Market | 2026-2036
North America Child Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Child Resistant Packaging Market Analytics
The capital-intensity divergence between integrated film producers and specialized closure molders is unwinding competitive stability in child-resistant packaging. Berry Global Inc. leverages vertical integration across resin conversion and thermoforming to control input costs for pharmaceutical bottles. Amcor plc anchors its position through R&D intensity in sustainable barrier films that meet both child-resistant and senior-friendly standards. WestRock Company differentiates via paper-based structural packaging that navigates growing regulatory pressure against single-use plastics.
Child-resistant packaging comprises engineered containers and closures requiring deliberate physical manipulation to access contents, typically incorporating dual-action mechanisms such as push-and-turn or squeeze-and-slide designs with torque thresholds measured in inch-pounds. These systems serve the primary commercial purpose of preventing accidental ingestion by children under five years while preserving adult accessibility. Plastic bottles dominate volume demand within the product type dimension, though child-resistant blister packs capture disproportionate margin pools due to pharmaceutical serialization requirements. Push-and-turn closures remain the mature design standard, while dual-lock mechanisms represent the fastest-growing segment as cannabis and nicotine pouch regulations proliferate across US states.
The US Consumer Product Safety Commission enforces the Poison Prevention Packaging Act, which mandates child-resistant closures for hazardous household substances and shapes baseline demand across pharmaceuticals and chemicals. Health Canada maintains parallel requirements through its national pharmaceutical regulator, creating cross-border compliance complexity for manufacturers serving both markets. State-level cannabis packaging boards in California, Colorado, and Illinois impose supplemental testing protocols that exceed federal minimums. Stakeholders must monitor the divergence between state cannabis rules and any future federal harmonization efforts that would reshape certification requirements and testing burdens.
Market Dynamics
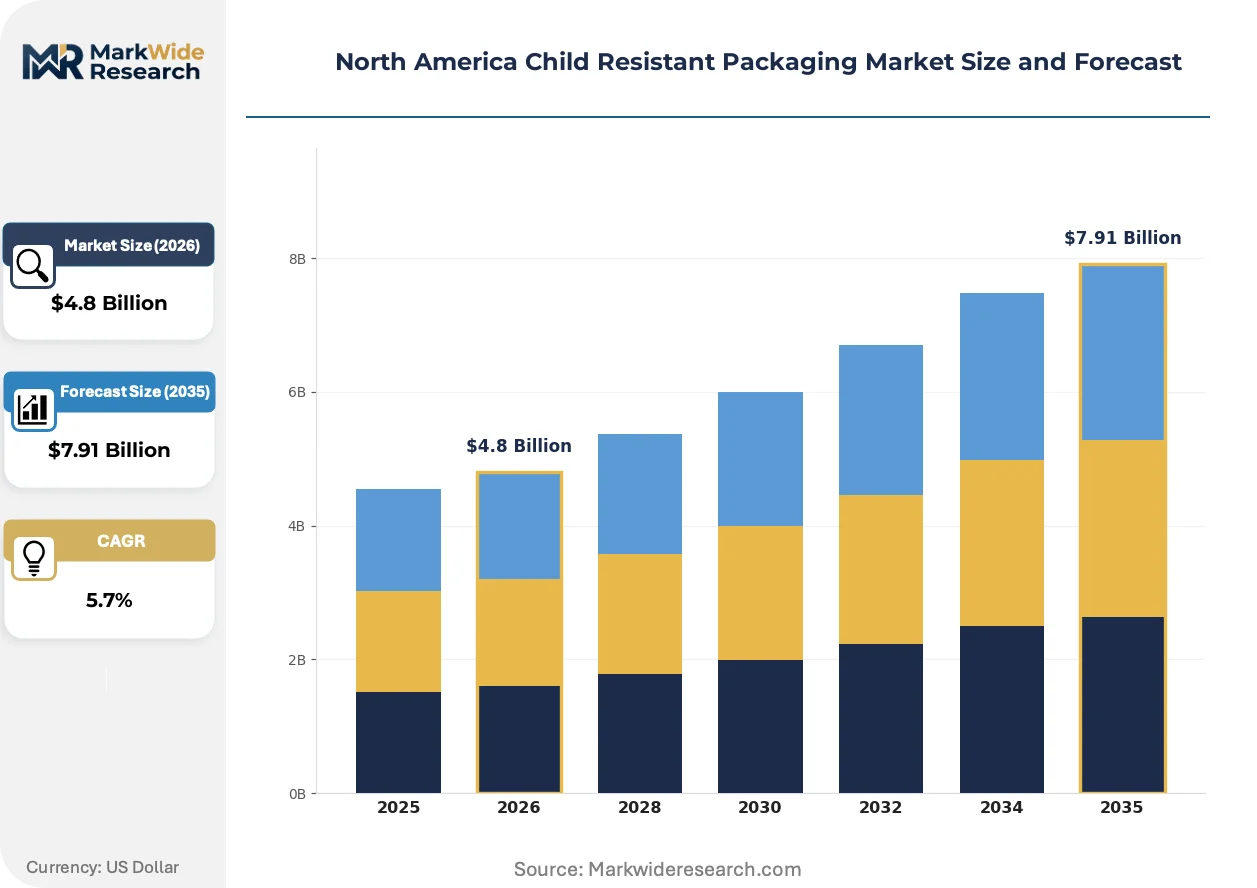
Regulatory layering across federal and state jurisdictions is fragmenting certification requirements and forcing manufacturers to maintain parallel testing protocols for the same product categories.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:The US Consumer Product Safety Commission maintains strict compliance thresholds for household chemicals and pharmaceuticals, sustaining baseline demand for certified closures across OTC medications and cleaning products.
- State cannabis packaging mandates:California, Colorado, and Illinois impose supplemental child-resistant testing protocols that exceed federal minimums, creating dedicated product lines for dispensary-grade containers and exit bags.
- Blister pack serialization:Pharmaceutical track-and-trace requirements are elevating child-resistant blister formats over bottles for unit-dose compliance in chronic disease medications.
Market Restraints
- Resin cost volatility:Polypropylene and polyethylene input prices fluctuate with petrochemical feedstock markets, compressing margins for injection-molded closure specialists without backward integration into resin production.
- Testing laboratory concentration:Third-party certification capacity clusters in California and Ontario, creating bottlenecks for manufacturers seeking multi-jurisdiction approvals.
- Senior accessibility trade-offs:Torque thresholds that satisfy child-resistant standards often conflict with arthritis-friendly opening mechanisms, limiting addressable markets for aging populations.
Strategic Opportunities
- Nicotine pouch regulation expansion:Emerging state-level mandates for oral nicotine products are extending child-resistant requirements beyond traditional tobacco into adjacent packaging categories.
- Paper-based structural packaging:Fiber-based cartons with integrated locking mechanisms can capture share from plastic bottles as municipal bans on single-use plastics proliferate across Canadian provinces and US cities.
- Dual-lock mechanism patents:Squeeze-and-slide designs with independent certification for cannabis and pharmaceutical applications command premium positioning in state-regulated channels.
Industry Challenges
- Human factors engineering talent:Specialized expertise in child-resistant mechanism design remains concentrated among legacy closure engineers approaching retirement, constraining innovation pipelines.
- Multi-jurisdiction certification timelines:Parallel testing for US Consumer Product Safety Commission, Health Canada, and state cannabis boards extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Child Resistant Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Bags, Boxes, Tubes Material: Plastic, Glass, Metal, Paper Design Type: Push-and-Turn, Squeeze, Child-resistant Blister, Dual-Lock End User: Pharmaceuticals, Cosmetics, Household Products, Food & Beverage |
| Companies Covered | Berry Global Inc., Amcor plc, WestRock Company, AptarGroup, Inc., Gerresheimer AG, O.Berk Company, Comar LLC, CL Smith, MJS Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Child Resistant Packaging Market Evolving Landscape
Material science advances and regulatory precision are converging to redefine performance benchmarks for barrier properties and opening-force consistency across temperature and humidity ranges.
Biodegradable barrier films with integrated tear-resistant layers are fragmenting the traditional plastic monopoly in pharmaceutical blister applications. Specialty compounders in Massachusetts and Quebec are scaling pilot production of polylactic acid blends that maintain child-resistant delamination thresholds. This material transition is fragmenting supplier relationships as brand owners dual-source between conventional and bio-based certification pathways.
The US Consumer Product Safety Commission's 2023 guidance on senior-friendly alternative packaging is forcing recalibration of torque testing protocols. Manufacturers must now validate dual-performance SKUs that pass both child-resistant and senior-accessibility standards simultaneously. Pharmaceutical contract packagers in New Jersey and Illinois are restructuring quality assurance workflows to accommodate parallel certification tracks.
Direct-to-patient subscription models for chronic medications are compressing traditional wholesale distribution channels. Specialty pharmacies now specify child-resistant pouches and wallet packs that integrate with automated dispensing systems rather than standard bottles. This channel shift concentrates demand among e-commerce fulfillment centers in Texas and Tennessee that prioritize dimensional efficiency over retail shelf presence.
North America Child Resistant Packaging Market Segmentation
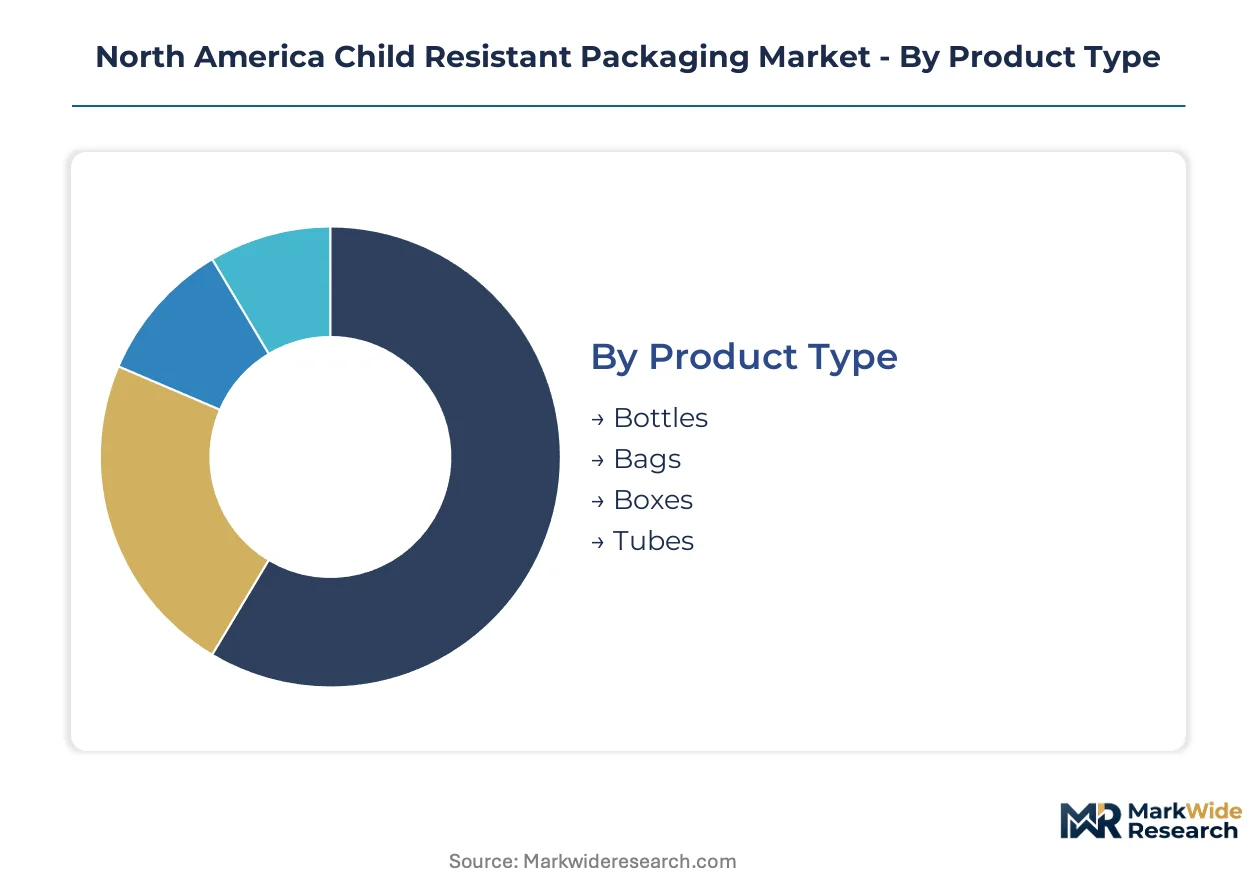
Child-resistant packaging segmentation reveals where substitution pressures and regulatory mandates intersect most intensely. Product format choices increasingly hinge on material compatibility with dual-lock mechanisms and state-level cannabis testing protocols.
Product Type:
Bottles face mounting substitution pressure from flexible formats as e-commerce fulfillment prioritizes dimensional efficiency over shelf presence.
- Bottles:HDPE and PET containers with injection-molded push-and-turn closures dominate pharmaceutical dispensing in California and Texas. Poison Prevention Packaging Act compliance thresholds sustain baseline demand despite rigid format limitations in automated fulfillment.
- Bags:Multi-layer flexible pouches with heat-sealed zipper mechanisms capture cannabis exit-bag mandates in Colorado and Illinois. State boards require resealable child-resistant certification that exceeds federal minimums for single-use containers.
- Boxes:Folding cartons with integrated friction-lock tabs serve cosmetic and nicotine pouch applications where premium unboxing experience competes with safety requirements.
- Tubes:Squeeze-and-slide laminated structures concentrate in topical pharmaceutical and sunscreen segments where dispensing precision matters.
Bottles anchor the volume base while bags gain share at the steepest rate.
Material:
Cost tier stratification separates integrated resin producers from converters dependent on spot-market polyethylene and polypropylene.
- Plastic:Polypropylene homopolymer and impact copolymers enable living-hinge designs for dual-lock closures with consistent torque performance across humidity ranges. Berry Global and Amcor control captive resin supply for pharmaceutical-grade certification.
- Paper:Fiber-based structural boards with moisture-resistant coatings fragment the cosmetic and nicotine pouch segments as Canadian provinces advance single-use plastic bans. WestRock scales integrated pulp-to-carton production for child-resistant folding carton lines.
- Glass:Amber and cobalt blue bottles with polypropylene closures serve light-sensitive pharmaceutical compounds where barrier impermeability outweighs weight penalties.
- Metal:Tinplate and aluminum containers with press-fit closures retain niche positions in solvent-based household chemical applications.
Plastic commands the volume base while paper gains share at the steepest rate.
Design Type:
Application-specific torque requirements fragment engineering resources across divergent human-factors validation protocols.
- Push-and-Turn:The mature standard for pharmaceutical bottles requires 16-25 inch-pounds of simultaneous downward force and rotation. US Consumer Product Safety Commission testing protocols concentrate certification expertise in New Jersey and Ontario laboratories.
- Dual-Lock:Squeeze-and-slide mechanisms with independent latch releases command premium positioning in California cannabis packaging. State mandates require sequential manipulation that exceeds single-action federal standards.
- Squeeze:Compliant closures for tube formats rely on radial compression thresholds validated against child-panel testing.
- Child-resistant Blister:Thermoformed PVC and Aclar laminates with peel-push barriers serve unit-dose pharmaceutical serialization requirements.
Push-and-turn anchors the volume base while dual-lock gains share at the steepest rate.
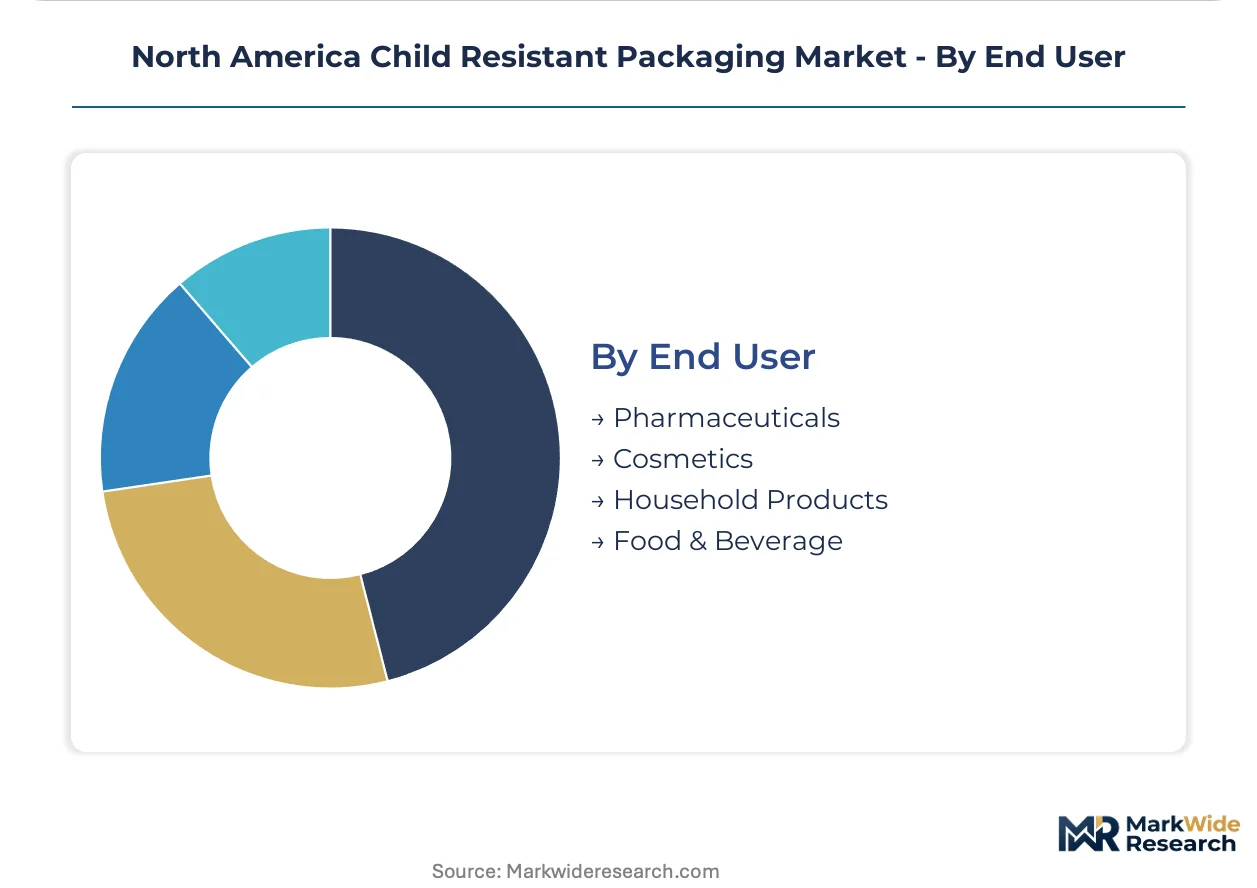
End User:
Customer type determines certification burden intensity, with pharmaceuticals facing the most layered multi-jurisdiction requirements.
- Pharmaceuticals:Prescription and OTC medications drive the largest certification volume through US Consumer Product Safety Commission and Health Canada parallel approvals. Track-and-trace serialization elevates blister packs over bottles for chronic disease therapies distributed through specialty pharmacies.
- Household Products:Cleaning solvents and laundry pods trigger Poison Prevention Packaging Act mandates with less stringent senior-accessibility trade-offs than pharmaceutical applications.
- Cosmetics:Nail care and hair treatment products face emerging state-level child-resistant requirements in California and New York that exceed federal cosmetic safety standards.
- Food & Beverage:Cannabis-infused edibles and beverages impose the most restrictive packaging rules through state cannabis control boards rather than federal food safety regulators.
Pharmaceuticals anchor the volume base while food and beverage gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North America, with Mexican converters absorbing resin price swings most acutely while US pharmaceutical buyers prioritize certification reliability over unit cost.
United States
California and Texas concentrate cannabis and pharmaceutical packaging demand where state boards impose testing protocols exceeding federal minimums. The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act thresholds for household chemicals and OTC medications. New Jersey hosts dense clusters of contract packagers restructuring quality assurance workflows to accommodate dual child-resistant and senior-accessibility certifications.
Canada
Ontario and Quebec drive pharmaceutical-grade demand through Health Canada parallel approval requirements that create cross-border complexity for manufacturers. Provincial single-use plastic bans in British Columbia and Ontario accelerate fiber-based carton adoption against conventional plastic bottles. Montreal and Toronto testing laboratories handle multi-jurisdiction certification bottlenecks that extend product launch timelines.
Mexico
Baja California and Chihuahua house maquiladora operations serving US pharmaceutical contract packaging demand with cost-sensitive resin conversion. Mexico's national consumer protection agency maintains evolving alignment with US Consumer Product Safety Commission standards for exported household chemical containers. Guadalajara clusters emerging flexible packaging converters targeting cannabis-adjacent nicotine pouch formats for US state markets.
North America Child Resistant Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin producers controlling captive supply chains while independent molders compete on customization velocity. The top tier commands pharmaceutical certification relationships that lock in multi-year supply agreements. Three archetypes define competitive positioning: backward-integrated resin converters, specialized closure engineers, and fiber-based structural innovators. Dominant moves include geographic expansion into state cannabis regulatory zones and portfolio diversification across senior-friendly dual-performance formats.
Among North American integrated packaging conglomerates, Berry Global Inc., Amcor plc, and WestRock Company exemplify divergent strategic anchors. Berry Global represents the resin-captive archetype with in-house polypropylene supply for pharmaceutical-grade certification. Amcor occupies the sustainable barrier film position targeting senior-accessibility compliance. WestRock sits within the fiber-based structural tier navigating municipal plastic bans through paperboard locking mechanisms.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| WestRock Company |
| AptarGroup, Inc. |
| Gerresheimer AG |
| O.Berk Company |
| Comar LLC |
| CL Smith |
| MJS Packaging |
| Others |
Value Network & Pricing Analysis
Polylactic acid blends displacing polypropylene in pharmaceutical blister applications are simultaneously relocating pilot production to Massachusetts and Quebec while compressing margin premiums for conventional resin converters. This material transition fragments supplier relationships as brand owners dual-source certification pathways, forcing parallel inventory strategies across bio-based and petroleum-derived feedstocks.
Pricing Analysis
After-market certification renewal revenue sustains lifetime value for testing laboratories in California and Ontario. Three-tier pricing structure across pharmaceutical-grade, cannabis-compliant, and household chemical tiers separates torque-validated closures from basic push-and-turn designs. Price differentiation hinges on Health Canada parallel approval complexity and state cannabis board supplemental testing. Pricing pressure stems from resin cost volatility as polypropylene spot markets fluctuate with petrochemical feedstock indices. Contract packagers in New Jersey exhibit highest price sensitivity due to compressed fulfillment margins, while integrated resin producers like Berry Global maintain lowest sensitivity through captive supply.
Supply Chain Analysis
Third-party certification capacity clustering in California and Ontario creates bottlenecks that extend multi-jurisdiction approval timelines for manufacturers seeking US Consumer Product Safety Commission and Health Canada validation. Raw material supply draws from US Gulf Coast polypropylene production, Alberta polyethylene feedstocks, and emerging Quebec polylactic acid pilot facilities. Supply chain risk centers on single-source vulnerability for specialized child-panel testing laboratories in Toronto and New Jersey. Distribution runs through pharmaceutical contract packagers in Illinois and New Jersey, cannabis fulfillment centers in Colorado and California, and e-commerce hubs in Texas and Tennessee.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among specialty pharmacy chains and cannabis multi-state operators, consolidating procurement volumes for child-resistant packaging into fewer purchasing decision-makers with expanded negotiating leverage.
For Market Incumbents: Consolidate certification relationships with US Consumer Product Safety Commission and Health Canada laboratories to lock in multi-year supply agreements before testing capacity constraints worsen. Acquire dual-lock mechanism patents in California cannabis packaging to defend against squeeze-and-slide specialists entering from adjacent nicotine pouch markets. Prioritize backward integration into resin production to offset polypropylene cost volatility compressing margins for pure-play closure molders. For New Entrants and Emerging Players: Senior-accessibility engineering services represent an under-served layer where incumbents under-invest in arthritis-friendly torque validation. Target Illinois and Colorado cannabis packaging with dual-performance SKUs that satisfy both child-resistant and senior-accessibility standards simultaneously. Pursue white-label partnerships with emerging oral nicotine pouch brands seeking state-compliant exit packaging ahead of federal harmonization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible packaging converters in Baja California maquiladora zones serving US pharmaceutical demand with undifferentiated resin conversion. Frame long-term viability around regulatory complexity persistence rather than commoditization risk, as multi-jurisdiction certification timelines extend product launch cycles. Watch for federal cannabis packaging harmonization efforts as the inflection signal that would reshape state-level testing burdens and certification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Lock Mechanism Patent Acquisition | Captures premium positioning in California cannabis exit-bag mandates exceeding federal minimums. |
| Backward Integration into Resin Production | Insulates margin compression from polypropylene spot market volatility in Gulf Coast feedstocks. |
| Senior-Accessibility Certification Investment | Addresses US Consumer Product Safety Commission 2023 guidance on dual-performance SKU validation. |
| Multi-Jurisdiction Testing Laboratory Partnership | Reduces eight-to-fourteen-month certification timelines for Health Canada parallel approvals. |
| Fiber-Based Structural Packaging Scale-Up | Navigates British Columbia and Ontario single-use plastic bans through paperboard locking mechanisms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of US Consumer Product Safety Commission enforcement databases, Health Canada pharmaceutical guidance documents, and state cannabis board regulatory filings. Primary interviews engaged packaging engineers at pharmaceutical contract manufacturers, procurement directors at specialty pharmacy chains, regulatory affairs managers at cannabis multi-state operators, and testing laboratory technicians in California and Ontario. Secondary validation drew from FDA packaging guidance archives, SEC 10-K disclosures by integrated packaging conglomerates, and customs trade data on resin imports. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, design mechanism, and end-user dimensions.
Segmentation dimensions modeled include product format, material substrate, closure design type, and end-user industry across the projection horizon. The analytical framework incorporates pharmaceutical serialization requirements, state cannabis packaging mandates, and household chemical compliance thresholds throughout the forecast period. CAGRs were derived from regression analysis of historical adoption curves weighted by regulatory enforcement intensity and substitution dynamics between bottles and flexible formats. Industry-specific inputs encompassed torque testing protocol evolution, resin price elasticity by buyer archetype, and e-commerce fulfillment channel shift velocities.
Underlying assumptions cover sustained Poison Prevention Packaging Act enforcement, continued state-federal regulatory divergence in cannabis packaging, and stable petrochemical feedstock pricing, with deviation risk concentrated in federal harmonization efforts and biodegradable barrier film scale-up timelines. Practitioners should keep alternative scenarios live as senior-accessibility standard adoption and municipal plastic ban proliferation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Packaging Solutions Market