
 Hip Orthosis Market | 2026-2036
Hip Orthosis Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Orthosis Market Analysis
German prosthetic component manufacturers is broadening fabrication capacity for carbon fiber hip braces to serve European and North American contract orders. Ottobock leverages its polymer research campus in Duderstadt to sustain premium positioning across custom-molded lines. Bauerfeind anchors its competitive stance through orthopedic clinic partnerships that extend trained fitting services. Ossur competes on adjustable mechanism patents that dominate acute-phase rehabilitation protocols.
A hip orthosis is a mechanical external device that stabilizes the pelvic-femoral joint through calibrated articulation limits, typically employing aluminum uprights, thermoplastic pelvic bands, and thigh cuffs with 0-90 degree flexion control to prevent dislocation or support post-surgical tissue healing. Carbon fiber technology commands premium pricing due to strength-to-weight ratios that reduce patient fatigue during extended ambulation. Post-operative orthosis generates the largest revenue pool given mandatory deployment following total hip arthroplasty, while 3D printed segments attract fastest-growing interest from orthopedic clinics seeking patient-specific anatomic fits that improve compliance duration.
FDA 510(k) premarket notification requirements govern hip orthosis commercialization in the United States, with ISO 13485 quality management certification serving as baseline market access credential for European and Asian distribution. The EU Medical Device Regulation intensifies clinical evidence expectations for Class IIa devices, compelling manufacturers to expand post-market surveillance infrastructure. Stakeholders must monitor reimbursement code consolidation across Medicare Advantage plans that directly influences hospital procurement committee priorities.
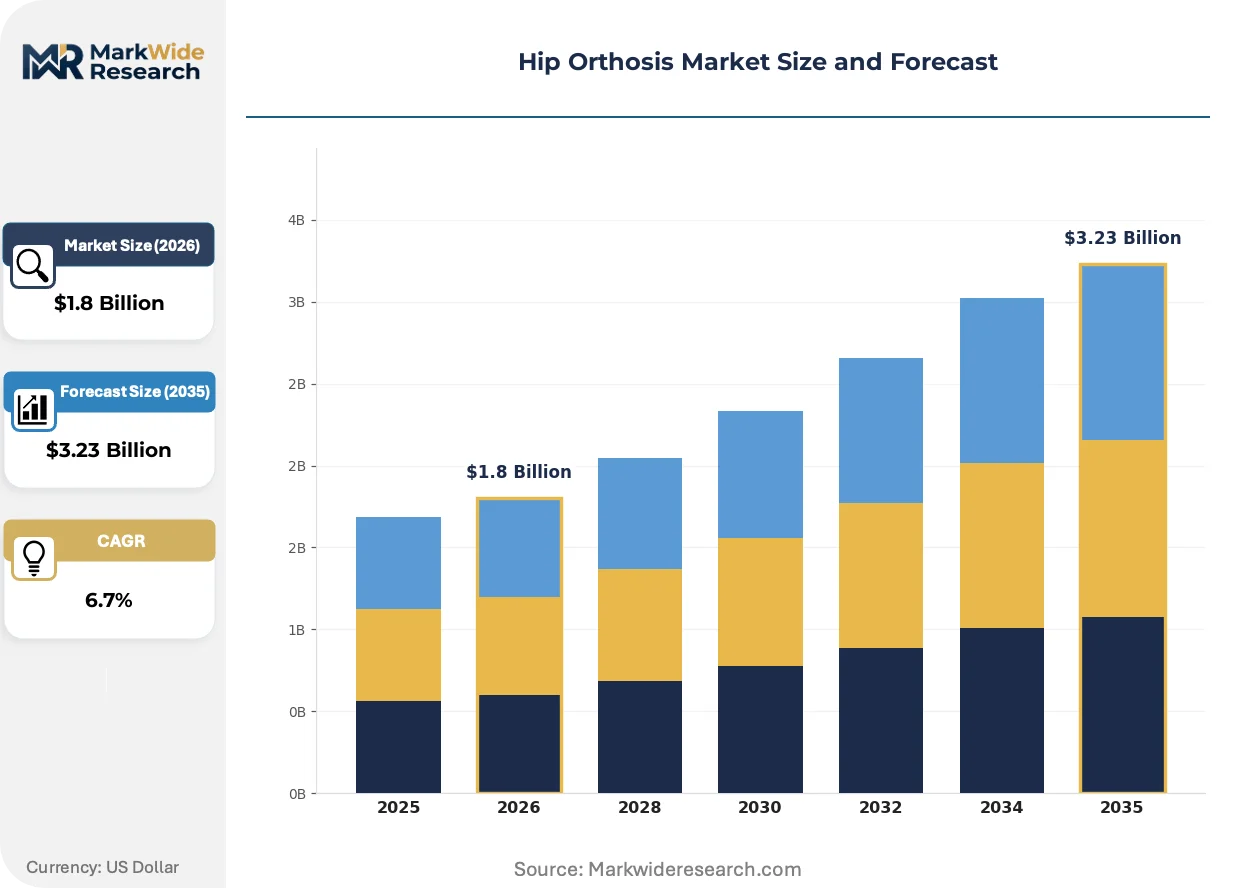
Market Dynamics
Carbon fiber manufacturing consolidation in Germany and the United States is compressing supply timelines for premium hip orthosis components while forcing mid-tier fabricators toward aluminum alternatives. This material bifurcation is reshaping competitive tiers across post-operative and ambulatory segments.
Growth Catalysts
- EU Medical Device Regulation (MDR) compliance mandates:Class IIa device reclassification is accelerating hospital procurement of ISO 13485-certified hip stabilization systems to preempt supply disruptions.
- Polymer research campuses:Advanced thermoplastic formulation facilities in Lower Saxony are enabling rapid prototyping cycles that shorten custom-molded orthosis delivery windows.
- Post-operative rehabilitation protocols:Mandatory hip orthosis deployment following total hip arthroplasty in United States Medicare Advantage networks sustains baseline clinical demand.
Market Restraints
- Carbon fiber feedstock volatility:Aerospace sector competition for polyacrylonitrile precursor strains orthosis manufacturer margins during supply contractions.
- Single-source articulation hinge suppliers:Concentrated precision machining capacity in Swiss manufacturing clusters creates vulnerability for adjustable mechanism producers.
- Biomechanical fitting complexity:Pelvic-femoral joint measurement standardization gaps between orthopedic clinics limit scalable remote configuration services.
Strategic Opportunities
- 3D printing convergence with AI-driven gait analysis:Orthopedic clinics in the Netherlands are piloting patient-specific anatomic fits that extend compliance duration through dynamic pressure mapping integration.
- United States rural health clinic penetration:Underserved regions in the Mountain West present white space for telehealth-integrated fitting services that reduce specialist travel burdens.
- Japanese long-term care insurance expansion:METI-guided reimbursement revisions for geriatric mobility devices are opening public payer channels previously restricted to acute-care procurement.
Industry Challenges
- Certified orthotist workforce scarcity:United States Bureau of Labor Statistics data shows insufficient trained fitting specialists to match expanding ambulatory surgery center volumes.
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel articulation mechanisms require extended clinical documentation timelines that delay revenue recognition.
- Legacy hospital ERP integration:Orthosis inventory management systems frequently conflict with orthopedic implant procurement platforms, creating reconciliation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Orthosis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Orthosis, Rigid Orthosis, Adjustable Orthosis, Post-Operative Orthosis End User: Hospitals, Rehabilitation Centers, Home Care, Orthopedic Clinics Technology: Traditional Design, 3D Printed, Custom Molded, Carbon Fiber Distribution Channel: Online Sales, Retail Pharmacies, Specialty Stores, Direct Sales |
| Companies Covered | Corflex, Ottobock, Bauerfeind, RSLSteeper, Fillauer, Ossur, RCAI Restorative Care of America, Innovation Rehab, DonJoy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Orthosis Market Emerging Trajectories
Digital fabrication workflows are compressing the gap between clinical measurement and device delivery, while regulatory harmonization efforts across North America and Europe are recalibrating quality management investments.
Sensor-embedded hip orthosis systems are unifying real-time kinematic feedback with post-surgical rehabilitation protocols. Academic medical centers in Massachusetts and Bavaria are deploying pressure-sensitive thigh cuffs that transmit ambulation data to physical therapy dashboards. This convergence is unifying hardware reimbursement with remote monitoring service codes, compressing the traditional separation between device and care delivery economics.
The EU Medical Device Regulation's post-market surveillance requirements are intensifying clinical evidence obligations for Class IIa orthotic devices. Manufacturers must now maintain systematic complaint registries and periodic safety update reports that extend quality infrastructure costs. German and Irish notified bodies are experiencing backlog concentrations that delay CE marking timelines for novel carbon fiber frame designs.
Hospital procurement committees are consolidating vendor relationships through orthopedic implant bundling agreements that attach hip orthosis supply to arthroplasty device contracts. Independent durable medical equipment distributors in the United States Southeast are losing shelf access as integrated delivery networks centralize purchasing. This concentration is most visible in Florida and Texas health systems where Medicare Advantage penetration drives standardized device formularies.
Hip Orthosis Market Segmentation
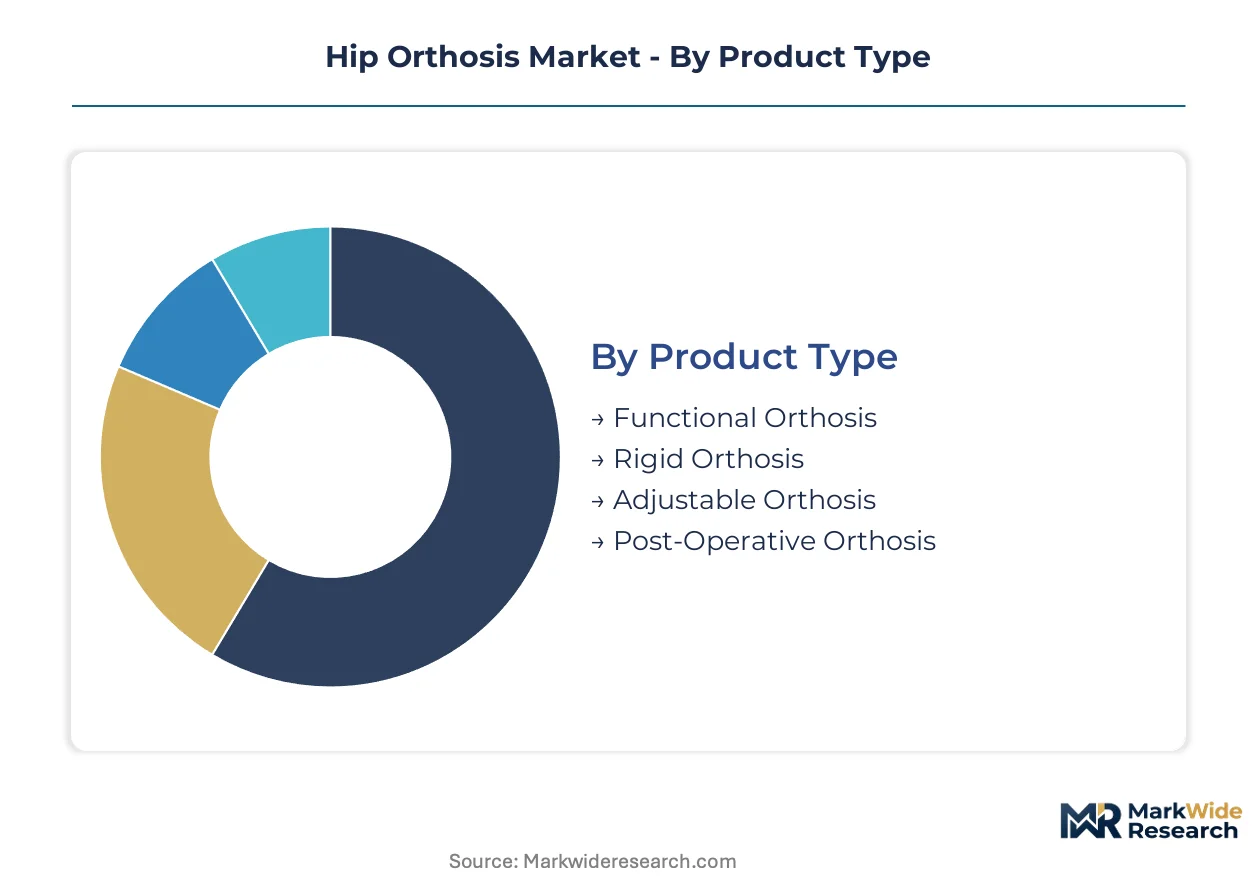
Hip orthosis segmentation reflects divergent clinical priorities across acute intervention and long-term mobility management. Material science investments and reimbursement pathway fragmentation create distinct competitive arenas within each category.
Product Type:
Volume concentration favors standardized post-surgical devices, while premium margins attach to articulation sophistication.
- Post-Operative Orthosis:Rigid frame assemblies with 0-90 degree flexion stops dominate hospital procurement following total hip arthroplasty. United States Medicare Advantage networks mandate deployment, creating predictable demand concentration.
- Adjustable Orthosis:Hinge mechanisms with calibrated resistance settings serve acute-phase rehabilitation protocols. Swiss precision machining clusters supply articulation components that command premium positioning.
- Functional Orthosis:Dynamic support systems for ambulatory patients with neuromuscular conditions.
- Rigid Orthosis:Fixed-position frames for maximum stability in dislocation prevention.
Mature deployment sits with Post-Operative Orthosis. Newer deployment is concentrated in Adjustable Orthosis.
End User:
Procurement authority determines pricing tolerance, with institutional buyers extracting volume discounts unavailable to individual purchasers.
- Hospitals:Integrated delivery networks in Florida and Texas centralize purchasing through orthopedic implant bundling agreements. Device formularies standardize on carbon fiber frames for premium positioning.
- Orthopedic Clinics:Custom fitting services generate recurring revenue through patient-specific configuration. Netherlands-based clinics pilot AI-driven gait analysis integration.
- Rehabilitation Centers:Extended-stay facilities prioritize durability for high-utilization environments.
- Home Care:Direct-to-patient channels expand with telehealth-integrated remote fitting services.
Reimbursement stability favors Hospitals. Steepest expansion trajectory belongs to Orthopedic Clinics.
Technology:
Manufacturing sophistication separates price tiers, with fabrication method directly determining clinical customization depth.
- Carbon Fiber:Polyacrylonitrile precursor frames deliver strength-to-weight ratios that reduce patient fatigue during extended ambulation. Aerospace sector competition for feedstock strains manufacturer margins.
- 3D Printed:Patient-specific anatomic fits improve compliance duration through dynamic pressure mapping. Netherlands and Massachusetts academic medical centers deploy sensor-embedded prototypes.
- Custom Molded:Thermoplastic formulations from Lower Saxony research campuses enable rapid prototyping cycles.
- Traditional Design:Aluminum uprights and standard pelvic bands serve cost-sensitive procurement.
Volume concentration remains with Traditional Design. Technology transition is accelerating in 3D Printed.
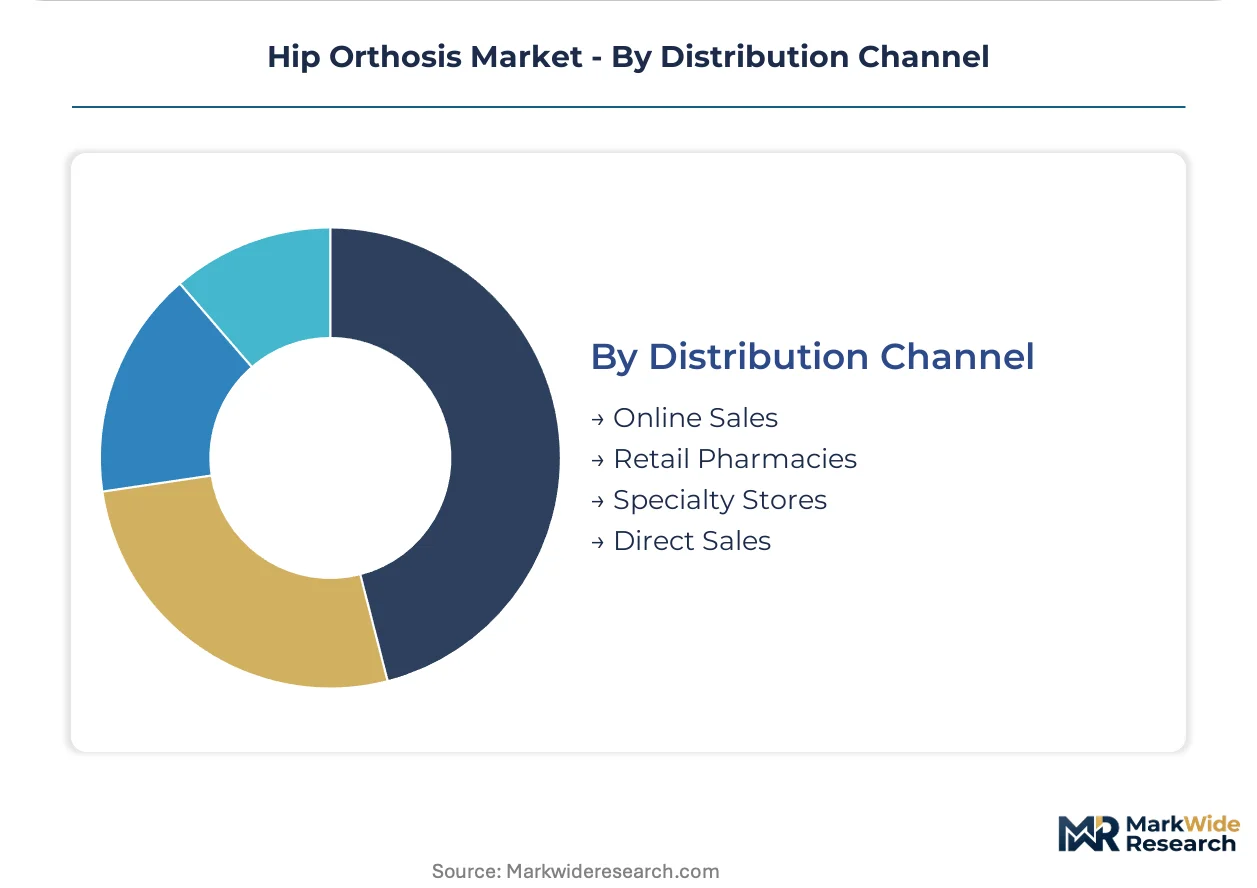
Distribution Channel:
Channel selection reflects patient acuity and configuration complexity, with high-touch fitting requirements limiting pure digital penetration.
- Direct Sales:Manufacturer representatives serve integrated delivery networks with implant bundling agreements. Hospital procurement committees consolidate vendor relationships through orthopedic device contracts.
- Specialty Stores:Certified orthotist staffing supports complex fitting requirements. United States Southeast independent distributors lose shelf access to network centralization.
- Retail Pharmacies:Standardized off-the-shelf products for uncomplicated post-surgical support.
- Online Sales:Remote configuration services target rural Mountain West regions with specialist access gaps.
Established penetration centers on Direct Sales. Channel experimentation is expanding fastest in Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyacrylonitrile precursor manufacturing clusters in Germany and the United States anchor carbon fiber supply for premium hip orthosis fabrication. Aerospace sector competition for feedstock strains margins across both markets. Regional procurement patterns diverge between Medicare-governed hospital networks and EU MDR-compliant integrated delivery systems.
United States
Medicare Advantage networks mandate post-operative hip orthosis deployment following total hip arthroplasty, creating predictable hospital procurement volume. FDA 510(k) premarket notification pathways govern Class II device commercialization timelines. Integrated delivery networks in Florida and Texas centralize purchasing through orthopedic implant bundling agreements that standardize carbon fiber frame formularies.
Germany
EU Medical Device Regulation Class IIa reclassification accelerates ISO 13485-certified system adoption to preempt supply disruptions. German and Irish notified bodies experience backlog concentrations that delay CE marking for novel frame designs. Lower Saxony polymer research campuses enable rapid prototyping cycles for custom-molded orthosis delivery.
Japan
METI-guided reimbursement revisions for geriatric mobility devices open public payer channels previously restricted to acute-care procurement. Aging demographics drive consistent clinical uptake of hip stabilization systems. Academic medical centers in Kanto deploy sensor-embedded prototypes with real-time kinematic feedback integration.
Netherlands
Orthopedic clinics pilot AI-driven gait analysis convergence with 3D printing for patient-specific anatomic fits that extend compliance duration. EU MDR post-market surveillance requirements intensify clinical evidence obligations for Class IIa devices. Eindhoven Region fabrication facilities experiment with dynamic pressure mapping integration.
Switzerland
Precision machining clusters supply articulation hinge components that command premium positioning in adjustable mechanism segments. Single-source supplier concentration creates vulnerability for producers dependent on calibrated resistance settings. Swissmedic oversight aligns with EU MDR equivalence agreements for cross-border distribution.
Hip Orthosis Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital fabrication and sensor-embedded differentiation. The vendor base separates into three maturity tiers: legacy manufacturers with hospital procurement relationships, mid-scale fabricators with regional orthopedic clinic networks, and technology-focused startups advancing 3D printing workflows. Dominant competitive moves include backward integration into carbon fiber precursor supply and strategic partnerships with academic medical centers for clinical validation.
Within the premium-tier vector, Ottobock and Ossur exemplify archetypes of research-intensive positioning. Ottobock anchors its stance through polymer formulation capabilities tied to geographic research infrastructure. Ossur occupies a position defined by adjustable mechanism intellectual property. Bauerfeind represents the clinical partnership archetype, with orthopedic clinic networks extending trained fitting services as a competitive moat.
| Leading Market Players |
|---|
| Corflex |
| Ottobock |
| Bauerfeind |
| RSLSteeper |
| Fillauer |
| Ossur |
| RCAI Restorative Care of America |
| Innovation Rehab |
| DonJoy |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in Florida and Texas anchor procurement volume through orthopedic implant bundling agreements that compress vendor margins while standardizing carbon fiber frame specifications across hospital formularies. This buyer concentration forces three-tier pricing stratification across premium custom-molded, standard adjustable, and economy aluminum upright segments.
Pricing Analysis
Warranty and fitting service bundling separates premium positioning from unbundled transactional sales in mid-tier channels. Carbon fiber frames with multi-year coverage and certified orthotist support command substantial premiums over aluminum alternatives sold through retail pharmacy without configuration assistance. Price differentiation rests on ISO 13485 certification tier and geographic delivery cost to rural Mountain West regions. Pricing pressure stems from aerospace sector competition for polyacrylonitrile precursor that strains manufacturer margins. Home care direct-to-patient channels exhibit highest price sensitivity due to limited reimbursement coverage.
Supply Chain Analysis
ISO 13485 and FDA 510(k) qualification gating restricts component sourcing to certified precision machining clusters in Switzerland, polymer research campuses in Lower Saxony, and carbon fiber fabrication facilities in Germany and the United States. Raw material dependencies center on polyacrylonitrile precursor, thermoplastic pelvic band formulations, and Swiss-manufactured articulation hinges. Single-source supplier concentration for calibrated resistance mechanisms creates vulnerability for adjustable mechanism producers. Distribution runs through manufacturer direct sales to integrated delivery networks, with independent specialty stores losing shelf access to network centralization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hip orthosis market sits in a technology-transition phase where 3D printing convergence with AI-driven gait analysis is displacing traditional custom-molded fabrication workflows across Netherlands and Massachusetts academic medical centers.
For Market Incumbents: Extend polymer research capabilities through backward integration into carbon fiber precursor supply to defend margin position against aerospace sector feedstock competition. Ottobock's Duderstadt campus model demonstrates how captive thermoplastic formulation capacity sustains premium positioning. Reinforce hospital procurement relationships through orthopedic implant bundling agreements before integrated delivery networks complete vendor consolidation in Florida and Texas health systems. For New Entrants and Emerging Players: Rural Mountain West health clinics represent the most penetrable buyer archetype for telehealth-integrated remote fitting services that reduce specialist travel burdens. Japanese long-term care insurance expansion under METI guidance opens public payer channels previously restricted to acute-care procurement. A direct-to-patient digital configuration platform with AI-driven measurement tools offers the clearest go-to-market angle against established distributor networks. For Investors and Strategic Acquirers: The window for entry favors technology-focused startups with validated 3D printing workflows and academic medical center clinical partnerships. Long-term viability over the next decade hinges on sensor-embedded hardware reimbursement convergence with remote monitoring service codes. The signal to monitor is Medicare Advantage plan reimbursement code consolidation that would accelerate hospital procurement committee standardization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa reclassification accelerates ISO 13485-certified system adoption across German and Irish notified body jurisdictions. |
| Hospital System Partnership | Orthopedic implant bundling agreements in Florida and Texas integrated delivery networks standardize carbon fiber frame formularies. |
| Software Companion Development | Sensor-embedded thigh cuffs with real-time kinematic feedback unify hardware reimbursement with remote monitoring service codes. |
| Reimbursement Strategy | METI-guided Japanese long-term care insurance revisions open public payer channels for geriatric mobility devices. |
| Backward Integration | Carbon fiber precursor supply control defends margins against aerospace sector polyacrylonitrile competition. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings from primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA 510(k) filings, EU MDR notified body registries, and orthopedic clinic procurement records. Bottom-up segmentation modeling and top-down macroeconomic triangulation reconcile volume and value estimates.
Comparable historical reference periods across post-operative rehabilitation protocol changes and reimbursement code revisions anchor the projection horizon. The analytical framework models product type, end user, technology, and distribution channel dimensions alongside regional regulatory cluster variations. CAGRs derive from procedure volume trajectories, material cost curves, and certification timeline assumptions. Forecast inputs incorporate carbon fiber feedstock availability and certified orthotist workforce expansion rates.
Revisions become necessary when EU MDR notified body backlog concentrations, Medicare Advantage reimbursement consolidations, or aerospace sector polyacrylonitrile demand surges materialize beyond baseline assumptions. Forecasts reflect documented assumptions about hospital procurement centralization and 3D printing adoption curves. A model refresh is warranted upon material change in FDA 510(k) predicate device determination timelines or Japanese METI reimbursement revision implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Smart Orthopedic Implants Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Animal External Fixation Market