
 Physiotherapy Devices Market | 2026-2036
Physiotherapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Physiotherapy Devices Market Outlook
Remote monitoring subscriptions and software-defined treatment protocols is broadening what physiotherapy device vendors actually sell. Zimmer MedizinSysteme GmbH leverages its German engineering base to sustain premium positioning across European hospital procurement channels. Performance Health competes through dense distribution networks that supply clinics with bundled exercise equipment and consumables. Dynatronics Corporation anchors its presence in North American physical therapy practices with integrated electrotherapy and ultrasound platforms.
Physiotherapy devices encompass therapeutic instruments that apply mechanical, thermal, electrical, or electromagnetic energy to musculoskeletal tissue, typically operating at ultrasound frequencies between 1–3 MHz or electrical stimulation pulse widths of 50–400 microseconds to promote tissue repair, modulate pain signaling, or restore range of motion. Electrotherapy devices command the largest installed base among product types due to their versatility across pain management and rehabilitation protocols, while laser therapy within the technology dimension captures expanding interest from sports medicine practitioners seeking non-invasive soft-tissue interventions. Exercise equipment retains mature demand profiles in hospital settings, though home care channels show structural momentum as remote therapeutic monitoring integrations improve.
The FDA regulates therapeutic devices under 21 CFR Part 890 physical medicine instruments, requiring substantial equivalence demonstrations for market entry, while the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for CE-marked electrotherapy and ultrasound systems. Germany's Federal Institute for Drugs and Medical Devices enforces MDR conformity assessments that shape product development priorities for vendors targeting European reimbursement eligibility. Stakeholders must monitor evolving digital health integration standards that determine whether connected physiotherapy platforms qualify for preferential procurement in integrated care systems.
Market Dynamics
Software-enabled treatment protocols are compressing hardware replacement cycles while expanding recurring revenue streams for physiotherapy device vendors. Clinics now evaluate capital purchases through total cost-of-ownership lenses that weight subscription analytics and remote monitoring capabilities alongside traditional electrotherapy specifications.
Growth Catalysts
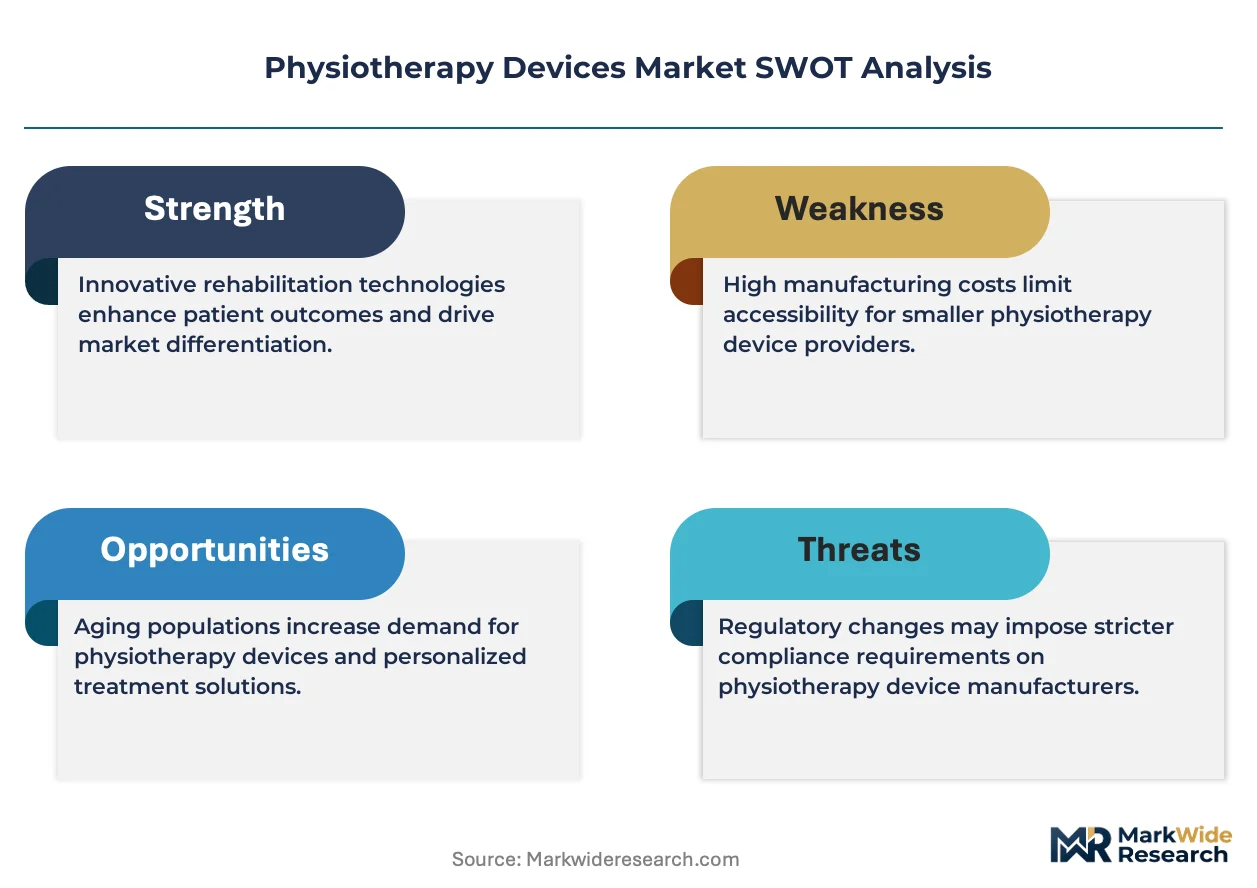
- Statutory reimbursement frameworks:Germany's statutory health insurance system reimburses physiotherapy sessions at standardized rates, sustaining predictable capital expenditure cycles for electrotherapy and laser equipment procurement across clinic networks.
- Sports medicine volume expansion:Professional and amateur athletic programs are embedding physiotherapy modalities into injury prevention protocols, driving demand for portable ultrasound and electrical stimulation units.
- Home care channel maturation:Remote therapeutic monitoring integrations are validating prescription-grade devices for residential deployment, extending manufacturer reach beyond institutional settings.
Market Restraints
- Input cost concentration:Piezoelectric ceramic suppliers in East Asia control critical raw material flows for therapeutic ultrasound transducers, exposing manufacturers to supply disruption risks.
- Technical performance ceilings:Electrical stimulation devices face physiological tolerance limits that constrain pulse parameter expansion, capping efficacy differentiation between product tiers.
- Regulatory pathway friction:FDA 510(k) clearance requirements for novel therapeutic indications demand substantial equivalence demonstrations that extend development timelines and elevate compliance expenditures.
Strategic Opportunities
- Rural clinic penetration:Underpenetrated secondary cities in India present whitespace for affordable electrotherapy platforms as outpatient rehabilitation infrastructure expands under national health mission programs.
- Technology convergence:Integration of artificial intelligence motion tracking with resistance-based exercise equipment is enabling real-time form correction and adaptive loading protocols.
- Direct-to-patient channels:Telehealth-integrated device rental models are bypassing traditional distributor networks, capturing margin compression value and generating usage data assets.
Industry Challenges
- Specialized technician scarcity:Clinical engineers capable of servicing integrated electrotherapy-ultrasound platforms remain concentrated in metropolitan hospital systems, constraining field support scalability.
- Legacy system interoperability:Electronic health record integration requirements force device manufacturers to maintain multiple connectivity protocols, elevating firmware complexity and certification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physiotherapy Devices Market |
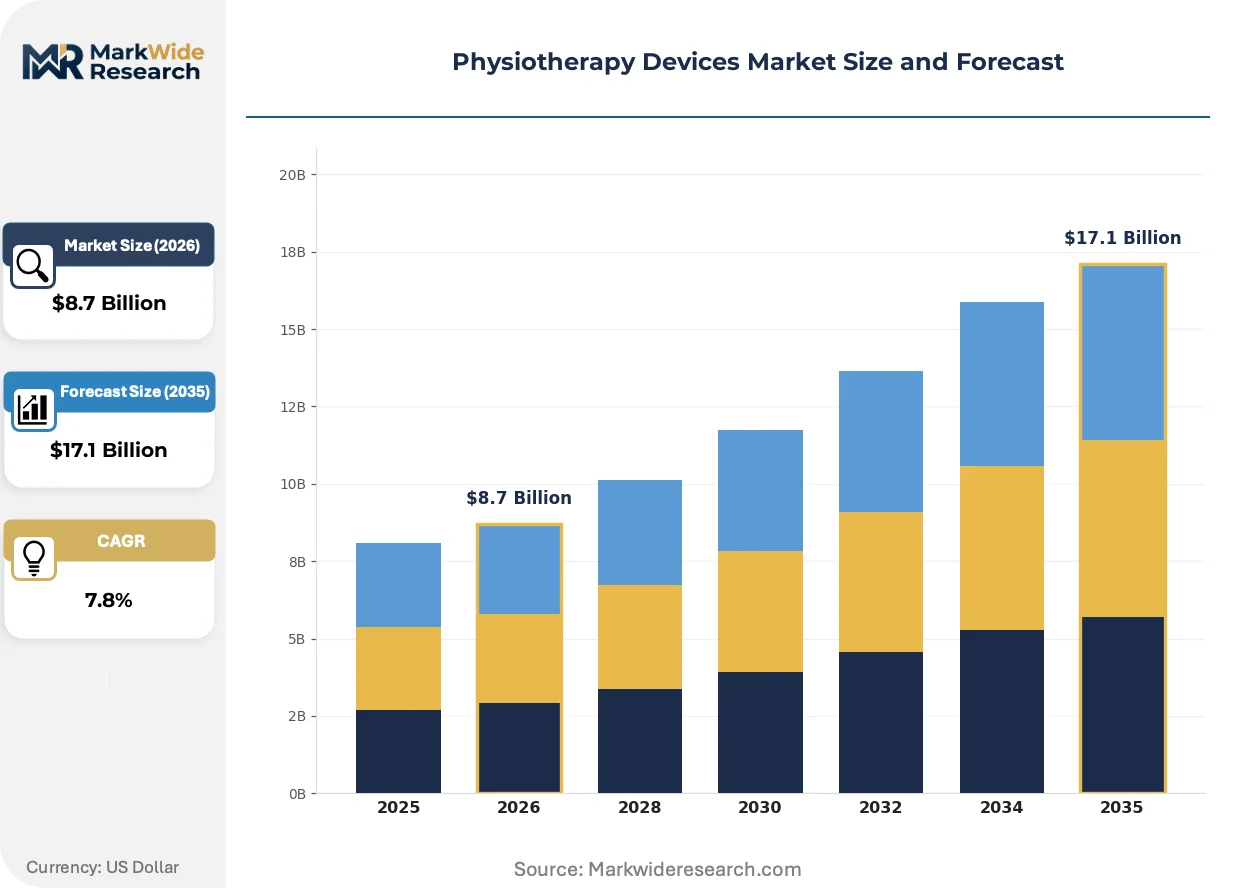
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Therapy Devices, Electrotherapy Devices, Exercise Equipment, Continuous Passive Motion Devices Application: Rehabilitation, Pain Management, Sports Medicine, Orthopedic End User: Clinics, Hospitals, Home Care, Sports Facilities Technology: Electrical Stimulation, Laser Therapy, Biofeedback, Cryotherapy |
| Companies Covered | BTL Industries, Enovis Corporation, Dynatronics Corporation, Enraf-Nonius B.V., EMS Physio Ltd., Zimmer MedizinSysteme GmbH, Performance Health, Storz Medical AG, Zynex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physiotherapy Devices Market Strategic Shifts
Digital biomarker extraction and predictive analytics are repositioning physiotherapy hardware as data collection infrastructure. Vendors now compete on algorithmic treatment personalization rather than pulse parameter specifications alone.
Photobiomodulation systems utilizing specific wavelength combinations are expanding into post-operative rehabilitation protocols. Orthopedic surgery centers in the United States are adopting these platforms for accelerated soft-tissue healing. The technology is expanding into ambulatory surgical center discharge bundles as standard-of-care expectations shift.
EU Medical Device Regulation clinical evaluation requirements are elevating post-market surveillance obligations for electrotherapy manufacturers. Vendors must now maintain systematic literature reviews and vigilance reporting systems that extend beyond pre-market clearance. German and French notified bodies are enforcing these mandates most stringently, compressing competitive timelines for smaller market entrants.
Subscription-based equipment access is displacing outright purchase models among independent physiotherapy practices. Leasing arrangements bundle maintenance, software updates, and consumable replenishment into predictable monthly obligations. This pattern concentrates most visibly in the United Kingdom where practice consolidation has elevated purchasing sophistication.
Physiotherapy Devices Market Segmentation
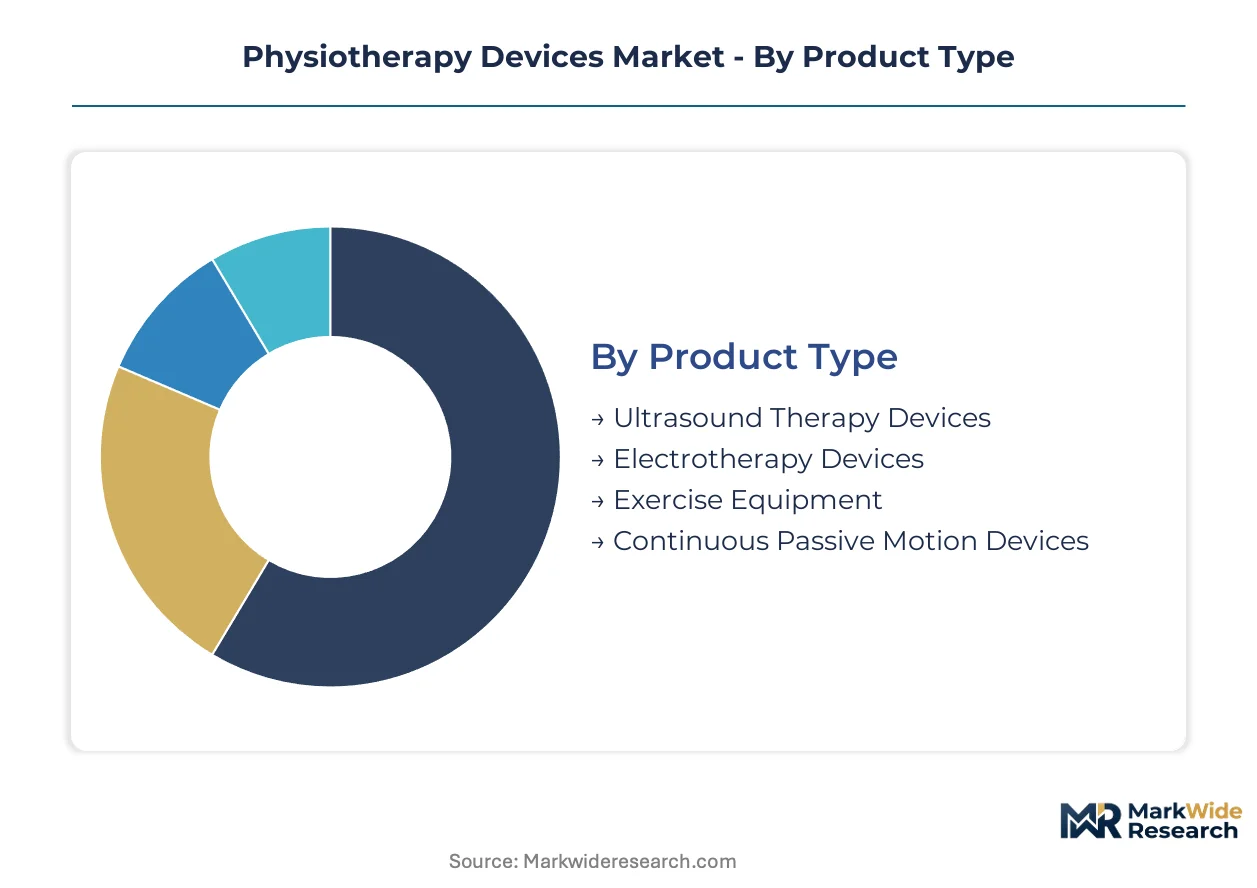
Physiotherapy device purchasing decisions fragment across technical specifications, clinical settings, and reimbursement pathways. Understanding where specifications concentrate versus where deployment scales reveals vendor prioritization logic and capital allocation efficiency across the value chain.
Product Type:
Ultrasound and electrotherapy platforms anchor procurement specifications through frequency range and waveform precision requirements.
- Electrotherapy Devices:These systems deliver controlled electrical impulses through surface electrodes at pulse widths of 50–400 microseconds for neuromuscular stimulation and pain modulation. Demand clusters in German statutory insurance-funded clinics where reimbursement reliability sustains capital replacement cycles for TENS and NMES platforms.
- Ultrasound Therapy Devices:Therapeutic ultrasound systems operate at 1–3 MHz frequencies to generate thermal and mechanical tissue effects. Sports medicine clinics in the United States drive procurement volume as FDA 510(k) clearance pathways validate clinical claims for soft-tissue injury protocols.
- Exercise Equipment:Resistance-based rehabilitation systems support range-of-motion restoration through progressive loading protocols.
- Continuous Passive Motion Devices:Motorized joint mobilization systems automate post-surgical rehabilitation for knee and shoulder procedures.
Mature deployment sits with Electrotherapy Devices. Newer deployment is concentrated in Continuous Passive Motion Devices.
Application:
Clinical use cases diverge between acute intervention protocols and long-term functional restoration programs.
- Pain Management:Non-pharmacological interventions targeting nociceptive and neuropathic pain pathways through modulated electrical or thermal energy delivery. Hospital outpatient departments in Germany prioritize these modalities given statutory reimbursement alignment and opioid reduction mandates.
- Sports Medicine:Injury prevention and accelerated return-to-play protocols for athletic populations. United States collegiate and professional athletic programs sustain demand for portable ultrasound and electrical stimulation units with validated efficacy data.
- Rehabilitation:Post-acute functional restoration programs following neurological or orthopedic events.
- Orthopedic:Post-surgical protocols targeting joint replacement and fracture recovery timelines.
Volume concentration favors Pain Management. Margin expansion is concentrating in Sports Medicine.
End User:
Procurement authority and reimbursement eligibility shape capital expenditure patterns across institutional and residential settings.
- Clinics:Independent physiotherapy practices and multi-site clinic networks constitute the primary volume channel. German clinic chains leverage statutory health insurance contracts to standardize equipment procurement across regional footprints.
- Hospitals:Acute care and rehabilitation hospitals integrate physiotherapy devices into comprehensive service lines. United States health systems prioritize EHR-integrated platforms that satisfy interoperability requirements for value-based care contracts.
- Home Care:Prescription-grade devices for residential deployment under remote therapeutic monitoring protocols.
- Sports Facilities:Dedicated athletic training centers and professional team medical departments.
Reimbursement stability sits with Clinics. Channel expansion is accelerating in Home Care.
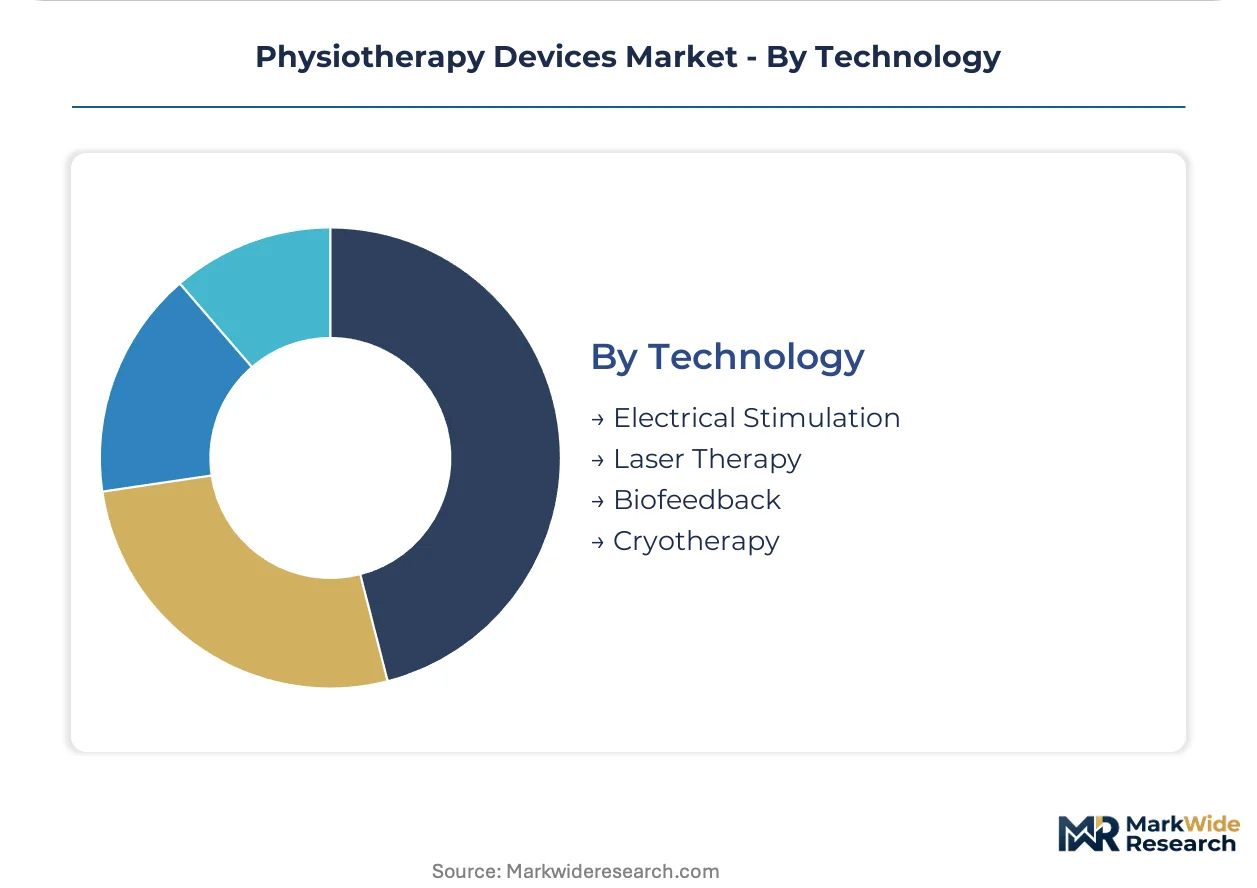
Technology:
Energy delivery mechanisms differentiate clinical efficacy claims and regulatory clearance pathways.
- Electrical Stimulation:Waveform-controlled current delivery systems for neuromuscular activation and pain gate modulation. FDA 510(k) substantial equivalence requirements for novel indications extend development timelines for parameter expansion claims.
- Laser Therapy:Photobiomodulation systems utilizing specific wavelength combinations for soft-tissue healing acceleration. Orthopedic surgery centers in the United States are adopting these platforms for post-operative rehabilitation bundles.
- Biofeedback:Real-time physiological signal monitoring for patient-guided neuromuscular re-education.
- Cryotherapy:Controlled cold thermal delivery for inflammation management and pain reduction.
Regulatory clarity sits with Electrical Stimulation. Clinical validation investment is concentrating in Laser Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Germany and the United States, while demand absorption spreads across statutory reimbursement markets and sports medicine corridors. Production capabilities anchor in precision engineering clusters, with consumption patterns tracking regulatory clarity and insurance coverage depth.
United States
Sports medicine clinics and orthopedic surgery centers drive procurement volume for therapeutic ultrasound and electrical stimulation platforms. The FDA's 510(k) clearance pathway under 21 CFR Part 890 shapes product development timelines and clinical claim validation. The Boston-Cambridge corridor hosts medical device engineering talent pools that feed into electrotherapy platform innovation.
Germany
Statutory health insurance reimbursement for physiotherapy sessions sustains predictable capital expenditure cycles across clinic networks. The Federal Institute for Drugs and Medical Devices enforces MDR conformity assessments that determine CE-marking eligibility for electrotherapy systems. The Stuttgart-Karlsruhe manufacturing belt anchors precision transducer production for therapeutic ultrasound equipment.
Japan
Aging demographics and rehabilitation infrastructure expansion sustain demand for electrotherapy and continuous passive motion devices. METI oversees medical device quality management system certifications that govern market entry for foreign manufacturers. The Osaka-Kobe industrial zone concentrates rehabilitation equipment distributors serving domestic hospital procurement channels.
India
Outpatient rehabilitation infrastructure expansion under national health mission programs creates whitespace for affordable electrotherapy platforms. The Central Drugs Standard Control Organization regulates medical device imports and local manufacturing compliance for physiotherapy equipment. The Mumbai-Pune corridor attracts contract manufacturing investments targeting price-sensitive clinic segments.
United Kingdom
Practice consolidation among independent physiotherapy practices elevates purchasing sophistication and subscription-based equipment access models. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit for electrotherapy and laser therapy systems. The Greater London area concentrates private clinic chains standardizing equipment procurement across regional footprints.
Physiotherapy Devices Market Competitive Environment
Top-tier vendors anchor premium positioning through engineering heritage and regulatory mastery, while mid-scale specialists compete on distribution density and bundled service offerings. The vendor base organizes around three strategic archetypes: German-engineered precision manufacturers, North American distribution-heavy integrators, and Swiss-Austrian shockwave therapy specialists. Competitive moves concentrate on software-enabled subscription transitions and EHR interoperability certifications that secure hospital procurement contracts.
Within the German-engineered tier, Zimmer MedizinSysteme GmbH and BTL Industries exemplify premium positioning sustained through MDR compliance depth and hospital procurement channel relationships. Dynatronics Corporation represents the North American integrated platform approach, anchoring presence in physical therapy practices through combined electrotherapy-ultrasound systems. Performance Health occupies a position defined by dense distribution networks supplying clinics with bundled exercise equipment and consumable replenishment programs.
| Leading Market Players |
|---|
| BTL Industries |
| Enovis Corporation |
| Dynatronics Corporation |
| Enraf-Nonius B.V. |
| EMS Physio Ltd. |
| Zimmer MedizinSysteme GmbH |
| Performance Health |
| Storz Medical AG |
| Zynex, Inc. |
| Others |
Value Chain & Pricing Dynamics
Software-defined treatment protocols are compressing hardware replacement cycles while simultaneously fragmenting supplier power across firmware developers and cloud infrastructure providers. This technological pivot elevates recurring subscription revenue for vendors but concentrates cost pressure on legacy electrotherapy manufacturers dependent on transactional equipment sales.
Pricing Analysis
Margin tightening in the premium tier reflects MDR compliance investment burdens and extended CE-marking timelines that German manufacturers must absorb. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified European systems from FDA-cleared North American platforms and price-optimized Asian imports. Subscription bundling of software updates and remote monitoring is displacing outright purchase models among UK clinic chains, compressing upfront revenue recognition. Independent physiotherapy practices exhibit highest price sensitivity, while hospital procurement committees prioritize interoperability certifications over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's national health mission programs are reshaping sourcing patterns for affordable electrotherapy platforms targeting rural clinic deployment. Manufacturing concentration rests on Germany for precision transducer engineering, China for piezoelectric ceramic substrates, and the United States for FDA-regulated final assembly. Critical dependencies include rare-earth elements for laser diodes, medical-grade aluminum for device housings, and specialized polymers for electrode construction. Single-source vulnerability concentrates in East Asian ceramic suppliers controlling therapeutic ultrasound transducer inputs. Distribution runs through hospital procurement channels, GPO contracts, and direct-to-clinic field sales organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation creates a cost-of-compliance moat that favors incumbents with established notified body relationships and systematic post-market surveillance infrastructure.
For Market Incumbents: Deploy software subscription transitions to defend against hardware commoditization pressure from Asian contract manufacturers. Deepen MDR technical documentation capabilities to accelerate CE-marking timelines relative to smaller competitors. Consolidate field service networks to address specialized technician scarcity constraining integrated platform support scalability. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian outpatient rehabilitation infrastructure presents whitespace for affordable electrotherapy platforms. Target secondary cities under national health mission expansion where statutory procurement frameworks are standardizing equipment specifications. Pursue telehealth-integrated rental models to bypass entrenched distributor relationships in mature markets. For Investors and Strategic Acquirers: Re-rating potential sits with software-enabled platform vendors given remote therapeutic monitoring integration tailwinds and recurring revenue visibility. Acquisition focus should center on European MDR-compliant manufacturers with hospital procurement channel depth and algorithmic treatment personalization capabilities. Monitor FDA 510(k) clearance velocity for novel therapeutic indications as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates CE-marking timelines for electrotherapy systems targeting German statutory reimbursement eligibility. |
| Software Companion Development | Enables remote therapeutic monitoring integrations that validate prescription-grade devices for home care deployment. |
| Hospital System Partnership | Secures EHR-integrated platform procurement contracts under US value-based care interoperability requirements. |
| Reimbursement Strategy | Aligns device specifications with Germany's statutory health insurance physiotherapy session reimbursement frameworks. |
| Geographic Manufacturing Footprint | Positions assembly capacity within India's domestic-content preference zones for national health mission tenders. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, MDR conformity assessment durations, and statutory reimbursement rate adjustments anchored the trend analysis, supplemented by interviews with physiotherapy device product managers, hospital biomedical engineers, clinic procurement directors, and notified body technical assessors. Secondary validation drew from FDA 510(k) database filings, BfArM vigilance reports, German statutory health insurance reimbursement schedules, and hospital GPO contract disclosures. Bottom-up equipment shipment estimates triangulated against top-down healthcare capital expenditure forecasts.
Segment-weighting across product type, application, end user, and technology dimensions informed volume and value projections across the analysis window. Electrotherapy device installed base data, ultrasound therapy frequency specification trends, and laser therapy clinical validation investment patterns served as industry-specific forecast inputs. CAGRs were derived from equipment replacement cycle compression rates and subscription revenue transition trajectories.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in private clinic equipment utilization metrics introduce uncertainty bands around home care channel expansion assumptions. Forecasts reflect documented assumptions regarding reimbursement stability and software adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
3D Medical Implant Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market