
 Orthopedic Fracture Repairing Implants for Osteoporosis Market | 2026-2036
Orthopedic Fracture Repairing Implants for Osteoporosis Market Size, Share, and Industry Trends Forecast 2026-2036
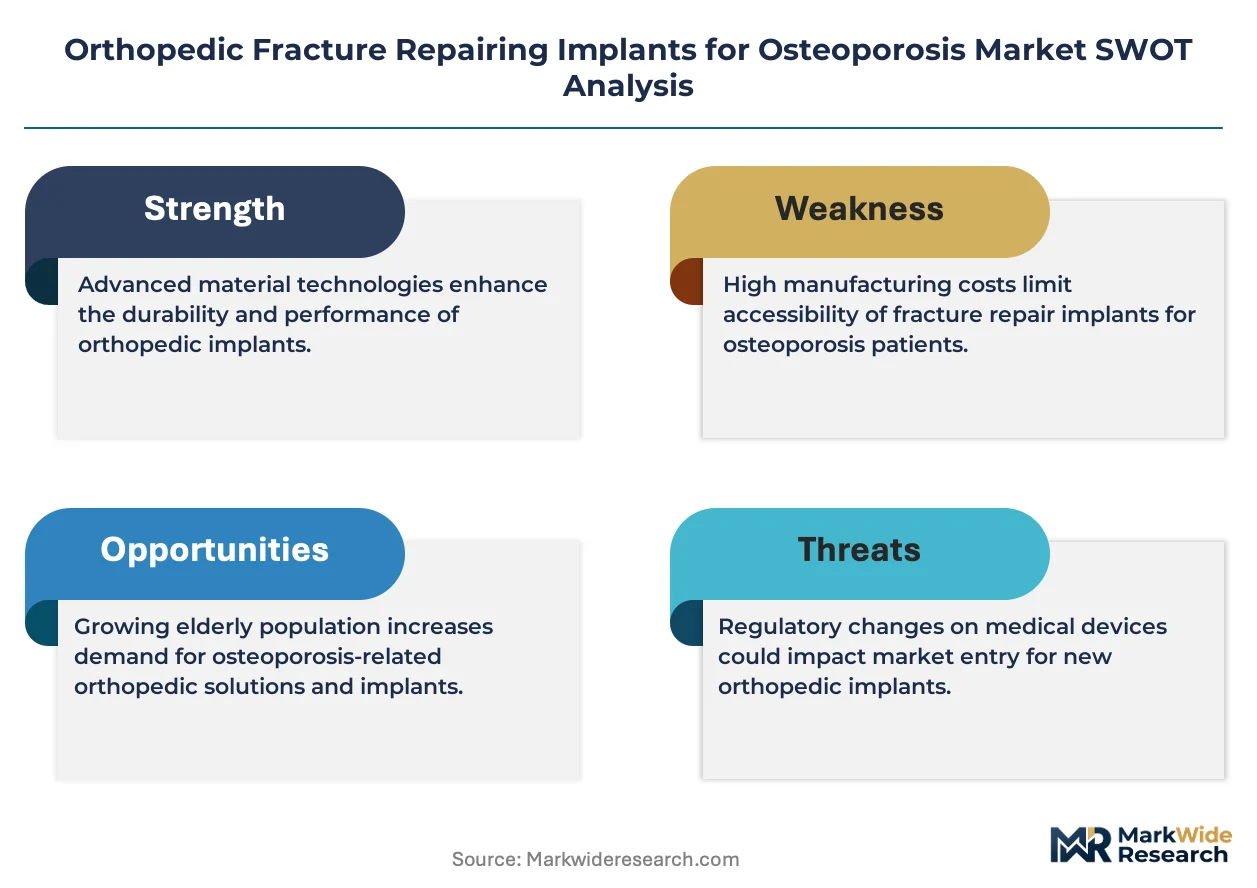
Orthopedic Fracture Repairing Implants for Osteoporosis Market Outlook
The hospital end-user segment is shifting toward integrated fracture care pathways that combine surgical implantation with post-operative bone health management. Stryker Corporation leverages its trauma platform breadth to sustain service contracts across major health systems. Zimmer Biomet Holdings anchors its position through specialized plating systems designed for compromised bone density. Johnson & Johnson competes via DePuy Synthes with differentiated cement augmentation techniques for screw fixation in osteoporotic bone.
Orthopedic fracture repairing implants for osteoporosis are load-bearing devices manufactured from titanium alloys, stainless steel, or bioresorbable polymers with thread designs optimized for low-density cancellous bone. These implants mechanically stabilize fragility fractures while distributing stress across structurally compromised skeletal sites to enable biological union. Plates and screws command the largest revenue share due to their versatility across anatomical sites, while biodegradable fixation represents the fastest-expanding technology segment as surgeons seek to eliminate hardware removal procedures in elderly patients. Internal fixation dominates procedural volume, though external fixation retains importance in polytrauma cases where soft tissue compromise precludes immediate definitive surgery.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments govern market entry, with both agencies intensifying scrutiny of biomechanical performance data in osteoporotic bone models. ISO 5834 standards for implant materials and ASTM F1264 testing protocols for intramedullary devices establish baseline safety benchmarks that manufacturers must satisfy for commercial access. Stakeholders should monitor evolving CMS and national health technology assessment body positioning on bone-acting pharmacotherapy co-reimbursement, as integrated medical-surgical coverage models will reshape implant procurement economics and procedure site selection.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously demanding integrated bone health management protocols alongside implant supply, forcing manufacturers to reconfigure service offerings around longitudinal patient outcomes rather than discrete device sales.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for biomechanically validated osteoporotic bone models are compressing product development cycles for trauma device manufacturers.
- Germany's Diagnosis-Related Group reimbursement:Bundled payment structures for fragility fracture intervention incentivize health systems to standardize on high-performance plating systems.
- Titanium foam surface modifications:Advanced porous coatings with optimized elastic modulus matching are expanding indications for screw fixation in severely compromised cancellous bone.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese smelter dominance creates raw material price volatility that propagates through implant manufacturing cost structures.
- EMA MDR clinical evidence requirements:Expanded post-market surveillance obligations for bioresorbable polymers extend commercialization timelines by 18-24 months.
- Pharmacological substitution threat:Denosumab and romosozumab fracture prevention protocols reduce surgical intervention rates in high-risk geriatric cohorts.
Strategic Opportunities
- Japan's super-aged municipalities:Rural prefectures with 35%+ population over 65 present concentrated demand for ambulatory surgical center-based fracture stabilization.
- Point-of-care 3D printing:Hospital-based titanium additive manufacturing enables patient-specific plate contouring for complex pelvic fragility fractures.
- CMS Innovation Center bundled payment pilots:Medicare accountable care organization contracts reward integrated medical-surgical osteoporosis management pathways.
Industry Challenges
- Biomechanical testing capacity:Validated osteoporotic bone surrogate availability constrains preclinical validation throughput for novel thread geometries.
- Legacy ERP integration:Hospital supply chain systems require expensive middleware development to support implant-level utilization tracking for value-based contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Fracture Repairing Implants for Osteoporosis Market |
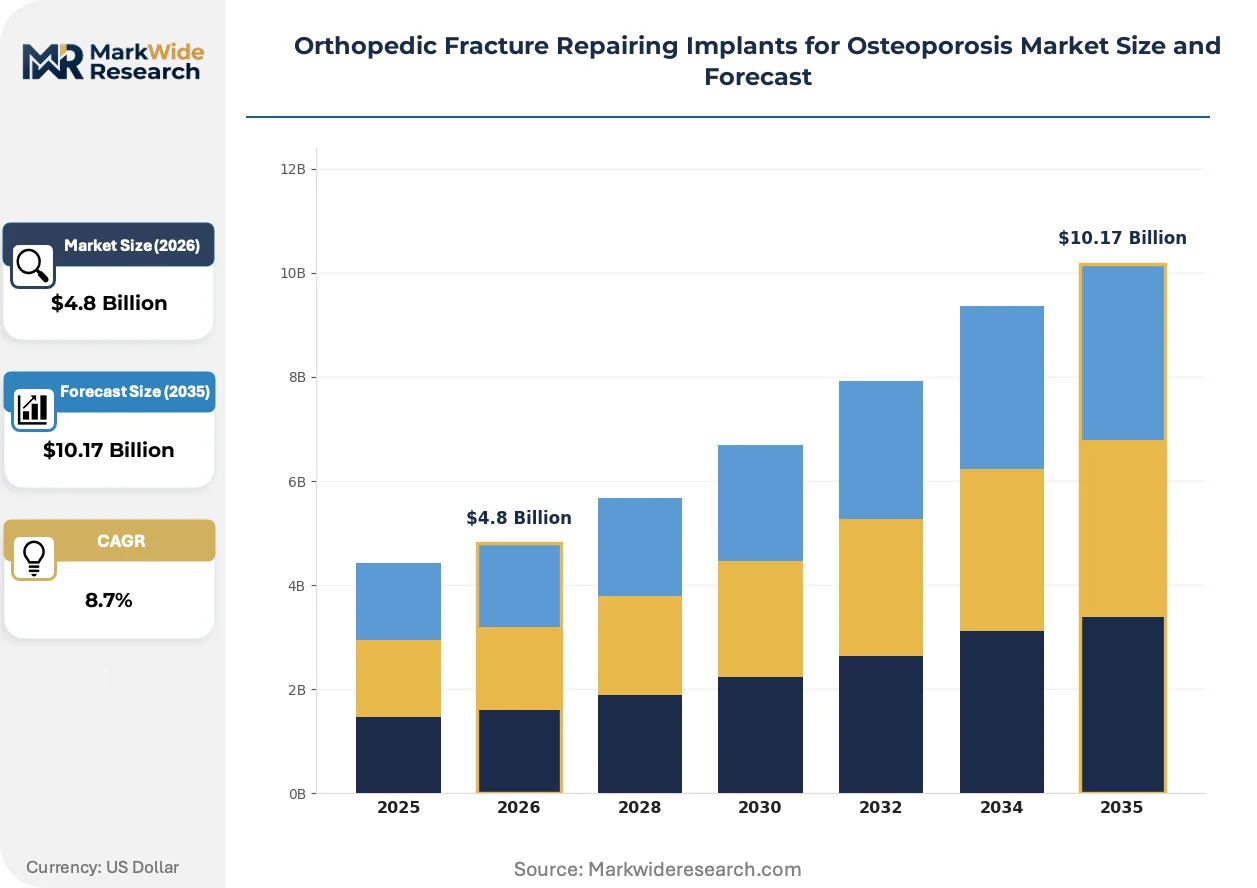
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Pins, Rods Technology: Internal Fixation, External Fixation, Biodegradable, Non-biodegradable End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Care Application: Hip Fractures, Wrist Fractures, Spine Fractures, Ankle Fractures |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Johnson & Johnson, Medtronic Plc, Smith & Nephew, Arthrex, Inc., NuVasive, Globus Medical, Inc., DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Fracture Repairing Implants for Osteoporosis Market Strategic Shifts
Bioresorbable magnesium alloys are disrupting traditional titanium fixation paradigms while regulatory agencies recalibrate evidentiary standards for patient-matched devices, and procurement organizations restructure supplier relationships around total episode economics.
Magnesium-calcium alloy intramedullary nails are absorbing mechanical loading during the critical 12-week fracture healing window before corroding into biocompatible byproducts. Academic medical centers in Germany and Japan are piloting these devices for distal radius fragility fractures in patients over 75. The technology is absorbing revenue from conventional titanium hardware removal procedures while creating new reimbursement negotiation complexity with payers unfamiliar with biodegradable device coding.
EMA Medical Device Regulation Article 10.4 post-market clinical follow-up requirements are mandating systematic registry participation for all osteoporotic fracture implants. Manufacturers must now submit annual safety performance reports to notified bodies, with non-compliance triggering certificate suspension. Small-to-mid cap plating specialists without existing European clinical infrastructure face disproportionate compliance cost burdens relative to multinational trauma platform holders.
Ambulatory surgery centers are consolidating orthopedic trauma volume through direct-to-employer contracting for fragility fracture episodes. These facilities bypass traditional hospital purchasing committees and negotiate implant pricing through committed volume guarantees with single-source vendors. Texas and Florida health systems exhibit the most advanced center-of-excellence models, where bundled payments cover pre-operative bone density assessment through 90-day post-discharge pharmacotherapy initiation.
Orthopedic Fracture Repairing Implants for Osteoporosis Market Segmentation
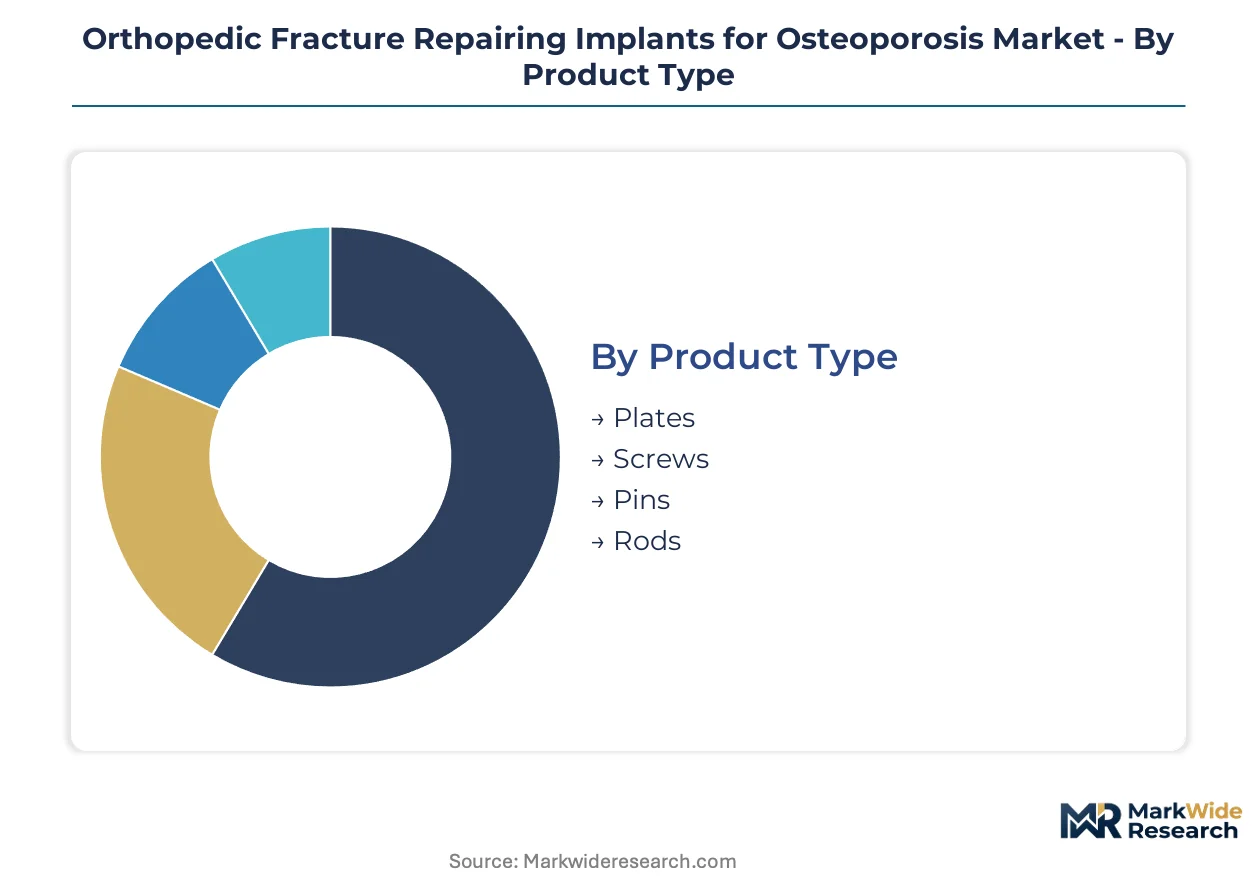
Segmentation in the orthopedic fracture repairing implants for osteoporosis market reveals distinct regulatory pathways, procurement economics, and clinical utility patterns across product configurations. Each dimension carries specific FDA 510(k) and EMA MDR certification burdens that shape manufacturer portfolio priorities and hospital purchasing decisions.
Product Type:
FDA 510(k) clearances for plates and screws require biomechanical testing in osteoporotic bone surrogates, while pins and rods face less stringent premarket validation under simplified substantial equivalence pathways.
- Plates:Anatomically contoured titanium or stainless steel constructs with locking screw interfaces distribute mechanical load across compromised cortical bone. Demand concentrates in German trauma centers where Diagnosis-Related Group reimbursement incentivizes definitive surgical stabilization over conservative management in hip fracture patients.
- Screws:Cancellous-optimized thread geometries with dual-lead designs enhance purchase in low-density bone. Japanese hospitals drive procurement volume for proximal humerus and distal radius applications where early mobilization protocols require robust fixation.
- Pins:Kirschner wire constructs provide provisional stabilization in wrist fractures and pediatric applications. United States ambulatory surgery centers favor disposable sterile packaging to reduce reprocessing costs.
- Rods:Intramedullary nails with proximal and distal interlocking capabilities dominate femoral shaft fracture management. EMA MDR Article 10.4 post-market surveillance obligations extend commercialization timelines for novel surface-modified variants.
Plates sit at the top of the volume ranking, with biodegradable fixation alternatives climbing the fastest across European markets.
Technology:
Cost tiering separates premium bioresorbable magnesium alloys from standard titanium internal fixation and economy-grade external fixation systems, with reimbursement coding complexity varying sharply across modalities.
- Internal Fixation:Plates, screws, and intramedullary devices provide rigid mechanical stabilization through direct bone-implant interface. United States hospitals account for dominant procedural volume under Medicare Severity Diagnosis-Related Group reimbursement structures.
- External Fixation:Pin-based frames with carbon fiber connecting rods enable provisional stabilization in polytrauma with soft tissue compromise. German level-one trauma centers maintain dedicated inventory for open fracture protocols.
- Biodegradable:Magnesium-calcium alloys absorb mechanical loading during the 12-week healing window before resorbing into biocompatible byproducts. Japanese academic medical centers pilot distal radius applications in patients over 75, though unfamiliar payer coding creates reimbursement friction.
- Non-biodegradable:Conventional titanium and stainless steel constructs require secondary hardware removal procedures in symptomatic patients. EMA clinical evidence requirements for permanent implants focus on long-term biocompatibility rather than resorption kinetics.
Internal fixation captures the dominant revenue share, with biodegradable systems gaining share fastest among elderly cohorts seeking to avoid reoperation.
End User:
Customer type determines procurement channel complexity, with integrated health systems demanding longitudinal outcome tracking that standalone clinics cannot support.
- Hospitals:Comprehensive trauma centers with 24-hour orthopedic coverage perform complex hip and spine fracture stabilization. United States health systems increasingly bundle implant procurement with post-discharge bone health management under CMS Innovation Center pilot contracts.
- Orthopedic Clinics:Specialized ambulatory facilities concentrate elective wrist and ankle fracture fixation. Texas and Florida direct-to-employer contracting models bypass traditional hospital purchasing committees through committed volume guarantees.
- Rehabilitation Centers:Post-acute facilities manage external fixation frame adjustments and pin site care. German municipal networks integrate these services into fragility fracture pathway standardization.
- Home Care:Remote monitoring and pharmacotherapy adherence programs extend osteoporosis management beyond the surgical episode. Japanese super-aged municipalities with 35% plus population over 65 pilot decentralized fracture prevention protocols.
Hospitals dominate absolute procedure volume, with orthopedic clinics expanding their surgical footprint fastest through ambulatory site-of-service migration.
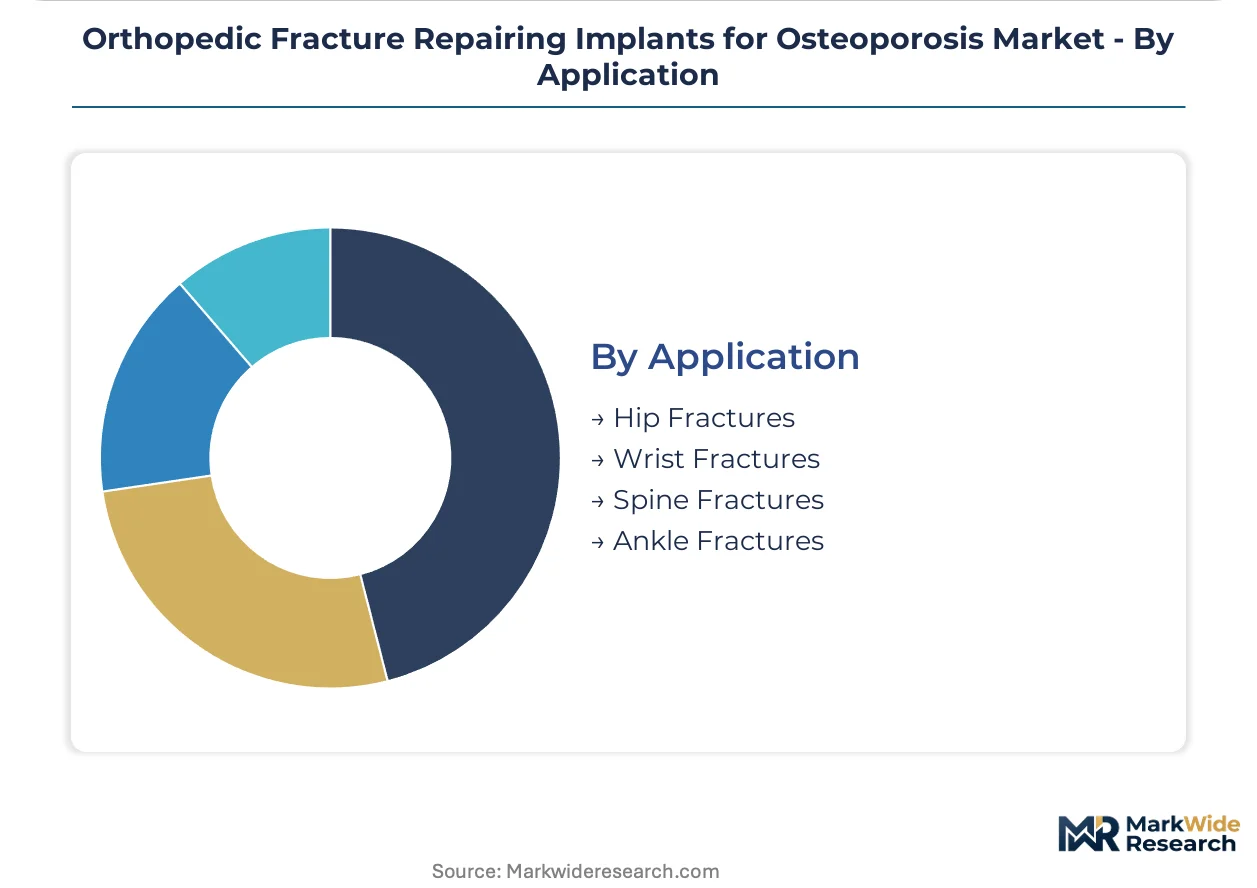
Application:
Anatomical site dictates implant specification requirements, with load-bearing joints demanding higher-grade materials and more intensive regulatory scrutiny than non-weight-bearing applications.
- Hip Fractures:Proximal femoral nails and sliding hip screws stabilize intertrochanteric and femoral neck fractures in geriatric patients. German DRG reimbursement rates for these procedures exceed those for other anatomical sites, concentrating manufacturer R&D investment.
- Wrist Fractures:Volar locking plates and biodegradable magnesium nails address distal radius fragility fractures. Japanese demand for early functional recovery drives adoption of motion-preserving fixation in patients over 75.
- Spine Fractures:Pedicle screw-rod constructs with cement augmentation address osteoporotic vertebral compression and burst patterns. EMA MDR requirements for spinal implants mandate extensive biomechanical testing in osteoporotic bone models.
- Ankle Fractures:Fibular plating and syndesmotic fixation address fragility patterns in low-energy trauma. United States ambulatory surgery centers capture growing volume through same-day discharge protocols.
Hip fractures command the highest implant expenditure per procedure, with wrist fracture fixation expanding most quickly as magnesium alloy technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EMA MDR compliance costs in Europe push production toward jurisdictions with streamlined medical device pathways. Manufacturers now optimize location decisions around notified body capacity and clinical trial infrastructure rather than labor costs alone.
United States
Medicare Severity Diagnosis-Related Group reimbursement structures drive hospital procurement of advanced plating systems for hip fracture stabilization. FDA 510(k) pathway streamlining accelerates clearance timelines for biomechanically validated osteoporotic bone models. Texas and Florida health systems lead ambulatory surgery center migration through direct-to-employer bundled payment contracts.
Germany
Diagnosis-Related Group reimbursement rates for fragility fracture intervention exceed those elsewhere in Europe, concentrating manufacturer R&D investment. EMA MDR Article 10.4 post-market surveillance obligations extend commercialization timelines for novel implant variants. Bavarian trauma centers pilot magnesium-calcium alloy intramedullary nails for distal radius applications.
Japan
Super-aged municipalities with 35% plus population over 65 present concentrated demand for ambulatory surgical center-based fracture stabilization. PMDA regulatory frameworks accommodate expedited review for devices addressing geriatric-specific indications. Kansai region academic medical centers lead biodegradable fixation pilot programs for patients over 75.
United Kingdom
National Institute for Health and Care Excellence technology appraisals influence procurement decisions for osteoporotic fracture implants across National Health Service trusts. MHRA post-Brexit regulatory autonomy enables divergence from EMA MDR timelines where justified by clinical evidence. London trauma networks integrate bone health management into fragility fracture pathways.
Switzerland
Swissmedic regulatory efficiency attracts manufacturers seeking parallel European market access with reduced notified body queue times. Premium reimbursement rates for innovative implant technologies support adoption of advanced surface-modified devices. Basel-Zurich corridor hosts specialized biomechanical testing facilities serving preclinical validation requirements.
Orthopedic Fracture Repairing Implants for Osteoporosis Market Competitive Environment
Portfolio diversification dominates the current landscape as trauma platform holders expand service contracts beyond discrete device sales into longitudinal bone health management. The vendor base concentrates around multinational conglomerates with integrated trauma portfolios and specialized plating specialists with anatomical focus. Three archetypes prevail: full-platform trauma suppliers, orthopedic-focused device manufacturers, and spine-specialized implant developers. M&A activity and strategic partnerships represent the primary competitive vectors as scale requirements intensify.
Among full-platform trauma suppliers, Stryker Corporation and Zimmer Biomet Holdings exemplify the integrated service model that hospital procurement consolidation now demands. Johnson & Johnson occupies a position within the orthopedic-focused tier through its DePuy Synthes franchise, representing the archetype of diversified health technology conglomerates competing via differentiated augmentation techniques. Medtronic Plc anchors the spine-specialized segment, reflecting how vertebral compression fracture applications require distinct biomechanical expertise from appendicular trauma fixation.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Johnson & Johnson |
| Medtronic Plc |
| Smith & Nephew |
| Arthrex, Inc. |
| NuVasive |
| Globus Medical, Inc. |
| DePuy Synthes |
| Others |
Value Chain & Pricing Dynamics
Biomedical metallurgist clusters in the Basel-Zurich corridor anchor European implant manufacturing, with labor-cost differentials between Swiss precision engineering centers and Chinese titanium processing hubs driving three-tier pricing spreads across premium surface-modified devices, standard locking-plate systems, and economy-grade external fixation frames.
Pricing Analysis
Distributor margins of 15-25 percent on trauma implants compress as hospital procurement consolidation accelerates direct manufacturer contracting. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance tier and ISO 5834 certification grade, with German Diagnosis-Related Group reimbursement rates supporting premium-tier absorption while United States ambulatory surgery centers exhibit acute price sensitivity on commoditized Kirschner wire constructs. Cost compression in standard plating systems intensifies because Russian and Chinese titanium sponge supply concentration propagates raw material volatility through manufacturing cost structures.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume health system demand while specialized orthopedic distributors serve standalone trauma centers with inventory-managed consignment models. Titanium sponge smelting concentrates in Russia and China, with secondary refining and alloy production anchored in Japan and Germany. Raw material dependencies span titanium sponge, medical-grade stainless steel, and bioresorbable magnesium-calcium feedstocks. Single-source vulnerability in titanium sponge supply creates exposure to export restriction cascades. Distribution runs through hospital purchasing committees and ambulatory surgery center direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing footprint arbitrage between EMA MDR compliance costs in Europe and FDA 510(k) streamlining in the United States creates margin expansion opportunities for dual-registered device portfolios.
For Market Incumbents: Deepen backward integration into titanium alloy production to offset Russian and Chinese smelter price volatility, while expanding service contracts beyond device supply into longitudinal bone health management protocols that hospital procurement consolidation now demands. Cement augmentation technique R&D investment defends positioning against biodegradable magnesium alloy substitution threats. For New Entrants and Emerging Players: Japanese super-aged municipalities with 35 percent plus population over 65 represent an underserved buyer archetype where ambulatory surgical center-based fracture stabilization lacks established vendor relationships. Point-of-care 3D printing partnerships with rural German trauma networks offer white-space penetration for patient-specific plate contouring capabilities. Reimbursement strategy development must precede commercial launch given unfamiliar payer coding for biodegradable devices. For Investors and Strategic Acquirers: Full-platform trauma suppliers are the most active acquirer in this space, consolidating specialized plating specialists to satisfy hospital demands for integrated service breadth. Long-term viability hinges on EMA MDR compliance infrastructure and post-market clinical follow-up registry participation capabilities. Watch CMS Innovation Center bundled payment pilot expansion as the inflection signal for integrated medical-surgical procurement model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker Corporation leverages trauma platform breadth to sustain service contracts across major United States health systems. |
| CE Marking Pathway | EMA MDR Article 10.4 post-market surveillance obligations extend commercialization timelines for novel bioresorbable polymer variants. |
| Reimbursement Strategy | Germany's Diagnosis-Related Group bundled payment structures incentivize health systems to standardize on high-performance plating systems. |
| Software Companion Development | Hospital supply chain systems require middleware development to support implant-level utilization tracking for value-based contracts. |
| FDA Submission | Accelerated 510(k) clearance timelines for biomechanically validated osteoporotic bone models compress product development cycles. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down titanium alloy production tracking forms the analytical core. Primary interviews with orthopedic trauma surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Triangulation between demand-side utilization patterns and supply-side manufacturing capacity ensures cross-verified volume estimation.
Input-output matrices map implant unit demand across product type, technology modality, end-user facility category, and anatomical application through the projection horizon. Segmentation dimensions modeled include internal versus external versus biodegradable fixation, hospital versus ambulatory surgery center site of service, and hip versus wrist versus spine versus ankle anatomical targets. CAGRs derive from surgical procedure volume trajectories, aging demographic projections, and reimbursement policy elasticity assumptions. Titanium sponge price volatility and EMA MDR compliance cost inflation represent key forecast sensitivity inputs.
Underlying measurement precision varies by segment; hip fracture implants carry tighter precision than biodegradable fixation given established procedural coding and reimbursement stability. Forecasts reflect documented assumptions regarding regulatory pathway timelines, pharmacological substitution rates, and hospital consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Computer-Assisted Orthopedic Surgery Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Shoulder Arthroplasty Market