
 Veterinary Orthopedic Injectable Drug Market | 2026-2036
Veterinary Orthopedic Injectable Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Orthopedic Injectable Drug Market Analytics
North American manufacturing capacity for sterile veterinary injectables is fragmenting as compounders and specialty CMOs enter the orthopedic space. Zoetis Inc. leverages its biologics infrastructure to dominate the platelet-rich plasma segment. Dechra Pharmaceuticals PLC anchors European distribution through its veterinary-specialist sales force. Virbac S.A. competes on hyaluronic acid formulations with region-specific regulatory dossiers.
Veterinary orthopedic injectable drugs comprise sterile parenteral formulations—NSAIDs, corticosteroids, hyaluronic acid, and platelet-rich plasma—delivered intra-articularly or peri-operatively to manage inflammation, pain, and cartilage degradation in companion animals. These products require endotoxin-controlled manufacturing, validated sterility assurance levels, and species-specific pharmacokinetic profiling to ensure therapeutic efficacy and safety across canine, feline, and equine patients. Liquid formulations lead volume due to ease of administration in clinical settings, while lyophilized powder formats command margin premiums for biologic stability. Platelet-rich plasma represents the fastest-growing category as autologous therapy protocols expand in specialty referral hospitals. Pain management applications sustain the largest revenue pool, though joint health maintenance shows accelerating growth as preventive care protocols extend treatment windows.
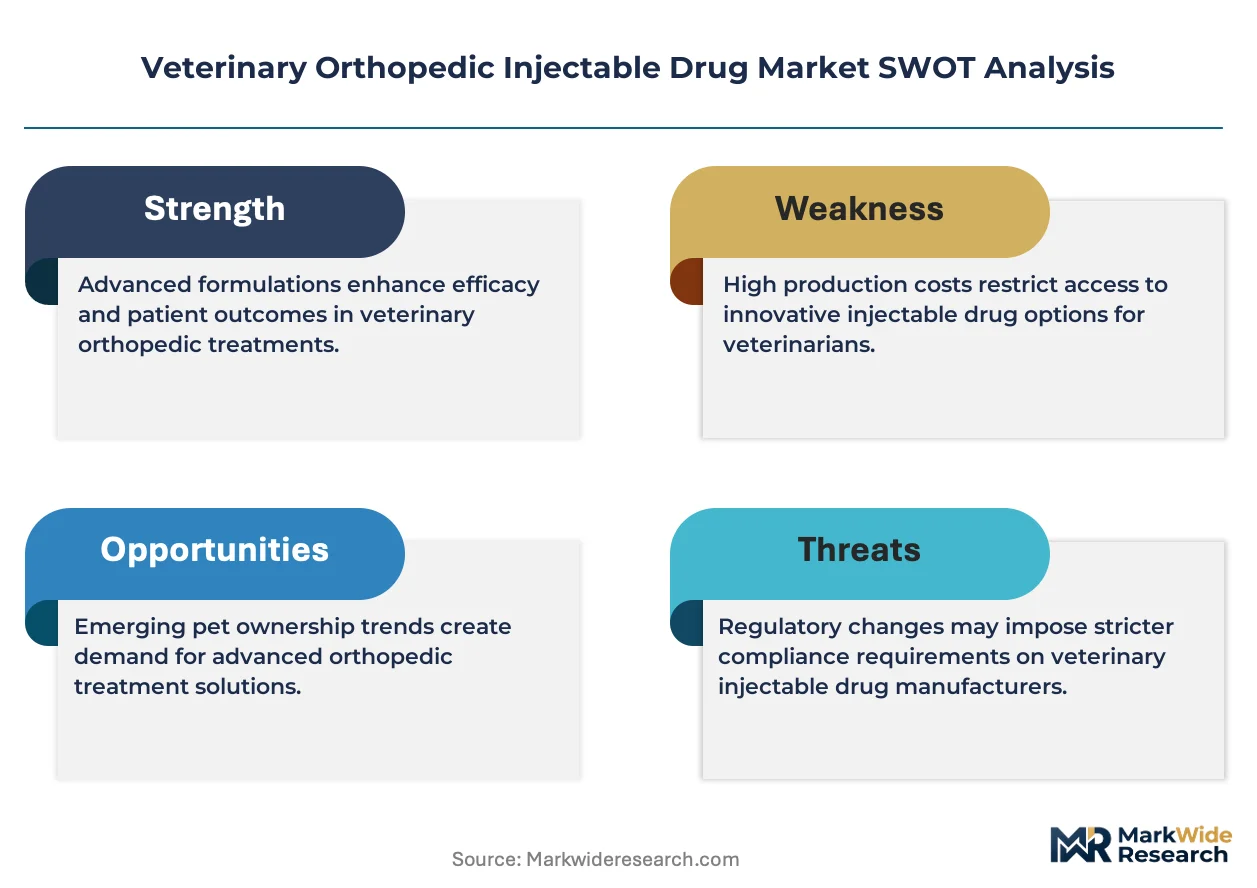
The FDA Center for Veterinary Medicine mandates New Animal Drug Application pathways for novel orthopedic injectables, while the USDA Animal and Plant Health Inspection Service oversees biologic products including autologous cell therapies. The EU Veterinary Medicines Regulation harmonizes marketing authorization requirements across member states, affecting cross-border product access for hyaluronic acid and PRP kits. Stakeholders must monitor evolving biologic classification criteria and species expansion labels, as regulatory determinations on cell-therapy versus drug status will reshape competitive entry barriers and reimbursement frameworks.
Market Dynamics
Specialty veterinary clinics are consolidating procurement power through group purchasing organizations, compressing margins for orthopedic injectable manufacturers while simultaneously demanding validated sterility data and extended stability documentation that smaller compounders cannot provide.
Growth Catalysts
- Pet Insurance Penetration:United States pet insurance carriers now cover intra-articular therapies under wellness riders, removing cost barriers for hyaluronic acid and platelet-rich plasma protocols in companion animal orthopedics.
- FDA Center for Veterinary Medicine Streamlining:The FDA CVM's expanded conditional approval pathways for minor-use minor-species drugs accelerate commercialization timelines for novel osteoarthritis therapies targeting canine and feline patients.
- Autologous Processing Technology:Point-of-care centrifugation systems enable same-visit platelet-rich plasma preparation, embedding orthopedic biologics into routine specialty practice workflows.
Market Restraints
- API Supply Concentration:Pharmaceutical-grade hyaluronic acid raw material production clusters in Chinese fermentation facilities, exposing formulation partners to geopolitical trade friction and import inspection delays.
- Biologic Classification Uncertainty:The USDA APHIS and FDA CVM maintain overlapping jurisdiction for cell-derived orthopedic therapies, creating dual-track submission requirements that extend pre-market timelines by 18-24 months.
- Compounding Pharmacy Substitution:503B outsourcing facilities produce unapproved intra-articular formulations at 40-60% below innovator pricing, capturing price-sensitive general practice volume.
Strategic Opportunities
- Equine Sports Medicine Expansion:Racing and performance horse markets in Kentucky, Florida, and California present underpenetrated demand for regenerative orthopedic injectables with documented return-to-competition outcomes.
- Preventive Protocol Adoption:Early-intervention joint health programs in young large-breed dogs are extending treatment windows before radiographic osteoarthritis manifests, creating recurring revenue streams.
- Veterinary Telemedicine Integration:Remote consultation platforms are routing post-injection monitoring to digital channels, reducing follow-up friction and expanding addressable geography beyond referral hospital catchment areas.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:Aseptic processing specialists with veterinary parenteral experience command premium compensation in human pharmaceutical markets, constraining CMO capacity expansion.
- Endotoxin Validation Complexity:Species-specific pyrogen testing protocols for canine, feline, and equine matrices lack harmonized standards, forcing redundant analytical method development across product registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Orthopedic Injectable Drug Market |
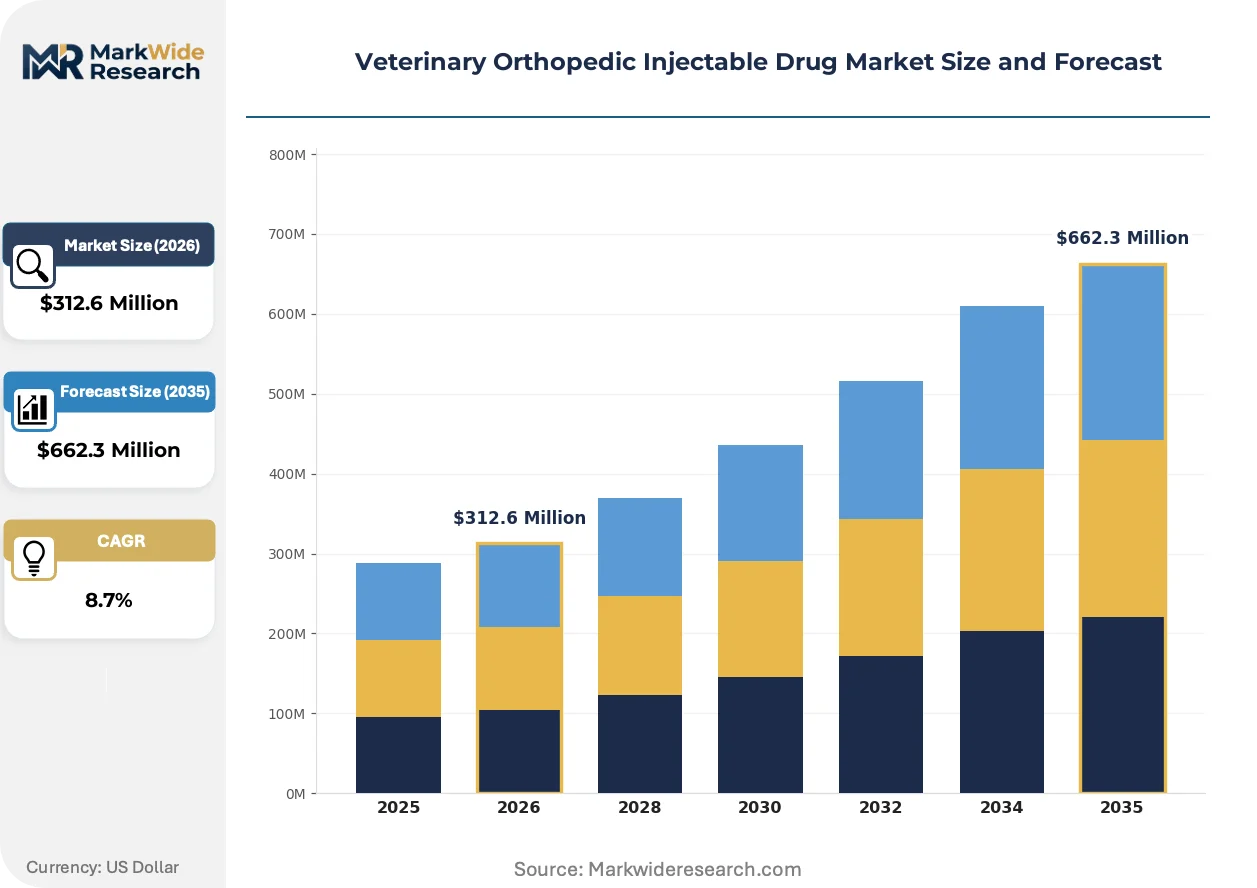
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Corticosteroids, Hyaluronic Acid, Platelet-Rich Plasma End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinarians Application: Post-Operative Care, Pain Management, Injury Recovery, Joint Health Formulation: Liquid, Lyophilized Powder, Emulsion, Suspension |
| Companies Covered | Merck Animal Health, Virbac S.A., Zoetis Inc., Dechra Pharmaceuticals PLC, Vetoquinol S.A., Elanco Animal Health, Ceva Santé Animale, Norbrook Laboratories Ltd., Boehringer Ingelheim Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Orthopedic Injectable Drug Market Evolving Landscape
Orthopedic injectable development is pivoting from synthetic small molecules toward autologous and allogeneic biologics, reshaping manufacturing infrastructure requirements and regulatory submission strategies across the veterinary pharmaceutical sector.
Lyophilized platelet-rich plasma formulations are collapsing cold-chain dependency for biologic therapies. Specialty referral hospitals in the United States and Western Europe are adopting room-temperature stable kits to eliminate ultralow freezer capital expenditure. This technology is collapsing the infrastructure barrier that previously restricted biologic therapy to academic and corporate flagship sites.
The EU Veterinary Medicines Regulation's environmental risk assessment mandates now require biodegradation data for intra-articular excipients. Formulators are reformulating hyaluronic acid carrier solutions to exclude persistent organic pollutants. Hyaluronic acid suppliers with ISO 14001-certified fermentation facilities are capturing preferred vendor status in European marketing authorization dossiers.
Pet owners are researching orthopedic therapy options through veterinary telehealth platforms before scheduling specialty consultations. This self-directed education is compressing the traditional referral funnel, with clients arriving at clinics already requesting specific injectable modalities by name. The phenomenon is most pronounced in United States urban markets with high digital native demographics and established pet insurance coverage.
Veterinary Orthopedic Injectable Drug Market Segmentation
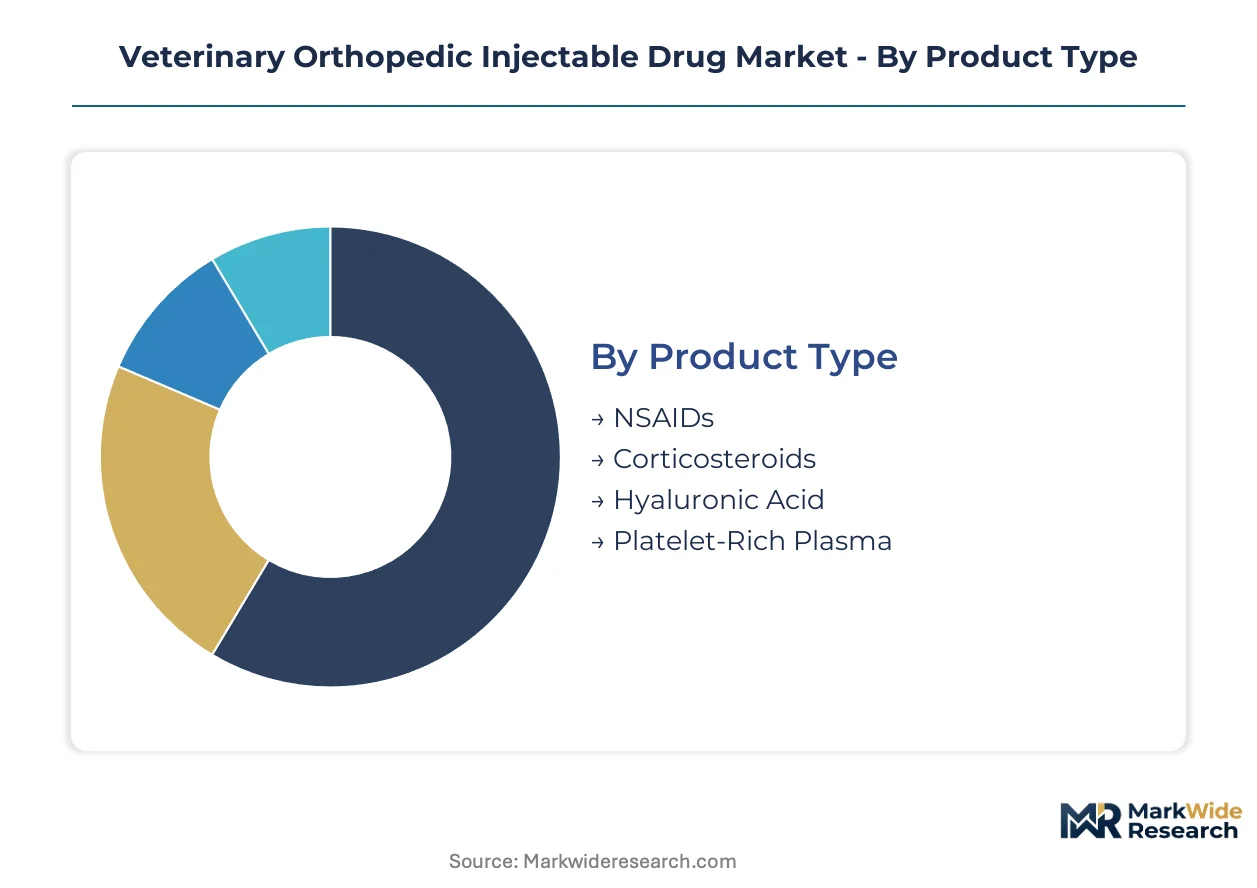
Segmentation in veterinary orthopedic injectables reveals how formulation technology, clinical setting, and therapeutic objective intersect to determine procurement patterns. Each dimension carries distinct regulatory, pricing, and supply chain implications that shape manufacturer strategy.
Product Type:
Cost tier determines reimbursement positioning and manufacturing complexity across the therapeutic spectrum.
- NSAIDs:Synthetic small-molecule formulations dominate volume in general practice settings. Procurement concentrates in United States independent clinics where pet insurance wellness riders rarely cover biologic alternatives, constraining price elasticity.
- Hyaluronic Acid:Fermentation-derived polysaccharide requiring pharmaceutical-grade endotoxin control. Demand clusters in German and French specialty referral hospitals where EMA-authorized viscosupplementation protocols command premium positioning.
- Corticosteroids:Long-acting intra-articular suspensions with established veterinary formularies.
- Platelet-Rich Plasma:Autologous biologic gaining share fastest in equine sports medicine.
NSAIDs hold installed capacity. Platelet-Rich Plasma is rotating up the share rankings.
End User:
Customer type dictates sterility assurance requirements, cold-chain infrastructure, and purchasing consolidation leverage.
- Veterinary Clinics:Independent and corporate general practices represent the volume anchor. United States group purchasing organizations are consolidating procurement power, compressing margins while demanding extended stability documentation that excludes smaller compounders.
- Animal Hospitals:Multi-specialty referral centers with in-house anesthesia and surgical suites. California and Texas academic veterinary medical centers anchor biologic therapy adoption, driven by residency training programs and documented outcome publication requirements.
- Research Institutions:University veterinary schools and contract research organizations driving pharmacokinetic validation.
- Mobile Veterinarians:Equine and large-animal practitioners requiring field-stable formulations.
Animal Hospitals anchor biologic uptake. Mobile Veterinarians are expanding fastest as telemedicine integration reduces follow-up friction.
Application:
Therapeutic objective shapes dosing frequency, combination therapy protocols, and preventive versus reactive care positioning.
- Pain Management:Acute and chronic analgesia protocols sustain the largest revenue pool. United States specialty clinics in Florida and Colorado are embedding multimodal injectable regimens into total knee replacement workflows, extending peri-operative pharmaceutical spend.
- Joint Health:Preventive maintenance in young large-breed dogs represents the steepest expansion trajectory. Kentucky equine practitioners are pioneering early-intervention protocols that delay radiographic osteoarthritis manifestation.
- Post-Operative Care:Peri-articular and intra-articular administration following orthopedic surgery.
- Injury Recovery:Soft-tissue and ligament rehabilitation protocols.
Pain Management commands current spend. Joint Health is climbing the fastest as preventive protocols extend treatment windows.
Formulation:
Physical state determines stability requirements, cold-chain dependency, and margin structure.
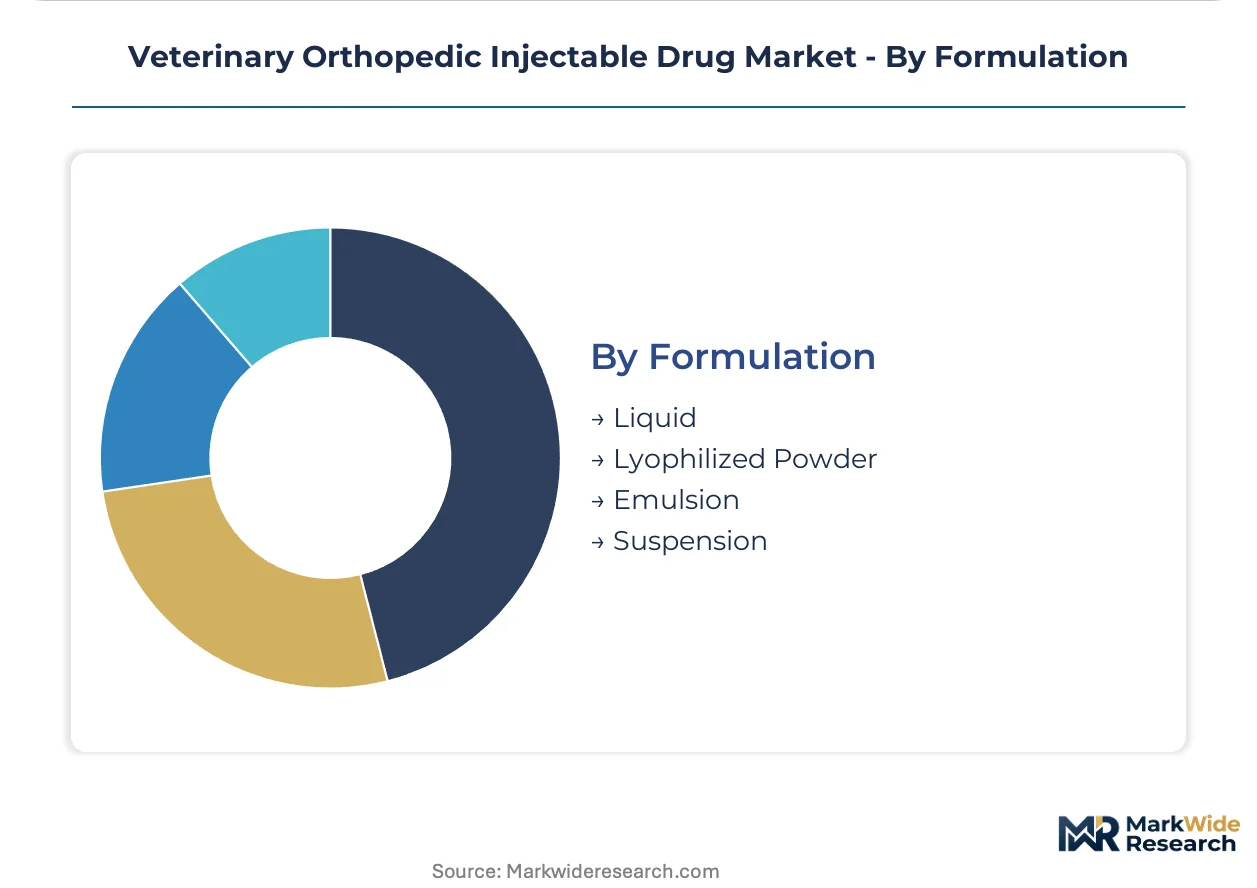
- Liquid:Ready-to-use solutions dominate clinical volume due to administration convenience. United States specialty referral hospitals prioritize liquid NSAIDs and hyaluronic acid for same-visit intra-articular delivery, minimizing preparation time.
- Lyophilized Powder:Freeze-dried biologics command margin premiums for stability. European Union marketing authorization dossiers increasingly require ISO 14001-certified fermentation facilities for hyaluronic acid carrier excipients under environmental risk assessment mandates.
- Emulsion:Lipid-based delivery systems for sustained release.
- Suspension:Particulate formulations for depot effect.
Liquid formulations hold volume leadership. Lyophilized Powder is gaining share fastest as room-temperature stable kits collapse infrastructure barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA Center for Veterinary Medicine anchors regulatory pathways for the United States, while demand clusters concentrate in specialty referral hospitals across multiple developed markets. Pet insurance penetration and referral practice density determine uptake velocity in each geography.
United States
Kentucky, Florida, and California drive equine sports medicine demand for regenerative injectables. The FDA CVM's conditional approval pathways for minor-use minor-species drugs accelerate canine osteoarthritis therapy commercialization. Specialty referral hospitals in Lexington and Ocala anchor biologic therapy adoption through documented return-to-competition outcomes.
Germany
EMA-authorized viscosupplementation protocols command premium positioning in German specialty referral hospitals. The EU Veterinary Medicines Regulation harmonizes marketing authorization requirements, affecting cross-border hyaluronic acid access. Industrial clusters in Baden-Württemberg and Bavaria host fermentation facilities supplying pharmaceutical-grade raw materials.
United Kingdom
Dechra Pharmaceuticals PLC anchors European distribution through veterinary-specialist sales force penetration. The UK Veterinary Medicines Directorate enforces pharmacovigilance standards for intra-articular therapies. Greater London and Southeast England concentrate multi-specialty referral centers adopting preventive joint health protocols.
France
Virbac S.A. competes on hyaluronic acid formulations with region-specific regulatory dossiers across French-speaking markets. ANSM oversight of veterinary biologics intersects with EU environmental risk assessment mandates for intra-articular excipients. The Lyon veterinary school corridor drives pharmacokinetic validation research for species-specific matrices.
Japan
PMDA marketing authorization requirements shape entry timelines for novel orthopedic biologics in companion animal markets. METI industrial policy supports domestic fermentation capacity for pharmaceutical-grade polysaccharides. Tokyo and Osaka metropolitan areas concentrate pet insurance carriers now covering intra-articular therapies under wellness riders.
Veterinary Orthopedic Injectable Drug Market Competitive Landscape
Global animal health conglomerates and regional veterinary specialists split the market between scale-driven biologics infrastructure and localized formulation expertise. The vendor base concentrates around three strategic archetypes: diversified pharmaceutical majors with biologics platforms, mid-cap veterinary specialists with captive distribution, and compounders serving price-sensitive general practice. Consolidation through acquisition of autologous processing technology and backward integration into fermentation capacity represent dominant competitive moves.
Within the diversified pharmaceutical tier, Zoetis Inc. and Merck Animal Health exemplify scale-driven biologics infrastructure deployment. Virbac S.A. occupies a position as a formulation specialist with region-specific regulatory dossier capabilities. These three anchors demonstrate how geographic origin and corporate structure map to competitive positioning in sterile parenteral manufacturing.
| Leading Market Players |
|---|
| Merck Animal Health |
| Virbac S.A. |
| Zoetis Inc. |
| Dechra Pharmaceuticals PLC |
| Vetoquinol S.A. |
| Elanco Animal Health |
| Ceva Santé Animale |
| Norbrook Laboratories Ltd. |
| Boehringer Ingelheim Animal Health |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from pharmaceutical-grade hyaluronic acid fermentation hubs into downstream price tiers, compressing margins for formulation partners while amplifying spreads between GPO-negotiated contract tiers and spot procurement in independent veterinary clinics.
Pricing Analysis
United States intra-articular therapy pricing spans threefold from economy NSAID vials through premium platelet-rich plasma kits, with differentiation anchored in FDA CVM approval status and cold-chain stability documentation. Group purchasing organizations extract 15-25 point concessions from manufacturers by aggregating specialty hospital volume. Cost compression in the standard tier intensifies as 503B compounders capture price-sensitive general practice demand. Independent clinics exhibit highest price sensitivity; multi-specialty referral centers prioritize validated sterility data over unit cost.
Supply Chain Analysis
Export control regimes on bioreactor automation technology limit capacity expansion in emerging manufacturing jurisdictions, concentrating pharmaceutical-grade polysaccharide output in China, Germany, and Japan. Formulation partners draw from fermentation-derived sodium hyaluronate, endotoxin-controlled water-for-injection systems, and species-specific pyrogen testing reagents. Single-source vulnerability clusters in Chinese raw material nodes exposed to customs inspection delays. Distribution runs through veterinary-specialist distributors with cold-chain certification, bypassing general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary orthopedic injectable market sustains defensive moats through regulatory entrenchment: FDA CVM and USDA APHIS dual-track submission requirements create 18-24 month pre-market barriers that compounders cannot replicate, locking in incumbent positioning for validated sterile manufacturers.
For Market Incumbents: Harden biologics infrastructure through backward integration into ISO 14001-certified fermentation capacity, securing preferred vendor status under EU environmental risk assessment mandates. Deepen channel control by acquiring point-of-care centrifugation technology providers, eliminating third-party autologous processing dependencies that threaten margin capture in the platelet-rich plasma segment.
For New Entrants and Emerging Players: Kentucky equine sports medicine corridors present underpenetrated demand for regenerative injectables with documented return-to-competition outcomes. Target mobile veterinarians in Florida and California through field-stable lyophilized kit formulations that collapse cold-chain infrastructure requirements. Pursue telemedicine-integrated distribution partnerships to extend geographic reach beyond traditional referral hospital catchment areas.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors autologous processing platform owners over commodity formulation houses. Five-to-ten year viability rests on cell-therapy versus drug classification clarity from FDA CVM and USDA APHIS. Watch for regulatory determinations on biologic status as the inflection signal: favorable rulings would unlock reimbursement frameworks and reshape competitive entry economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | ISO 14001 certification secures preferred vendor positioning in EU marketing authorization dossiers. |
| Acquisition of Point-of-Care Centrifugation Technology | Same-visit PRP preparation embeds biologics into routine specialty practice workflows. |
| Lyophilized Formulation Development | Room-temperature stability eliminates ultralow freezer capital expenditure barriers in regional clinics. |
| Veterinary Telemedicine Platform Partnership | Remote post-injection monitoring expands addressable geography beyond referral hospital catchment areas. |
| Dual-Track Regulatory Submission Capability | Simultaneous FDA CVM and USDA APHIS navigation collapses pre-market timeline uncertainty for cell-derived therapies. |
Research Methodology
Desk research of FDA CVM approval databases, EMA veterinary marketing authorization registers, and USDA APHIS biologic product listings preceded structured interviews with specialty veterinary clinic procurement directors, sterile manufacturing CMO executives, and animal health regulatory affairs leads. Secondary validation drew from trade customs data on pharmaceutical-grade hyaluronic acid imports, SEC 10-K filings of listed animal health conglomerates, and GPO contract disclosure databases. Bottom-up volume estimates from individual product registrations triangulated against top-down market sizing from veterinary expenditure surveys.
The forecast framework held pet insurance penetration rates and referral practice density distributions within observed trajectories while varying biologic classification scenarios and raw material trade friction assumptions. Segmentation modeling spanned formulation technology, end-user facility type, therapeutic application objective, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns of comparable intra-articular therapies. Industry-specific inputs included species-specific pharmacokinetic validation timelines and endotoxin testing protocol harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by 503B compounders into validated sterile manufacturing would shift outcomes toward faster price erosion in the standard tier. Material shifts in FDA CVM biologic classification determinations or sustained disruption to Chinese fermentation facility output would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Femoral Head Prostheses Market