
 Global Patient Positioning Devices Market | 2026-2036
Global Patient Positioning Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Positioning Devices Market Foresight
The EU Medical Device Regulation is consolidating demand for reusable, sterilizable patient positioning systems across European healthcare networks. Stryker Corporation leverages its integrated surgical technologies portfolio to anchor premium positioning solutions within hospital operating suites. Getinge AB sustains competitive positioning through its infection control expertise that extends into validated sterilization cycles for reusable positioning pads and supports.
Patient positioning devices are mechanical or pressure-distributing systems engineered to immobilize, stabilize, or orient patients during diagnostic, therapeutic, or surgical interventions, typically incorporating radiolucent composites, viscoelastic gels, or vacuum-bead matrices to maintain anatomical alignment under load. Their primary purpose is to prevent nerve compression, pressure injuries, and positioning-related complications while enabling unobstructed access for clinicians and imaging equipment. Vacuum positioning technology leads in radiotherapy applications where reproducible immobilization directly impacts treatment accuracy, while gel positioning dominates surgical suites due to its conformability and thermal stability under prolonged procedures. Foam positioning occupies the economy tier across physical therapy clinics where replacement frequency and capital constraints shape procurement patterns.
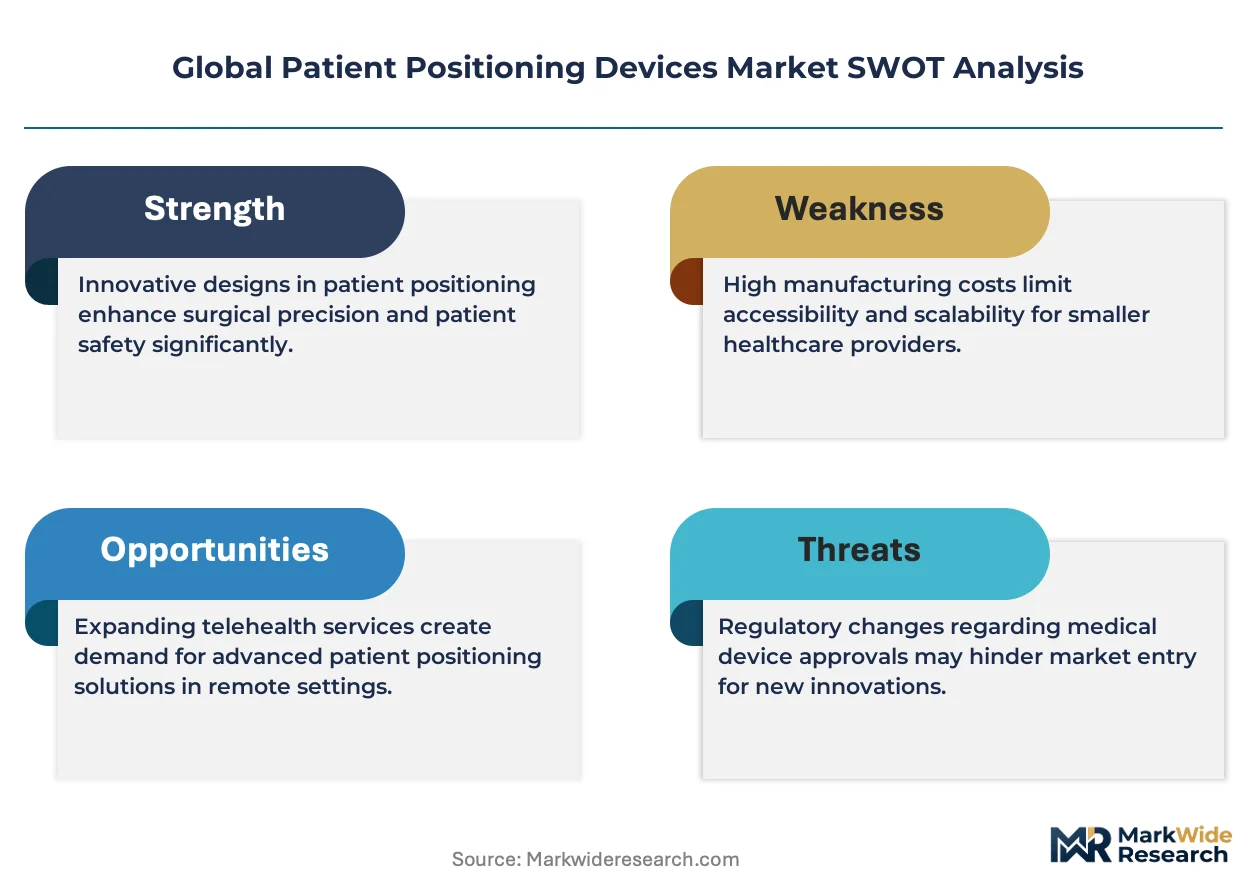
The FDA enforces biocompatibility and sterilization validation standards under its medical device quality system regulations, while ISO 13485 certification shapes supplier eligibility for contract manufacturing relationships with branded device companies. The EU MDR's heightened clinical evidence requirements for Class I reusable devices are forcing smaller positioning pad manufacturers to consolidate or exit the European market. Stakeholders must monitor how FDA guidance on cleaning validation for reusable patient contact surfaces evolves, as this will determine whether single-use disposable positioning systems capture share from traditional reusable platforms in high-throughput surgical settings.
Market Dynamics
Hospital supply chain consolidation across the United States is compressing vendor margins while amplifying procurement power for standardized positioning platforms. Ambulatory surgery center expansion is simultaneously fragmenting demand toward specialized, procedure-specific immobilization systems.
Growth Catalysts
- EU MDR compliance mandates:The EU Medical Device Regulation's clinical evidence requirements for Class I reusable devices are accelerating hospital procurement of validated, sterilizable positioning systems from certified suppliers.
- Radiotherapy precision demands:Reproducible immobilization requirements in proton and photon beam therapy centers are driving vacuum positioning technology adoption for head-and-neck oncology protocols.
- Minimally invasive surgery volume:Laparoscopic and robotic procedure expansion in United States ambulatory settings is generating demand for pressure-distributing gel supports that maintain thermal stability under prolonged pneumoperitoneum.
Market Restraints
- Silicone gel input volatility:Medical-grade viscoelastic gel formulations face petrochemical feedstock price swings that compress margin predictability for premium positioning pad manufacturers.
- Single-use substitution threat:Disposable foam positioning systems are capturing share in high-throughput outpatient surgical settings where cleaning validation costs exceed replacement economics.
- European vendor consolidation:Smaller reusable pad manufacturers lacking ISO 13485 certification are exiting the EU market under MDR burden, reducing competitive supply diversity.
Strategic Opportunities
- India surgical infrastructure:Private hospital chain expansion under the country's PLI scheme for medical devices is creating first-mover positioning for radiolucent composite manufacturers establishing local assembly.
- AI-enabled positioning convergence:Integration of optical tracking with vacuum-bead immobilization systems is enabling real-time patient shift detection during fractionated radiotherapy delivery.
- Japan geriatric rehabilitation:METI-funded eldercare facility modernization is opening procurement channels for pressure injury prevention mattresses with integrated positioning functionality.
Industry Challenges
- Biocompatibility testing timelines:FDA 510(k) submissions for novel radiolucent composites face extended validation cycles for cytotoxicity and sensitization endpoints.
- Legacy EMR integration friction:Positioning device utilization tracking for hospital asset management requires HL7 FHIR interface development that strains mid-tier manufacturer IT resources.
- Sterilization validation expertise scarcity:Validated steam and hydrogen peroxide cycle development for reusable supports demands specialized microbiology talent concentrated among contract sterilization providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Positioning Devices Market |
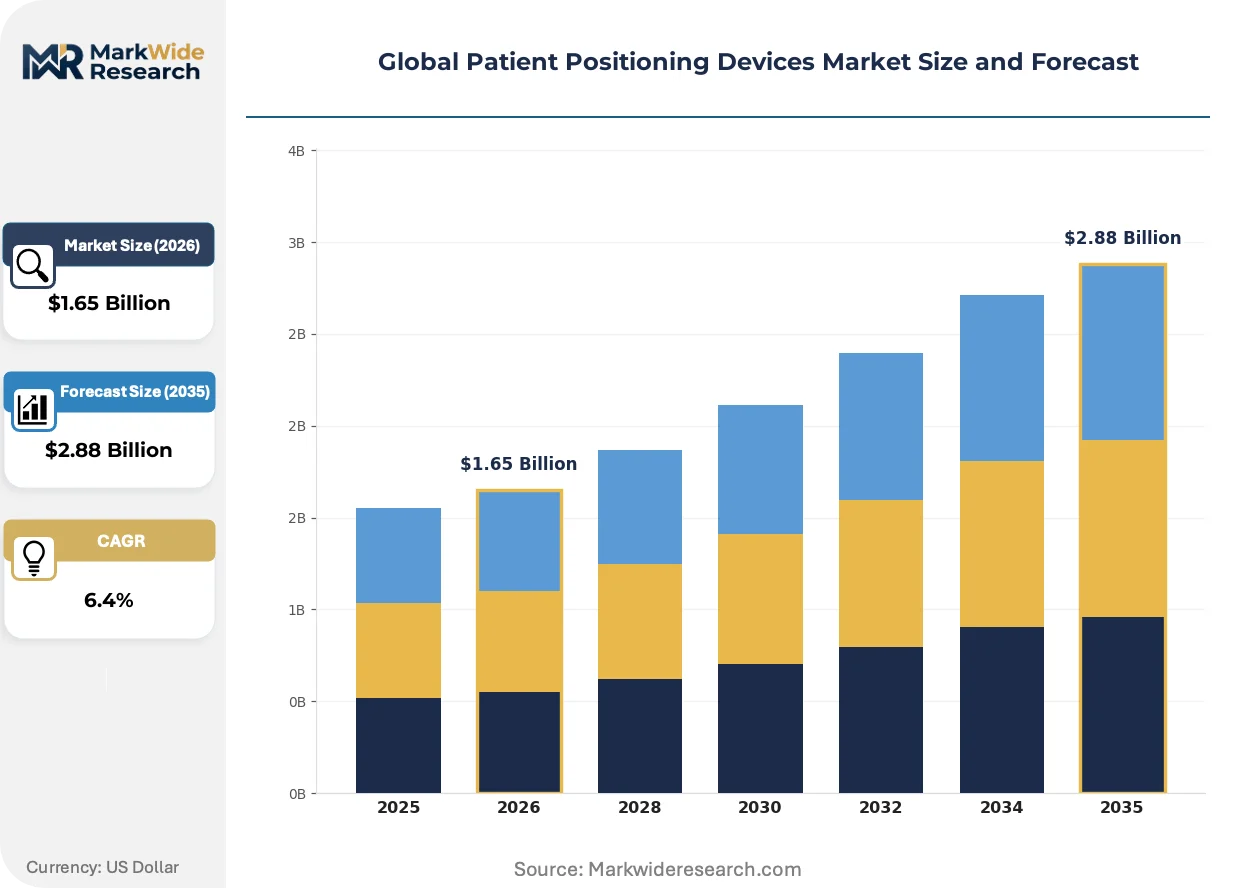
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Supports, Body Boards, Positioning Pads, Arm Supports, Leg Supports Technology: Vacuum Positioning, Gel Positioning, Foam Positioning, Air Cell, Moldable Positioning Application: Radiotherapy, Diagnostic Imaging, Surgical Procedures, Physical Therapy, Patient Transport End User: Hospitals, Ambulatory Surgery Centers, Physical Therapy Clinics, Diagnostic Centers, Rehabilitation Facilities |
| Companies Covered | Stryker Corporation, Getinge AB, STERIS plc, Hill-Rom Holdings, Mizuho OSI, Span-America Medical Systems, Medtronic, Arjo, Skytron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Positioning Devices Market Shifts & Advancements
Radiotherapy and surgical positioning technology trajectories are converging around reproducibility, traceability, and pressure injury prevention. Material science advances and regulatory digitization are reshaping how immobilization systems demonstrate clinical value.
Carbon fiber reinforced polymer positioning cradles are unifying radiolucency requirements across imaging modalities from CT simulation through cone-beam CT guidance. Academic medical centers in Germany and the United States are adopting these platforms for spine and pelvic radiotherapy protocols. The technology is unifying previously separate positioning inventories into single-platform investments that reduce capital duplication across radiation oncology departments.
China's NMPA medical device unique identification system is mandating traceability serialization for Class II and III positioning products entering domestic distribution. Manufacturers must embed UDI-compliant labeling and establish post-market surveillance infrastructure to maintain market access. Domestic Chinese suppliers are responding faster than multinational competitors, leveraging SAMR-aligned quality management systems already deployed for domestic device registration.
Hospital group purchasing organizations are unbundling positioning device procurement from capital equipment bundles, creating standalone sourcing events for gel pads, vacuum bags, and reusable supports. This disintermediation pressures original equipment manufacturers who previously captured positioning attach rates through system sales. The pattern is most pronounced in United States integrated delivery networks consolidating orthopedic and spine surgery supply chains under centralized materials management.
Global Patient Positioning Devices Market Segmentation
Patient positioning device procurement follows distinct logic across clinical settings. Product selection hinges on sterilization compatibility, imaging transparency, and pressure injury prevention protocols specific to each intervention type.
Product Type:
Hospital materials managers prioritize durability cycles and replacement economics when evaluating positioning hardware.
- Positioning Pads:Multi-layer viscoelastic gel or composite foam constructions distribute pressure across bony prominences during prolonged procedures. Demand concentrates in United States ambulatory surgery centers where thermal stability under pneumoperitoneum drives premium gel specifications.
- Head Supports:Vacuum-bead or thermoplastic systems immobilize cranial anatomy for stereotactic radiosurgery and neurosurgical access. German university hospitals are expanding procurement of carbon fiber reinforced cradles that maintain sub-millimeter reproducibility across fractionated radiotherapy courses.
- Body Boards:Radiolucent composite platforms enable unobstructed imaging from simulation through treatment delivery.
- Arm Supports:Adjustable limb positioning systems facilitate lateral decubitus and prone surgical approaches.
- Leg Supports:Lithotomy and stirrup configurations support gynecologic and urologic procedure access.
Volume sits with Positioning Pads; growth tilts toward Head Supports.
Technology:
Technology selection maps directly to immobilization precision requirements and procedure duration.
- Vacuum Positioning:Bead-matrix systems conform to patient anatomy and lock into rigid immobilization via air evacuation. Proton therapy centers in the United States and Japan specify these platforms for head-and-neck protocols where millimeter-level reproducibility affects clinical outcomes.
- Gel Positioning:Medical-grade viscoelastic polymers maintain conformability and thermal neutrality across multi-hour interventions. Silicone gel input volatility compresses margin predictability for manufacturers serving high-volume surgical markets.
- Foam Positioning:Open-cell polyurethane systems dominate economy-tier procurement in physical therapy settings.
- Air Cell:Inflatable compartment systems enable dynamic pressure redistribution for bariatric patients.
- Moldable Positioning:Thermoplastic sheets conform to anatomy and harden for reproducible immobilization.
Installed base concentrates in Gel Positioning; steepest expansion trajectory belongs to Vacuum Positioning.
Application:
Application segmentation reflects divergent imaging and access requirements across clinical modalities.
- Surgical Procedures:Positioning systems must balance anatomical access with pressure injury prevention across laparoscopic, robotic, and open approaches. United States hospital networks are consolidating procurement of standardized gel platforms across orthopedic and spine service lines.
- Radiotherapy:Immobilization reproducibility directly impacts treatment accuracy in external beam and proton protocols. Academic medical centers in Germany and the United States are unifying positioning inventories around carbon fiber cradles that span CT simulation through cone-beam CT guidance.
- Diagnostic Imaging:Radiolucent positioning enables artifact-free MRI, CT, and PET acquisition.
- Physical Therapy:Foam-based positioning supports rehabilitation exercise protocols with frequent replacement cycles.
- Patient Transport:Transfer boards and slide sheets facilitate safe movement between care settings.
Revenue weight rests with Surgical Procedures; expansion concentrates in Radiotherapy.
End User:
End-user procurement patterns diverge sharply between capital-intensive hospital systems and fragmented outpatient settings.
- Hospitals:Integrated delivery networks leverage centralized supply chain contracts to standardize positioning platforms across service lines. United States hospital consolidation is compressing vendor margins while amplifying purchasing power for validated, sterilizable systems.
- Ambulatory Surgery Centers:High-throughput outpatient settings prioritize single-use disposables where cleaning validation costs exceed replacement economics. These facilities are fragmenting demand toward procedure-specific immobilization systems.
- Physical Therapy Clinics:Capital constraints and replacement frequency shape economy-tier foam procurement.
- Diagnostic Centers:Imaging-focused facilities require radiolucent positioning compatible with multi-modality workflows.
- Rehabilitation Facilities:Long-term care settings emphasize pressure injury prevention in bed-bound populations.
Procurement volume clusters in Hospitals; share gain is accelerating fastest in Ambulatory Surgery Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American procurement concentration as hospital networks headquartered there consolidate supply chain contracts for standardized positioning platforms across orthopedic and spine service lines.
United States
Integrated delivery networks in Texas and Florida are expanding ambulatory surgery center footprints with procedure-specific gel positioning systems. FDA biocompatibility validation requirements under 510(k) pathways shape supplier eligibility for contract manufacturing relationships. Cleveland Clinic and Mayo Clinic procurement consortiums in Ohio and Minnesota are driving standardization of vacuum positioning technology across radiation oncology departments.
Germany
University hospitals in Munich and Heidelberg are unifying radiotherapy positioning inventories around carbon fiber reinforced cradles for sub-millimeter reproducibility. EU MDR clinical evidence mandates for Class I reusable devices are compressing vendor diversity as smaller manufacturers exit. The Medical Valley cluster around Nuremberg-Erlangen is accelerating optical tracking integration with vacuum-bead immobilization systems.
Japan
Proton therapy centers in Chiba and Kobe are specifying vacuum positioning platforms for head-and-neck oncology protocols. METI-funded eldercare facility modernization is opening procurement channels for pressure injury prevention mattresses with integrated positioning functionality. The Kansai medical device manufacturing corridor around Osaka is expanding domestic production of radiolucent composite platforms.
China
Private hospital chain expansion under the PLI scheme for medical devices is creating first-mover positioning for radiolucent composite manufacturers establishing local assembly. NMPA unique identification system mandates are forcing traceability serialization infrastructure investments for Class II and III positioning products. The Yangtze River Delta medical technology zone around Shanghai is consolidating domestic supplier certification under SAMR-aligned quality management systems.
India
Corporate hospital chains in Maharashtra and Karnataka are upgrading surgical infrastructure with pressure-distributing positioning systems for minimally invasive procedure expansion. CDSCO medical device rules are tightening registration requirements for imported positioning pads and supports. The Gujarat medical device manufacturing cluster around Ahmedabad is attracting contract sterilization providers to serve reusable positioning system validation needs.
Global Patient Positioning Devices Market Competitive Landscape
The competitive structure tilts toward diversified surgical technology conglomerates with integrated positioning portfolios. Hospital supply chain consolidation across the United States is compressing vendor margins while amplifying procurement power for standardized platforms. Three archetypes dominate: integrated surgical technology providers, infection control specialists extending into validated sterilization systems, and regional composite manufacturers serving radiotherapy precision requirements. Competitive moves concentrate on strategic partnerships with proton therapy center developers and backward integration into medical-grade gel formulation supply.
Among diversified surgical technology providers, Stryker Corporation and Medtronic exemplify the integrated portfolio archetype that anchors premium positioning solutions within hospital operating suites. Getinge AB occupies a distinct position as an infection control specialist extending validated sterilization expertise into reusable positioning pad markets. These three entities represent the concentration of procurement influence as hospital networks consolidate purchasing decisions through centralized supply chain contracts.
| Leading Market Players |
|---|
| Stryker Corporation |
| Getinge AB |
| STERIS plc |
| Hill-Rom Holdings |
| Mizuho OSI |
| Span-America Medical Systems |
| Medtronic |
| Arjo |
| Skytron |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty positioning pad manufacturers anchor supply consolidation across United States hospital networks, translating procurement scale into disciplined pricing tiers that compress margin elasticity for mid-tier gel formulation suppliers serving ambulatory surgery centers.
Pricing Analysis
Outcome-linked pricing for radiotherapy immobilization systems ties contract value to millimeter-level reproducibility metrics in proton beam centers. Three-tier pricing structure across premium carbon fiber cradles, validated gel platforms with ISO 13485 certification, and economy foam pads separates clinical-grade sterilization cycles from basic pressure distribution. Cost compression in the economy tier intensifies because single-use disposables eliminate cleaning validation overhead for high-throughput outpatient settings. Ambulatory surgery centers exhibit acute price sensitivity; academic medical centers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks require qualified suppliers for both domestic gel formulation and Asian radiolucent composite fabrication. Manufacturing concentrates in China for carbon fiber reinforced polymers, Germany for precision-machined vacuum-bead systems, and the United States for medical-grade silicone gel compounding. Feedstock exposure centers on petrochemical-derived viscoelastic polymers and specialized epoxy resins for radiolucent platforms. Single-source vulnerability persists in validated sterilization cycle development, where contract providers with microbiology expertise command allocation priority. Distribution runs through hospital group purchasing organizations and direct contracts with proton therapy center developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in validated sterilization infrastructure prop pricing discipline for reusable positioning systems, as EU MDR compliance timelines outstrip qualified contract provider capacity expansion.
For Market Incumbents: Hedge against single-use substitution by securing backward integration into medical-grade gel formulation supply and expanding captive sterilization capacity in the United States Midwest. Stryker Corporation and Getinge AB anchor positioning through infection control expertise; smaller ISO 13485-certified specialists must defend share through GPO contract renewals before MDR-driven vendor consolidation completes. For New Entrants and Emerging Players: AI-enabled optical tracking integration with vacuum-bead immobilization offers a technology-first wedge into radiotherapy precision markets where academic medical centers prioritize real-time shift detection over legacy platform familiarity. Target India's private hospital chains under PLI scheme incentives with local radiolucent composite assembly partnerships. Pursue software companion development pathways that bypass capital-intensive sterilization validation requirements. For Investors and Strategic Acquirers: FDA 510(k) submission backlogs for novel radiolucent composites are the leading indicator that sterilization validation expertise scarcity will deepen competitive moats for incumbent platforms with established quality management systems. Long-term viability favors diversified surgical technology conglomerates with integrated positioning portfolios over standalone pad manufacturers facing biocompatibility testing timeline extensions. Monitor CDSCO registration tightening in India as a signal for emerging market entry barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | EU MDR compliance mandates eliminate uncertified competitors from German and French hospital procurement channels. |
| Backward Integration into Gel Formulation | Captive silicone polymer supply insulates margin predictability against petrochemical feedstock volatility. |
| Proton Therapy Center Partnership | Mayo Clinic and Cleveland Clinic consortiums standardize vacuum positioning specifications across radiation oncology. |
| Software Companion Development | HL7 FHIR interface integration enables positioning device utilization tracking for hospital asset management contracts. |
| Local Assembly in India | PLI scheme incentives for medical devices reduce landed cost for private hospital chains in Maharashtra and Karnataka. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures, complemented by interviews with radiation oncology physicists, biomedical engineers, hospital purchasing committee chairs, and sterilization validation specialists. Secondary sources included CMS Medicare reimbursement data, NMPA unique identification system mandates, and customs records for radiolucent composite imports. Bottom-up demand modeling across product types and technologies triangulated against top-down healthcare capital expenditure trends.
Cross-referencing historical positioning device replacement cycles with expert panel input on proton therapy center expansion timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application setting, and end-user procurement archetype. CAGRs derived from procedure volume trajectories in minimally invasive surgery and fractionated radiotherapy, weighted by capital equipment deployment patterns in academic medical centers versus ambulatory settings.
Several conditions sit outside the modeled scope, including abrupt FDA guidance revisions on cleaning validation for reusable patient contact surfaces and geopolitical disruptions to carbon fiber precursor supply chains. Forecasts reflect assumptions about MDR implementation timelines and hospital supply chain consolidation velocity. Deviation in proton therapy reimbursement policy or single-use disposable adoption curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Knee Arthrodesis Implant Market