
 India Non-Resilient Floor Covering Market | 2026-2036
India Non-Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
India Non-Resilient Floor Covering Market Foresight
Premium vitrified tile specifications is reorganizing procurement patterns across India's built environment. Kajaria Ceramics Ltd leverages integrated kiln capacity across Uttar Pradesh and Gujarat to sustain cost leadership in glazed vitrified tiles. Somany Ceramics Ltd anchors its position through extensive dealer networks penetrating Tier-2 and Tier-3 cities. RAK Ceramics India Private Ltd competes on large-format slab technology imported from its UAE parent operations.
India non-resilient floor covering comprises rigid surfacing materials—ceramic, porcelain, natural stone, laminate, and vinyl products—manufactured through high-temperature firing or pressure-bonding processes to achieve compressive strength exceeding 35 MPa for heavy-traffic commercial installation. Ceramic and porcelain tiles dominate material throughput due to water absorption rates below 0.5 percent that suit humid tropical climates across India's coastal states. Tile commands the largest product-type share by installed volume, while stone surfaces capture premium margin pools in luxury residential and five-star hospitality segments. E-Commerce distribution channels are gaining traction for standardized SKUs, though project-scale commercial orders still flow through wholesale and direct-sales relationships.
BIS mandates ceramic tile grading under IS 15622, while the CEA's building energy codes indirectly steer specification toward thermally efficient porcelain surfaces. India's PLI scheme for specialty steel and construction materials is expected to extend downstream into tile manufacturing equipment, altering capital-intensity calculations for domestic producers. Stakeholders must monitor how state-level RERA enforcement tightens developer accountability for material specifications in residential projects.
Market Dynamics
Commercial real estate developers in Mumbai and Bengaluru are expanding specification-grade tile procurement, tightening quality thresholds that cascade through Gujarat's Morbi ceramic cluster and reshape domestic manufacturing priorities.
Growth Catalysts
- CEA building energy codes:Thermally efficient porcelain surfaces are gaining preference in commercial specifications across Maharashtra and Karnataka as developers target green building certifications.
- Morbi ceramic cluster concentration:Gujarat's integrated supply base delivers cost-competitive vitrified tile volumes that penetrate Tier-2 and Tier-3 distribution networks nationwide.
- RERA enforcement:State-level accountability mandates for residential developers are elevating material documentation standards and reducing substandard tile incidence in new construction.
Market Restraints
- Natural gas price volatility:Kiln firing operations in Morbi remain exposed to LNG import fluctuations that compress operating margins for continuous-process manufacturers.
- BIS certification friction:IS 15622 grading compliance creates 4-6 month approval timelines that delay new product launches and favor incumbent certified producers.
- Laminate flooring substitution:Click-lock vinyl and wood-plastic composite surfaces are capturing budget residential segments in Delhi-NCR and Pune where moisture exposure is limited.
Strategic Opportunities
- PLI scheme extension:The production-linked incentive framework for specialty steel and construction materials is expected to encompass tile manufacturing equipment, altering capital-intensity calculations for domestic producers.
- E-commerce standard SKUs:Digital channels are gaining traction for retail tile volumes in Kerala and Tamil Nadu, bypassing traditional dealer markups for standardized formats.
- Large-format slab technology:Premium residential and five-star hospitality segments in Hyderabad and Chennai are importing thin-profile porcelain surfaces that command margin premiums over conventional ceramic.
Industry Challenges
- Digitized specification workflows:Architects and project consultants are migrating to BIM-compatible material libraries, forcing tile manufacturers to invest in 3D asset creation and API integration.
- Dealer network reconfiguration:Tier-2 city distributors face working capital strain from extended project payment cycles, compressing inventory turns and reducing breadth of stocked SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Non-Resilient Floor Covering Market |
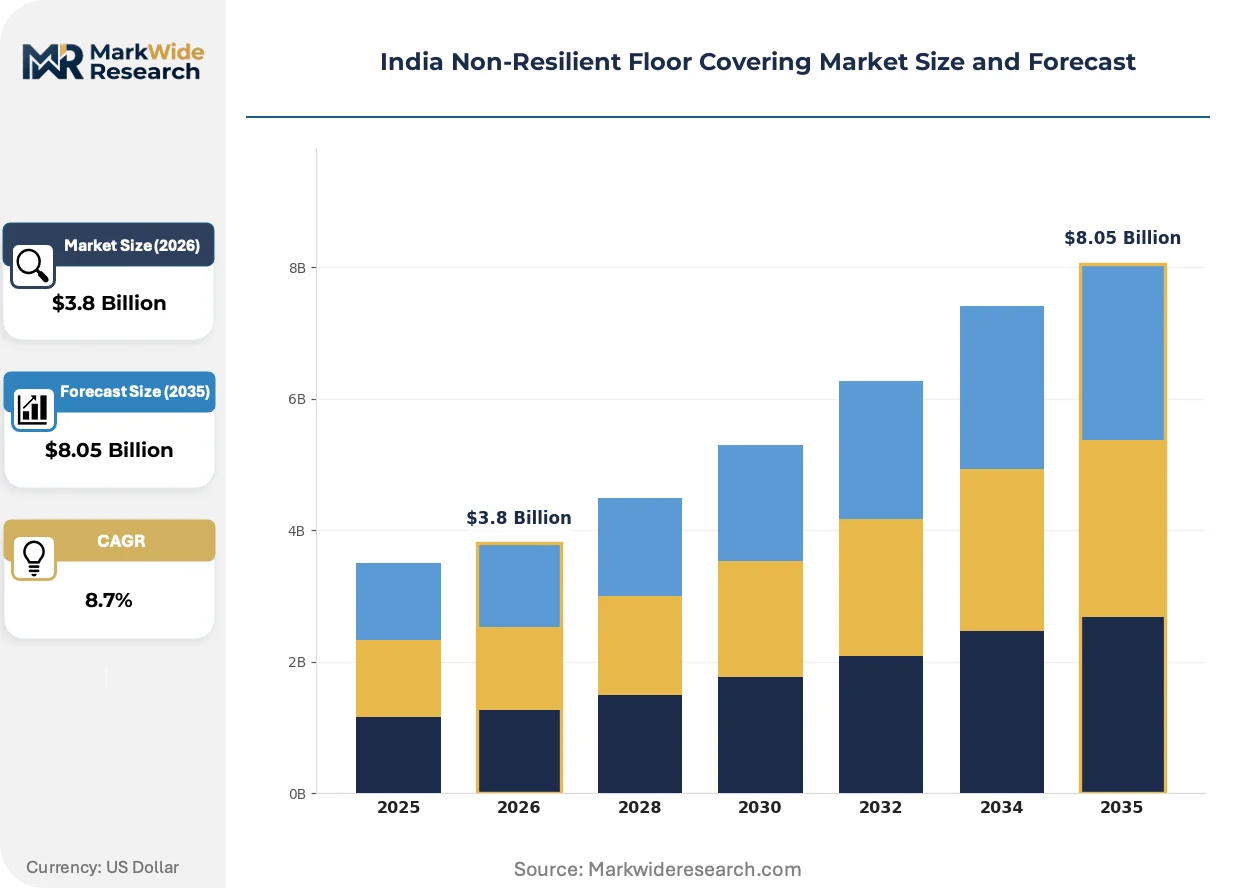
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tile, Laminate, Vinyl, Stone Application: Residential, Commercial, Industrial, Institutional Material: Ceramic, Porcelain, Natural Stone, Composite Distribution Channel: Retail Stores, E-Commerce, Wholesale, Direct Sales |
| Companies Covered | Kajaria Ceramics Ltd, Somany Ceramics Ltd, Century Plyboards India Ltd, Greenply Industries Ltd, Murudeshwar Ceramics Ltd, RAK Ceramics India Private Ltd, Mohawk Industries Inc, Accord Floors, Orient Bell Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Non-Resilient Floor Covering Market Shifts & Advancements
Digital inkjet decoration systems are compressing design-to-production lead times while large-format pressing technology is enabling thinner, lighter porcelain surfaces that reduce freight costs and installation labor.
Single-pass digital printing is decomposing the traditional screen-printing infrastructure that dominated Morbi's tile corridors. Luxury residential developers in Bengaluru and Hyderabad are specifying photorealistic stone and wood replicas at 600x1200mm formats. This capability shift is collapsing minimum order quantities for custom designs and fragmenting batch production economics across mid-scale manufacturers.
BIS mandates ceramic tile grading under IS 15622 with tightened water absorption thresholds that disqualify legacy kiln outputs. The standard's 2024 revision elevates modulus of rupture requirements for commercial-grade classifications. Export-oriented producers in Gujarat are recalibrating glaze formulations to simultaneously satisfy domestic BIS specifications and Gulf region import protocols.
Developer procurement is consolidating around direct-manufacturer relationships for project-scale volumes, disintermediating traditional wholesale channels in Mumbai's Parel and Bengaluru's Peenya industrial zones. E-commerce platforms are capturing standardized residential replacement demand in Kochi and Coimbatore with 48-hour delivery guarantees. This channel bifurcation is forcing distributors to specialize either in project logistics or last-mile retail service.
India Non-Resilient Floor Covering Market Segmentation
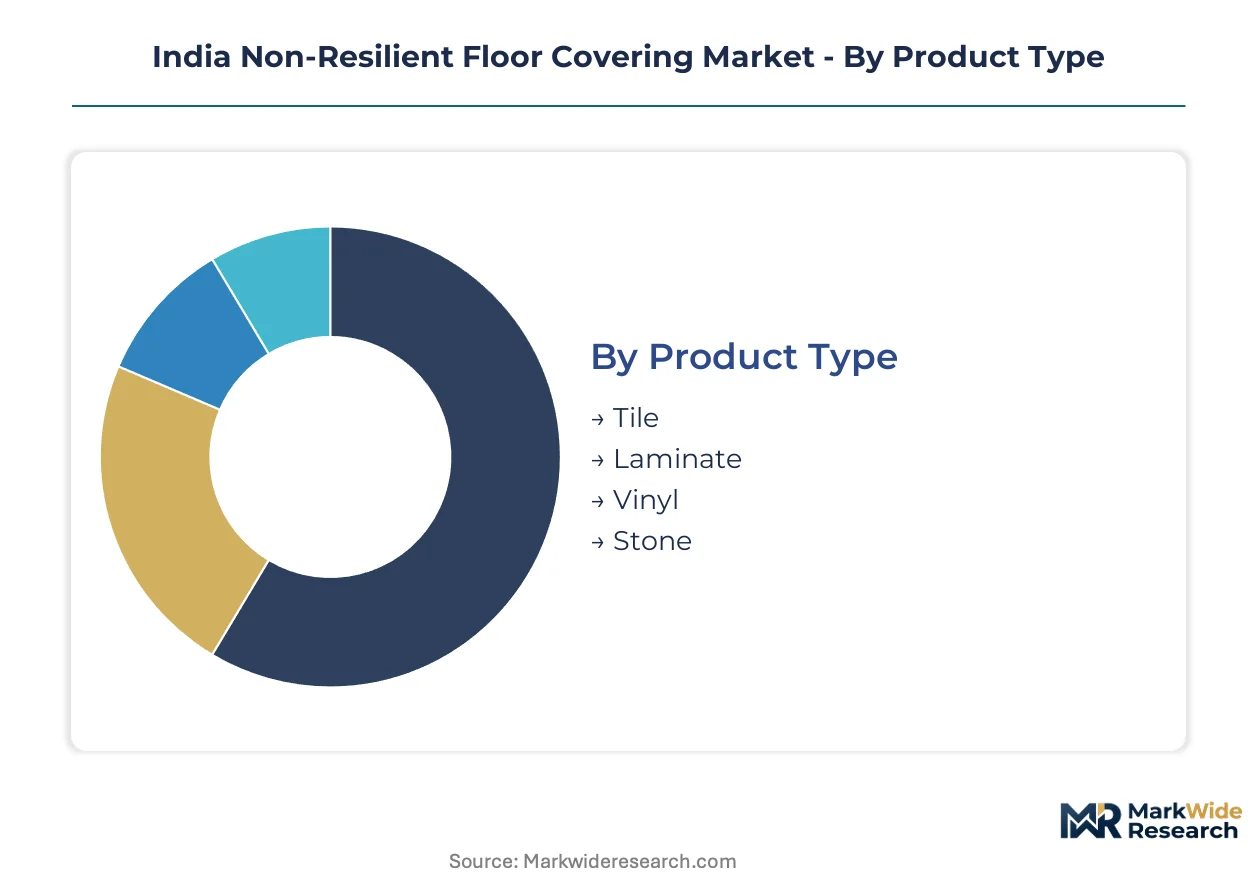
India's non-resilient floor covering market fragments across four intersecting dimensions that determine procurement routes and margin capture. Product type and distribution channel alignment shapes whether manufacturers compete on project-scale logistics or retail SKU velocity.
Product Type:
Channel-mix varies sharply by product rigidity and installation complexity, with project-scale volumes flowing through wholesale-direct pipelines while standardized formats migrate toward digital retail.
- Tile:Ceramic and vitrified surfaces dominate commercial specifications across Maharashtra and Karnataka. Mumbai developers specify 600x1200mm formats for high-traffic lobbies, with Morbi cluster producers capturing 48-hour fulfillment through direct-sales relationships.
- Laminate:Click-lock wood-composite surfaces penetrate budget residential replacement demand in Delhi-NCR. Moisture-sensitivity limits specification to dry interior zones, compressing margin pools versus porcelain alternatives.
- Vinyl:Rigid-core and glue-down formats serve institutional healthcare and education segments where chemical resistance and acoustic dampening outweigh premium aesthetics.
- Stone:Marble and granite surfaces command luxury residential and five-star hospitality specifications in Hyderabad and Chennai, with imported slabs bypassing domestic wholesale channels entirely.
Tile dominates installed base. Stone is where expansion concentrates.
Application:
Cost-tier stratification separates specification-grade commercial procurement from price-sensitive residential replacement cycles.
- Residential:Tier-2 and Tier-3 city homeowners drive volume through dealer networks stocking 300x300mm and 400x400mm ceramic formats. RERA enforcement is elevating documentation standards for new construction material specifications.
- Commercial:Bengaluru and Mumbai office developments specify BIS-certified vitrified tiles with modulus of rupture exceeding 35 MPa. CEA building energy codes steer thermally efficient porcelain selection for green certification compliance.
- Industrial:Chemical-resistant epoxy-modified surfaces serve pharmaceutical and food-processing facilities in Gujarat and Maharashtra where contamination control mandates rigid flooring.
- Institutional:Government healthcare and education projects in Tamil Nadu and Kerala flow through tender-based wholesale procurement with extended payment cycles compressing distributor working capital.
Residential commands volume throughput. Commercial delivers margin expansion.
Material:
Supply concentration in Gujarat's Morbi corridor shapes cost-positioning across ceramic and porcelain grades.
- Ceramic:Water absorption rates of 3-6 percent suit dry interior residential applications. Morbi kilns produce standardized formats for pan-India distribution through Tier-2 dealer networks.
- Porcelain:Sub-0.5 percent water absorption and compressive strength exceeding 50 MPa enables heavy-traffic commercial installation. BIS IS 15622 certification creates 4-6 month approval friction favoring incumbent producers.
- Natural Stone:Rajasthan marble and granite quarries supply premium residential and hospitality segments, with Italian and Turkish imports capturing ultra-luxury specifications in Mumbai and Delhi.
- Composite:Engineered stone and terrazzo-derivative surfaces serve institutional healthcare applications requiring seamless hygiene surfaces and chemical resistance.
Ceramic leads installed volume. Porcelain is climbing the fastest on specification-grade commercial demand.
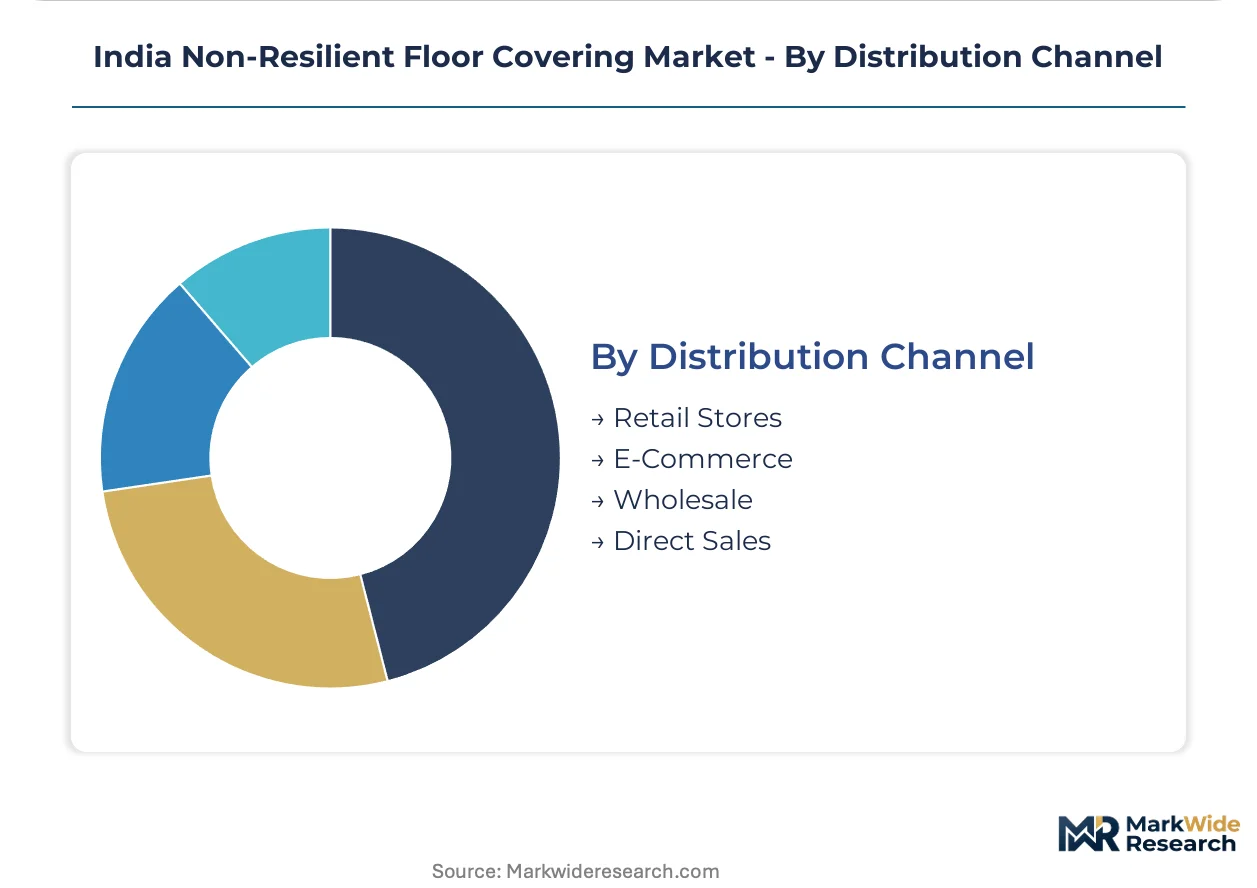
Distribution Channel:
Customer-type stratification separates project-scale logistics from last-mile retail service requirements.
- Retail Stores:Tier-2 city showrooms in Uttar Pradesh and Madhya Pradesh stock 200-300 SKUs with working capital strain from 90-day project payment cycles. Inventory turns compress as developers consolidate direct-manufacturer relationships.
- E-Commerce:Standardized 300x300mm and 400x400mm ceramic formats gain traction in Kerala and Tamil Nadu with 48-hour delivery guarantees. Digital channels bypass traditional dealer markups for replacement demand.
- Wholesale:Mumbai's Parel and Bengaluru's Peenya industrial zones handle project-scale logistics for commercial developers. Bulk procurement consolidates around direct-manufacturer relationships disintermediating traditional intermediaries.
- Direct Sales:Large-format slab and premium stone specifications flow through manufacturer-direct relationships for luxury residential and hospitality projects in Hyderabad and Chennai.
Wholesale retains project-scale dominance. E-Commerce is gaining share fastest on retail standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's non-resilient floor covering trade flows reflect a deepening import dependency for premium stone and large-format porcelain, even as Gujarat's Morbi cluster scales export volumes toward Gulf and African markets.
Maharashtra
Mumbai's commercial real estate developers specify BIS-certified vitrified tiles for high-traffic office lobbies and retail atriums. The state's adoption of CEA building energy codes steers procurement toward thermally efficient porcelain surfaces. Thane and Navi Mumbai logistics corridors handle inbound containerized slab imports from Italy and Turkey for luxury residential projects.
Gujarat
Morbi's integrated ceramic cluster produces over 80 percent of India's domestic tile volume through continuous-process kiln operations. BIS IS 15622 certification mandates from the central government have tightened quality thresholds, disqualifying legacy low-grade output. The cluster's natural gas-fired infrastructure remains exposed to LNG import price volatility that compresses operating margins during supply shocks.
Karnataka
Bengaluru's technology campus expansions and co-working space developments drive specification-grade porcelain demand for heavy-traffic installations. State-level RERA enforcement has elevated material documentation standards for residential developers. Peenya industrial zone wholesalers are consolidating direct-manufacturer relationships, disintermediating traditional distribution layers.
Tamil Nadu
Chennai's five-star hospitality pipeline imports thin-profile large-format porcelain slabs that command margin premiums over domestic ceramic alternatives. The state's institutional healthcare and education projects flow through tender-based procurement with extended payment cycles. Coimbatore's emerging e-commerce penetration offers 48-hour delivery guarantees for standardized residential replacement tiles.
Telangana
Hyderabad's luxury residential segment specifies photorealistic stone replicas in 600x1200mm formats for premium apartment developments. State infrastructure investment in metro rail corridors has activated transit-oriented commercial flooring specifications. Local dealer networks face working capital strain from 90-day project payment cycles, compressing inventory breadth.
India Non-Resilient Floor Covering Market Competitive Landscape
Listed leaders compete with private specialists across integrated kiln capacity and distribution reach. The market structure concentrates around three to four scaled manufacturers controlling specification-grade commercial channels, while mid-tier fabricators fragment across regional dealer networks. Strategic archetypes separate integrated producers with captive raw material sourcing from import-dependent specialists and laminate-focused wood-panel conglomerates. Competitive moves center on backward integration into frit and glaze formulation, plus digital channel development for standardized retail SKUs.
Among India-based ceramic producers, Kajaria Ceramics Ltd and Somany Ceramics Ltd exemplify the integrated archetype with multi-state kiln footprints, while RAK Ceramics India Private Ltd occupies a position as the UAE-parented specialist in large-format slab technology. Century Plyboards India Ltd and Greenply Industries Ltd represent wood-panel conglomerates that have diversified into laminate flooring surfaces, competing on click-lock installation convenience rather than ceramic durability. Murudeshwar Ceramics Ltd anchors a regional specialist position within South Indian distribution networks.
| Leading Market Players |
|---|
| Kajaria Ceramics Ltd |
| Somany Ceramics Ltd |
| Century Plyboards India Ltd |
| Greenply Industries Ltd |
| Murudeshwar Ceramics Ltd |
| RAK Ceramics India Private Ltd |
| Mohawk Industries Inc |
| Accord Floors |
| Orient Bell Ltd |
| Others |
Supply & Pricing Matrix
Ninety-day inventory turns across Morbi's wholesale distributors signal compressed working capital cycles that simultaneously constrain supply breadth and amplify price volatility for mid-tier ceramic grades. This lead-time compression concentrates pricing power with kiln-integrated manufacturers capable of 48-hour fulfillment, while fragmenting margin capture across dealer networks facing extended project payment cycles from Bengaluru and Mumbai developers.
Pricing Analysis
Commercial real estate developers anchor pricing stratification across three performance tiers: BIS-certified vitrified tiles command premiums for green building compliance, standard glazed ceramics serve volume residential replacement, and unbranded Morbi output competes on spot-market economics. Price differentiation hinges on IS 15622 certification status and direct-manufacturer relationship access, with certified producers capturing margin premiums while uncertified fabricators face cost compression from natural gas price volatility. Margins are tightening in the economy tier as laminate flooring substitution accelerates in Delhi-NCR moisture-limited applications.
Supply Chain Analysis
Strait of Hormuz LNG transit underwrites kiln firing economics across Gujarat's Morbi cluster, where continuous-process operations consume pipeline gas volumes tethered to import price fluctuations. Raw material dependencies center on Rajasthan feldspar, imported Italian glaze pigments, and Saudi petrochemical-derived polymer binders for composite surfaces. Single-source vulnerability concentrates in natural gas supply contracts, with distribution running through Mumbai's Parel and Bengaluru's Peenya wholesale corridors for project-scale logistics alongside emerging e-commerce channels for standardized retail SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as specification-grade commercial procurement consolidates around direct-manufacturer relationships while Tier-2 retail channels remain underserved by digital fulfillment capabilities. BIM-compatible material libraries and 48-hour e-commerce delivery guarantees create niche entry points for agile specialists.
For Market Incumbents: Secure backward integration into frit and glaze formulation to defend margin position against imported large-format slab competition from UAE-parented specialists. Invest in captive natural gas storage infrastructure to buffer LNG price volatility exposure that currently compresses operating margins across Morbi's continuous-process kilns. For New Entrants and Emerging Players: Last-mile digital fulfillment gaps in Kerala and Tamil Nadu residential replacement markets offer white-space entry with 48-hour delivery guarantees for standardized 300x300mm and 400x400mm ceramic formats. Target Coimbatore and Kochi e-commerce penetration with API-integrated inventory systems that bypass traditional dealer markups and capture working capital-strained distributor volume. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-grade commercial channels concentrate around three to four scaled manufacturers while mid-tier fabricators fragment across regional networks. Monitor BIS certification approval timelines as inflection indicator—extended 4-6 month friction favors incumbent certified producers and creates acquisition targets among approval-pending mid-cap specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glaze Formulation | Captive frit production insulates margin from imported pigment cost volatility and accelerates BIS compliance timelines. |
| Digital Channel Development for Standard SKUs | E-commerce penetration in Kerala and Tamil Nadu bypasses 90-day dealer payment cycles and captures replacement demand velocity. |
| Large-Format Slab Technology Licensing | Thin-profile porcelain imports from UAE parent operations command premium positioning in Hyderabad and Chennai luxury residential. |
| Natural Gas Storage Infrastructure | On-site LNG buffering reduces exposure to Hormuz transit price spikes that compress Morbi kiln operating margins. |
| BIM-Compatible Asset Library Investment | 3D material specifications integrate with architect workflows migrating to digitized procurement platforms across Mumbai and Bengaluru. |
Research Methodology
Cross-validation between primary field interviews and secondary trade data anchors the qualitative findings in this study. Plant managers at Morbi cluster kilns, procurement leads at Mumbai commercial developers, Tier-2 city dealer principals, and CEA regulatory officials provided operational perspective. Secondary sources encompass BIS certification registries, Gujarat ceramic export customs records, RERA compliance filings, and CEA building energy code adoption tracking. Bottom-up production volume estimates from Morbi cluster capacity utilization triangulate against top-down construction sector flooring spend projections.
Sensitivity analysis across natural gas price bands, BIS certification approval timelines, and e-commerce penetration rates stress-tests base case assumptions over the projection horizon. Segmentation modeling incorporates product type rigidity, application cost-tier, material water absorption performance, and distribution channel logistics structure. CAGRs derive from installed base replacement cycles, commercial real estate pipeline tracking, and PLI scheme equipment incentive uptake assumptions.
Forecasts assume regulatory continuity in BIS IS 15622 enforcement and CEA building energy code adoption; material policy shifts would require re-modeling. Natural gas import price volatility, laminate substitution acceleration, and RERA documentation standard tightening constitute primary revision triggers. Practitioners should keep alternative scenarios live as LNG supply contract renegotiations and PLI scheme equipment incentive extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market