
 US Flooring Market | 2026-2036
US Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
US Flooring Market Insights
The US flooring market is pivoting on a widening gap between premium performance-engineered surfaces and commodity roll-goods. Mohawk Industries leverages captive resin and fiber operations to sustain margin compression at the mid-tier. Shaw Industries anchors its position through extensive domestic tufting and extrusion capacity. Interface differentiates via carbon-neutral tile programs and closed-loop reclamation infrastructure.
US flooring encompasses surface coverings manufactured from wood fiber composites, synthetic polymers, mineral aggregates, and textile backings, typically specified by wear-layer thickness, AC abrasion ratings, or static load tolerance for commercial traffic. The primary purpose is to protect structural substrates while providing aesthetic, acoustic, or ergonomic performance in built environments. Hardwood commands the premium residential specification channel where plank width and species certification drive selection. Vinyl, particularly rigid core SPC and WPC formats, captures the fastest growth trajectory across residential replacement and light commercial segments. Carpet maintains volume leadership in multifamily and hospitality roll-good applications, though margin pools have shifted toward modular tile in corporate fit-outs.
EPA TSCA Title VI governs composite wood formaldehyde emissions, while OSHA workplace safety standards influence installation contractor liability and adhesive specification. The California Air Resources Board maintains the most stringent state-level emissions protocols, effectively setting the national compliance baseline for manufacturers distributing across state lines. Stakeholders must monitor evolving DOE embodied carbon tracking requirements and state-level extended producer responsibility legislation that could reshape material recovery obligations.
Market Dynamics
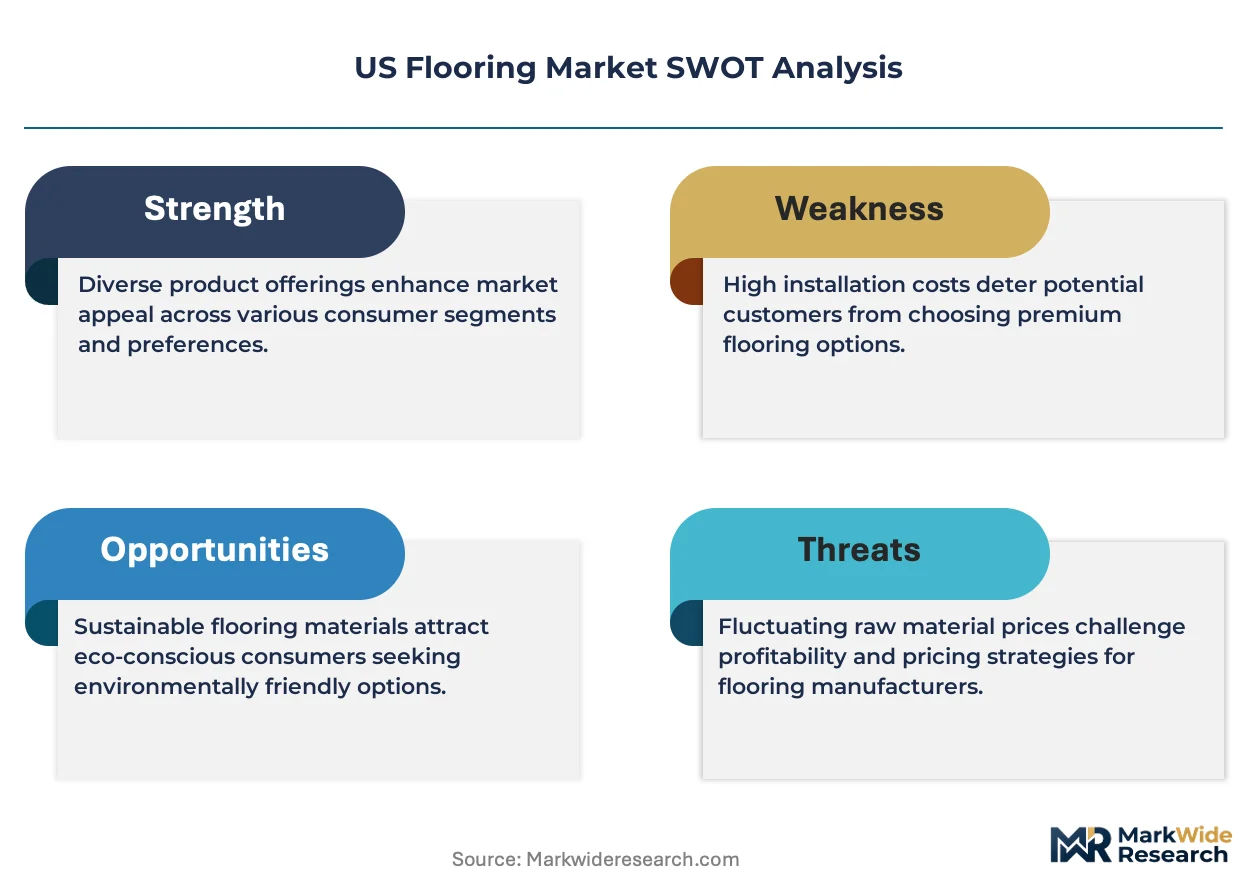
The US flooring market is bifurcating around EPA TSCA Title VI compliance costs, with certified engineered wood commanding premium positioning while uncertified imports face distribution lockouts. This regulatory wedge is compressing mid-tier margins and accelerating consolidation among domestic manufacturers with captive resin operations.
Growth Catalysts
- Multifamily Housing Pipeline:Texas and Florida metropolitan corridors are driving specification-grade vinyl and engineered hardwood volumes through accelerated permit issuance and rental unit absorption.
- EPA TSCA Title VI Certification:Composite wood products meeting the federal formaldehyde emissions standard gain preferential placement in big-box retail and institutional procurement channels.
- Rigid Core SPC Formulation:Stone-polymer composite technology is displacing traditional LVT in residential replacement applications through enhanced dimensional stability and click-profile installation speed.
Market Restraints
- Petrochemical Feedstock Volatility:Vinyl flooring margins remain exposed to PVC resin and plasticizer price swings tied to Gulf Coast refinery output fluctuations.
- Domestic Tufting Concentration:Carpet roll-good production clusters in Georgia and South Carolina create geographic supply risk during regional weather disruptions or logistics bottlenecks.
- Formaldehyde Testing Burden:California CARB Phase 2 third-party verification requirements add recurring certification costs that disproportionately burden smaller import distributors.
Strategic Opportunities
- Closed-Loop Reclamation Infrastructure:Post-consumer carpet and vinyl recovery networks in the Northeast and Pacific Coast states could satisfy emerging extended producer responsibility mandates before federal standardization.
- Carbon-Neutral Tile Programs:Interface-style embodied carbon tracking and offset integration appeals to corporate fit-out specifications seeking LEED v4.1 compliance.
- Light Commercial Modular Expansion:Healthcare and education renovation cycles favor glue-down LVT and bio-based tile over sheet goods, opening specification channels beyond traditional residential replacement.
Industry Challenges
- Certified Installer Shortage:EPA RRP lead-safe renovation training requirements and specialized SPC/WPC substrate preparation skills constrain qualified contractor availability in high-growth Sun Belt markets.
- Legacy Adhesive Specification Conflicts:Transition from solvent-based to water-based and pressure-sensitive adhesive systems requires retraining distributor specification teams and overcoming established installation contractor preferences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Flooring Market |
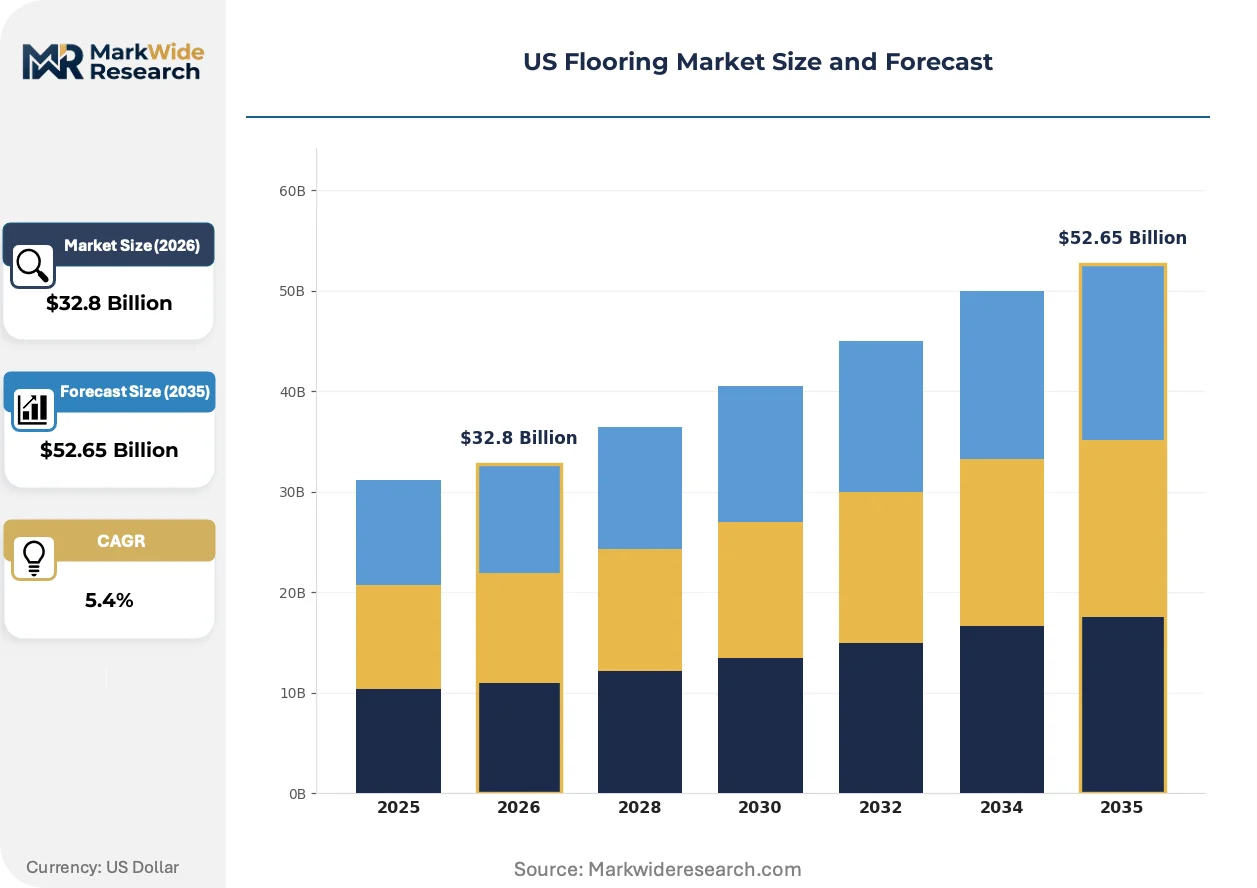
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Vinyl, Laminate, Hardwood End User: Residential, Commercial, Industrial, Institutional Installation Type: DIY, Professional, Pre-finished, On-site Distribution Channel: Online, Retail Stores, Wholesale, Direct |
| Companies Covered | Daltile, Tarkett, Mohawk Industries, Interface, Mannington Mills, Shaw Industries, AFI Licensing, Floor & Decor, Armstrong Flooring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Flooring Market Trends and Innovations
Digital printing and embossing technologies are collapsing the aesthetic differentiation gap between synthetic and natural materials, while regulatory carbon tracking and reclamation mandates reshape product lifecycle accountability. These forces are redrawing competitive moats around technical compliance rather than design alone.
Digital surface replication is automating the translation of exotic hardwood and natural stone visuals onto vinyl and laminate substrates with register-embossed texture synchronization. Residential replacement buyers and multifamily developers are specifying these products at accelerating rates for high-traffic common areas. This capability is automating the commoditization of premium aesthetic tiers that previously required genuine material procurement.
California Air Resources Board maintains the most stringent state-level formaldehyde emissions protocols, effectively setting the national compliance baseline for manufacturers distributing across state lines. The EPA's TSCA Title VI certification requirements impose third-party testing burdens that favor domestic producers with integrated quality control systems. Engineered hardwood and laminate segments face the steepest compliance cost escalations as retailers enforce chain-of-custody documentation.
Corporate and institutional buyers are consolidating flooring specification authority through national account procurement teams, displacing decentralized project-level decision-making. Design-build and integrated project delivery contracts in healthcare and education verticals are bundling material selection with installation warranties. This concentration is most visible in Texas and Florida metropolitan construction corridors where developer scale enables direct manufacturer negotiation.
US Flooring Market Segmentation
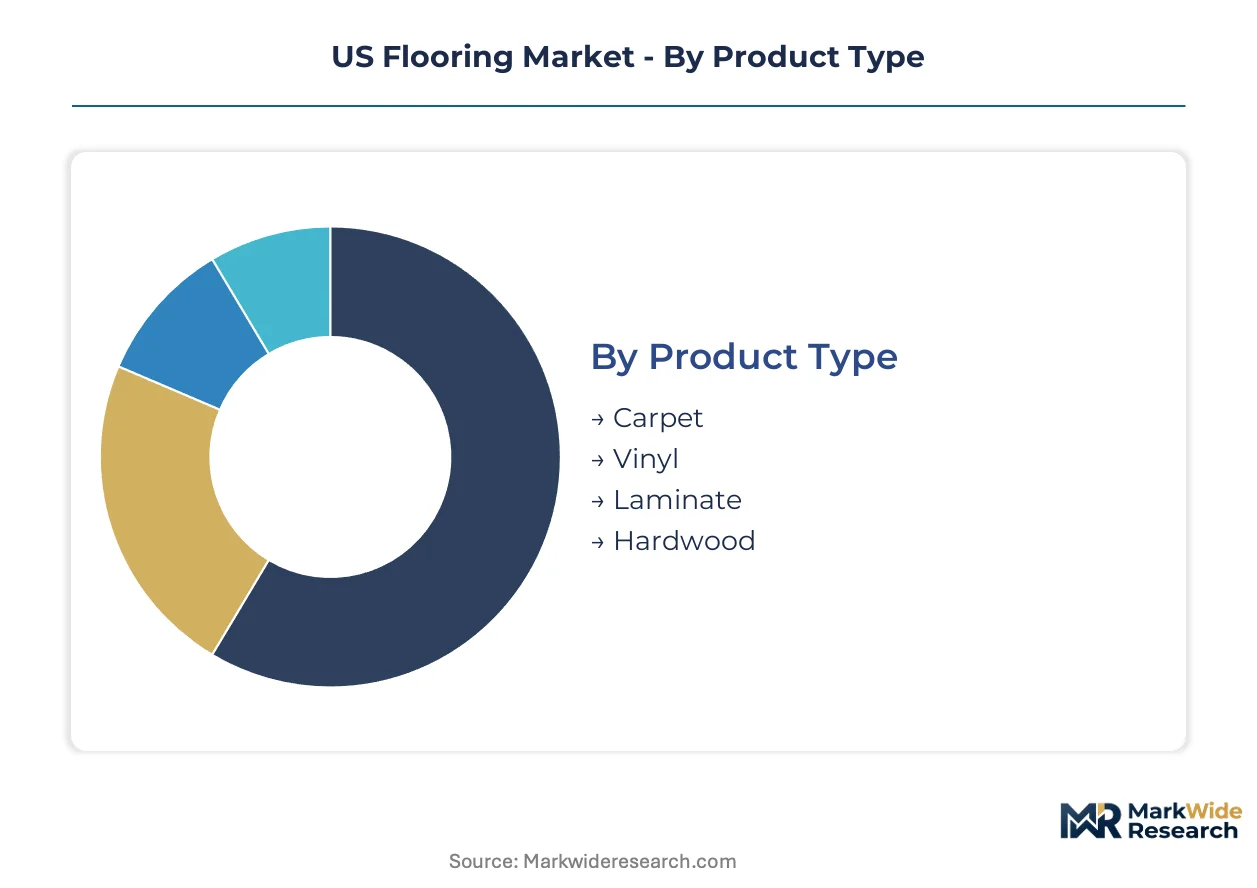
US flooring demand fragments across material performance tiers, installation labor models, and procurement channels that reshape margin capture. Replacement cycles and new construction specifications pull volume through divergent pathways.
Product Type:
Upgrade decisions hinge on wear-layer durability, substrate compatibility, and regulatory compliance costs that vary sharply by material chemistry.
- Vinyl:Rigid core SPC and WPC formats combine limestone-polymer composites with click-lock profiles for dimensional stability in humid climates. Texas and Florida multifamily developers specify these for rental unit turnover speed and moisture resistance.
- Hardwood:Engineered planks with thick wear layers anchor premium residential specifications where species certification and wide-plank aesthetics drive selection. CARB Phase 2 and EPA TSCA Title VI compliance documentation now gates big-box retail placement.
- Carpet:Tufted nylon and PET fiber roll-goods dominate multifamily and hospitality applications through acoustic performance and lower installed cost per square foot.
- Laminate:High-density fiber core products with aluminum oxide wear layers compete on price in residential replacement channels, though formaldehyde testing burdens constrain import sourcing.
Carpet sits at the top of the volume ranking, with vinyl climbing the fastest.
End User:
Application context dictates specification authority, warranty requirements, and maintenance protocol complexity.
- Residential:Single-family replacement cycles and new construction closings concentrate demand in suburban corridors. Homeowner preferences for DIY-friendly formats reshape product development priorities.
- Commercial:Corporate fit-outs and retail rollouts specify modular tile and glue-down LVT through national account procurement teams. LEED v4.1 compliance and embodied carbon tracking influence material selection.
- Institutional:Healthcare and education renovation cycles favor slip-resistant surfaces with antimicrobial treatments and extended wear warranties.
- Industrial:Static control flooring and chemical-resistant epoxy systems serve manufacturing and warehousing applications with specialized substrate preparation requirements.
Residential commands the largest share of unit volume, while commercial specifications are expanding most quickly.
Installation Type:
Labor model selection determines project timeline, skill premium, and adhesive specification constraints.
- Professional:Certified contractors handle substrate moisture testing, floor leveling, and warranty-backed finishing. EPA RRP lead-safe renovation training requirements constrain qualified installer availability in Sun Belt growth markets.
- DIY:Click-profile rigid core and floating laminate formats reduce tool requirements and installation error rates. Big-box retailers promote these through in-store demonstration and video tutorial support.
- Pre-finished:Factory-applied coatings eliminate on-site sanding and curing delays, accelerating project completion for commercial timelines.
- On-site:Unfinished hardwood and custom stain matching retain specification in historic renovation and ultra-premium residential segments.
Professional installation captures the majority of commercial and institutional volume, with DIY formats gaining share fastest in residential replacement.
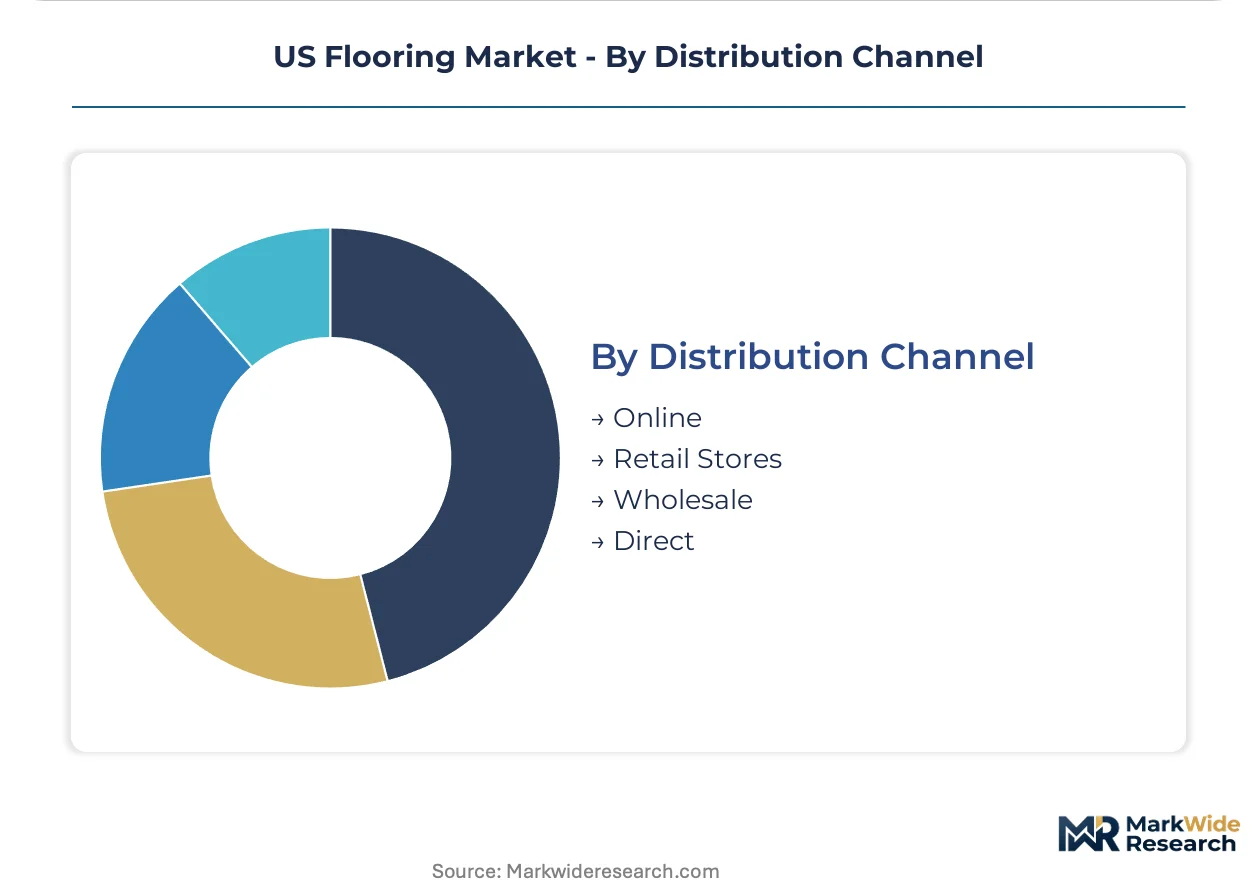
Distribution Channel:
Channel selection shapes price transparency, specification support, and inventory carrying costs.
- Retail Stores:Home center and specialty flooring showrooms provide tactile sampling and in-house installation referral networks. These locations concentrate in metropolitan construction corridors.
- Wholesale:Distributor warehouses serve contractor accounts with volume pricing, job-site delivery, and credit terms. Georgia and South Carolina tufting clusters feed this channel for carpet roll-goods.
- Direct:Large multifamily developers and national retail chains negotiate manufacturer-direct pricing for specification-grade vinyl and engineered hardwood.
- Online:E-commerce platforms compete on price for standardized products with established brand recognition, though sample ordering and return logistics create friction.
Retail stores maintain the highest transaction volume, with direct channel expansion accelerating among scaled developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's engineered hardwood exports compete with US domestic production on certification standards, while China's laminate manufacturing faces EPA TSCA Title VI distribution barriers. Regional flooring demand clusters around metropolitan construction corridors with distinct regulatory and supply chain profiles.
California
Los Angeles and San Francisco multifamily developers specify CARB Phase 2 certified engineered hardwood for luxury rental conversions. The California Air Resources Board maintains formaldehyde emissions protocols that exceed federal TSCA Title VI thresholds, forcing distributors to maintain dual inventory tiers. Sacramento's state procurement offices anchor institutional vinyl tile specifications for education renovation bonds.
Texas
Dallas-Fort Worth and Houston metropolitan corridors drive rigid core SPC volume through accelerated multifamily permit issuance and rental absorption rates. The Texas Department of Licensing and Regulation enforces contractor certification for commercial installation warranties. Georgia carpet tufting clusters supply roll-goods through Dallas wholesale distribution hubs serving Sun Belt replacement cycles.
Florida
Miami and Tampa construction corridors prioritize moisture-resistant vinyl formats for humid climate performance in hospitality and senior housing verticals. The Florida Building Code mandates specific substrate preparation protocols for coastal flood zone installations. Dalton, Georgia manufacturers maintain dedicated Florida inventory positions through Jacksonville and Orlando distribution nodes.
New York Metro
Manhattan and Brooklyn commercial fit-outs specify modular carpet tile with embodied carbon tracking for LEED v4.1 compliance in corporate headquarters relocations. The New York State Department of Environmental Conservation enforces extended producer responsibility frameworks for post-consumer carpet recovery. Newark and Bridgeport port facilities handle European luxury vinyl import volumes for Northeast retail channels.
Southeast
Atlanta and Charlotte anchor residential replacement demand through big-box retail concentration and DIY-friendly product penetration. Georgia and South Carolina tufting clusters face geographic supply risk during Atlantic hurricane season logistics disruptions. EPA Region 4 enforcement of RRP lead-safe renovation training constrains certified installer availability in rapid-growth suburban corridors.
US Flooring Market Competitive Landscape
Top-tier vendors anchor specification-grade engineered wood and rigid core vinyl segments, while mid-tier domestic fabricators compete on CARB Phase 2 compliance speed and wholesale distributor relationships. The market structure favors manufacturers with captive resin operations and integrated quality control systems that absorb EPA TSCA Title VI testing burdens. Three archetypes dominate: vertically integrated fiber-resin producers, specialty modular tile innovators, and wholesale distributor private-label platforms. Consolidation accelerates through acquisition of regional extrusion capacity and strategic partnerships with multifamily developer procurement teams.
Among Georgia-based integrated producers, Mohawk Industries and Shaw Industries exemplify scale-driven archetypes with captive supply chain control. Interface occupies a position within the carbon-neutral modular tile specialization tier, representing closed-loop reclamation infrastructure investment. Tarkett and Armstrong Flooring sit within the diversified surface covering portfolio segment, anchoring multi-material specification capability across residential and institutional channels.
| Leading Market Players |
|---|
| Daltile |
| Tarkett |
| Mohawk Industries |
| Interface |
| Mannington Mills |
| Shaw Industries |
| AFI Licensing |
| Floor & Decor |
| Armstrong Flooring |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EPA TSCA Title VI compliant engineered wood and uncertified imports creates parallel pricing ladders that reshape procurement patterns across residential and commercial channels. This divergence concentrates margin capture among domestic manufacturers with captive resin operations while compressing mid-tier positioning for import-dependent distributors.
Pricing Analysis
Capacity additions in Georgia and South Carolina are reshaping price floors for carpet roll-goods through concentrated tufting scale. Three-tier pricing structure across premium engineered hardwood, specification-grade vinyl, and commodity laminate segments reflects CARB Phase 2 certification costs and wear-layer thickness differentials. Price erosion runs through laminate imports facing third-party testing burdens. Multifamily developers exhibit highest price sensitivity, while luxury residential buyers prioritize species certification over per-square-foot cost.
Supply Chain Analysis
PVC resin supply rests on Gulf Coast petrochemical complexes and integrated domestic producers with captive chlorine-alkali operations. Limestone filler draws from Tennessee and Alabama quarry networks, while Georgia tufting clusters anchor carpet fiber production. Single-source vulnerability concentrates in plasticizer additives tied to regional refinery output fluctuations. Distribution runs through Dallas and Atlanta wholesale hubs serving Sun Belt metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as multifamily developers shift specification authority toward CARB Phase 2 certified engineered hardwood for luxury rental conversions.
For Market Incumbents: Cement specification-grade positioning through accelerated TSCA Title VI certification documentation and direct procurement relationships with Texas and Florida multifamily developers. Threat from rigid core SPC displacement of traditional LVT demands backward integration into limestone-polymer composite extrusion capacity. Channel control through captive wholesale distribution in Atlanta and Dallas anchors margin defense.
For New Entrants and Emerging Players: Begin with carbon-neutral modular tile programs targeting corporate fit-out specifications in New York Metro and California markets seeking LEED v4.1 compliance. Healthcare and education renovation cycles offer penetrable white-space beyond residential replacement saturation. Go-to-market leverage through embodied carbon tracking integration with national account procurement teams.
For Investors and Strategic Acquirers: Consolidation pressure builds where EPA testing burdens disproportionately burden smaller import distributors lacking integrated quality control systems. Long-term viability favors vertically integrated producers with captive resin and fiber operations across the projection horizon. Acquisition target archetype: regional extrusion specialists with established CARB Phase 2 compliance infrastructure. Signal to watch: state-level extended producer responsibility legislation triggering material recovery obligation reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Operations | Mohawk and Shaw anchor margin control through captive PVC and fiber production. |
| Carbon-Neutral Tile Program Launch | Interface-style embodied carbon tracking satisfies corporate LEED v4.1 procurement mandates. |
| Closed-Loop Reclamation Infrastructure | Post-consumer carpet recovery networks preempt extended producer responsibility enforcement. |
| Direct Developer Procurement Partnership | Scaled multifamily builders in Texas and Florida negotiate manufacturer-direct pricing. |
| Certified Installer Network Expansion | EPA RRP-trained contractor pools constrain qualified labor availability in Sun Belt growth markets. |
Research Methodology
Direct dialogue with flooring manufacturer product managers, wholesale distributor account executives, multifamily developer procurement directors, and certified installation contractors grounded this analysis in operational reality. Secondary validation drew from EPA TSCA Title VI certification databases, California Air Resources Board emissions protocols, SEC 10-K filings of publicly traded flooring companies, and metropolitan construction permit data. Bottom-up volume estimates triangulated against top-down market sizing across material segments.
Segment-level projections across vinyl, hardwood, carpet, and laminate categories incorporated installation type splits and distribution channel dynamics throughout the forecast period. CAGRs derived from historical replacement cycle analysis, new construction absorption rates, and regulatory compliance cost trajectories. Industry-specific inputs included petrochemical feedstock price correlation models and multifamily housing pipeline tracking across Texas and Florida metropolitan corridors.
Several conditions sit outside the modeled scope, including potential federal extended producer responsibility standardization, abrupt Gulf Coast refinery disruptions, and tariff restructuring on Asian laminate imports. Forecasts reflect documented assumptions about regulatory enforcement continuity and construction labor availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
China Wood Flooring Market