
 Global Flooring and Carpet Market | 2026-2036
Global Flooring and Carpet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flooring and Carpet Market Analysis
Direct-to-contractor digital platforms is rewriting procurement pathways across the Global Flooring and Carpet Market, compressing traditional distributor markups and accelerating specification-to-installation timelines. Mohawk Industries leverages captive carpet tile manufacturing across multiple continents to sustain margin control amid raw material volatility. Shaw Industries Group anchors its position through backward integration into polymer fiber production, insulating itself from petrochemical price swings. Tarkett competes on regenerative material science, differentiating its resilient flooring portfolio with post-consumer recycled content thresholds that exceed industry baselines.
Global Flooring and Carpet encompasses load-bearing and decorative surface coverings manufactured from textile, polymer, mineral, or wood-based substrates, typically specified by wear-layer thickness, slip-resistance rating, and acoustic absorption coefficient for commercial applications. The category serves primary functions of structural protection, thermal insulation, and interior environmental quality management across built environments. Luxury vinyl commands expanding share in hospitality and healthcare settings where moisture resistance and rapid installation offset first-cost premiums against traditional alternatives. Engineered wood occupies the premium residential tier, with thicker wear layers and stable cross-ply construction commanding specification in multi-family housing and high-end commercial interiors. Carpet tiles retain dominance in corporate office fit-outs, where modular replacement economics and design flexibility sustain recurring renovation demand.
The EPA's formaldehyde emission standards for composite wood products and REACH's restriction on phthalates in resilient flooring substrates jointly elevate compliance costs for manufacturers serving transatlantic markets. ISO 14001 environmental management certification and EPDs (Environmental Product Declarations) increasingly function as pre-qualification gates for public-sector procurement in Germany, France, and the Netherlands. Stakeholders must monitor how the EU's Construction Products Regulation revision tightens circularity requirements, as recyclability mandates will force capital redeployment toward closed-loop manufacturing infrastructure before specification criteria fully crystallize.
Market Dynamics
The EU Green Deal's embodied-carbon thresholds for construction materials are redirecting specification decisions toward low-emission substrates, forcing manufacturers to reconfigure supply chains before circularity mandates fully crystallize.
Growth Catalysts
- Residential renovation intensity:Retrofit cycles in the United States, Germany, and China compress replacement intervals and sustain recurring volume pull across load-bearing surface coverings.
- REACH phthalate restrictions:The EU's chemical framework elevates compliance costs for incumbent resilient flooring suppliers, creating specification openings for bio-based polymer alternatives.
- Carpet tile modularity:Modular replacement economics in corporate office fit-outs sustain recurring renovation demand through design flexibility and zone-specific refresh capabilities.
Market Restraints
- Petrochemical input volatility:Polymer fiber and vinyl resin costs swing with crude oil benchmarks, compressing margin predictability for manufacturers lacking backward integration.
- Formaldehyde emission compliance:The EPA's composite wood standards and overlapping state-level thresholds in California multiply testing and certification burdens for engineered wood suppliers.
- Mineral substrate freight costs:Ceramic and stone flooring faces structural disadvantage from weight-driven logistics premiums versus lightweight polymer alternatives.
Strategic Opportunities
- China tier-one commercial retrofit:Beijing, Shanghai, and Shenzhen office stock turnover accelerates specification windows for acoustic-rated carpet tile and rapid-install resilient systems.
- EPD pre-qualification gates:ISO 14001 certification and Environmental Product Declarations increasingly function as mandatory filters for public-sector procurement in Germany, France, and the Netherlands.
- Digital contractor platforms:Direct-to-installer procurement channels compress traditional distributor markups and accelerate specification-to-installation timelines.
Industry Challenges
- Closed-loop manufacturing capex:EU Construction Products Regulation revisions force capital redeployment toward recyclability infrastructure before return-on-investment certainty emerges.
- Cross-border certification fragmentation:Divergent acoustic absorption, slip-resistance, and fire-rating standards between North American and European jurisdictions multiply SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flooring and Carpet Market |
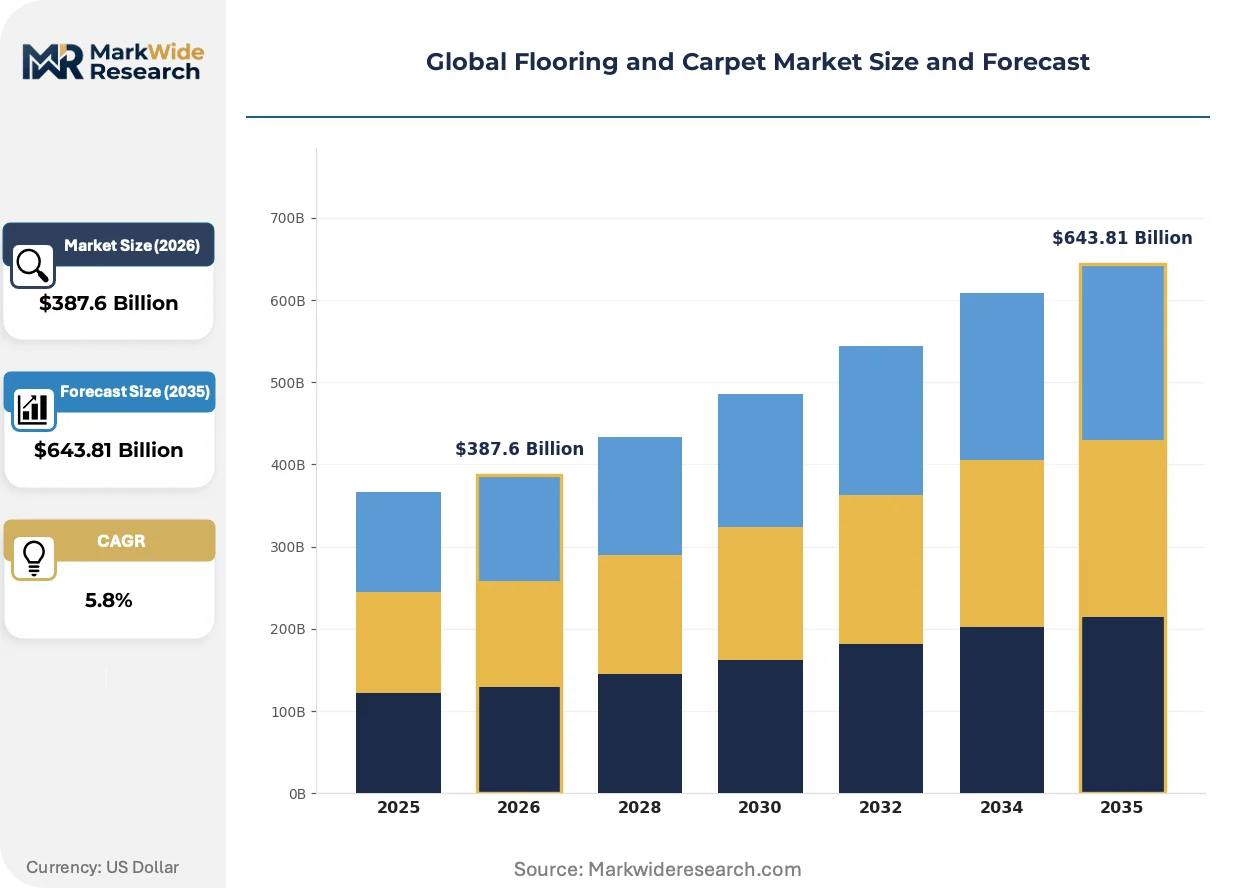
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet Tiles, Luxury Vinyl, Engineered Wood, Laminate Installation Type: Glue-Down, Floating, Staple, Nail-Down End User: Residential, Commercial, Hospitality, Industrial Material: Nylon, Polyester, Polypropylene, Wool |
| Companies Covered | Mohawk Industries, Shaw Industries Group, Tarkett, Interface, Beaulieu International Group, Milliken & Company, Forbo Management SA, Oriental Weavers, Gerflor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flooring and Carpet Market Emerging Trajectories
Material science convergence with digital specification tools is compressing traditional product development cycles and enabling real-time performance optimization across substrate categories.
Luxury vinyl tile is hybridizing polymer core layers with mineral composite fillers to achieve enhanced dimensional stability and acoustic dampening. Hospitality and healthcare facilities specify these systems where moisture resistance and rapid installation offset first-cost premiums against traditional alternatives. The technology is hybridizing specification criteria by merging resilient flooring performance with engineered wood aesthetic versatility.
REACH's restriction on phthalates in resilient flooring substrates elevates compliance costs for manufacturers serving transatlantic markets. Industrial consequence includes accelerated R&D redirection toward bio-plasticizers and non-PVC polymer systems. Healthcare and education verticals in Germany and the Netherlands respond fastest, embedding chemical hazard screening into procurement workflows ahead of mandate deadlines.
Facility managers now unbundle installation from material supply, contracting directly with certified installer networks rather than accepting turnkey distributor packages. Corporate real estate departments in the United States and United Kingdom lead this disintermediation, using digital platforms to compare labor rates and schedule flexibility independent of product sourcing. The shift compresses project timelines but exposes buyers to interface risk between material warranties and installation workmanship guarantees.
Global Flooring and Carpet Market Segmentation
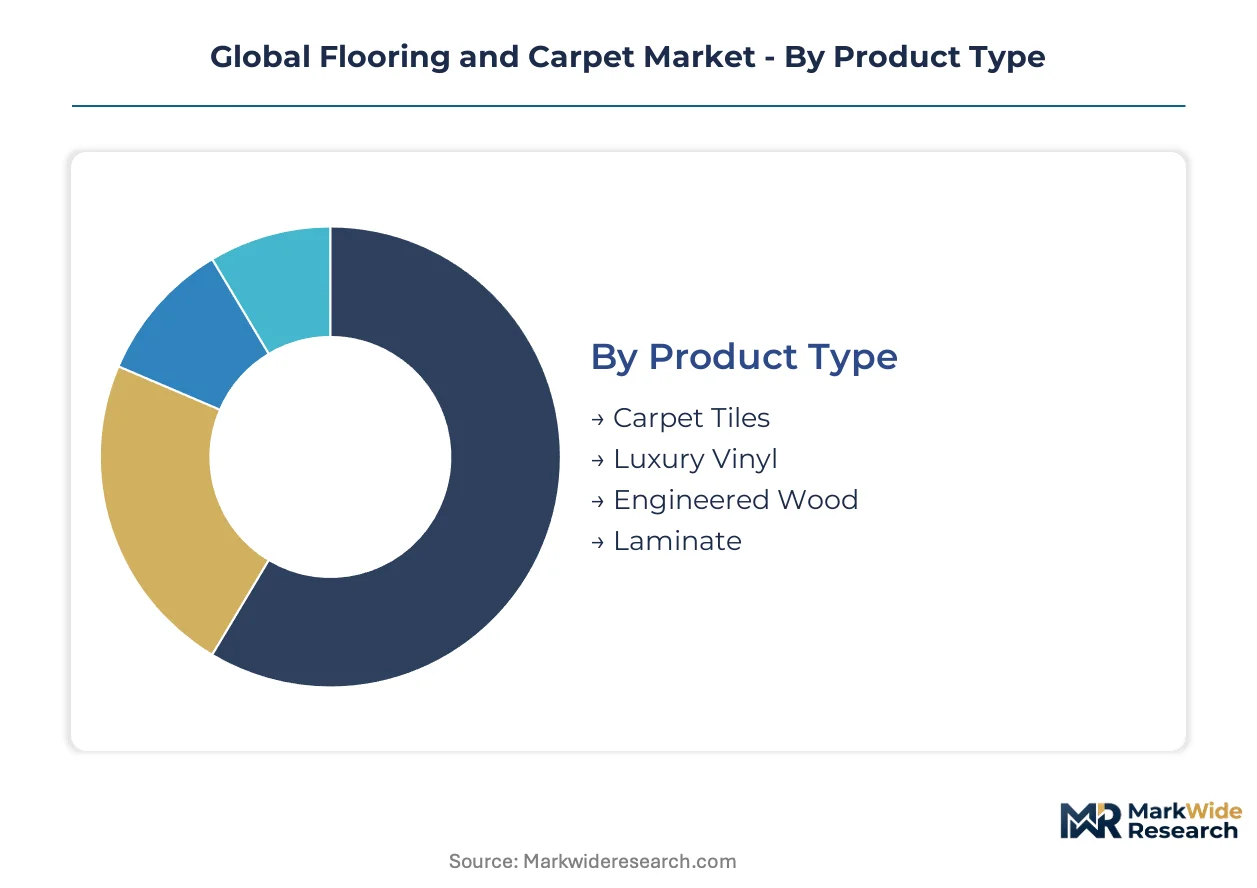
Specification behavior diverges sharply across substrate categories and installation methods in the Global Flooring and Carpet Market. Procurement teams segment decisions by wear-layer durability, acoustic performance, and circularity credentials rather than surface aesthetics alone.
Product Type:
Cost tier stratification determines margin architecture and capital intensity across substrate manufacturing.
- Carpet Tiles:Modular nylon or polypropylene face fibers bonded to PVC or bitumen backing enable zone-specific replacement in high-traffic corporate environments. Beijing, Shanghai, and Shenzhen office retrofit cycles compress specification windows for acoustic-rated systems with rapid-install backing technologies.
- Luxury Vinyl:Multi-layer polymer construction with mineral composite cores achieves dimensional stability and moisture resistance for healthcare and hospitality verticals. Germany and the Netherlands specify bio-plasticizer formulations ahead of REACH phthalate mandate deadlines.
- Engineered Wood:Cross-ply substrates with thick wear layers command premium residential specification where dimensional stability matters.
- Laminate:High-density fiberboard cores with melamine wear surfaces occupy economy residential tiers in volume markets.
Carpet tiles command the established base. The steepest expansion runs through luxury vinyl systems.
Installation Type:
Application context dictates labor cost structures and project timeline flexibility across built environments.
- Glue-Down:Permanent adhesive bonding delivers maximum dimensional stability for commercial roll goods and resilient sheet in healthcare corridors. United States hospitality renovation programs favor this method for durability in high-rolling-load zones despite extended cure times.
- Floating:Click-lock or loose-lay systems eliminate subfloor preparation costs and enable rapid tenant improvement cycles. China's tier-one commercial retrofit market specifies these for accelerated office turnover timelines.
- Staple:Traditional fastening for residential broadloom carpet over cushion in wood-framed construction.
- Nail-Down:Solid and engineered wood plank specification in high-end residential and heritage restoration contexts.
Glue-down methods retain commercial dominance. Floating systems are climbing the fastest in tenant-driven retrofit segments.
End User:
Customer type determines performance specification thresholds and procurement channel preferences.
- Residential:Renovation intensity in the United States and Germany sustains volume for premium engineered wood and luxury vinyl plank. Homeowner specification increasingly filters through direct-to-contractor digital platforms that compress traditional distributor markups.
- Commercial:Corporate real estate departments in the United Kingdom and United States unbundle material supply from installation, contracting certified installer networks directly through procurement platforms.
- Hospitality:Moisture resistance and rapid installation drive luxury vinyl specification in hotel renovation programs.
- Industrial:Load-bearing and chemical resistance requirements favor epoxy and polished concrete over traditional flooring substrates.
Residential anchors volume throughput. Commercial retrofits are gaining share fastest in specification value terms.
Material:
Supply concentration and petrochemical input volatility shape margin predictability across fiber categories.
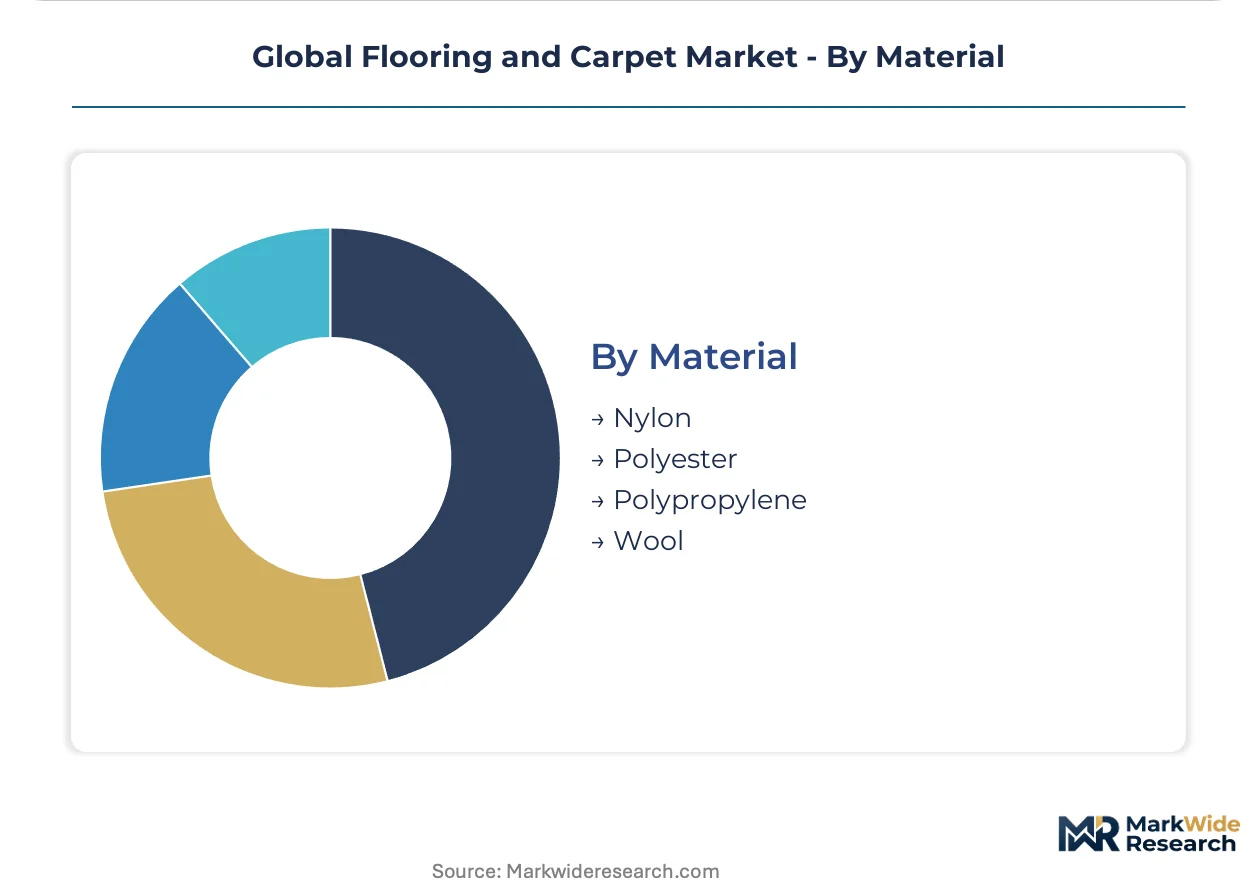
- Nylon:Solution-dyed variants deliver superior stain resistance and colorfastness for commercial carpet tile face fibers. Backward integration into caprolactam production insulates major suppliers from petrochemical price swings.
- Polyester:Post-consumer recycled content from PET bottle feedstocks meets EU Green Deal circularity thresholds for public-sector procurement in France and the Netherlands.
- Polypropylene:Olefin fibers resist moisture and chemical degradation in indoor-outdoor and basement applications.
- Wool:Natural fiber specification persists in premium residential and heritage commercial contexts where embodied-carbon credentials outweigh first-cost premiums.
Nylon holds the performance-premium position. Polyester is expanding most quickly on circularity-driven specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers extract premium pricing for low-emission substrates while Chinese suppliers compete on volume throughput in tier-one retrofit markets. This pricing-power asymmetry reflects divergent regulatory stringency and specification gatekeeping across transatlantic procurement workflows.
United States
Residential renovation intensity in Texas and Florida sustains volume pull for luxury vinyl plank and engineered wood systems. EPA formaldehyde emission standards for composite wood products elevate compliance costs for cross-border suppliers. Corporate real estate departments in New York and Chicago unbundle material supply from installation, contracting certified installer networks through direct digital platforms.
Germany
Public-sector procurement in Bavaria and North Rhine-Westphalia mandates ISO 14001 certification and Environmental Product Declarations as pre-qualification gates. REACH phthalate restrictions accelerate specification redirection toward bio-based polymer alternatives. The Stuttgart and Munich industrial clusters concentrate R&D investment in closed-loop manufacturing infrastructure ahead of EU Construction Products Regulation circularity mandates.
China
Beijing, Shanghai, and Shenzhen office stock turnover compresses replacement intervals for acoustic-rated carpet tile and rapid-install resilient systems. National dual carbon goals redirect specification decisions toward low-emission substrates in state-backed commercial retrofit programs. The Yangtze River Delta manufacturing base supplies captive polymer fiber production to insulate major producers from petrochemical price volatility.
Netherlands
Healthcare and education verticals in Amsterdam and Rotterdam embed chemical hazard screening into procurement workflows ahead of REACH mandate deadlines. EPD pre-qualification gates function as mandatory filters for municipal construction tenders. The Randstad logistics corridor enables rapid distribution of bio-plasticizer formulations to German and Belgian specification markets.
France
Post-consumer recycled content thresholds in public-sector flooring procurement concentrate demand in Île-de-France and Auvergne-Rhône-Alpes. EU Green Deal embodied-carbon benchmarks redirect specification toward polyester fiber systems from PET bottle feedstocks. Lyon-based manufacturing clusters develop regenerative material science capabilities to exceed industry circularity baselines.
Global Flooring and Carpet Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on fiber and resin supply. The vendor base organizes around three tiers: multinational surface-covering conglomerates with captive raw material production, mid-scale regional fabricators serving procurement platform channels, and niche specialists in regenerative or bio-based substrates. Competitive moves concentrate on backward integration into polymer production and digital platform partnerships that compress distributor intermediation.
Among US-based conglomerates, Mohawk Industries and Shaw Industries Group anchor the scale-driven tier with captive manufacturing footprints across multiple continents. Tarkett occupies a distinct position within the regenerative-material archetype, differentiating through post-consumer recycled content thresholds. These three exemplify how vertical control over fiber and resin supply insulates margin predictability amid petrochemical input volatility.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Tarkett |
| Interface |
| Beaulieu International Group |
| Milliken & Company |
| Forbo Management SA |
| Oriental Weavers |
| Gerflor |
| Others |
Supply Flow & Price Mechanics
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across the Global Flooring and Carpet Market. Crude oil benchmark swings compress margin predictability for manufacturers lacking captive polymer production while forcing buyers toward long-term offtake contracts that lock in volume discounts against spot-market exposure.
Pricing Analysis
Configured-to-order pricing for acoustic-rated carpet tile and rapid-install resilient systems commands 15-25% premiums over standard roll goods in corporate retrofit programs. Three-tier pricing structure across premium, standard, and economy levels segments by wear-layer thickness and certification grade—EPD-bearing products extract margin in German public procurement while economy laminate faces price erosion from Chinese volume imports. Pricing pressure stems from freight-driven cost compression in mineral substrate categories. Residential renovation buyers in Texas and Florida show highest price sensitivity; hospitality specifiers in New York and Chicago prioritize moisture resistance over first-cost optimization.
Supply Chain Analysis
Upstream caprolactam and vinyl resin production concentrates in China, Germany, and the United States. Nylon fiber draws from petrochemical feedstocks; engineered wood rests on cross-ply lumber cores; bio-plasticizer formulations hinge on agricultural derivative supply. Single-source vulnerability runs through Yangtze River Delta polymer production clusters exposed to dual carbon policy disruptions. Distribution runs through direct-to-contractor digital platforms that disintermediate traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Flooring and Carpet Market is entering a cyclical recovery phase anchored by commercial real estate retrofit cycles in tier-one Chinese cities and German public-sector procurement acceleration.
For Market Incumbents: Pre-empt margin compression from REACH phthalate compliance costs by accelerating backward integration into bio-plasticizer R&D and captive polymer fiber production. Secure ISO 14001 certification ahead of EU Construction Products Regulation circularity mandates to lock in pre-qualification status for Dutch and French municipal tenders. For New Entrants and Emerging Players: Establish a beachhead in China's tier-one commercial floating-floor retrofit segment where rapid-install systems face supply gaps against compressed project timelines. Target bio-based polymer alternatives for German healthcare and education verticals ahead of mandate deadlines; leverage procurement platform partnerships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: EU Construction Products Regulation revisions reshape the acquisition landscape by elevating closed-loop manufacturing infrastructure to strategic premium status. Five-to-ten-year viability favors targets with captive recycling capabilities and EPD-certified product portfolios. Monitor REACH enforcement acceleration as the signal for bio-based substitute demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Fiber Production | Captive caprolactam supply insulates Mohawk and Shaw from crude oil volatility. |
| EPD Certification Investment | Mandatory pre-qualification for Bavaria and North Rhine-Westphalia public tenders. |
| Digital Platform Partnership | Direct-to-contractor channels compress distributor markups in US residential renovation. |
| Bio-Plasticizer R&D Scale-Up | REACH phthalate restrictions redirect German healthcare specification toward alternatives. |
| Closed-Loop Manufacturing Infrastructure | EU circularity mandates force capital redeployment ahead of specification crystallization. |
Methodological Framework
Operator-level perspectives from facility managers, corporate real estate procurement leads, carpet tile specification consultants, and certified installer network coordinators anchored the qualitative base. Primary interviews triangulated against secondary sources including EPA formaldehyde emission filings, REACH substance restriction databases, EU Construction Products Regulation draft texts, and China dual carbon policy implementation guidelines. Bottom-up volume modeling from substrate-level production data converged with top-down spending estimates from commercial construction permit databases.
Scenario-bracketing around petrochemical price volatility bands and regulatory compliance timeline uncertainty shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include substrate category, installation method, end-user vertical, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation against historical replacement cycle data, with cross-validation against Chinese tier-one office stock turnover rates and German public-sector tender award patterns.
Stress conditions across crude oil benchmark swings, REACH enforcement acceleration, and EU circularity mandate implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on retrofit cycle intensity and specification gatekeeper behavior. Material shifts in EU Construction Products Regulation final text or China dual carbon policy enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Carpet Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market