
 Foam Flooring Products Market | 2026-2036
Foam Flooring Products Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Flooring Products Market Analytics
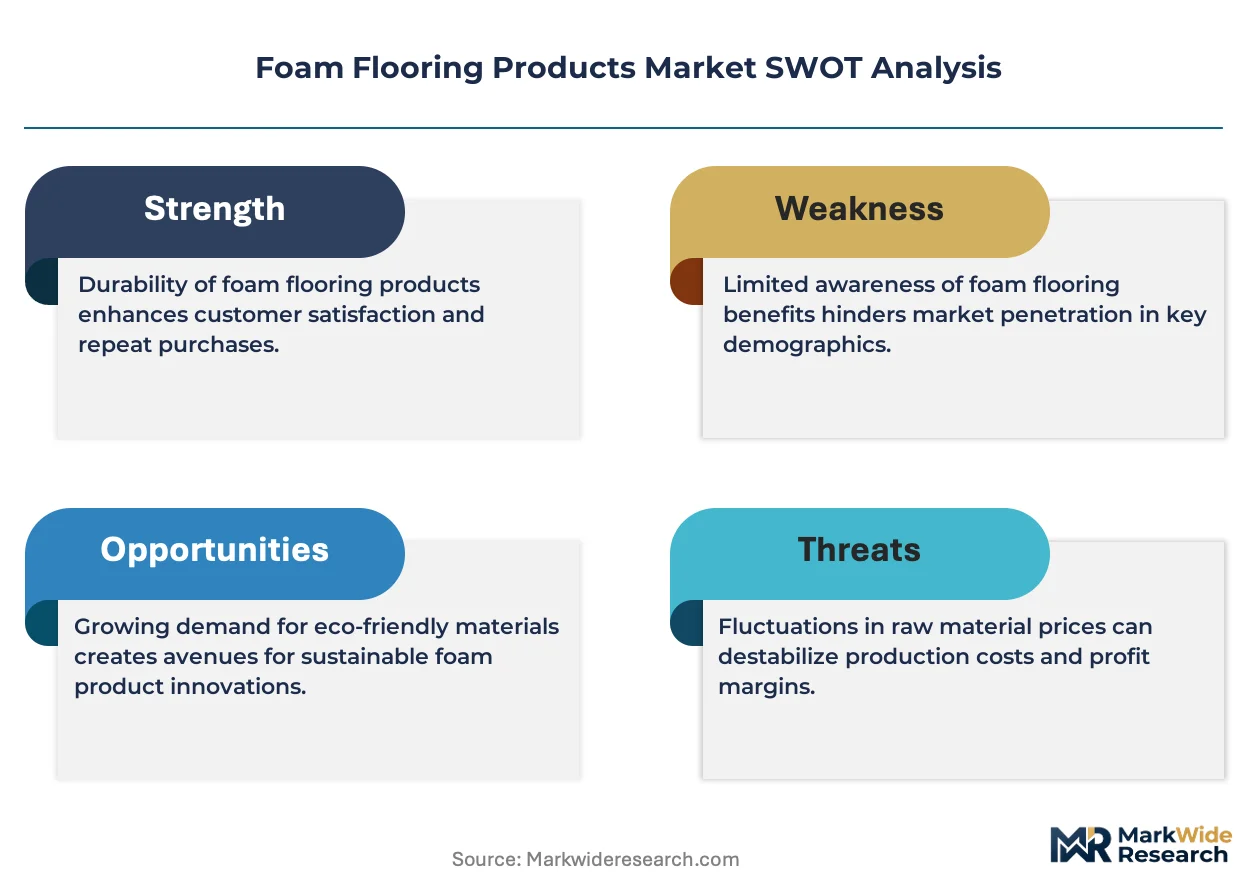
The capital-intensity divergence between integrated manufacturers and asset-light distributors is reorganizing competitive dynamics in foam flooring. Future Foam, Inc leverages captive resin sourcing to sustain margin stability across volatile petrochemical cycles. Rogue Fitness dominates direct-to-consumer channels in the home fitness segment. Greatmats anchors its position through specialized modular configurations for institutional buyers.
Foam flooring products encompass interlocking tiles, rolled sheets, and plank systems manufactured from expanded polymer substrates including ethylene-vinyl acetate (EVA), polyethylene (PE), and rubber compounds, typically engineered to densities between 45-120 kg/m³ for shock absorption and acoustic dampening in commercial and residential environments. Interlocking tiles command the largest revenue pool due to simplified installation protocols and replacement economics, while foam rolls capture the fastest expansion trajectory in temporary event flooring and rental applications. EVA formulations lead material demand for lightweight fitness applications, whereas rubber compounds retain premium positioning in heavy-load industrial zones where oil resistance and durability thresholds exceed polymer alternatives.
The EPA regulates volatile organic compound emissions from foam manufacturing facilities under Clean Air Act provisions, while OSHA mandates slip-resistance thresholds for commercial installations through walking-working surface standards. The EU REACH framework restricts phthalate plasticizer content in PVC-based flooring, redirecting formulation R&D toward bio-based alternatives. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York that will reshape end-of-life collection infrastructure and material recovery economics.
Market Dynamics
REACH compliance in the European Union is forcing wholesale reformulation of EVA-based foam flooring, redirecting R&D investment toward bio-based plasticizers and compressing margins for manufacturers dependent on legacy phthalate chemistries.
Growth Catalysts
- Home Fitness Infrastructure:Residential gym installations across the United States and Canada are pulling interlocking EVA tiles into basements and garages at volumes previously reserved for commercial channels.
- REACH Chemical Restrictions:The EU's tightening standards on phthalate content are accelerating certification-driven procurement among institutional buyers seeking future-proofed supply chains.
- Export Manufacturing Clusters:Production concentration in coastal Chinese provinces is driving unit cost reductions through scale economies in extrusion and die-cutting equipment.
Market Restraints
- Petrochemical Input Volatility:Ethylene and vinyl acetate monomer prices swing with crude oil indices, eroding margin predictability for non-integrated compounders.
- Geographic Supply Concentration:Dependence on Shandong and Zhejiang province manufacturers creates vulnerability to port congestion and regional power rationing.
- Performance Ceiling in Heavy-Load Zones:EVA density limitations below 120 kg/m³ exclude foam flooring from forklift traffic areas where rubber compounds dominate.
Strategic Opportunities
- Temporary Event Flooring:Rental and festival applications in Germany and France are expanding foam roll deployment for rapid-install, non-permanent surface needs.
- Bio-Based Formulation Mandates:The EU Green Deal's circular economy action plan is creating preferential procurement channels for flooring with certified recycled content.
- Direct-to-Consumer Channel Maturation:Specialized fitness retailers in the United States are bypassing traditional distribution to capture margin through private-label tile systems.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation expertise in non-phthalate plasticizers remains concentrated among a narrow cohort of European compound specialists.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of EPA VOC compliance, REACH registration, and state-level extended producer responsibility rules in California and New York stretches regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Flooring Products Market |
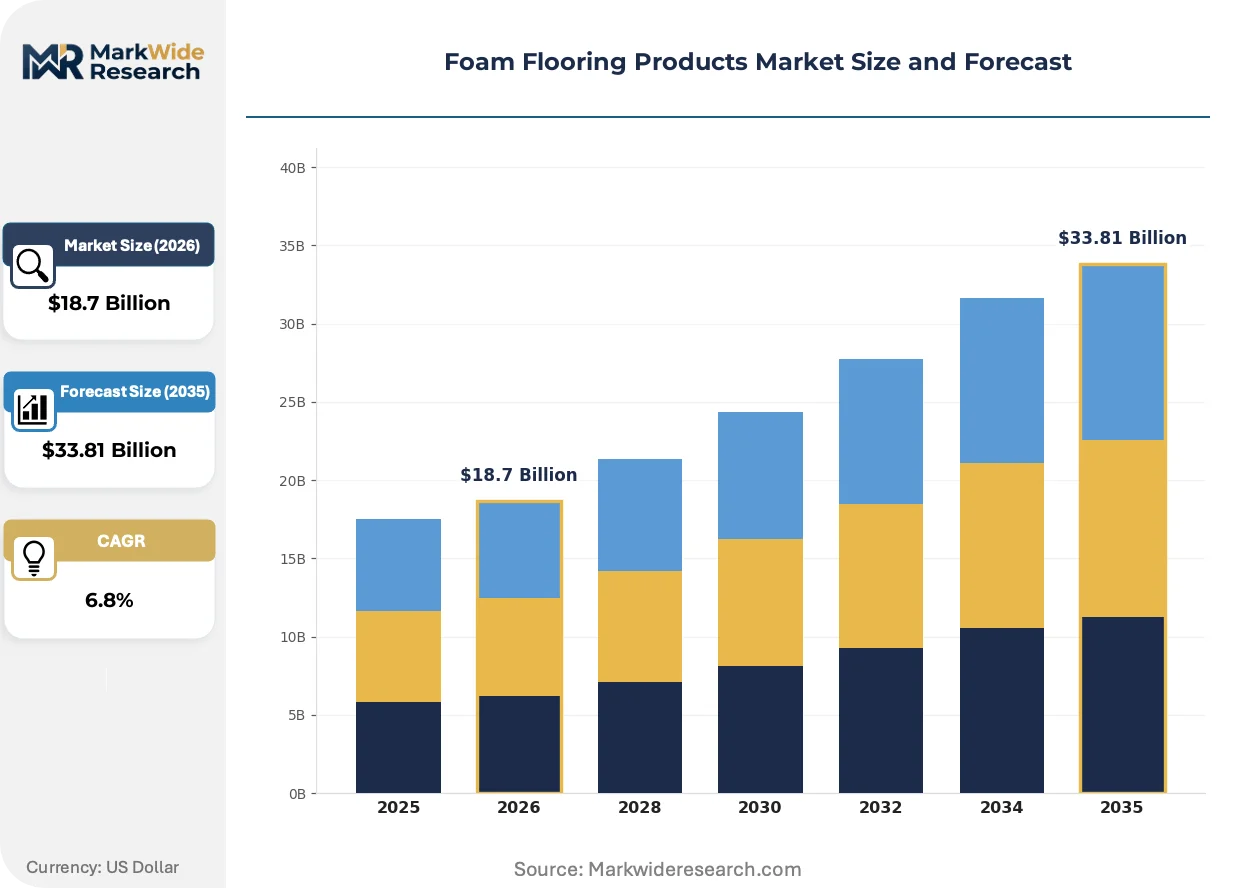
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interlocking Tiles, Foam Rolls, Planks, Square Mats Application: Fitness Centers, Play Areas, Dance Studios, Home Gyms Material: EVA, PE, Rubber, PVC End User: Commercial, Residential, Educational, Industrial |
| Companies Covered | Rubber Flooring Inc., Future Foam, Inc, Greatmats, Rogue Fitness, SeaDek, U.S. Rubber, 3M, Titan Brands, Flexco Floors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Flooring Products Market Evolving Landscape
Formulation chemistry and installation logistics are diverging sharply between permanent institutional specifications and transient residential deployments, splitting R&D priorities across incompatible performance profiles.
Thermoplastic polyurethane (TPU) foam substrates are supplanting conventional EVA in premium fitness studio installations where abrasion resistance and dimensional stability under cyclic loading determine replacement intervals. Boutique gym operators in metropolitan United States markets are specifying TPU-core interlocking systems at 40% price premiums to reduce five-year lifecycle costs. This material migration is compressing addressable volume for commodity EVA compounders while opening formulation partnerships with specialized elastomer suppliers.
The EPA's Clean Air Act enforcement on VOC emissions from foam manufacturing facilities is tightening throughput limits at extrusion plants in Ohio and Texas, forcing capital deployment into thermal oxidizer upgrades or facility relocation. Smaller compounders without captive resin sourcing are consolidating toll manufacturing relationships to share compliance burdens. California's pending extended producer responsibility legislation is accelerating design-for-recyclability investments among suppliers targeting municipal procurement channels.
Specification authority is migrating from facilities managers to procurement departments armed with total-cost-of-ownership models that weight installation speed, replacement modularity, and end-of-life recovery value. Institutional buyers in German healthcare and education sectors are unbundling flooring supply from installation service contracts, pressuring distributors to demonstrate standalone material value. This disintermediation is most visible in Nordic markets where public tender platforms mandate separated line-item pricing for product and labor components.
Foam Flooring Products Market Segmentation
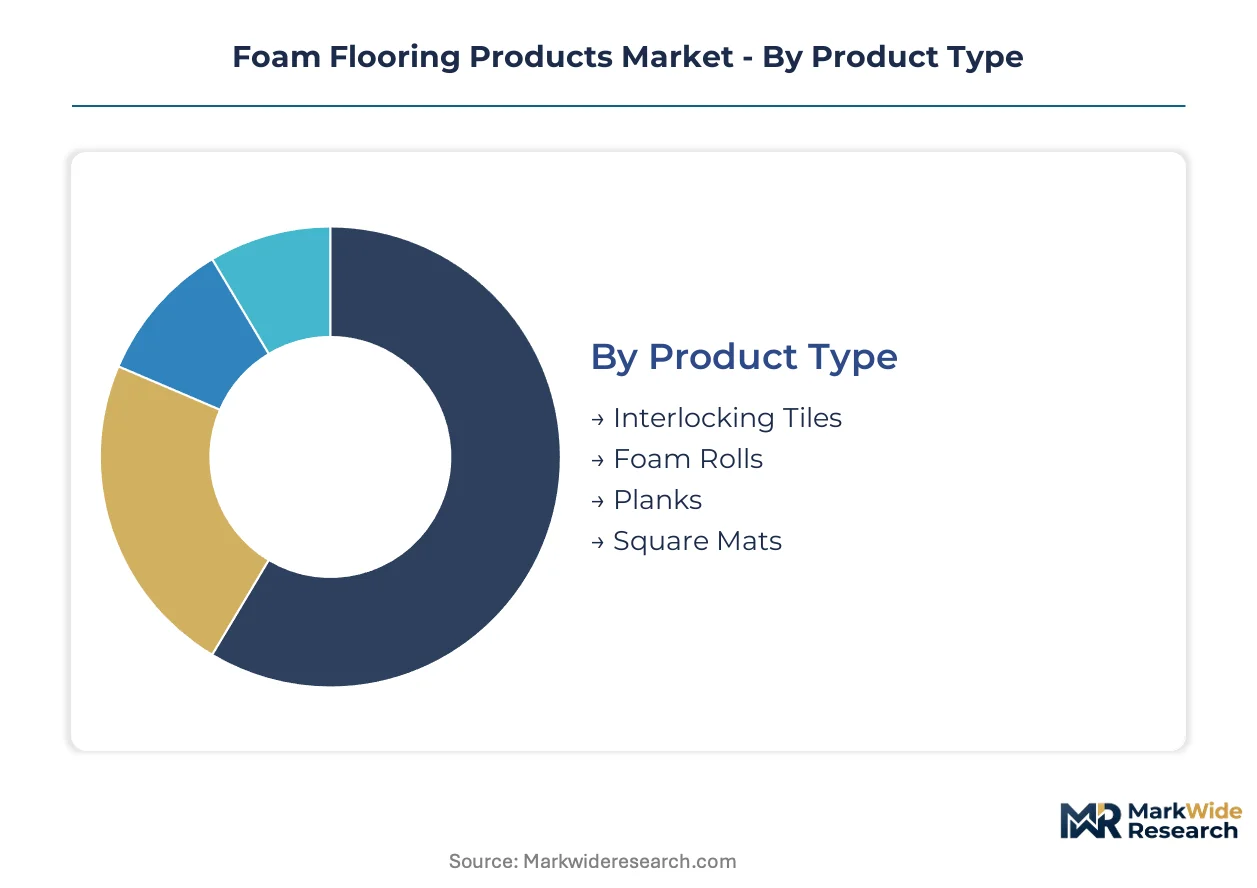
Channel mix varies sharply across foam flooring segments. Direct-to-consumer platforms dominate residential fitness purchases, while institutional buyers route through specialized distributors with installation capabilities.
Product Type:
Fitness specialty retailers and mass e-commerce platforms split volume by installation complexity and replacement economics.
- Interlocking Tiles:Modular EVA-based systems with puzzle-edge connections enable tool-free installation by end-users. Rogue Fitness and Amazon marketplace channels pull these into residential garages across the United States and Canada, driven by home gym buildouts requiring rapid deployment without contractor labor.
- Foam Rolls:Continuous extruded sheets in 4-6 foot widths serve temporary surface needs with minimal seam requirements. Festival rental operators in Germany and France specify rolls for rapid-install event flooring where same-day deployment and teardown compress labor budgets.
- Planks:Rectangular tongue-and-groove configurations mimic hardwood aesthetics for boutique studio environments.
- Square Mats:Fixed-dimension pads target martial arts dojos and gymnastics training centers requiring defined activity zones.
Interlocking tiles dominate installed base. Foam rolls are where expansion concentrates.
Application:
Facility type determines performance specifications, with load-bearing requirements and cleaning protocols driving material selection.
- Fitness Centers:High-traffic commercial gyms require abrasion-resistant TPU or dense rubber compounds under cyclic loading from free weights and cardio equipment. Boutique operators in metropolitan United States markets accept 40% price premiums for five-year lifecycle cost reduction.
- Home Gyms:Basements and garages pull lightweight EVA tiles through Amazon and Dick's Sporting Goods channels, with consumers prioritizing portability and moisture resistance over durability thresholds.
- Play Areas:Childcare facilities and municipal parks specify shock-absorbing surfaces for fall-height compliance.
- Dance Studios:Sprung floors with specific resiliency ratings protect performer joints during repetitive impact.
Fitness centers anchor commercial volume. Home gyms are climbing the fastest.
Material:
Petrochemical input exposure and regulatory compliance burdens stratify margin profiles across polymer categories.
- EVA:Ethylene-vinyl acetate copolymers at 45-120 kg/m³ densities dominate lightweight fitness applications. REACH phthalate restrictions are forcing European compounders toward bio-based plasticizer reformulations, compressing margins for legacy suppliers.
- Rubber:Natural and synthetic compounds retain premium positioning in forklift traffic zones and industrial settings where oil resistance and load-bearing capacity exceed EVA limitations.
- PE:Polyethylene substrates serve cost-sensitive temporary applications with lower durability requirements.
- PVC:Polyvinyl chloride formulations face declining institutional acceptance due to plasticizer toxicity concerns and end-of-life incineration restrictions.
EVA commands production volume. Rubber captures value concentration.
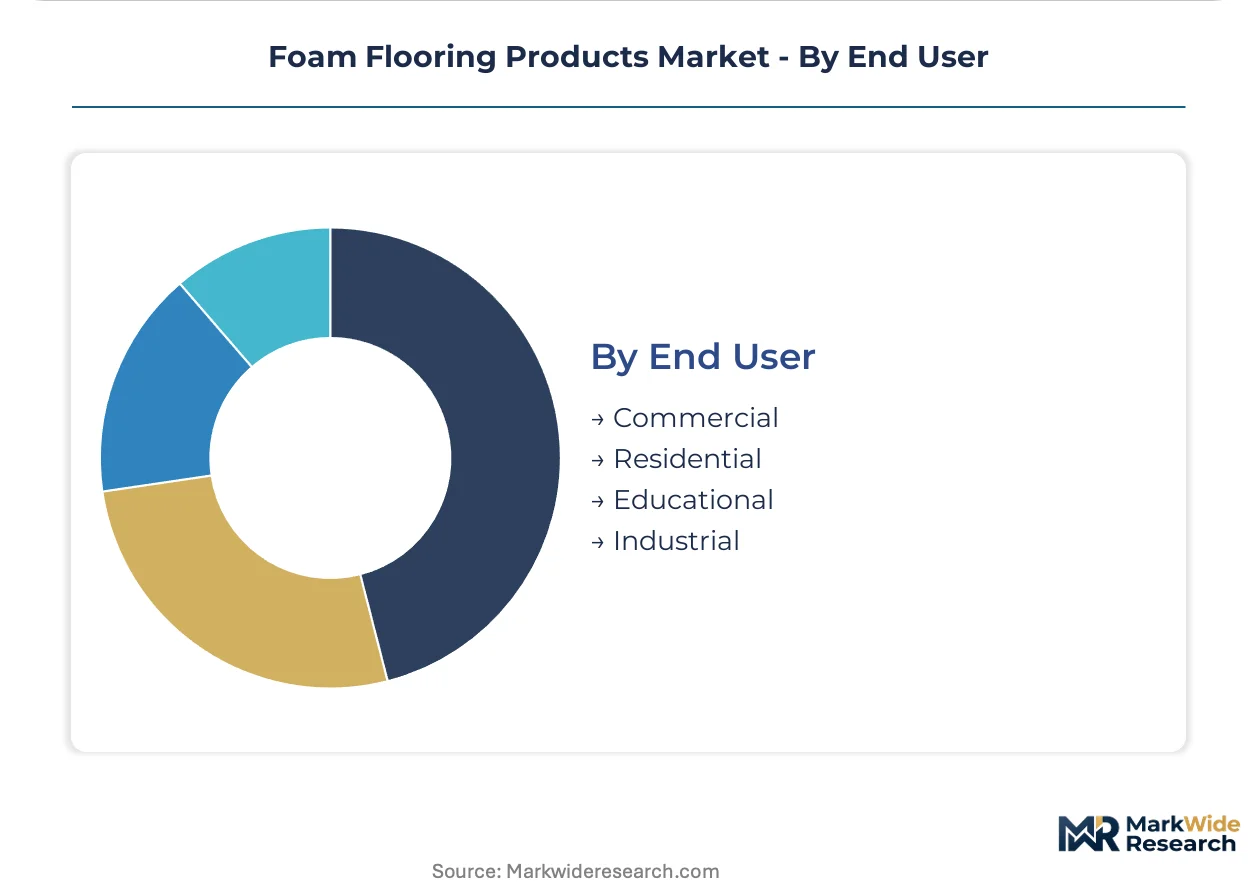
End User:
Procurement sophistication and total-cost-of-ownership modeling intensity separate institutional buyers from consumer segments.
- Commercial:Gym chains and hospitality operators unbundle product from installation contracts, pressuring distributors to demonstrate standalone material value through separated line-item pricing in German and Nordic public tenders.
- Residential:Individual consumers prioritize first-cost minimization and visual aesthetics over lifecycle durability, driving private-label tile systems through specialized fitness retailers.
- Educational:K-12 schools and universities specify modular replacement economics for high-wear common areas.
- Industrial:Manufacturing facilities require oil-resistant rubber compounds in maintenance bays and assembly zones.
Commercial buyers dictate specification standards. Residential channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing clusters dominate export supply, while the United States and Germany absorb premium volumes through divergent regulatory filters. Import dependence in fitness flooring runs through Shandong and Zhejiang province exporters serving North American home gym demand.
United States
Residential garage and basement conversions are pulling interlocking EVA tiles through Amazon and Dick's Sporting Goods channels at unprecedented velocity. The EPA enforces Clean Air Act VOC emission limits at extrusion facilities in Ohio and Texas, forcing capital into thermal oxidizer upgrades. Rogue Fitness anchors direct-to-consumer distribution from its Columbus, Ohio operational base.
Germany
Festival rental operators in Berlin and Munich specify foam rolls for rapid-install event flooring where same-day deployment compresses labor budgets. ECHA's REACH framework restricts phthalate plasticizer content, redirecting formulation R&D toward bio-based alternatives. The country's national chemical regulator maintains strict certification timelines for institutional procurement channels.
China
Coastal manufacturing provinces in Shandong and Zhejiang drive unit cost reductions through scale economies in extrusion and die-cutting equipment. The Ministry of Ecology and Environment enforces dual carbon goals that constrain energy-intensive foam production during regional power rationing periods. Qingdao-based compounders serve export-oriented fitness flooring demand.
Canada
Cold-climate moisture resistance requirements in basement installations favor EVA formulations with closed-cell density profiles. Health Canada regulates plasticizer migration limits in childcare facility flooring through national safety standards. Toronto and Vancouver metropolitan areas concentrate residential fitness infrastructure buildouts.
France
Boutique fitness studio operators in Paris and Lyon accept price premiums for TPU-core interlocking systems to reduce lifecycle replacement costs. The EU Green Deal's circular economy action plan creates preferential procurement channels for flooring with certified recycled content. Marseille logistics hubs facilitate Mediterranean distribution of rolled temporary event surfaces.
Foam Flooring Products Market Competitive Landscape
Concentration sits with integrated resin compounders and specialized fitness distributors rather than diversified flooring conglomerates. The vendor base stratifies across three tiers: captive resin producers sustaining margin stability through petrochemical cycle volatility, direct-to-consumer fitness specialists capturing residential gym demand, and institutional distributors unbundling product from installation services. Dominant competitive moves include backward integration into ethylene-vinyl acetate supply chains and geographic expansion through toll manufacturing partnerships to share regulatory compliance burdens.
Among North American fabricators, Future Foam, Inc exemplifies the integrated compounder archetype through captive resin sourcing capabilities. Rogue Fitness occupies a position within the direct-to-consumer specialist tier, while Greatmats represents institutional distribution expertise with modular configuration capabilities for specialized buyer segments.
| Leading Market Players |
|---|
| Rubber Flooring Inc. |
| Future Foam, Inc |
| Greatmats |
| Rogue Fitness |
| SeaDek |
| U.S. Rubber |
| 3M |
| Titan Brands |
| Flexco Floors |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Shandong compounders and North American fitness distributors lock in ethylene-vinyl acetate supply access while insulating buyers from petrochemical price swings. These contracts bundle volume commitments with REACH pre-certification, converting regulatory compliance into a pricing premium mechanism for institutional procurement channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with TPU-core systems commanding 40% premiums over commodity EVA tiles due to abrasion resistance certifications. Price differentiation hinges on density grade and California extended producer responsibility pre-compliance status. Cost compression in standard-grade EVA is intensifying because Shandong manufacturers are absorbing petrochemical volatility to maintain export share. Residential consumers through Amazon channels exhibit highest price sensitivity, while German healthcare facilities demonstrate lowest sensitivity due to total-cost-of-ownership procurement models.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for custom die-cut configurations, compressing to 3-4 weeks for standardized interlocking tiles from Zhejiang extrusion plants. Manufacturing concentrates in China, with secondary capacity in Ohio and Texas serving EPA-regulated domestic demand. Raw material flows draw from ethylene crackers along the US Gulf Coast, vinyl acetate monomer shipments from Singapore, and bio-based plasticizer trials from European compound specialists. Single-source vulnerability runs through Shandong port congestion during regional power rationing. Distribution feeds from Qingdao export hubs through Los Angeles and Rotterdam logistics nodes into direct-to-consumer and institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions are disrupting formulation economics faster than incumbent R&D cycles can absorb, creating asymmetric opportunity for agile compound specialists. The EU Green Deal's circular economy mandates are accelerating certification-driven procurement that favors pre-compliant supply chains.
For Market Incumbents: Secure captive resin sourcing or toll manufacturing partnerships in Ohio and Texas to buffer EPA thermal oxidizer compliance costs. Deepen backward integration into ethylene supply chains to defend margin stability against vinyl acetate monomer volatility. Prioritize bio-based plasticizer certification investments to preempt REACH-driven customer defection toward European compound specialists. For New Entrants and Emerging Players: Installation service unbundling in German and Nordic public tenders represents the most penetrable white-space, where facilities managers now demand separated line-item pricing. Target temporary event flooring rental operators in France and Germany with rapid-deploy foam roll configurations. Pursue direct-to-consumer private-label partnerships with Dick's Sporting Goods and specialized fitness retailers to bypass distributor margin capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated compounders with captive resin sourcing, where contract structures insulate cash flow from petrochemical cycles. Acquisition targets should display REACH pre-certification, Qingdao-based export infrastructure, and established toll manufacturing relationships. Watch for EU Green Deal procurement mandate acceleration as the inflection signal for bio-based formulation valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive resin sourcing insulates Future Foam from vinyl acetate monomer price volatility. |
| REACH Pre-Certification Investment | Bio-based plasticizer approval accelerates German healthcare procurement channel access. |
| Toll Manufacturing Partnership Expansion | Shared EPA thermal oxidizer compliance burdens enable smaller compounder market participation. |
| Direct-to-Consumer Channel Development | Rogue Fitness bypasses traditional distribution to capture residential garage gym margin. |
| Design-for-Recyclability R&D Program | California extended producer responsibility legislation creates preferential municipal procurement positioning. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Shandong and Zhejiang extrusion facilities, procurement leads at US fitness retailers, and regulatory affairs directors at European compounders; and secondary validation through USITC trade data, EPA Clean Air Act enforcement records, ECHA REACH registration databases, and SEC filings from integrated manufacturers. Bottom-up volume estimates from production capacity utilization rates were triangulated against top-down demand projections from home gym installation surveys and institutional procurement pipeline tracking.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, material formulation, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating petrochemical input price scenarios and certification timeline probabilities. Industry-specific forecast inputs included EVA density grade adoption rates, TPU substitution elasticity in boutique fitness studios, and extended producer responsibility legislation passage likelihoods in California and New York.
Underlying assumptions cover REACH enforcement continuity, dual carbon goal adherence in Chinese coastal provinces, and residential fitness infrastructure investment persistence, with deviation risk concentrated in vinyl acetate monomer supply disruptions and EPA thermal oxidizer retrofit delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Stone Flooring Market