
 Rigid Core Flooring Market | 2026-2036
Rigid Core Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Core Flooring Market Insights
Subscription-based floor monitoring and predictive maintenance software is hardening into a standard service layer bundled with premium rigid core installations. Mohawk Industries leverages its manufacturing scale to anchor North American supply chains for Stone Plastic Composite substrates. Shaw Industries sustains R&D intensity in click-lock engineering, while Tarkett competes through geographic diversification across European and Asian distribution networks.
Rigid core flooring denotes a multi-layer plank system comprising a stabilized polymer core—typically calcium carbonate-infused PVC or polymeric composite exceeding 4mm thickness—topped with a printed decorative film and wear-layer, engineered for dimensional stability under moisture exposure. The product serves commercial and residential environments requiring water resistance without subfloor preparation penalties. Stone Plastic Composite leads product type margins due to density and acoustic performance, while Luxury Vinyl Tile occupies the largest volume pool through retail channel penetration. Click Lock installation dominates residential retrofit demand, whereas Glue-Down methods prevail in healthcare facilities where rolling-load compliance is mandatory.
EPA TSCA Title VI governs formaldehyde emissions in composite core materials, compelling reformulation of Wood Plastic Composite variants toward NAF or ULEF resins. California Air Resources Board protocols extend beyond federal baselines, creating a bifurcated compliance landscape for U.S. manufacturers. REACH restrictions on phthalate plasticizers and EU Green Deal embodied-carbon thresholds reshape European import specifications. Stakeholders must monitor evolving state-level low-carbon procurement mandates and building retrofit incentives that will determine which core chemistries and installation formats capture institutional specification share.
Market Dynamics
California's Title 24 building efficiency standards and parallel codes in Germany and Australia are forcing core chemistry reformulations toward low-VOC, thermally efficient substrates, while residential renovation volumes in the United States concentrate demand around waterproof, dimensionally stable systems.
Growth Catalysts
- REACH restrictions on phthalate plasticizers:European import specifications are tightening, compelling manufacturers to accelerate bio-based plasticizer adoption and capture premium positioning in EU Green Deal-aligned procurement.
- Healthcare facility rolling-load compliance:Glue-down rigid core installations satisfy institutional durability requirements where traditional resilient flooring fails, expanding specification share in acute care and senior living construction.
- Residential retrofit activity:North American homeowners prioritize click-lock waterproof planks over site-finished hardwood, eliminating subfloor preparation costs and shortening project timelines.
Market Restraints
- Calcium carbonate supply concentration:S-PVC and SPC substrate production depends on high-purity mineral feedstocks concentrated in specific mining regions, exposing margins to bulk transport cost volatility.
- Wood Plastic Composite formaldehyde emissions:EPA TSCA Title VI compels reformulation toward NAF or ULEF resins, adding certification complexity and raw material substitution costs for WPC variants.
- Luxury Vinyl Tile substitution pressure:Thinner, lower-cost LVT competes for retail channel volume, compressing average selling prices in price-sensitive residential segments.
Strategic Opportunities
- Subscription-based floor monitoring services:Predictive maintenance software bundled with premium installations creates recurring revenue streams and locks in contractor-specifier relationships.
- EU Green Deal embodied-carbon thresholds:Low-carbon core chemistries qualify for public procurement preference and building retrofit incentives across European institutional markets.
- Acoustic performance differentiation:Stone Plastic Composite density advantages open specification in multi-family housing and hospitality verticals where IIC ratings determine code compliance.
Industry Challenges
- Click-lock engineering talent scarcity:Precision tolerancing for waterproof joint systems requires specialized polymer processing expertise that outpaces current vocational training pipeline output.
- Multi-jurisdiction certification timelines:CARB protocols extending beyond EPA baselines create bifurcated testing requirements that delay product launches and fragment inventory SKUs.
- Legacy flooring removal integration:Retrofit contractors face coordination complexity when existing asbestos-containing resilient floors trigger abatement protocols before rigid core installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Core Flooring Market |
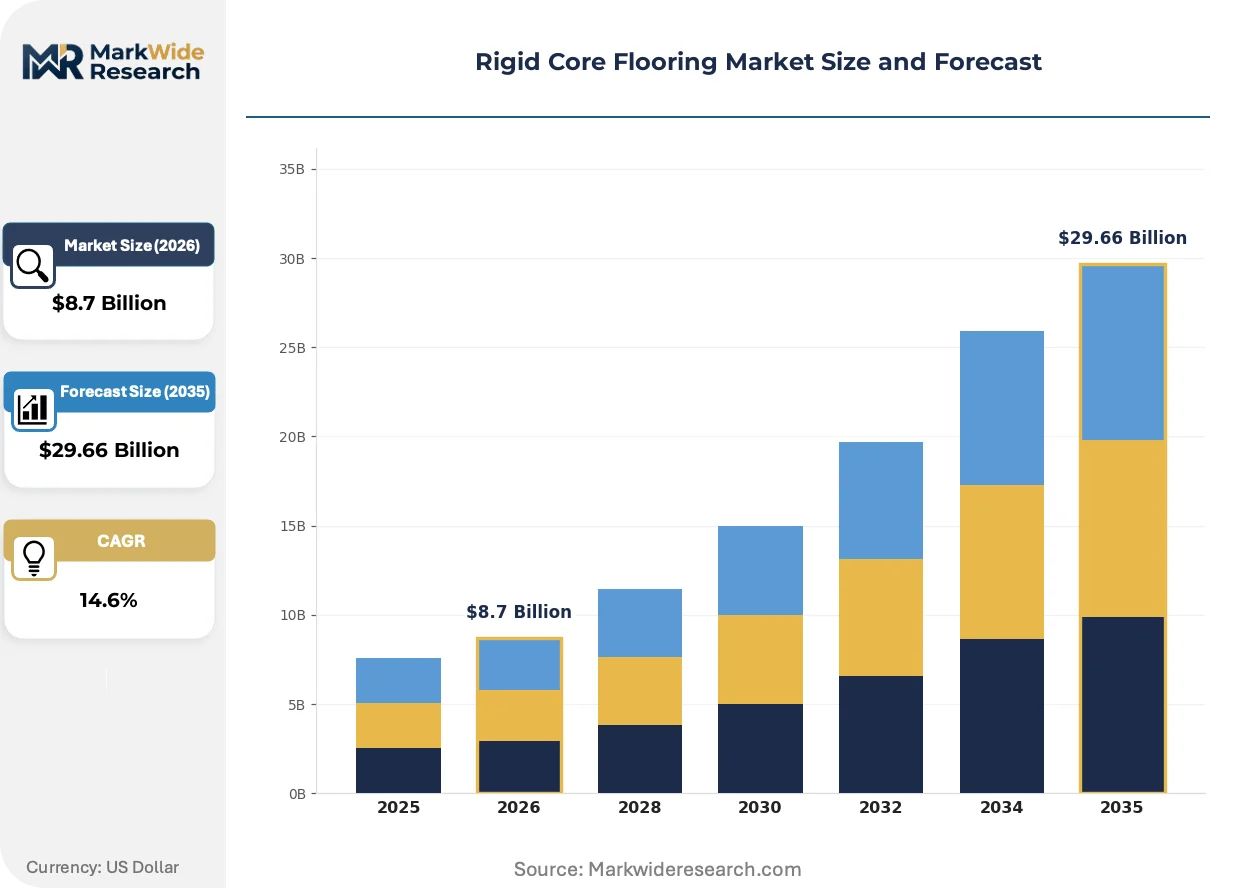
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Stone Plastic Composite, Wood Plastic Composite, Laminate, Engineered Vinyl Application: Commercial Spaces, Residential Homes, Educational Institutes, Healthcare Facilities, Hospitality Venues Installation Method: Floating, Glue-Down, Loose Lay, Click Lock End User: Property Developers, Interior Designers, Facilities Managers, Retailers |
| Companies Covered | Mohawk Industries, Armstrong Flooring, Mannington Mills, Shaw Industries, Tarkett, Gerflor, Forbo Holding, Interface, Novalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Core Flooring Market Trends and Innovations
Material science convergence with digital specification tools is compressing product development cycles and reshaping how architects and contractors evaluate substrate performance claims against code requirements.
Digital printing technology is integrating photorealistic wood and stone visual layers with registered embossing that matches texture to grain patterns. High-end residential developers and hospitality designers specify these enhanced-decor films for premium renovation projects. This capability is integrating aesthetic parity with natural materials into standard product tiers, collapsing the price-performance gap between engineered and authentic surfaces.
EU Green Deal embodied-carbon thresholds are tightening import specifications for polymer-intensive building products. European distributors now require Environmental Product Declarations and third-party verified carbon footprints for core substrates. German and French public procurement mandates are accelerating supplier transitions toward recycled-content PVC and bio-based stabilizer systems.
Building information modeling workflows are embedding flooring performance databases directly into architectural specification software. Design firms in the United States and Australia now filter products by thermal resistance, acoustic ratings, and VOC emissions before requesting samples. This behavioral shift concentrates volume with manufacturers who invest in structured data interoperability and certified attribute transparency.
Rigid Core Flooring Market Segmentation
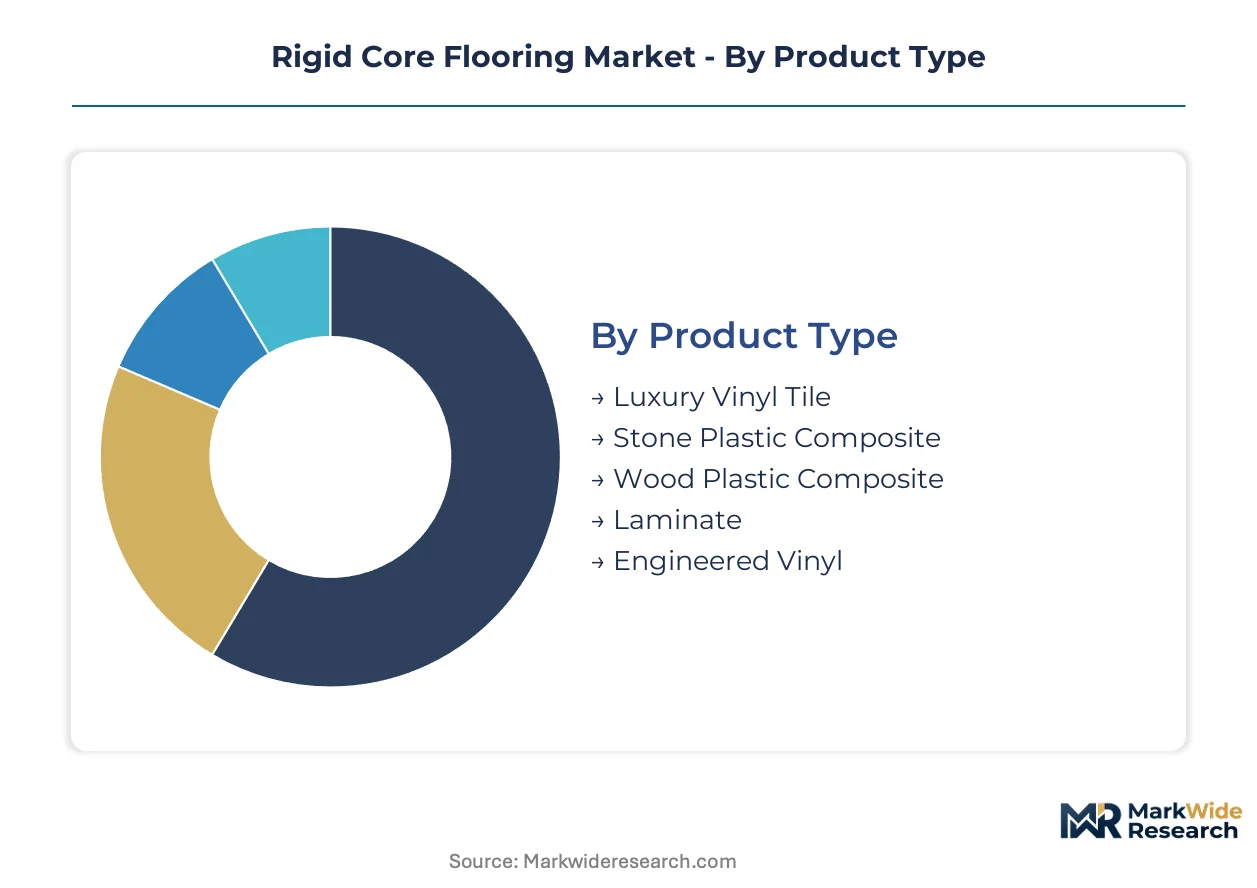
Segmentation in rigid core flooring reveals how capital deployment, specification requirements, and installation constraints fragment demand across substrate chemistries and end-use environments. Manufacturers optimize production lines and inventory positions by aligning core formulations with the performance thresholds demanded by specific building codes and facility types.
Product Type:
Capital intensity varies sharply across polymer core formulations, with mineral-loaded substrates demanding extrusion equipment capable of processing high filler loadings at precision tolerances.
- Stone Plastic Composite:Calcium carbonate-infused PVC cores exceeding 60% mineral content deliver density-driven dimensional stability and superior acoustic dampening. Multi-family housing developers in Germany and the United States specify SPC for IIC rating compliance in podium construction, though high-purity limestone feedstock concentration in specific mining regions exposes margins to bulk transport volatility.
- Luxury Vinyl Tile:Thinner polymer constructions without rigid mineral cores occupy the largest volume pool through mass retail channel penetration. Price-sensitive residential renovation segments in the United States favor LVT for budget-conscious waterproof flooring, compressing average selling prices against thicker rigid alternatives.
- Wood Plastic Composite:Cellulosic fiber-polymer composites require NAF or ULEF resin systems to satisfy EPA TSCA Title VI formaldehyde emission limits. Certification complexity and raw material substitution costs constrain WPC expansion in North American markets with stringent air quality protocols.
- Laminate:High-density fiberboard cores with melamine wear layers compete on visual authenticity at lower price points, though moisture susceptibility limits specification in wet-area applications.
- Engineered Vinyl:Multi-ply constructions combining polymer cores with enhanced wear layers target premium hospitality and healthcare segments requiring extended performance warranties.
Luxury Vinyl Tile absorbs the bulk of installed capacity; Stone Plastic Composite is expanding most quickly.
Application:
Performance specifications diverge across building types, with institutional environments demanding rolling-load compliance and acoustic ratings that residential retrofit contractors rarely encounter.
- Commercial Spaces:Office and retail fit-outs prioritize rapid installation turnaround and lease-term durability. Glue-down rigid core systems dominate Class A office renovations in the United States where tenant improvement allowances must stretch across large floorplates.
- Healthcare Facilities:Acute care and senior living construction mandate flooring that withstands rolling medical equipment and aggressive disinfection protocols. SPC and engineered vinyl cores with enhanced wear layers capture specification share where traditional resilient flooring fails under continuous sterilization cycles.
- Residential Homes:North American homeowners prioritize click-lock waterproof planks over site-finished hardwood, eliminating subfloor preparation costs and shortening project timelines for kitchen and basement renovations.
- Educational Institutes:K-12 and university construction balances first-cost constraints against 30-year lifecycle performance, with public procurement favoring products carrying Environmental Product Declarations.
- Hospitality Venues:Hotel renovation cycles demand rapid installation with minimal operational disruption, favoring floating systems that reduce guest room downtime during property refreshes.
Residential Homes commands the largest volume base; Healthcare Facilities is climbing the fastest as institutional construction prioritizes infection control and durability.
Installation Method:
Labor skill requirements and subfloor condition tolerance determine contractor preference across installation formats, with precision tolerancing for waterproof joint systems requiring specialized polymer processing expertise.
- Click Lock:Mechanically interlocking plank edges enable floating installation without adhesive, dominating residential retrofit demand where homeowners seek DIY-compatible renovation options.
- Glue-Down:Full-spread adhesive application satisfies healthcare facility rolling-load compliance where mechanical joints would fail under continuous equipment traffic.
- Floating:Interlocking systems installed over underlayment without subfloor attachment accelerate project timelines in commercial tenant improvements with tight occupancy schedules.
- Loose Lay:Friction-backed planks relying on perimeter anchoring suit temporary installations and exhibition spaces requiring rapid deployment and removal.
Click Lock captures the majority of residential volume; Glue-Down is gaining share fastest in institutional specification.
End User:
Procurement authority and specification influence vary across the value chain, with facilities managers increasingly embedding performance databases into long-term maintenance planning.
- Property Developers:Multi-project volume purchasers negotiate direct manufacturer relationships for master specification programs across residential and commercial portfolios.
- Facilities Managers:Healthcare and educational institutions leverage lifecycle cost modeling to justify premium core chemistries against extended replacement intervals.
- Interior Designers:Hospitality and high-end residential projects specify registered embossing and photorealistic decor films where aesthetic parity with natural materials drives selection.
- Retailers:Big-box and specialty flooring channels curate inventory depth based on regional renovation activity and local contractor preference for click-lock versus glue-down formats.
Property Developers concentrate the largest procurement volumes; Facilities Managers is expanding most quickly as predictive maintenance software locks in premium specification relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates rigid core flooring production capacity while the United States absorbs the largest consumption volumes through residential renovation channels. Germany and Australia impose stringent thermal efficiency codes that reshape material specifications. This production-consumption asymmetry drives cross-border trade flows and regional formulation adaptations.
United States
Residential retrofit contractors in California, Texas, and Florida drive click-lock waterproof plank demand as homeowners abandon site-finished hardwood. EPA TSCA Title VI governs formaldehyde emissions in composite cores, compelling WPC reformulation toward NAF resins. The Southeast manufacturing corridor—centered on Georgia and South Carolina—hosts extrusion facilities serving big-box retail distribution.
China
Property developers in Shanghai, Shenzhen, and Hangzhou specify SPC substrates for multi-family podium construction requiring acoustic dampening. The country's national building efficiency standards tighten thermal performance thresholds for flooring assemblies. The Yangtze River Delta manufacturing cluster supplies calcium carbonate-infused PVC cores to export markets across Asia-Pacific and North America.
Germany
Healthcare facility construction in Berlin, Munich, and Hamburg mandates glue-down rigid core systems for rolling-load compliance in acute care environments. REACH restrictions on phthalate plasticizers accelerate bio-based stabilizer adoption among domestic compounders. The North Rhine-Westphalia industrial belt concentrates polymer processing expertise for EU Green Deal-aligned procurement.
Australia
Commercial tenant improvement projects in Sydney and Melbourne prioritize rapid-install floating systems to minimize occupancy disruption. State-level building codes extend California Title 24 thermal efficiency standards to flooring specifications. The Melbourne manufacturing hub serves Oceania distribution networks with low-VOC core formulations.
Canada
Multi-family housing developers in Toronto and Vancouver specify SPC for IIC rating compliance in mid-rise wood-frame construction. Health Canada and PMRA protocols align with EPA emission baselines while permitting provincial low-carbon procurement incentives. The Ontario-Quebec corridor anchors North American supply chain integration for mineral-loaded substrate production.
Rigid Core Flooring Market Competitive Landscape
Capital-heavy producers compete with asset-light designers and specification aggregators across the rigid core flooring value chain. The vendor base organizes into three tiers: integrated polymer compounders controlling mineral feedstock sourcing, regional fabricators specializing in click-lock engineering, and brand licensors managing retail channel relationships. Consolidation pressures concentrate among mid-scale extrusion operators facing calcium carbonate transport cost volatility. Dominant competitive moves include backward integration into mineral sourcing and geographic expansion through distribution partnerships.
Among North American integrated manufacturers, Mohawk Industries, Shaw Industries, and Armstrong Flooring occupy positions defined by manufacturing scale and retail channel penetration. Mohawk anchors supply chain control through captive mineral processing capacity. Shaw exemplifies the R&D-intensive archetype with sustained investment in joint engineering precision. Armstrong represents the brand-licensing model with diversified installation-format portfolios. Tarkett and Gerflor anchor European competitive positioning through geographic diversification across EU and Asian specification networks.
| Leading Market Players |
|---|
| Mohawk Industries |
| Armstrong Flooring |
| Mannington Mills |
| Shaw Industries |
| Tarkett |
| Gerflor |
| Forbo Holding |
| Interface |
| Novalis |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compounders in Germany and China's Yangtze River Delta anchor upstream mineral processing capacity, translating captive limestone sourcing into pricing discipline that resists volatile calcium carbonate spot markets while forcing asset-light fabricators toward thinner-margin LVT alternatives.
Pricing Analysis
Margin tightening in economy-tier LVT reflects mass retail channel saturation and thinner substrate specifications that sacrifice acoustic performance for first-cost advantage. Three-tier pricing structure across premium SPC, standard WPC, and economy LVT levels stratifies by mineral loading density and certification grade, with CARB-compliant NAF resin systems commanding measurable premiums. Cost-down pressure on WPC variants accelerates because EPA TSCA Title VI compliance adds raw material substitution burdens. Residential retrofit contractors exhibit highest price sensitivity, whereas healthcare facilities managers prioritize rolling-load warranty coverage over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with high-purity calcium carbonate feedstocks concentrated in specific Chinese mining regions and select German limestone quarries. S-PVC and SPC substrate production draws from mineral-loaded polymer compounds, printed decorative films, and wear-layer coatings, with extrusion equipment capacity anchoring output scalability. Tariff exposure on Chinese-origin cores threatens margin stability for North American distributors dependent on trans-Pacific container routes. Distribution runs through big-box retail consolidation in the United States and specialized flooring distribution networks across Germany and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral-loaded polymer cores are displacing legacy laminate and site-finished hardwood in moisture-prone applications, compressing specification timelines and rewarding manufacturers with integrated compound-to-distribution control.
For Market Incumbents: Acquire captive limestone processing capacity in Germany or China's Jiangsu province to insulate margins from bulk transport volatility. Consolidate click-lock engineering talent through targeted recruitment from polymer processing vocational programs, defending against precision-tolerance scarcity that delays waterproof joint system launches. For New Entrants and Emerging Players: Enter via acoustic performance specialization for multi-family housing developers in Canada and Germany where IIC rating compliance mandates SPC density advantages. Target facilities managers in healthcare and senior living construction with predictive maintenance software bundles that lock in premium specification relationships and recurring revenue streams. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale extrusion operators with stranded calcium carbonate supply agreements in China's interior provinces, trading at compressed multiples during logistics cost spikes. Monitor EU Green Deal embodied-carbon threshold enforcement as the inflection signal determining which core chemistries qualify for public procurement preference across German and French institutional markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Captive limestone supply from Jiangsu or Sichuan provinces insulates SPC margins from bulk transport volatility. |
| Bio-Based Plasticizer Transition | REACH-compliant stabilizer systems unlock EU Green Deal-aligned procurement in German healthcare construction. |
| Predictive Maintenance Software Launch | Subscription bundles with premium installations lock in contractor-specifier relationships in North American retrofit markets. |
| Click-Lock Engineering Talent Acquisition | Precision polymer processing expertise addresses vocational pipeline gaps delaying waterproof joint system launches. |
| Environmental Product Declaration Certification | Third-party verified carbon footprints satisfy French and German public procurement mandates for institutional flooring. |
Research Methodology
Independent corroboration across flooring manufacturer R&D directors, calcium carbonate compounder procurement leads, and big-box retail category managers underwrites the qualitative findings. Primary fieldwork engaged polymer processing engineers, healthcare facilities managers specifying rolling-load systems, and residential retrofit contractors evaluating click-lock installation formats. Secondary validation drew from EPA TSCA Title VI compliance databases, CARB emission certification registries, EU ECHA REACH restriction updates, and customs trade flow records for mineral-loaded PVC substrates. Bottom-up volume estimates triangulated against top-down construction spending allocations across residential renovation and institutional build-out categories.
Comparable-period anchoring to historical residential retrofit cycles and healthcare construction permitting trends established baseline demand assumptions across the analysis window. Segmentation modeling incorporated core chemistry tier, installation method complexity, end-use environment durability requirements, and regional regulatory cluster stringency. CAGRs derived from fitted trend extrapolation adjusted for mineral feedstock cost trajectories and building code adoption timelines. Industry-specific inputs included calcium carbonate purity grade pricing indices and multi-family housing IIC rating compliance adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged logistics disruption or accelerated EU carbon border adjustment implementation. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity between SPC and WPC formulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market