
 Entrance Matting Market | 2026-2036
Entrance Matting Market Size, Share, and Industry Trends Forecast 2026-2036
Entrance Matting Market Intelligence
A shift from capital expenditure purchases to outsourced rental and maintenance services is realigning procurement patterns for commercial end users. Service-oriented providers like Cintas Corporation and UniFirst Corporation leverage this trend by offering comprehensive mat replacement and cleaning programs. In contrast, materials science leader 3M competes on product performance, focusing on proprietary scraper and water-retention technologies. Forbo specializes in integrated flooring solutions, including high-performance entrance systems for large commercial projects.
Entrance matting refers to specialized flooring systems placed at building entryways to trap dirt, moisture, and debris from foot traffic. These products are engineered with materials like nitrile rubber backing for durability and slip resistance, combined with face fibers such as nylon or polypropylene for scraping and absorption. The commercial buildings application continues to represent the largest share of consumption, driven by office and retail facility needs. Within product types, nylon mats offer superior appearance retention and durability, while rubber mats are essential for outdoor and high-moisture scraper applications.
Product specifications are heavily influenced by safety and accessibility mandates, such as the Americans with Disabilities Act (ADA) in the United States, which governs changes in level and slip resistance. In Europe, compliance with REACH regulations for chemical content and CE marking for fire safety are critical for market access. Consequently, manufacturers must balance material innovation for performance with a complex and diverging set of international compliance requirements.
Market Dynamics
The market's evolution is driven by the convergence of stringent accessibility mandates and a shift to service-based consumption. Regulations like the Americans with Disabilities Act (ADA) dictate product design, while commercial end users increasingly favor outsourced rental and maintenance programs.
Growth Catalysts
- Accessibility Mandates:Regulations like the US Americans with Disabilities Act (ADA) specify mat profiles and slip resistance, creating mandatory demand from commercial buildings.
- Hospitality Sector Growth:New hotel and resort construction requires high-performance matting to manage foot traffic and maintain cleanliness in high-visibility entrance areas.
- Commercial Real Estate Expansion:Development of office and retail facilities, particularly in China, directly translates to large-scale installations of entrance flooring systems.
Market Restraints
- Input Cost Volatility:Fluctuations in nitrile rubber prices, a key backing material, compress manufacturer margins and create pricing uncertainty for commercial buyers.
- Threat from Integrated Systems:Architects increasingly specify seamless flooring with built-in entrance functions, bypassing standalone mats in large commercial projects.
- Divergent Compliance Rules:Navigating conflicting standards like the US ADA for accessibility and Europe’s CE marking for fire safety increases design complexity and cost.
Strategic Opportunities
- Specialized Industrial Verticals:Developing mats with anti-static properties opens opportunities in data centers and electronics manufacturing, which require specialized flooring.
- Smart Mat Integration:Embedding sensors for footfall counting and moisture detection offers a new data-as-a-service model for facility managers in retail.
- Rental Model Expansion:Extending outsourced rental and cleaning programs into underpenetrated European commercial markets offers a path to stable, recurring revenue.
Industry Challenges
- Rental Service Logistics:Service providers face significant operational complexity in managing the reverse logistics of collecting, professionally laundering, and redistributing mats across a wide geographic client base.
- Chemical Compliance Burden:Adhering to evolving substance regulations, such as the EU's REACH framework, requires continuous material reformulation and testing, increasing R&D overhead and supply chain risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Entrance Matting Market |
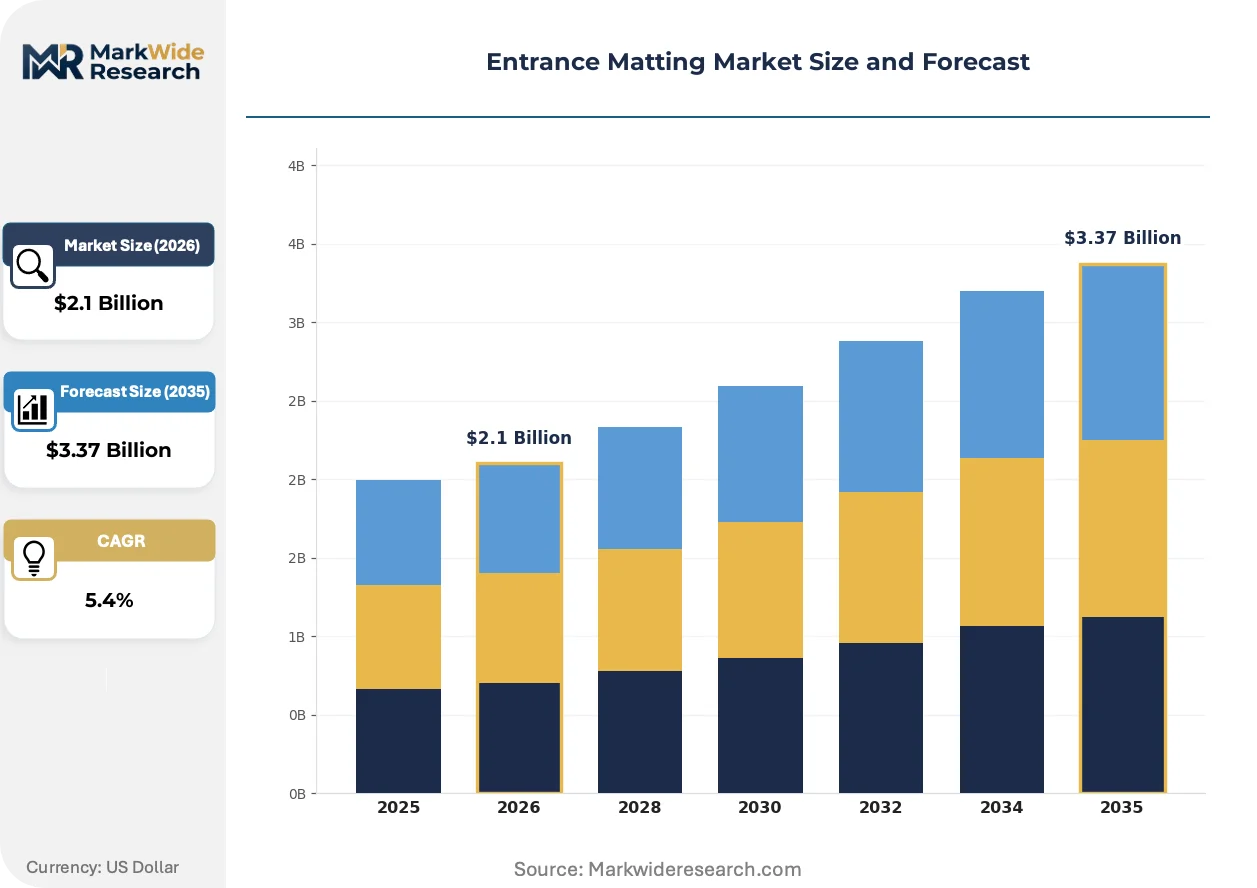
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Mats, Nylon Mats, Polypropylene Mats, Coir Mats, Carpet Mats Application: Commercial Buildings, Educational Institutions, Hospitality Venues, Healthcare Facilities, Transport Hubs Installation Type: Recessed, Surface Mounted, Frameless, Portable, Magnetic End User: Facility Management Companies, Property Developers, Retail Chains, Corporate Offices, Public Institutions |
| Companies Covered | 3M, Forbo, Cintas Corporation, Eagle Mat and Floor Products, NoTrax, UniFirst Corporation, Crown Matting Technologies, Bergo Flooring AB, Birrus Matting Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Entrance Matting Market Strategic Shifts & Innovations
Material science advancements and the demand for data-driven facility management are transforming entrance matting from a passive commodity into an active building system. Innovations focus on enhancing performance through proprietary materials and integrating digital functionalities to support operational efficiency.
Bi-level matting combines coarse scraping fibers with fine, absorbent fibers in a high-low pattern to trap debris and water. High-traffic facilities like airports and retail centers are standardizing on this technology for primary entrances. This design is decentralizing particle capture across a larger surface, improving containment and reducing cleaning cycles inside buildings.
The EU's Corporate Sustainability Reporting Directive (CSRD) elevates the importance of environmental product declarations. This regulation pressures manufacturers to provide data on recycled content, chemical safety, and end-of-life recyclability. Suppliers targeting European clients are now developing mats from recycled PET to meet new procurement criteria.
A move from capital purchases to full-service rental contracts is altering how commercial end users acquire matting. This subscription model, including cleaning and replacement, disrupts traditional distribution channels focused on one-time sales. The shift is most pronounced in North America's retail and healthcare sectors, which favor predictable service expenses.
Entrance Matting Market Segmentation
Understanding the diverse segments within the entrance matting market reveals distinct demand drivers and product specifications. This granular analysis identifies how material choices, installation methods, and end-user requirements shape product development. Manufacturers tailor solutions to specific application needs, optimizing performance for durability, safety, and aesthetic integration.
Product Type:
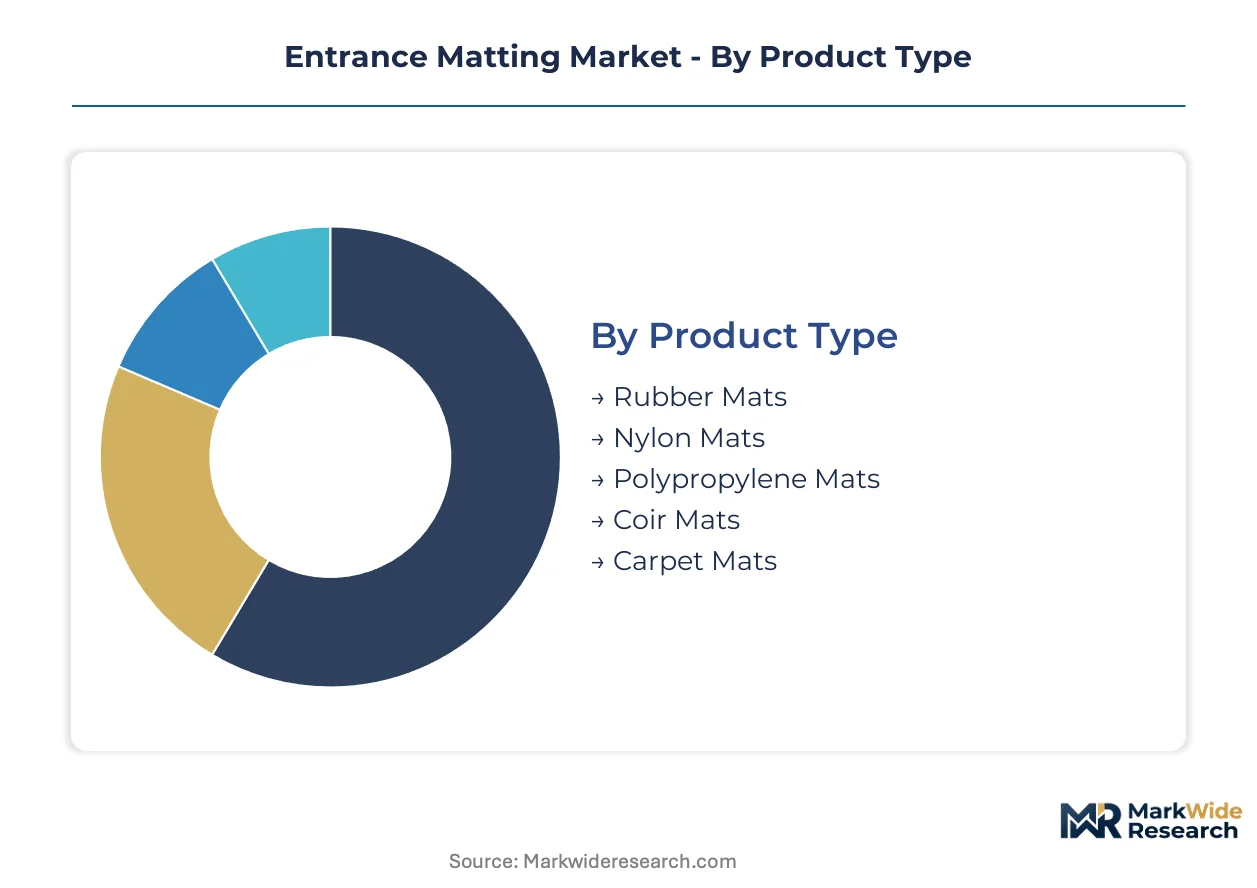
Buyers in the entrance matting market prioritize product type based on specific performance requirements for durability, moisture absorption, and scraping effectiveness.
- Nylon Mats:Nylon mats feature robust synthetic fibers with superior resilience and appearance retention, often backed with nitrile rubber. Demand concentrates in high-traffic commercial buildings and hospitality venues, driven by aesthetic appeal and moisture control.
- Rubber Mats:Rubber mats, from natural or synthetic compounds, provide exceptional durability, slip resistance, and weather resistance. Outdoor applications and industrial settings, such as manufacturing plants in Germany, widely adopt them for heavy-duty scraping.
- Polypropylene Mats:Polypropylene mats offer cost-effective solutions with good moisture absorption, suitable for moderate traffic areas.
- Coir Mats:Coir mats, from coconut husk fibers, provide excellent scraping action for coarse dirt, often used in residential entryways.
- Carpet Mats:Carpet mats integrate textile fibers for enhanced aesthetic appeal and moisture retention, found in office and retail environments.
Nylon Mats lead volumes today; Rubber Mats are gaining share fastest.
Application:
Volume consumption across entrance matting applications reflects varying foot traffic levels and specific functional requirements for cleanliness and safety.
- Commercial Buildings:Commercial buildings, including office spaces and retail outlets, require matting systems to manage high foot traffic and maintain interior cleanliness. Demand in expanding commercial real estate markets, such as China, drives significant market volume.
- Hospitality Venues:Hospitality venues, encompassing hotels, resorts, and restaurants, deploy entrance matting for aesthetic appeal, slip prevention, and moisture control. New construction projects in the United States increase demand for premium solutions.
- Educational Institutions:Educational institutions utilize durable matting to protect indoor flooring from dirt and moisture carried by student traffic.
- Healthcare Facilities:Healthcare facilities demand matting with anti-microbial properties and easy cleanability for hygienic environments.
- Transport Hubs:Transport hubs like airports require heavy-duty, bi-level matting to manage extreme footfall and severe debris.
Functional requirements for safety and cleanliness primarily dictate application-specific matting choices.
Installation Type:
Installation types often reflect cost tiers and architectural integration preferences, influencing project budgets and design aesthetics.
- Recessed:Recessed matting systems integrate into floor wells, providing a flush, seamless transition that minimizes tripping hazards. Large commercial projects in metropolitan areas like London favor these for permanent integration.
- Surface Mounted:Surface mounted mats are placed directly on existing flooring, with beveled edges to prevent tripping and allow easy repositioning. Retail chains and corporate offices in the US adopt them for flexibility and cost-effectiveness.
- Frameless:Frameless installations offer a minimalist look, cut precisely to fit an opening without a visible border.
- Portable:Portable mats provide temporary or flexible matting solutions, easily moved or stored, ideal for events or seasonal use.
- Magnetic:Magnetic matting systems use magnetic backing to secure mats to metallic floors, offering stability and easy removal.
Design preferences and functional integration drive matting installation type selection.
End User:
End users in the entrance matting market exhibit distinct procurement patterns and service expectations based on organizational structure and operational scale.
- Facility Management Companies:Facility management companies procure matting as part of broader service contracts, favoring rental and maintenance programs over capital purchases. This segment, active in North America, seeks predictable expenses and comprehensive replacement schedules.
- Retail Chains:Retail chains require durable and aesthetically pleasing matting for branding, slip prevention, and dirt control across numerous store locations. Large retail operations in the United States frequently integrate smart mat technology for footfall counting.
- Property Developers:Property developers specify matting during building construction, prioritizing durability and compliance with accessibility mandates like the US ADA.
- Corporate Offices:Corporate offices select matting for professional appearance, noise reduction, and employee safety, aligning with interior design schemes.
- Public Institutions:Public institutions, such as government buildings, demand high-performance, compliant matting solutions to manage heavy public traffic.
Procurement strategies and service integration define varying demands from different end-user types.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diverging regulatory frameworks across global markets create opportunities for manufacturing arbitrage, influencing where entrance matting products are designed and produced. Manufacturers often balance material innovation for performance with a complex set of international compliance requirements. This dynamic environment prompts strategic decisions regarding production location and market focus to optimize cost and market access.
China
Commercial real estate expansion and the robust hospitality sector fuel significant demand for entrance matting solutions in China. The country's GB standards influence product specifications for durability and safety in public and commercial spaces. Development in the Yangtze River Delta, encompassing cities like Shanghai, drives large-scale installations in new office towers and retail complexes.
United States
The hospitality sector's growth, particularly new hotel and resort construction, requires high-performance matting to manage heavy foot traffic in the United States. Compliance with the Americans with Disabilities Act (ADA) dictates specific mat profiles and slip resistance, creating mandatory demand for accessible products. The New York Metro area sees sustained demand from commercial buildings and high-end hospitality venues seeking premium entrance systems.
Germany
Germany's industrial settings and high-traffic commercial areas require durable and functional entrance matting solutions. Manufacturers must ensure compliance with CE marking for fire safety and REACH regulations for chemical content to access the market. North Rhine-Westphalia, a key manufacturing and logistics hub, exhibits strong demand for heavy-duty rubber mats in industrial facilities.
United Kingdom
New commercial office developments and expanding retail chains drive demand for aesthetic and functional entrance matting in the United Kingdom. Products must adhere to CE marking requirements, particularly for fire safety standards in public buildings. London's continuous commercial and hospitality project pipeline creates consistent demand for recessed and high-performance matting systems.
India
Rapid urbanization and the proliferation of new commercial and retail spaces contribute to the growing market for entrance matting in India. The Bureau of Indian Standards (BIS) sets general product quality and safety benchmarks, influencing local manufacturing practices. The Delhi-NCR region, a major commercial and retail hub, experiences significant volume consumption for both polypropylene and nylon mats.
Entrance Matting Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue specialized solutions and service-based models within the entrance matting market. The competitive landscape is characterized by a mix of material science innovators, integrated flooring solution providers, and service-oriented rental companies. Key strategic archetypes include product performance specialists, comprehensive service providers, and niche industrial solution developers. Companies frequently engage in portfolio diversification and strategic partnerships to broaden their market reach and solution offerings.
On the product performance vector, 3M exemplifies innovation through proprietary scraper and water-retention technologies, focusing on material science advancements for superior functionality. Forbo occupies a position as a specialist in integrated flooring solutions, providing high-performance entrance systems tailored for large commercial projects. Within the service-oriented segment, Cintas Corporation represents a major player, leveraging comprehensive mat replacement and cleaning programs that cater to the evolving procurement patterns of commercial end users.
| Leading Market Players |
|---|
| 3M |
| Forbo |
| Cintas Corporation |
| Eagle Mat and Floor Products |
| NoTrax |
| UniFirst Corporation |
| Crown Matting Technologies |
| Bergo Flooring AB |
| Birrus Matting Systems |
| Others |
Cost & Logistics Intelligence
Nitrile rubber price fluctuations directly impact manufacturing costs, pushing these expenses through to commercial buyers across various matting tiers. This volatility influences procurement decisions for facility managers and retail chains seeking predictable service expenses.
Pricing Analysis
Input cost volatility, particularly for nitrile rubber, directly influences the pricing of entrance matting solutions. Contract-based rental and maintenance programs offer commercial end users predictable service expenses, contrasting with transactional per-unit sales for capital purchases. Pricing differentiation stems from product performance features like proprietary scraper technology and material durability, such as nylon versus polypropylene fibers. Cost compression in the standard tier intensifies due to competition from cheaper alternatives. Facility management companies prioritize predictable service expenses, making them less price-sensitive for comprehensive rental models, while small businesses purchasing polypropylene mats often exhibit higher price sensitivity.
Supply Chain Analysis
Compliance with Europe’s REACH regulations for chemical content reshapes material sourcing, favoring suppliers capable of continuous reformulation and testing. Geographic supply concentration for finished goods is notable in China for high-volume commercial matting and Germany for specialized industrial rubber mats. The industry relies heavily on nitrile rubber for backing and various synthetic fibers for face materials. Input cost volatility for key raw materials, like nitrile rubber, presents a structural risk across the supply chain. Distribution runs through a dual model, combining direct sales for large integrated projects with service-oriented rental networks for recurring maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The entrance matting market acts as a regulatory compounder, with the Americans with Disabilities Act (ADA) in the United States driving mandatory demand for specific product designs. This regulatory push elevates performance standards and ensures market stability through compliance requirements.
For Market Incumbents: Deploy material science R&D to develop alternative backing materials, reducing reliance on volatile nitrile rubber pricing. Expand comprehensive rental and maintenance programs into underpenetrated European commercial markets, leveraging the shift from capital expenditure to service-based consumption. This strategy mitigates the threat from integrated flooring systems and reinforces compliance with evolving regulations like CE marking. Invest in advanced certification processes to meet diverging international compliance requirements.
For New Entrants and Emerging Players: E-commerce platforms offer a direct channel to reach facility managers seeking specialized solutions. Target specialized industrial verticals like data centers with anti-static mats, which present a clear white space. Integrating sensors for footfall counting and moisture detection creates a new data-as-a-service model, offering an innovative go-to-market angle for facility managers. The underpenetrated European commercial markets for rental services present a significant expansion opportunity.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional service providers face increasing operational complexity in managing reverse logistics. The market demonstrates long-term viability due to persistent regulatory mandates and the recurring revenue streams from rental contracts. Acquisition targets include niche technology providers developing smart mat solutions or regional service companies with established client bases. The adoption rate of bi-level matting in high-traffic facilities serves as a key signal to watch for broader market upgrading.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Diversification | Reduces reliance on volatile nitrile rubber, stabilizing production costs for manufacturers. |
| Smart Mat Integration | Captures new data-as-a-service revenue streams for retail facility managers. |
| Rental Service Expansion | Secures predictable, recurring revenue by addressing commercial end-user procurement shifts. |
| Advanced Certification | Ensures market access and compliance with diverging regulations like Europe’s REACH framework. |
| Bi-level Matting Standardization | Enhances particle containment and reduces internal cleaning cycles for high-traffic venues. |
Research Approach
Bottom-up commercial buildings and hospitality venues modeling reconciled against top-down matting manufacturers and service providers tracking forms the analytical core of this study. Primary interviews with product R&D directors, facility managers, and procurement specialists provided granular market insights. Secondary validation drew from government building codes like ADA, industry association reports, and corporate financial filings. This dual approach ensures robust data triangulation.
An input-output matrix frames the quantitative forecast, dissecting market dynamics across the analysis window. Segmentation dimensions included product type, application, installation method, and end-user categories, alongside material innovation trends. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key industry-specific forecast inputs included commercial real estate development pipelines and hospitality sector construction forecasts.
The model assumes a particular technology adoption path; alternative pathways for smart mat integration or bi-level matting would alter the outlook. Forecasts reflect current regulatory landscapes and anticipated input cost volatility. Unforeseen material science breakthroughs represent a specific risk factor. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market