
 India Carpets and Rugs Market | 2026-2036
India Carpets and Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
India Carpets and Rugs Market Foresight
India is tilting its carpet production capacity toward export-grade machine-made and tufted segments while preserving handmade heritage clusters. Obeetee Pvt. Ltd. leverages its Bhadohi-rooted artisan network to sustain premium hand-knotted output for international buyers. Jaipur Rugs Company anchors rural livelihood programs that feed decentralized weaving capacity into branded distribution. Welspun India Ltd competes through integrated polyester fiber-to-finished-rug operations at manufacturing scale.
Carpets and rugs are textile floor coverings constructed from pile yarns tufted, woven, or knotted onto primary backings with secondary latex or woven backing for dimensional stability, typically rated by face weight, pile height, and tuft bind strength for commercial traffic endurance. Their primary purpose spans acoustic dampening, thermal insulation, and interior spatial definition across built environments. Handmade and knotted categories occupy heritage premium positioning with elongated production cycles and artisan-dependent margin pools, while machine-made and tufted segments lead volume throughput through accelerated throughput and standardized specification. Wool and silk materials concentrate in luxury residential and hospitality specification, whereas polyester and cotton broaden accessibility across mass-market residential channels.
BIS, CDSCO-aligned textile safety protocols, and state-level handicraft development authorities shape product standards, chemical emission limits, and export certification pathways for Indian carpet manufacturers. The PLI scheme for textiles is channeling capital toward mechanized tufting and dyeing upgrades in designated carpet clusters. Stakeholders must monitor evolving EU REACH and US CPSC import compliance requirements alongside domestic BIS mark mandates to secure sustained market access across premium export corridors.
Market Dynamics
Machine-made tufting capacity expansion across Bhadohi-Mirzapur and Panipat clusters is compressing artisan-dependent lead times while BIS certification mandates force quality infrastructure upgrades. This dual pressure favors capitalized manufacturers capable of dual-track heritage and mechanized output.
Growth Catalysts
- PLI Scheme for Textiles:Capital subsidies for mechanized dyeing and tufting equipment accelerate capacity modernization in designated carpet clusters. Manufacturers accessing these incentives expand export-grade polyester and nylon rug output.
- Hospitality Procurement Expansion:Domestic hotel chains and international franchise operators specify Indian-made carpets for tier-2 and tier-3 property rollouts. This institutional demand stabilizes order pipelines for mid-scale tufted producers.
- EU REACH Alignment:Forward-integrated manufacturers investing in azo-free dye chemistry and formaldehyde emission controls secure sustained European market access. Compliance investments differentiate certified exporters from informal competitors.
Market Restraints
- Wool Input Volatility:Domestic wool supply constraints and import dependency on New Zealand and Australian fleece create margin pressure for hand-knotted segment producers. Price fluctuations compress artisan livelihood sustainability.
- Artisan Labor Concentration:Handmade carpet weaving skill pools concentrate in aging demographics across Uttar Pradesh rural belts. Succession gaps threaten heritage cluster output continuity without structured apprenticeship revival.
- Synthetic Fiber Substitution:Low-cost polypropylene and polyester machine-made alternatives displace cotton and jute flatweaves in mass residential channels. Material downgrading erodes traditional natural fiber market share.
Strategic Opportunities
- Kerala and Tamil Nadu Underpenetration:Southern Indian states exhibit low carpet consumption relative to northern markets. Targeted distribution partnerships with regional furniture retailers unlock latent residential demand.
- E-Commerce Direct Channels:Branded manufacturers bypass traditional export house intermediaries through proprietary digital storefronts. Direct consumer relationships capture margin pools previously allocated to trading layers.
- BIS Certification as Quality Signal:Mandatory textile floor covering standards create competitive moat for compliant domestic producers. Certified marks command specification preference in institutional and premium residential segments.
Industry Challenges
- Master Weaver Succession Crisis:Complex knotting techniques and design interpretation skills transfer inadequately to younger cohorts. Heritage cluster viability depends on structured skill documentation and incentive-aligned training programs.
- Capex Intensity for Compliance:BIS-mandated testing infrastructure and effluent treatment upgrades require substantial capital deployment. Small-scale weavers face exclusion from formal market channels without cooperative aggregation models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Carpets and Rugs Market |
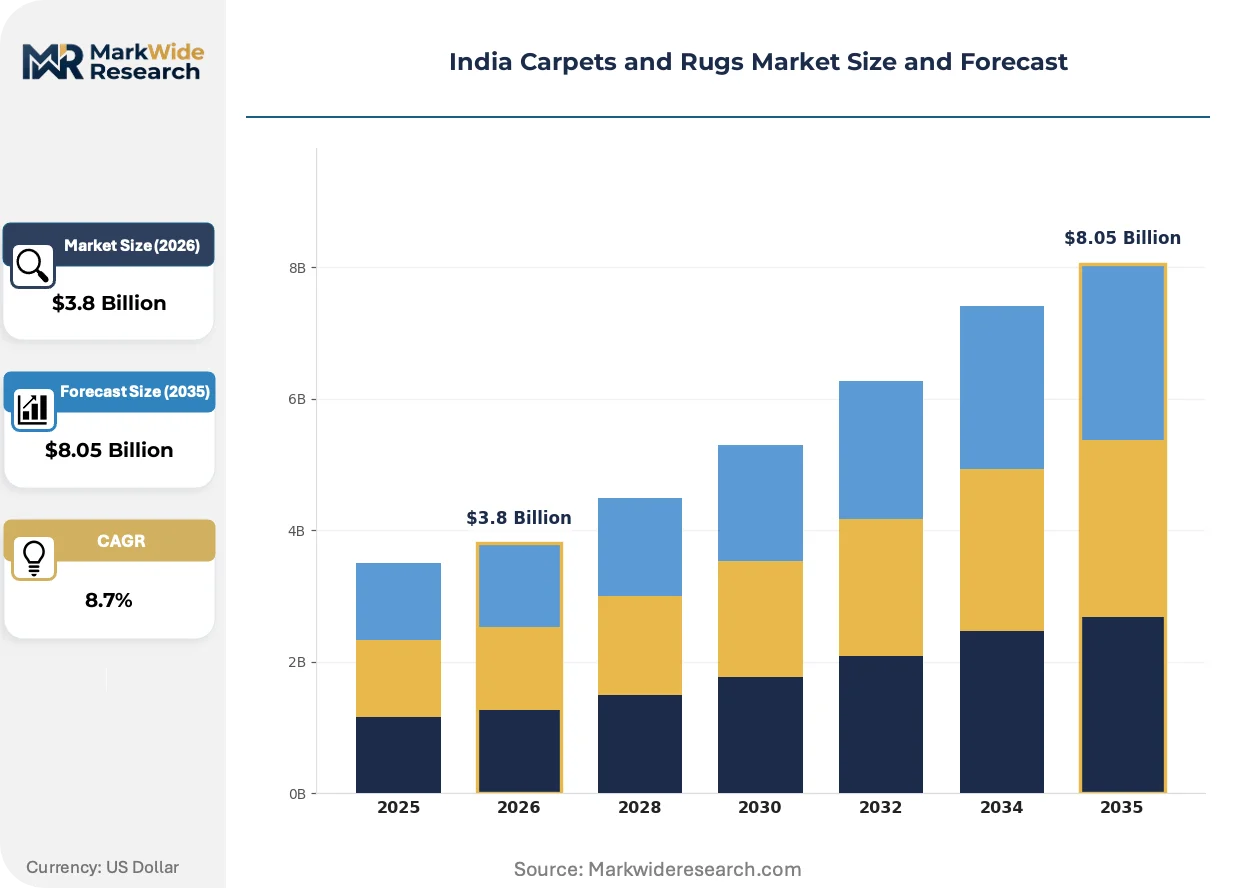
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handmade, Machine-Made, Tufted, Knotted Material: Wool, Silk, Cotton, Polyester End User: Residential, Commercial, Hospitality, Institutional Design Style: Traditional, Modern, Abstract, Geometric |
| Companies Covered | Obeetee Pvt. Ltd., Jaipur Rugs Company, Miras Carpet Industries, The Rug Republic, Vikram Carpets, Welspun India Ltd, Saraswati Global Pvt Ltd, YAK Carpet, Shahkar Rugs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Carpets and Rugs Market Shifts & Advancements
Digital design-to-loom workflows and automated color matching systems are compressing product development cycles. Regulatory chemical safety mandates and shifting procurement patterns toward certified sustainable sourcing complete the transformation vector.
Computer-aided design software paired with automated tufting control systems is digitizing pattern development and production specification transfer. Hospitality and commercial interior specifiers adopt these digitally validated samples for accelerated project timelines. The technology is digitizing traditional artisan-designer collaboration models while preserving design complexity at manufacturing scale.
BIS textile floor covering certification requirements are tightening formaldehyde emission limits and colorfastness benchmarks for domestic market access. Manufacturers must upgrade laboratory testing infrastructure and supply chain chemical documentation to maintain compliance. The hand-knotted heritage segment faces disproportionate adaptation burden given decentralized artisan production structures.
Institutional buyers now mandate EPDs and chain-of-custody documentation for hospitality and corporate fit-out specifications. Traditional spot-market purchasing through unverified intermediaries loses share to contracted supplier relationships with audit-ready sustainability credentials. Western European and North American import channels exhibit the strictest documentation requirements, filtering supplier eligibility.
India Carpets and Rugs Market Segmentation
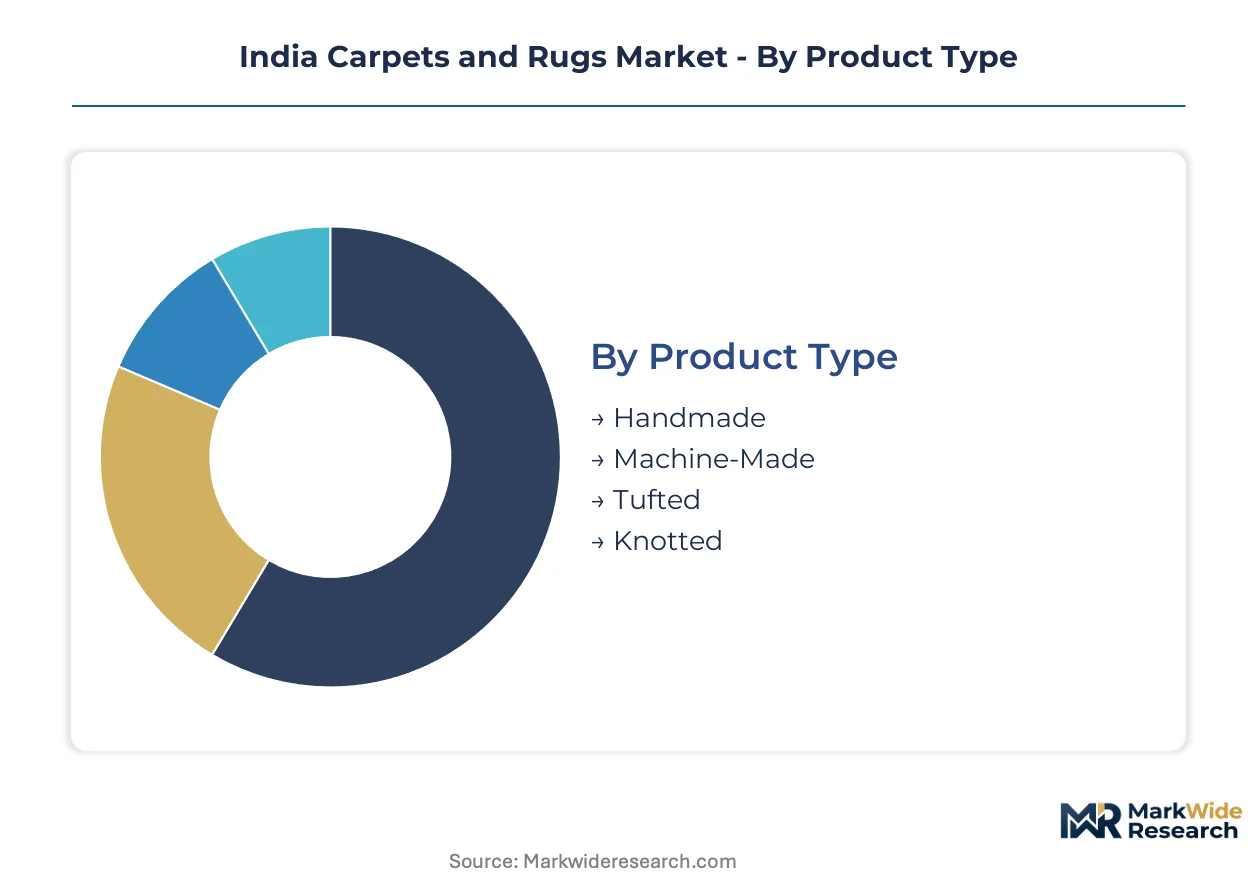
Segmentation reveals how India's carpet and rug manufacturers allocate capital between heritage artisan clusters and mechanized production corridors. Distinct material, end-use, and design preferences drive divergent margin structures and compliance requirements across the market.
Product Type:
After-sales service intensity varies sharply across production methods, with machine-made and tufted segments requiring warranty infrastructure while handmade categories depend on restoration specialist networks.
- Handmade:Artisan knotting and weaving techniques produce pile densities exceeding 100 knots per square inch for luxury residential specification. Demand concentrates in Uttar Pradesh's Bhadohi-Mirzapur belt where master weaver guilds supply heritage hospitality projects; BIS certification mandates now require formaldehyde testing that challenges decentralized cottage production.
- Machine-Made:Automated loom systems achieve throughput rates of 500+ square meters daily with standardized pile heights and tuft bind strengths. Panipat and Bhadohi mechanized clusters supply institutional procurement contracts for domestic hotel chains; PLI scheme subsidies accelerate polyester and nylon capacity expansion.
- Tufted:Primary backing fabrics receive yarn injection through multi-needle bar systems with latex secondary backing for dimensional stability.
- Knotted:Individual knot formation creates pile surface through Turkish or Persian knot density variations.
Machine-made holds the largest share; momentum sits with tufted segments gaining hospitality specification.
Material:
Cost tier stratification separates luxury natural fibers from mass-market synthetics, with wool and silk commanding 4-6x polyester price multiples.
- Wool:New Zealand and Australian merino fleece grades dominate premium hand-knotted production for export corridors. Supply volatility from import dependency compresses margins for Bhadohi heritage manufacturers; domestic procurement shortfalls force spot-market fleece purchases.
- Silk:Mulberry and tussah silk varieties enable 300+ knot density carpets with luminous pile surfaces. Karnataka and Tamil Nadu sericulture belts feed small-batch luxury production for Middle Eastern and East Asian export demand; raw silk price fluctuations track commodity exchange volatility.
- Cotton:Flatweave dhurrie traditions utilize indigenous short-staple varieties for breathable residential floor coverings.
- Polyester:Recycled PET fiber-to-yarn integration at Panipat complexes enables cost-competitive machine-made output.
Wool dominates value share; polyester climbs fastest on hospitality procurement volume.
End User:
Application requirements dictate performance specifications, with hospitality and institutional segments imposing fire-retardant and wear-classification standards absent in residential channels.
- Residential:Individual household procurement spans hand-knotted heirloom acquisitions to machine-made area rugs. Metropolitan Delhi-NCR and Mumbai markets concentrate premium demand; tier-2 city expansion drives polyester flatweave volume.
- Commercial:Corporate office fit-outs specify nylon and polypropylene broadloom with static-control backing. Bangalore and Hyderabad IT park developments anchor specification demand; BIS textile floor covering certification filters supplier eligibility.
- Hospitality:Hotel chains mandate EPD documentation and chain-of-custody verification for guest room and lobby installations.
- Institutional:Government and educational facilities prioritize cost-minimization through competitive bidding.
Residential maintains volume leadership; hospitality exhibits steepest expansion trajectory on tier-2 and tier-3 property rollouts.
Design Style:
Geography of demand correlates with aesthetic tradition, with export markets favoring classical motifs while domestic urban consumers shift contemporary.
- Traditional:Persian, Mughal, and Kashmiri floral medallion patterns sustain heritage cluster employment. European and North American import houses commission customized designs from Bhadohi master weavers; REACH-compliant dye chemistry adds 12-15% production cost burden.
- Modern:Minimalist palettes and open-field compositions align with Scandinavian and Japanese interior trends. Jaipur-based design studios digitize pattern libraries for accelerated sampling; e-commerce direct channels capture margin pools from trading intermediaries.
- Abstract:Non-representational color-field compositions target gallery and collector markets.
- Geometric:Repeating lattice and trellis patterns suit commercial specification standardization.
Traditional retains export value concentration; modern gains domestic share fastest on urban residential preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bhadohi-Mirzapur and Panipat clusters concentrate the majority of India's carpet manufacturing capacity, with Uttar Pradesh and Haryana states anchoring distinct production specializations across hand-knotted heritage and mechanized tufting segments.
Uttar Pradesh
Bhadohi-Mirzapur belt sustains the nation's densest artisan weaving concentration, with master weaver guilds supplying heritage hospitality projects and export-grade hand-knotted output. BIS certification mandates for textile floor coverings now require formaldehyde emission testing that challenges decentralized cottage production structures. Varanasi district clusters absorb dye chemistry upgrade costs to maintain European REACH compliance for wool carpet exports.
Haryana
Panipat mechanized tufting complexes supply institutional procurement contracts for domestic hotel chains and commercial fit-out specifications. PLI scheme capital subsidies accelerate polyester and nylon capacity expansion across integrated fiber-to-finished-rug operations. Ambala and Sonipat industrial zones concentrate automated loom systems achieving throughput rates exceeding 500 square meters daily.
Rajasthan
Jaipur-based design studios digitize pattern libraries for accelerated sampling and e-commerce direct channel distribution. State handicraft development authorities channel funding toward rural livelihood programs that feed decentralized weaving capacity into branded distribution networks. Jodhpur and Udaipur clusters specialize in wool and silk luxury residential specification for Middle Eastern export demand.
Jammu and Kashmir
Srinagar silk carpet weaving maintains 300+ knot density traditions for luminous pile surfaces targeting East Asian collector markets. Domestic wool supply constraints and raw silk price volatility compress margins for small-batch luxury producers. CDSCO-aligned textile safety protocols and export certification pathways require laboratory infrastructure investments beyond typical artisan cooperative scale.
Tamil Nadu
Sericulture belts around Coimbatore and Salem feed mulberry and tussah silk varieties to niche luxury carpet production. Southern Indian states exhibit low carpet consumption relative to northern markets, creating targeted distribution partnership opportunities with regional furniture retailers. State-level handicraft development authorities lack equivalent carpet-specific support infrastructure found in Uttar Pradesh and Rajasthan heritage clusters.
India Carpets and Rugs Market Competitive Landscape
Heritage-rooted artisan networks and integrated synthetic fiber manufacturers split the market across divergent margin structures and capital intensity profiles. Capitalized producers capable of dual-track heritage and mechanized output capture specification preference from hospitality procurement expansion. Strategic moves concentrate on BIS certification infrastructure deployment and PLI scheme subsidy access for dyeing and tufting equipment modernization.
Within the heritage-rooted tier, Obeetee Pvt. Ltd. and Jaipur Rugs Company exemplify distinct approaches to artisan network orchestration and rural livelihood program integration. Welspun India Ltd occupies a position among integrated synthetic fiber specialists leveraging captive polyester operations for cost-competitive machine-made output. These three anchors represent the strategic archetype spectrum spanning decentralized craft preservation, social enterprise distribution, and capital-intensive manufacturing scale.
| Leading Market Players |
|---|
| Obeetee Pvt. Ltd. |
| Jaipur Rugs Company |
| Miras Carpet Industries |
| The Rug Republic |
| Vikram Carpets |
| Welspun India Ltd |
| Saraswati Global Pvt Ltd |
| YAK Carpet |
| Shahkar Rugs |
| Others |
Supply & Pricing Matrix
Wool import dependency on New Zealand and Australian fleece determines both the premium-to-economy price spread and the geographic clustering of hand-knotted production around Bhadohi-Mirzapur. This raw material risk concentrates margin pressure on heritage manufacturers while driving mechanized polyester adoption in Panipat.
Pricing Analysis
BIS textile floor covering certification dictates the pricing tier structure across the Indian carpet market. Three-tier pricing structure across premium, standard, and economy levels separates BIS-marked hand-knotted wool carpets from uncertified cottage output and mass-market polyester machine-made alternatives. Price differentiation rests on certification grade and artisan knot density. Cost compression in the hand-knotted tier is intensifying because import fleece volatility and REACH-compliant dye chemistry add production burden. Institutional hospitality buyers exhibit the least price sensitivity, while mass residential channels in tier-2 cities drive polyester volume through acute cost consciousness.
Supply Chain Analysis
Single-source vulnerability in New Zealand and Australian wool imports dominates supply chain risk architecture for heritage manufacturers. Geographic supply concentration centers on India, New Zealand, and Australia for wool fleece, with China and India anchoring polyester fiber production. Raw material dependencies include merino wool grades, mulberry silk from Karnataka, and recycled PET feedstock. Distribution runs through export house intermediaries for European and North American corridors, while domestic channels increasingly shift toward direct e-commerce storefronts and regional furniture retailer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's carpet market is recovering from pandemic-induced hospitality procurement contraction, with tier-2 and tier-3 hotel property rollouts now anchoring cyclical demand restoration.
For Market Incumbents: Entrench BIS certification infrastructure as a competitive moat against informal cottage competitors. Deploy capital subsidies from the PLI scheme for textiles toward mechanized dyeing and tufting equipment in Panipat and Bhadohi clusters. Acquire distressed artisan cooperatives facing succession crises to consolidate heritage output capacity. For New Entrants and Emerging Players: Establish a beachhead in Tamil Nadu and Kerala underpenetrated residential markets through distribution partnerships with regional furniture retailers. Target the machine-made polyester hospitality specification segment where PLI subsidies compress capital barriers. Pursue direct-to-consumer digital channels to bypass entrenched export house intermediaries and capture margin pools. For Investors and Strategic Acquirers: Capital-efficient design studios with proprietary pattern libraries and e-commerce infrastructure represent the optimal acquisition target archetype. Long-term viability hinges on the ability to serve both heritage hand-knotted export demand and mechanized hospitality procurement simultaneously. Watch PLI scheme subsidy allocation rates as the inflection indicator for synthetic fiber capacity expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Infrastructure Deployment | Mandatory formaldehyde testing and colorfastness benchmarks create regulatory moats for compliant manufacturers. |
| PLI Scheme Equipment Modernization | Capital subsidies accelerate polyester and nylon tufting capacity expansion in designated carpet clusters. |
| Direct-to-Consumer Channel Launch | Proprietary digital storefronts capture margin pools previously allocated to export house intermediaries. |
| Artisan Cooperative Acquisition | Consolidation of distressed heritage weaving capacity addresses master weaver succession gaps. |
| Southern India Distribution Partnership | Tamil Nadu and Kerala furniture retailer alliances unlock latent residential demand in underpenetrated markets. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Master weavers, hospitality procurement managers at domestic hotel chains, textile chemical suppliers, and PLI scheme administrative officers provided operational perspective. Secondary sources include BIS certification records, CDSCO textile safety protocols, DGFT export statistics, and state-level handicraft development authority disbursement data. Bottom-up cluster capacity assessments triangulate against top-down trade flow analysis.
Calibration against historical production volume and export value trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions encompass production method, material grade, end-use application, and regional production cluster. CAGRs derive from slope analysis of normalized capacity utilization and procurement contract pipeline data. Forecast inputs include PLI subsidy allocation velocity and REACH compliance cost trajectories for dye chemistry.
Macroeconomic conditions sit as an overlay; deviation in rupee-denominated wool import costs or European hospitality construction cycles would shift the trajectory. Forecasts reflect documented assumptions regarding artisan labor pool stability and certification mandate enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market