
 China Laminate Flooring Market | 2026-2036
China Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
China Laminate Flooring Market Outlook
Buyer concentration among large-scale property developers is decoupling from traditional distributor networks as state-backed housing conglomerates centralize flooring procurement through direct mill contracts. Power Dekor leverages its captive resin-pressing capacity to secure volume commitments from these consolidated buyers. Yangzi Floor sustains dominance in Jiangsu province through vertically integrated substrate production. Chinafloors competes on export-grade certification breadth, serving OEM channels into Southeast Asian retail.
Laminate flooring comprises a multi-layer composite surface material built from a high-density fiberboard core, decorative paper impregnated with melamine resin, and a transparent aluminum oxide wear layer, engineered to simulate hardwood or stone aesthetics at lower installed cost. Water-resistant laminate variants command widening specification in coastal residential projects where humidity degradation risks persist. Click-lock installation systems anchor commercial retrofit demand by reducing labor hours and subfloor preparation requirements. Twelve-millimeter thickness grades occupy the premium residential segment where acoustic performance and underfoot stability drive specification.
China's national standards body administers GB/T 18102 for laminate flooring wear classification and formaldehyde release limits, while the Ministry of Ecology and Environment enforces MEE air-quality mandates affecting panel adhesive chemistry. MIIT industrial policy directives incentivize automated pressing line upgrades that reduce energy intensity per square meter produced. Stakeholders must monitor evolving GB standard revision cycles and provincial environmental enforcement intensity to anticipate compliance cost shifts and certification barrier changes.
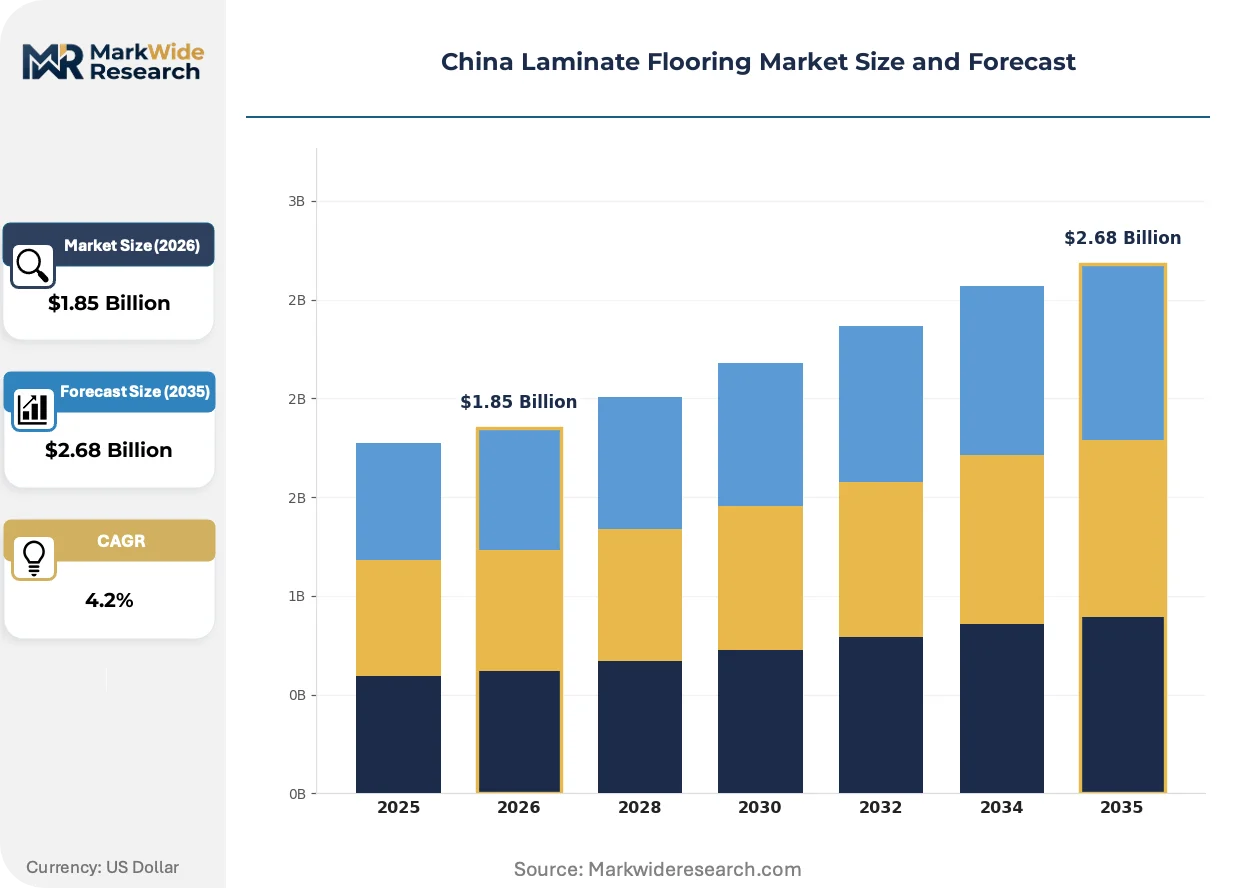
Market Dynamics
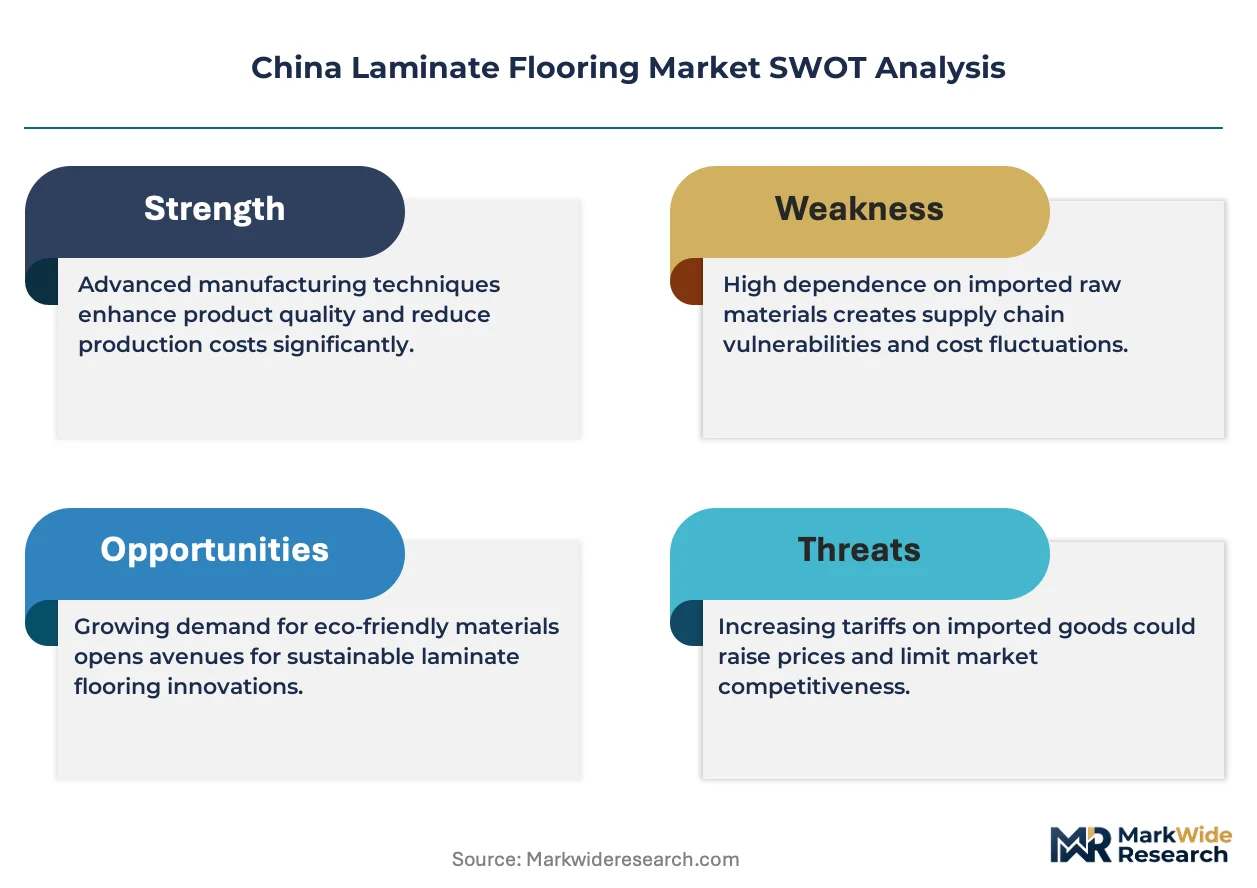
Centralized procurement by state-backed housing conglomerates is compressing traditional distributor margins and forcing mills to restructure sales organizations around direct account management.
Growth Catalysts
- GB Standard Upgrade:Tightened formaldehyde emission limits under GB/T 18102 are redirecting renovation demand toward certified domestic mills with compliant substrate production.
- Water-Resistant Formulation:Moisture-resistant HDF core technology is capturing specification share in coastal Jiangsu and Zhejiang residential projects.
- Tier-Two Urbanization:Housing stock renewal in Changzhou, Wuxi, and Ningbo is generating replacement surface demand as aging installations reach end-of-life.
Market Restraints
- Resin Input Volatility:Melamine and urea-formaldehyde adhesive costs fluctuate with coal-chemical feedstock pricing, squeezing pressing line margins.
- Substrate Concentration:High-density fiberboard supply clusters in Shandong and Hebei provinces, creating geographic single-source risk for Zhejiang-based laminators.
- Engineered Wood Substitution:SPC rigid vinyl and WPC composites are capturing price-sensitive commercial retrofit specification.
Strategic Opportunities
- Western Province Penetration:Chengdu and Xi'an construction markets remain underdeveloped for premium wear-grade specification.
- Export Certification Breadth:CARB Phase 2 and CE marking compliance opens OEM assembly channels into Southeast Asian retail distribution.
- MIIT Automation Incentives:Industrial policy directives subsidize pressing line upgrades that reduce per-unit energy intensity.
Industry Challenges
- Adhesive Chemistry Talent:Formulation expertise for low-emission resin systems remains concentrated among senior technicians at state-owned research institutes.
- GB Revision Cycle Uncertainty:Anticipated updates to wood-based panel standards create inventory risk for mills holding non-compliant substrate stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Laminate Flooring Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminate, Direct-Floor Laminate, Water-Resistant Laminate, Decorative Laminate Installation Type: Floating, Glue-Down, Nail-Down, Click-Lock Thickness: 7mm, 8mm, 10mm, 12mm End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Yangzi Floor, China National Building Material Group Corporation, Power Dekor, Vöhringer, Pergo China, Chinafloors, Shandong Jufeng Flooring, Shaw Floors China, Nature Floor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Laminate Flooring Market Strategic Shifts
Product differentiation is migrating from surface aesthetics to performance certification and installation efficiency as buyer procurement teams professionalize specification criteria.
Water-resistant laminate variants with wax-impregnated HDF cores and sealed click-lock edges are expanding into coastal residential segments where humidity degradation previously limited category penetration. Property developers in Ningbo and Zhoushan are specifying these grades for mid-rise apartment stock. The technology is expanding into territory once reserved for ceramic tile and engineered vinyl.
MEE air-quality enforcement is tightening volatile organic compound limits on panel adhesive curing operations. Mills in Jiangsu province face accelerated scrubber and thermal oxidizer installation timelines. Smaller pressing operations without captive chemical treatment capacity are consolidating toward compliant industrial park clusters.
Direct mill contracting is displacing layered distributor networks as state-backed developers centralize flooring procurement under dedicated materials divisions. Changzhou-based manufacturers are restructuring sales organizations around key account managers. The shift is most visible in Hangzhou and Suzhou where housing conglomerates operate captive fit-out subsidiaries.
China Laminate Flooring Market Segmentation
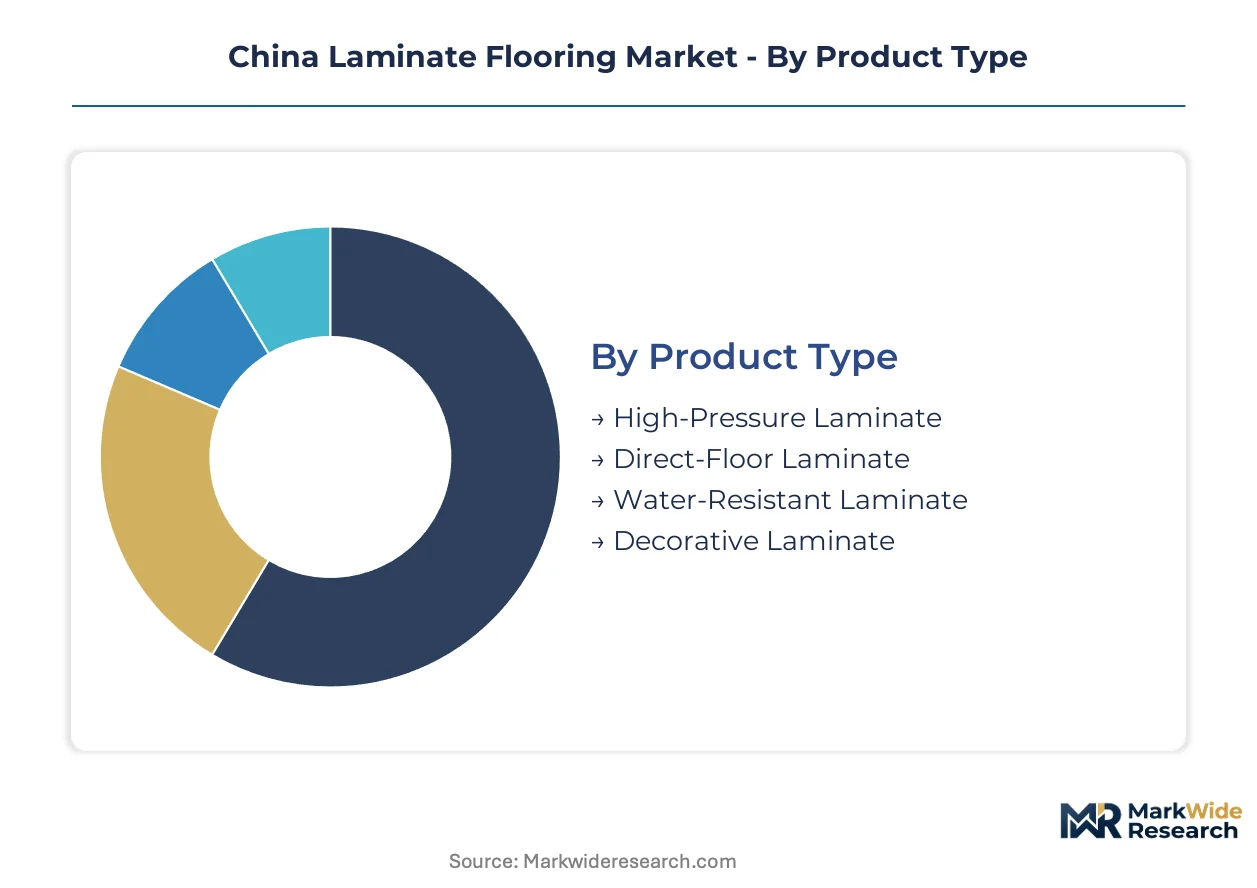
Segmentation in China's laminate flooring market reveals how procurement centralization and specification professionalization are reshaping product mix priorities. Buyers now segment by performance certification and installation efficiency rather than surface aesthetics alone.
Product Type:
Supply concentration in Jiangsu and Zhejiang provinces favors manufacturers with captive resin-pressing capacity and integrated substrate production.
- Water-Resistant Laminate:Wax-impregnated HDF cores and sealed click-lock edges resist humidity degradation. Property developers in Ningbo and Zhoushan specify these grades for mid-rise coastal apartment stock, displacing ceramic tile in territory previously reserved for moisture-proof surfaces.
- High-Pressure Laminate:Multi-layer construction with decorative paper saturated in thermosetting resins under heat and pressure delivers superior wear resistance. State-backed housing conglomerates in Hangzhou and Suzhou centralize procurement of these grades through direct mill contracts, bypassing traditional distributor networks.
- Direct-Floor Laminate:Simplified construction with direct resin application to substrate reduces manufacturing cost tiers.
- Decorative Laminate:Aesthetic-focused variants target renovation demand in tier-two cities where surface replacement drives specification.
Today's leader: Water-Resistant Laminate. Tomorrow's challenger: High-Pressure Laminate.
Installation Type:
Commercial retrofit demand prioritizes labor-hour reduction and subfloor preparation minimization, reshaping installer preferences across end-use segments.
- Click-Lock:Mechanical joining systems eliminate adhesive curing time and reduce skilled labor requirements. MEE air-quality enforcement on VOC-emitting adhesives accelerates specification in Jiangsu province industrial parks facing accelerated scrubber installation timelines.
- Glue-Down:Full-surface adhesive bonding delivers maximum stability for high-traffic commercial specifications in Chengdu and Xi'an underdeveloped premium markets.
- Floating:Interlocking planks without substrate attachment suit residential renovation where existing floor preservation matters.
- Nail-Down:Traditional fastening for wood-substrate applications retains niche specification in heritage property restoration.
Click-Lock systems expand most quickly as MEE mandates tighten adhesive chemistry compliance costs.
Thickness:
Acoustic performance and underfoot stability drive premium residential specification, while cost-sensitive commercial segments optimize material efficiency.
- 12mm:Dense core construction delivers superior sound dampening and structural rigidity. Housing stock renewal in Changzhou, Wuxi, and Ningbo generates replacement demand as aging installations reach end-of-life, with premium segments specifying this grade for perceived quality differentiation.
- 8mm:Balanced material efficiency and performance dominates volume production for export assembly channels into Southeast Asian retail distribution requiring CARB Phase 2 and CE marking compliance.
- 10mm:Mid-tier specification captures price-conscious residential renovation in tier-two urbanization corridors.
- 7mm:Minimal material profile serves temporary installation and budget-constrained commercial retrofit where subfloor quality permits reduced thickness.
12mm grades command premium positioning. 8mm variants scale fastest through export OEM channels.
End User:
Buyer concentration among large-scale property developers decouples procurement from distributor networks, with segment-specific compliance requirements diverging product flows.
- Residential:Renovation demand in tier-two cities strengthens as homeowners replace aging surfaces with moisture-resistant alternatives meeting updated GB/T 18102 formaldehyde emission limits. Certified domestic mills in Jiangsu province capture redirected procurement from non-compliant substrate sources.
- Commercial:Centralized materials divisions at state-backed housing conglomerates compress traditional distributor margins. Changzhou-based manufacturers restructure sales organizations around key account managers serving captive fit-out subsidiaries in Hangzhou and Suzhou.
- Hospitality:Brand-standard consistency requirements favor mills with export-grade certification breadth serving OEM channels.
- Industrial:Heavy-duty wear classification and chemical resistance specifications concentrate demand among specialized pressing operations.
Residential renovation sustains volume leadership. Commercial direct-contracting represents the steepest expansion trajectory as procurement professionalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled adhesive formulation technicians cluster in Jiangsu and Zhejiang provinces, anchoring China's laminate flooring production capacity and compliance expertise. These concentrations attract state-backed housing conglomerates seeking certified substrate supply.
Jiangsu Province
Changzhou and Wuxi house dense pressing line clusters serving renovation demand in tier-two cities. MIIT automation incentives accelerate scrubber installation timelines at mills facing MEE air-quality enforcement. Yangzi Floor leverages vertically integrated substrate production to dominate provincial supply.
Zhejiang Province
Ningbo and Zhoushan developers specify water-resistant grades for coastal mid-rise apartments. GB/T 18102 formaldehyde limits redirect procurement toward certified domestic mills with compliant HDF sourcing. Chinafloors anchors export-grade certification capacity for Southeast Asian OEM channels.
Shandong Province
High-density fiberboard supply clusters here create geographic single-source exposure for eastern laminators. Provincial environmental enforcement intensity fluctuates with seasonal air-quality campaigns. Shandong Jufeng Flooring exemplifies substrate-to-surface integration serving price-sensitive commercial segments.
Sichuan-Chongqing Region
Chengdu construction markets remain underdeveloped for premium wear-grade specification. Western province penetration opportunities concentrate in fit-out demand from state-backed housing conglomerates expanding beyond coastal clusters. Local distributors retain influence where direct mill contracting has not yet consolidated.
Hebei Province
Substrate production gravity here complements Shandong supply, though environmental compliance costs pressure smaller pressing operations. Mills without captive chemical treatment capacity consolidate toward compliant industrial park clusters. Power Dekor secures volume commitments through backward integration into resin-pressing capacity.
China Laminate Flooring Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's laminate flooring sector. State-backed housing conglomerates centralize procurement through direct mill contracts, compressing traditional distributor margins. Three archetypes dominate: vertically integrated substrate producers, export-certified OEM assemblers, and captive resin-pressing operators. Competitive moves concentrate on direct account management restructuring and pressing line automation upgrades subsidized under MIIT industrial policy.
Within the vertically integrated tier, Yangzi Floor and Power Dekor exemplify archetypes combining substrate production with surface finishing capacity. Chinafloors occupies a position among export-focused specialists. China National Building Material Group Corporation represents diversified conglomerate participation. These three anchors illustrate how procurement centralization favors mills with captive supply chain control and certified compliance breadth.
| Leading Market Players |
|---|
| Yangzi Floor |
| China National Building Material Group Corporation |
| Power Dekor |
| Vöhringer |
| Pergo China |
| Chinafloors |
| Shandong Jufeng Flooring |
| Shaw Floors China |
| Nature Floor |
| Others |
Value Chain & Pricing Dynamics
Centralized procurement by state-backed housing conglomerates is compressing traditional distributor margins and forcing mills to restructure sales organizations around direct account management, which in turn concentrates pricing power among vertically integrated manufacturers with captive resin-pressing capacity.
Pricing Analysis
Capacity additions in Jiangsu and Zhejiang provinces are reshaping price floors as automated pressing lines subsidized under MIIT industrial policy reduce per-unit energy intensity. Three-tier pricing structure across premium, standard, and economy levels separates 12mm acoustic-grade specification from 8mm export-tier and 7mm budget commercial variants. Pricing pressure stems from melamine and urea-formaldehyde adhesive cost volatility tied to coal-chemical feedstock pricing. Commercial retrofit buyers exhibit highest price sensitivity, while state-backed developers prioritize certification compliance over unit cost.
Supply Chain Analysis
Skilled adhesive formulation technicians cluster in Changzhou and Wuxi, anchoring production capacity and creating geographic labor scarcity for mills outside these concentrations. High-density fiberboard supply draws from Shandong and Hebei provinces, while decorative paper and melamine resin feedstock sources concentrate in eastern manufacturing corridors. Single-source vulnerability persists in HDF substrate supply, where Shandong and Hebei clusters create geographic concentration risk for Zhejiang-based laminators. Distribution runs through direct mill contracts to state-backed housing conglomerates, displacing layered distributor networks in Hangzhou and Suzhou.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China laminate flooring market functions as a stable compounder, with residential renovation demand in tier-two cities generating predictable replacement cycles as aging installations reach end-of-life.
For Market Incumbents: Deploy backward integration into captive resin-pressing capacity to secure volume commitments from consolidated buyers and defend against SPC rigid vinyl substitution in commercial retrofit segments. Invest in automated pressing line upgrades under MIIT subsidies to reduce energy intensity per square meter produced. Strengthen direct account management teams serving state-backed housing conglomerates in Hangzhou and Suzhou. For New Entrants and Emerging Players: GB/T 18102 formaldehyde emission upgrades open a window for certified domestic mills to capture procurement redirected from non-compliant substrate sources. Target underdeveloped premium wear-grade specification in Chengdu and Xi'an construction markets where local distributors retain influence. Pursue CARB Phase 2 and CE marking compliance to access Southeast Asian OEM assembly channels. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated substrate producers combining HDF manufacturing with surface finishing capacity. The five-to-ten year viability window favors mills with compliant chemical treatment capacity and scrubber installations ahead of MEE enforcement timelines. Monitor GB standard revision cycles and provincial environmental enforcement intensity as inflection indicators for compliance cost shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin-Pressing | Captive supply of melamine-impregnated decorative paper secures volume commitments from consolidated state-backed buyers. |
| MIIT-Subsidized Automation Upgrade | Automated pressing line investments reduce per-unit energy intensity and accelerate MEE air-quality compliance timelines. |
| Export Certification Expansion | CARB Phase 2 and CE marking compliance opens OEM assembly channels into Southeast Asian retail distribution networks. |
| Direct Account Management Restructuring | Key account manager deployment captures procurement centralization by state-backed housing conglomerates in tier-one cities. |
| Water-Resistant Formulation Development | Wax-impregnated HDF core technology captures specification share in coastal Jiangsu and Zhejiang residential projects. |
Study Parameters
Bottom-up residential and commercial flooring demand modeling reconciled against top-down laminate production capacity tracking forms the analytical core. Primary interviews with plant managers at pressing operations, procurement leads at state-backed housing conglomerates, distribution channel partners, and technical R&D directors at resin formulation specialists combined with secondary validation against MIIT industrial policy directives, MEE air-quality enforcement records, GB/T 18102 standard documentation, and customs export data. Triangulation between demand-side renovation project pipelines and supply-side capacity utilization rates at Jiangsu and Zhejiang manufacturing clusters anchored volume estimates.
Input-output matrices mapped HDF substrate supply from Shandong and Hebei against laminating capacity in eastern provinces, with segmentation across product type, installation system, thickness grade, and end-user category modeled throughout the forecast period. CAGRs derived from housing stock renewal rates in tier-two cities, export assembly channel growth into Southeast Asian retail, and substitution dynamics between laminate and engineered vinyl in commercial retrofit. Forecast inputs incorporated MIIT automation incentive uptake rates and GB standard revision anticipation effects on inventory holding patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated MEE enforcement campaigns or unexpected GB/T 18102 standard revisions. Practitioners should monitor coal-chemical feedstock pricing volatility, provincial environmental enforcement intensity fluctuations, and state-backed housing conglomerate procurement centralization pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market