
 Global Commercial Flooring Market | 2026-2036
Global Commercial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Flooring Market Foresight
Premium-performance flooring specifications is redrawing procurement priorities across commercial real estate. Mohawk Industries leverages captive carpet-tile capacity to sustain margin control in North American healthcare and education projects. Tarkett SA anchors European positioning through bio-based vinyl R&D and closed-loop recycling infrastructure. Interface specializes in carbon-neutral carpet-tile systems that dominate corporate sustainability mandates.
Commercial flooring encompasses wear-layer engineered surfaces installed in non-residential buildings, typically specified by abrasion-class ratings, slip-resistance coefficients, and substrate compatibility for high-traffic zones. Manufacturing integrates calendering, extrusion, or tufting processes with polyurethane or PVC wear layers to deliver durability cycles exceeding commercial warranty thresholds. Vinyl Flooring leads value contribution due to water resistance and lower lifecycle cost in healthcare and retail applications. Carpet Tiles represents the fastest-growing structural segment as modular replacement reduces downtime and waste in office fit-outs. Wood Flooring occupies a mature premium niche where FSC certification and acoustic underlayment justify specification in hospitality lobbies and executive suites.
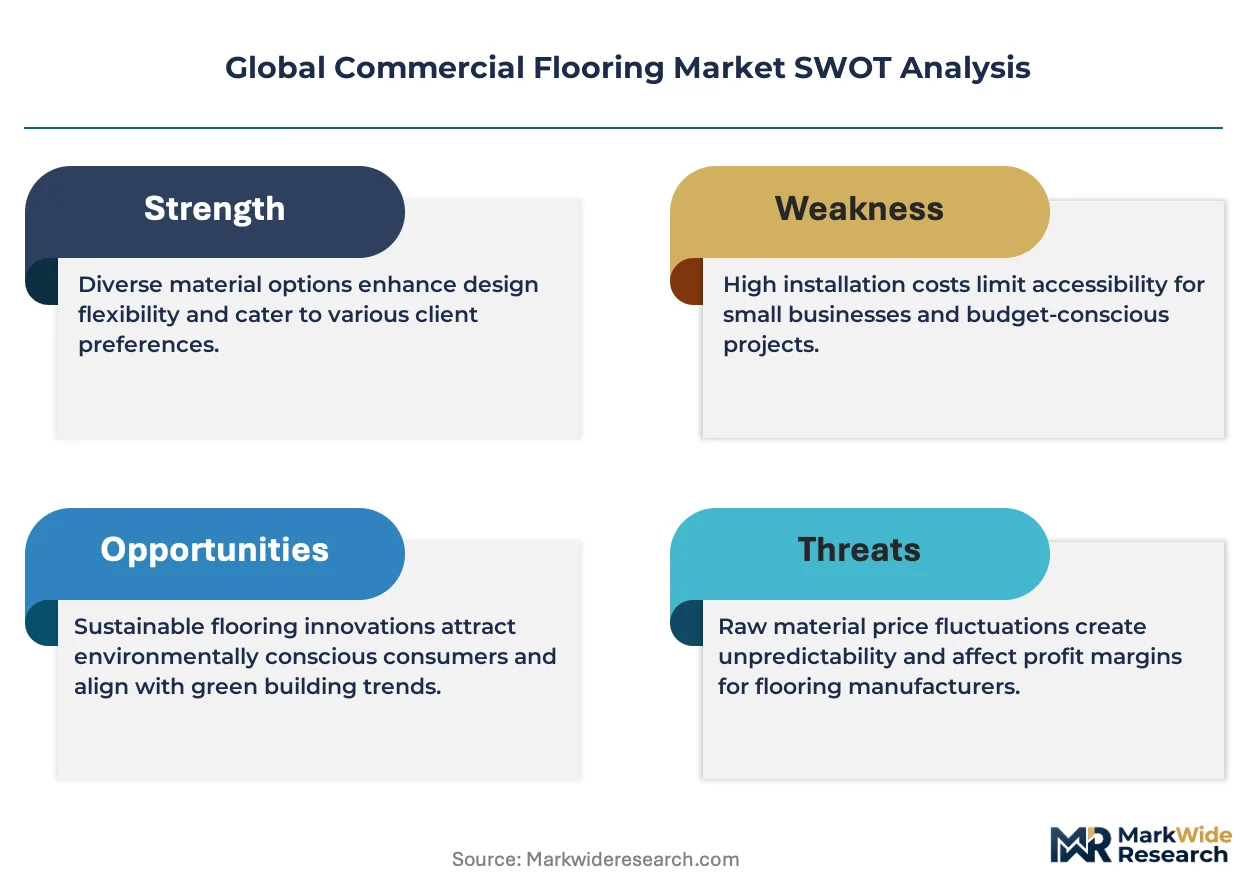
FDA guidelines on healthcare surface cleanability, EPA regulations on formaldehyde emissions from composite wood products, and REACH restrictions on phthalate plasticizers in vinyl formulations collectively tighten material compliance burdens. CE marking under the EU Construction Products Regulation mandates declared performance for fire reaction and slip resistance, creating divergent certification costs for exporters. Stakeholders must monitor how evolving extended-producer-responsibility frameworks in the EU and state-level low-carbon procurement rules in California reshape specification authority and supplier qualification thresholds.
Market Dynamics
Healthcare infection-control mandates are tightening floor-area specifications per bed, while the EU Green Deal accelerates low-VOC and recycled-content mandates that reshape material qualification thresholds across the supply base.
Growth Catalysts
- EU Green Deal mandates:Low-VOC and recycled-content requirements across member states are forcing specification upgrades in hospital and airport projects, pulling premium vinyl and bio-based alternatives into standard procurement tiers.
- Healthcare construction:China's hospital build-out pipeline and terminal upgrades are concentrating demand for abrasion-class rated surfaces with enhanced cleanability protocols.
- Modular replacement cycles:Carpet tile adoption is accelerating in office fit-outs as facilities managers prioritize downtime reduction and waste minimization over broadloom installation.
Market Restraints
- Phthalate plasticizer restrictions:REACH limitations on flexible vinyl formulations are forcing reformulation investments that compress margin structures for mid-tier suppliers without captive R&D.
- Petrochemical feedstock volatility:PVC resin and polyurethane precursor prices fluctuate with crude oil and natural gas benchmarks, destabilizing cost planning for project-based contracts.
- Formaldehyde emission controls:EPA regulations on composite wood products are fragmenting supplier qualification for hospitality and executive suite wood flooring segments.
Strategic Opportunities
- Carbon-neutral specification:Corporate sustainability mandates in Northern Europe are creating pull-through for cradle-to-cradle certified carpet tile systems with verified emission offsets.
- Closed-loop recycling infrastructure:Post-installation take-back programs in France and Germany are establishing new service revenue streams distinct from product margins.
- Digital specification tools:BIM-integrated flooring libraries are shortening the architect-to-contractor decision chain in US commercial real estate development.
Industry Challenges
- Fire reaction certification timelines:CE marking under the EU Construction Products Regulation requires third-party testing that delays project bidding cycles by 8-14 weeks for new product introductions.
- Substrate compatibility complexity:Moisture mitigation and acoustic underlayment integration with existing concrete slabs demands specialized installation labor that concentrates in urban contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Flooring Market |
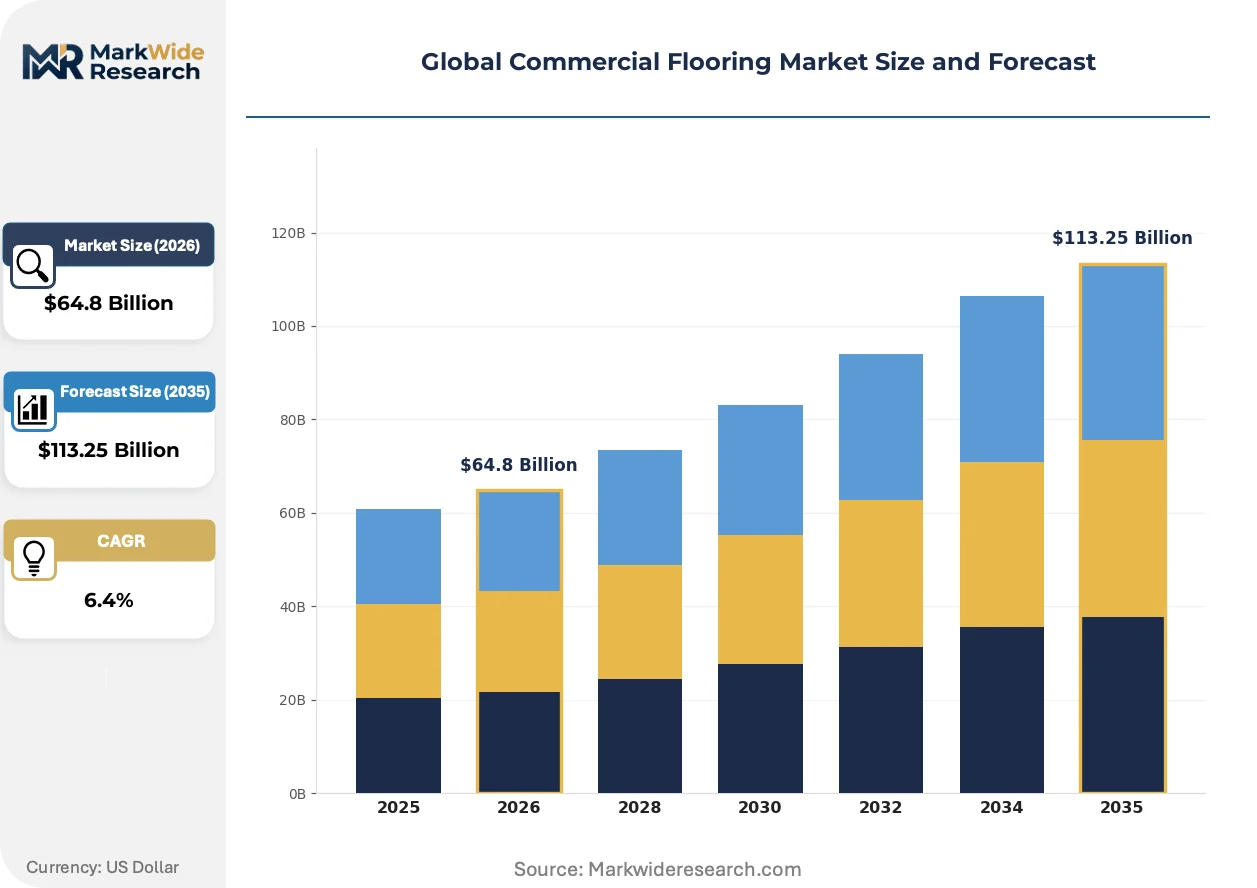
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $113.25 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet Tiles, Vinyl Flooring, Laminate Flooring, Wood Flooring, Rubber Flooring, Ceramic Tiles Application: Office Spaces, Educational Institutions, Hospitality, Healthcare Facilities, Retail Outlets, Public Buildings Installation Method: Glue-Down, Floating, Nail-Down, Tape-Down, Loose Lay, Interlocking End User: Property Developers, Facility Managers, Interior Designers, Contractors, Renovators, Maintenance Companies |
| Companies Covered | Forbo Holding AG, Armstrong Flooring, Inc., Mohawk Industries, Inc., Mannington Mills, Inc., Gerflor SAS, Shaw Industries Group, Inc., Interface, Inc., Beaulieu International Group NV, Tarkett SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Flooring Market Shifts & Advancements
Bio-based material science and digital specification platforms are converging to compress traditional procurement cycles while elevating performance transparency as a competitive differentiator in commercial real estate development.
Digitally printed luxury vinyl tile is fragmenting the specification hierarchy between sheet vinyl and engineered wood in hospitality and retail environments. Hotel operators in Dubai and Singapore are adopting water-resistant surfaces with wood-grain aesthetics that withstand pressure-washing protocols. This technology is fragmenting the traditional premium-mid-economy tier structure by enabling batch-size-one customization at mid-tier price points.
REACH restrictions on phthalate plasticizers are forcing vinyl compounders to migrate toward bio-based plasticizer alternatives derived from epoxidized soybean oil. Reformulation investments are concentrating among suppliers with integrated compounding capabilities. Healthcare and childcare facilities in Germany, the Netherlands, and Belgium are now specifying phthalate-free alternatives as default procurement standards.
Facilities managers are compressing replacement cycles from ten-year intervals to five-year modular refresh programs. Corporate headquarters in London and New York are unbundling flooring maintenance from capital project budgets, creating recurring service contracts. This pattern is most visible in technology sector fit-outs where lease terms and headcount volatility favor asset-light operating models over long-warranty capital installations.
Global Commercial Flooring Market Segmentation
Commercial flooring procurement decisions cascade through multiple specification layers that determine material performance, installation complexity, and lifecycle cost. Understanding how product attributes align with end-use requirements and decision-maker priorities exposes where margin concentrates and where substitution risk looms.
Product Type:
Domestic manufacturing dominates vinyl and carpet tile supply in North America and Europe, while wood and ceramic sourcing extends into Southeast Asian export networks. Export-led segments face longer certification timelines and freight-cost volatility that reshape landed pricing.
- Vinyl Flooring:Calendered or extruded PVC wear-layer systems deliver water resistance and chemical cleanability essential for hospital protocols. China's hospital construction pipeline and German healthcare renovation programs concentrate demand for phthalate-free formulations meeting REACH standards. Reformulation investments toward bio-based plasticizers are compressing margins for suppliers without captive compounding.
- Carpet Tiles:Modular tufted systems with bitumen or PVC backing enable zone replacement and waste reduction in corporate fit-outs. London and New York technology sector headquarters are unbundling flooring from capital budgets into five-year refresh service contracts. Cradle-to-cradle certification is becoming a gatekeeper specification in Northern European sustainability mandates.
- Laminate Flooring:High-density fiberboard core with melamine wear surface, specified where moisture exposure remains controlled.
- Wood Flooring:Engineered plank systems with FSC certification and acoustic underlayment, concentrated in Dubai and Singapore hospitality lobbies.
- Rubber Flooring:Vulcanized or rolled rubber for gymnasiums and healthcare circulation zones, dominated by Belgian and Italian producers.
- Ceramic Tiles:Porcelain and quarry tile for heavy-wear public building entrances, sourced primarily from Italian and Spanish export manufacturers.
Vinyl Flooring commands the established base. The steepest expansion runs through Carpet Tiles.
Application:
Cost-tier stratification separates premium-specification healthcare and hospitality from volume-driven educational and public building procurement. Higher abrasion-class ratings and extended warranty terms concentrate in upper tiers where lifecycle costing overrides first-cost sensitivity.
- Healthcare Facilities:Infection-control protocols mandate seamless sheet vinyl or heat-welded linoleum with documented cleanability under FDA surface guidelines. EU member states are expanding floor area per bed as isolation-room standards tighten. Pressure-washing compatibility is becoming a default specification for patient-room surfaces.
- Office Spaces:Carpet tile modularity dominates corporate headquarters where churn and headcount volatility favor asset-light operating models. Facilities managers in technology sector fit-outs prioritize downtime reduction over broadloom aesthetics. BIM-integrated specification tools are compressing architect-to-contractor decision cycles.
- Educational Institutions:Abrasion-class rated vinyl and rubber formulations for K-12 and university circulation corridors, procured through state-level cooperative purchasing agreements.
- Hospitality:Digitally printed luxury vinyl tile with wood-grain aesthetics is fragmenting the traditional premium-mid-economy structure in Dubai and Singapore hotel renovations.
- Retail Outlets:Rapid-turnover tenant improvements driving loose-lay and interlocking installation methods for speed-to-market.
- Public Buildings:Fire-reaction certified ceramic and vinyl systems for airport terminals and government facilities under EU Construction Products Regulation mandates.
Healthcare Facilities anchor premium-value capture. Office Spaces are gaining share fastest as service-contract models proliferate.
Installation Method:
Volume concentration sits with fast-track methods that minimize substrate preparation and skilled labor dependency. Margin accrues to specialized techniques requiring moisture mitigation expertise and acoustic performance engineering.
- Glue-Down:Full-spread adhesive application for permanent commercial installations demanding maximum dimensional stability. German and Dutch healthcare projects specify this method for seamless sheet vinyl in operating theaters. Substrate moisture testing and mitigation compliance add 8-14 weeks to project timelines.
- Floating:Click-lock engineered wood and laminate systems that accelerate installation over uneven concrete slabs. Hospitality lobby renovations in Dubai favor this method for speed and acoustic underlayment integration. Urban contractor networks with specialized floating-floor expertise command premium labor rates.
- Nail-Down:Traditional solid wood fastening, now confined to premium heritage restoration and executive suite specifications.
- Tape-Down:Pressure-sensitive adhesive systems for temporary retail and exhibition flooring with rapid removal requirements.
- Loose Lay:Friction-fit vinyl plank and tile for tenant improvements where lease terms preclude permanent attachment.
- Interlocking:Rigid-core vinyl and rubber tile for gymnasiums and light industrial zones requiring tool-free replacement.
Glue-Down retains the specification base for critical-performance zones. Floating methods are climbing the fastest as renovation cycles compress.
End User:
Customer-type fragmentation creates divergent procurement behaviors: capital-project developers prioritize first-cost and warranty transferability, while operating-phase managers prioritize service integration and replacement flexibility.
- Facility Managers:Operating-phase decision-makers unbundling flooring maintenance from capital budgets into recurring service contracts. Corporate headquarters in London and New York are compressing replacement cycles from ten-year intervals to five-year modular refresh programs. Outcome-based procurement is elevating suppliers with post-installation take-back capabilities.
- Property Developers:Speculative commercial real estate developers prioritizing first-cost minimization and warranty transferability to anchor tenants. US Class-A office construction is standardizing on carpet tile for leasable-floor flexibility. California state-level low-carbon procurement rules are reshaping supplier qualification thresholds.
- Interior Designers:Aesthetic and performance specification authority in hospitality and executive suite segments, increasingly leveraging digital material libraries.
- Contractors:Installation labor coordinators facing substrate compatibility complexity and specialized skill concentration in urban networks.
- Renovators:Fast-track project specialists driving demand for floating and loose-lay methods with minimal slab preparation.
- Maintenance Companies:Service-phase providers capturing recurring revenue streams distinct from product margins in EU closed-loop recycling frameworks.
Facility Managers are redirecting procurement toward service-integrated models. Property Developers remain the volume gatekeeper for new construction specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led flooring manufacturers face divergent certification timelines across destination markets, while import-dependent regions absorb freight-cost volatility that reshapes landed pricing for project-based contracts.
United States
Hospital construction pipelines in Texas and Florida concentrate demand for FDA-compliant cleanable surfaces as infection-control protocols expand floor area per bed. EPA formaldehyde emission controls on composite wood products fragment supplier qualification for hospitality segments. California's state-level low-carbon procurement rules reshape specification authority in Class-A office developments across Los Angeles and San Francisco.
China
Airport terminal upgrades in Beijing and Shanghai accelerate specifications for abrasion-class rated vinyl systems with pressure-washing compatibility. National dual carbon goals tighten material compliance for public building projects. The Yangtze River Delta manufacturing cluster supplies phthalate-free formulations for domestic healthcare renovation programs.
Germany
Healthcare facilities in Bavaria and North Rhine-Westphalia specify REACH-compliant phthalate-free vinyl as default procurement standards. The EU Green Deal accelerates low-VOC mandates across federal hospital renovation programs. Closed-loop recycling infrastructure in the Rhine-Ruhr region establishes post-installation take-back service revenue streams.
United Arab Emirates
Dubai and Abu Dhabi hospitality operators adopt digitally printed luxury vinyl tile with wood-grain aesthetics for pressure-washing protocols. MOHAP facility guidelines tighten cleanability specifications for healthcare surfaces. Jebel Ali industrial zone concentrates import distribution for re-export across Gulf Cooperation Council markets.
United Kingdom
London technology sector headquarters compress replacement cycles from ten-year intervals to five-year modular refresh programs. CE marking under EU Construction Products Regulation—still referenced in UK procurement—mandates fire reaction certification that delays bidding cycles. Manchester and Birmingham corporate fit-outs drive carpet tile demand for churn-resilient asset-light operating models.
Global Commercial Flooring Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D scale, creating a tiered structure where scale-driven players anchor volume segments while niche operators capture premium sustainability mandates. Consolidation concentrates among integrated manufacturers with captive compounding capabilities. Three archetypes dominate: diversified surface-material conglomerates, bio-based formulation specialists, and modular-system innovators. Competitive moves center on backward integration into resin supply and geographic expansion through specification partnerships with architect networks.
Within the diversified conglomerate tier, Mohawk Industries and Tarkett SA occupy positions that exemplify scale-driven supply chain control across multiple surface categories. Interface represents the modular-system archetype, anchoring corporate sustainability mandates through carbon-neutral carpet tile positioning. Among European specialists, Forbo Holding AG and Gerflor SAS sit within the bio-based formulation cluster, reflecting regional regulatory pressure toward phthalate-free alternatives.
| Leading Market Players |
|---|
| Forbo Holding AG |
| Armstrong Flooring, Inc. |
| Mohawk Industries, Inc. |
| Mannington Mills, Inc. |
| Gerflor SAS |
| Shaw Industries Group, Inc. |
| Interface, Inc. |
| Beaulieu International Group NV |
| Tarkett SA |
| Others |
Supply & Pricing Matrix
Bio-based plasticizer migration from petroleum-derived phthalates is redrawing raw material sourcing maps and compressing margin structures for vinyl compounders without captive reformulation capabilities. This substitution dynamic simultaneously elevates soybean oil derivative markets in North American agricultural regions and forces European REACH-compliant suppliers to absorb higher input costs or cede share to integrated competitors.
Pricing Analysis
Property developers anchor project-based contract pricing across the Global Commercial Flooring Market. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with FSC-certified wood and cradle-to-cradle carpet tile commanding substantial premiums. Cost compression in mid-tier vinyl runs through petrochemical feedstock volatility and REACH-driven reformulation investments. Facilities managers exhibit lowest price sensitivity, prioritizing lifecycle cost and service integration over first-cost minimization.
Supply Chain Analysis
China and Germany anchor vinyl compounding and carpet tile manufacturing respectively, with Belgium and Italy concentrating rubber flooring production. PVC resin and polyurethane precursors draw from petrochemical complexes in the US Gulf Coast and Middle Eastern export hubs. Single-source vulnerability concentrates in specialized bio-based plasticizer supply chains transitioning from epoxidized soybean oil. Distribution runs through architect-specified channels with BIM-integrated libraries compressing decision timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Commercial Flooring Market is accelerating through regulatory inflection as the EU Green Deal mandates reshape material qualification thresholds across member states. This disruption creates divergent winners between integrated reformulators and stranded mid-tier suppliers.
For Market Incumbents: Fortify backward integration into bio-based plasticizer supply and captive PVC compounding to defend margin structures against REACH-driven cost compression. Prioritize certification investment for CE marking and fire reaction testing to accelerate bidding cycles in EU hospital and airport projects. Channel control through architect network partnerships protects specification authority against digitally native entrants. For New Entrants and Emerging Players: Post-installation take-back service gaps in France and Germany offer white-space entry points where incumbents under-serve facilities managers with circular-economy mandates. Target London and New York technology sector headquarters with modular refresh service contracts that unbundle flooring from capital budgets. Go-to-market leverage centers on BIM-integrated specification tools that compress architect-to-contractor decision chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European vinyl specialists lacking integrated bio-based formulation capabilities. Long-term viability favors manufacturers with closed-loop recycling infrastructure and verified carbon-neutral positioning across the projection horizon. Monitor California state-level low-carbon procurement rule expansion as signal for US specification authority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Plasticizers | REACH compliance costs compress margins for non-integrated vinyl compounders in German healthcare markets. |
| Closed-loop Recycling Infrastructure Buildout | France and Germany's extended producer responsibility frameworks create recurring service revenue distinct from product sales. |
| BIM-integrated Specification Platform Launch | Digital libraries compress architect-to-contractor decision cycles in US commercial real estate development. |
| Carbon-neutral Certification Investment | Cradle-to-cradle positioning captures Northern European corporate sustainability mandates. |
| Regional Manufacturing Footprint Expansion | Yangtze River Delta proximity reduces freight-cost volatility for China's hospital construction pipeline. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with facilities managers, architect specification leads, flooring procurement directors, and installation contractors; and secondary validation through customs trade records, SEC 10-K filings, EU Construction Products Regulation databases, and REACH compliance registries. Bottom-up project pipeline tracking across healthcare and airport construction combined with top-down market sizing triangulation anchored volume estimates.
Across the analysis window, the forecast framework modeled product type segmentation, installation method complexity, end-user procurement behavior, and regional regulatory cluster effects. CAGRs derived from weighted scenario analysis incorporating construction pipeline visibility and material substitution elasticity. Key inputs included hospital floor-area-per-bed expansion rates and EU Green Deal implementation timelines.
Underlying assumptions cover sustained healthcare infrastructure investment and bio-based plasticizer cost convergence, with deviation risk concentrated in petrochemical price volatility and extended CE marking certification delays. Recalibration cycles align with material shifts in EU regulatory enforcement and China dual carbon policy implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market