
 Non-Resilient Floor Covering Market | 2026-2036
Non-Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Resilient Floor Covering Market Analytics
Multi-source ceramic tile procurement is hardening among large-scale hospitality developers seeking supply security across volatile raw material markets. Mohawk Industries leverages captive quarry access in North America to sustain cost-advantaged porcelain output. Shaw Industries Group anchors domestic manufacturing scale through vertically integrated fiber operations. Kajaria Ceramics Limited dominates India's organized tile retail channel with extensive distributor controls.
Non-resilient floor covering comprises rigid surfacing materials—ceramic, porcelain, natural stone, concrete, and wood—installed with permanent bonding methods, typically exhibiting Mohs hardness ratings above 5 and water absorption below 0.5% for vitrified grades, designed to withstand heavy static and dynamic loads in commercial and institutional environments. Ceramic tiles occupy mature, high-volume positions where manufacturing scale determines margin survival, while laminate segments face substitution pressure from luxury vinyl alternatives in residential renovation. Glue-down installation methods retain preference in healthcare and food-service settings where moisture intrusion risks mandate impermeable seams, whereas floating systems gain traction in multi-family residential for speed and labor cost reduction.
EPA regulations on volatile organic compound emissions from adhesives and sealants constrain product formulation choices for US-based installers and manufacturers. China's SAMR enforces GB standards on radioactive nuclide limits in ceramic tiles, shaping export qualification protocols for producers serving domestic and international markets. India's BIS certification for ceramic tile dimensional stability creates compliance thresholds that filter smaller unorganized competitors. Stakeholders must monitor evolving carbon-border adjustment mechanisms and embodied-carbon disclosure requirements that will restructure sourcing decisions across major construction corridors.
Market Dynamics
China's tightening GB standards on formaldehyde emissions and radioactive nuclide limits are compressing supplier margins while accelerating consolidation among export-oriented ceramic tile manufacturers serving Asia-Pacific commercial construction corridors.
Growth Catalysts
- Urban residential densification in India:Government housing schemes and metro corridor expansion are channeling investment into organized tile retail networks. Kajaria Ceramics and domestic competitors scale distributor controls to capture this demand.
- Healthcare facility construction codes:Glue-down ceramic and porcelain installation methods retain preference in US hospital and food-service settings where moisture intrusion risks mandate impermeable seams under EPA adhesive emission guidelines.
- Captive quarry access:North American manufacturers with backward integration into feldspar and kaolin deposits sustain cost-advantaged porcelain output against volatile raw material markets.
Market Restraints
- Natural gas price volatility:Energy-intensive kiln operations face margin compression from input cost swings, particularly affecting European ceramic tile producers dependent on spot LNG markets.
- Luxury vinyl tile substitution:Floating LVT systems gain traction in US multi-family residential renovation, displacing laminate segments with faster installation and lower labor requirements.
- Export qualification friction:China's SAMR enforcement of GB standards on radioactive nuclide limits creates compliance bottlenecks for smaller producers lacking in-house testing infrastructure.
Strategic Opportunities
- Carbon-border adjustment preparation:EU CBAM implementation timelines are forcing early movers to document embodied-carbon footprints across ceramic supply chains, creating certification premiums for compliant exporters.
- Modular prefabrication convergence:Offsite construction methods in hospitality and student housing are opening specification channels for factory-finished porcelain panels with integrated subfloor systems.
- India's BIS certification gaps:Dimensional stability testing requirements filter unorganized competitors, creating acquisition targets for organized players with laboratory infrastructure.
Industry Challenges
- Skilled installer scarcity:Glue-down ceramic specification in healthcare and commercial kitchens requires certified moisture-mitigation expertise that outpaces vocational training pipeline output.
- Legacy inventory reconfiguration:Distributors holding substantial laminate stock face working capital strain as procurement rotates toward LVT and SPC alternatives in residential channels.
- Cross-border certification timelines:India's BIS mark acquisition for imported vitrified tiles extends lead times, complicating just-in-time supply commitments for large-scale hospitality developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Resilient Floor Covering Market |
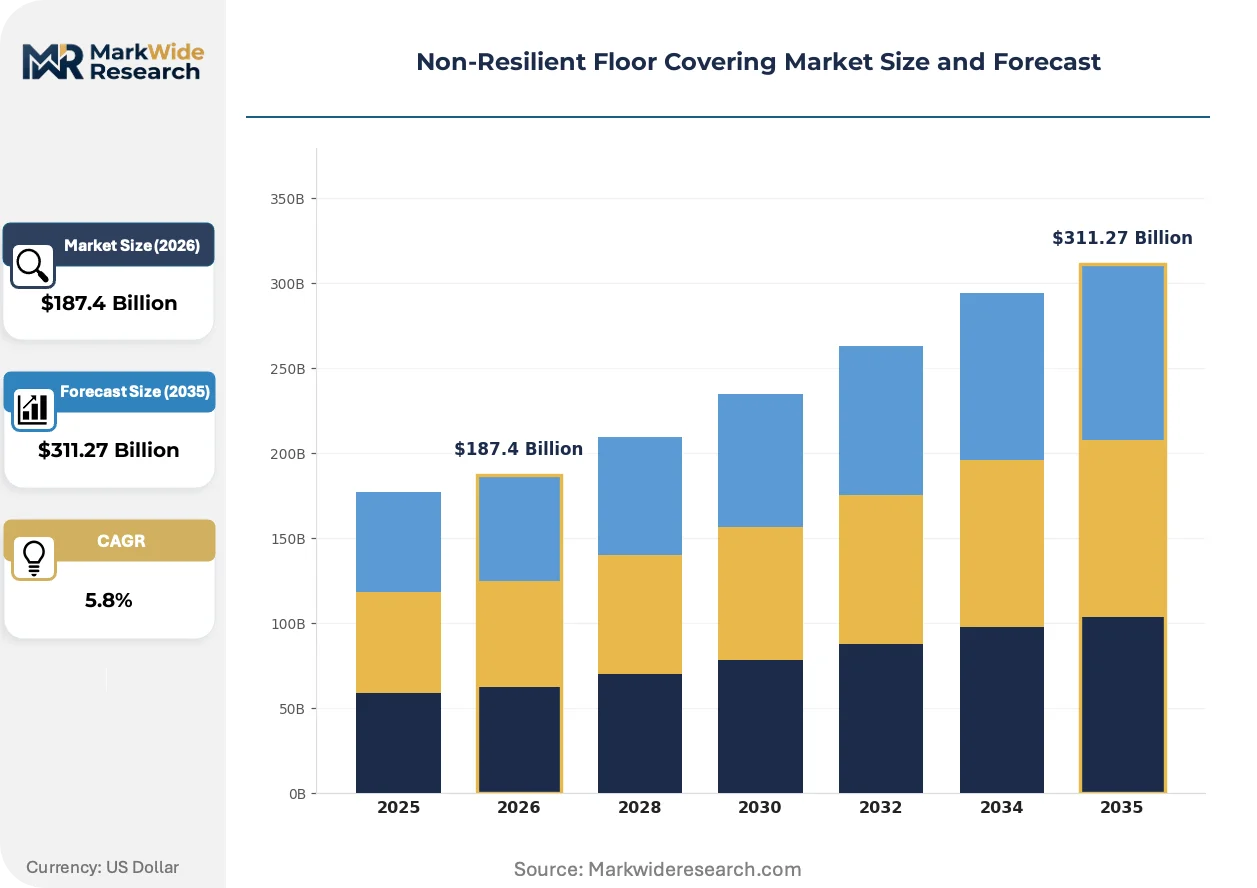
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Tiles, Vinyl Tiles, Laminate, Hardwood Installation Method: Glue-Down, Nail-Down, Floating, Grout End User: Residential, Commercial, Industrial, Hospitality Surface Finish: Polished, Matte, Textured, Glossy |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Mannington Mills, Inc., Kajaria Ceramics Limited, Daltile, Porcelanosa Grupo A.I.E., Crossville Inc., IVC-Group, Polyflor Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Resilient Floor Covering Market Evolving Landscape
Digitization of surface aesthetics and installation methodology is compressing product lifecycles while opening specification channels previously closed to rigid flooring categories.
Thin-format large porcelain panels are modularizing facade and flooring applications through reduced weight and expanded format dimensions. Hospitality developers in Dubai and Singapore specify these systems for high-traffic atrium spaces where seamless visual continuity matters. The technology is modularizing traditional trade boundaries between exterior cladding and interior surfacing, enabling single-source procurement contracts that compress project coordination overhead.
REACH restrictions on crystalline silica in construction materials are accelerating water-jet and dry-cutting equipment adoption across EU member states. Fabricators serving commercial stone and porcelain markets face capital equipment decisions to maintain workshop compliance. Italian and Spanish ceramic clusters are responding with collective investment in shared cutting facilities to distribute compliance costs across mid-tier producers.
Developer procurement teams are consolidating vendor panels and demanding extended performance warranties that bundle material supply with installation labor. Multi-source ceramic tile procurement is hardening among large-scale hospitality developers seeking supply security across volatile raw material markets. This concentration is most visible in Asia-Pacific commercial corridors where sovereign wealth-backed developers leverage scale to extract price-volume commitments from manufacturer consortiums.
Non-Resilient Floor Covering Market Segmentation
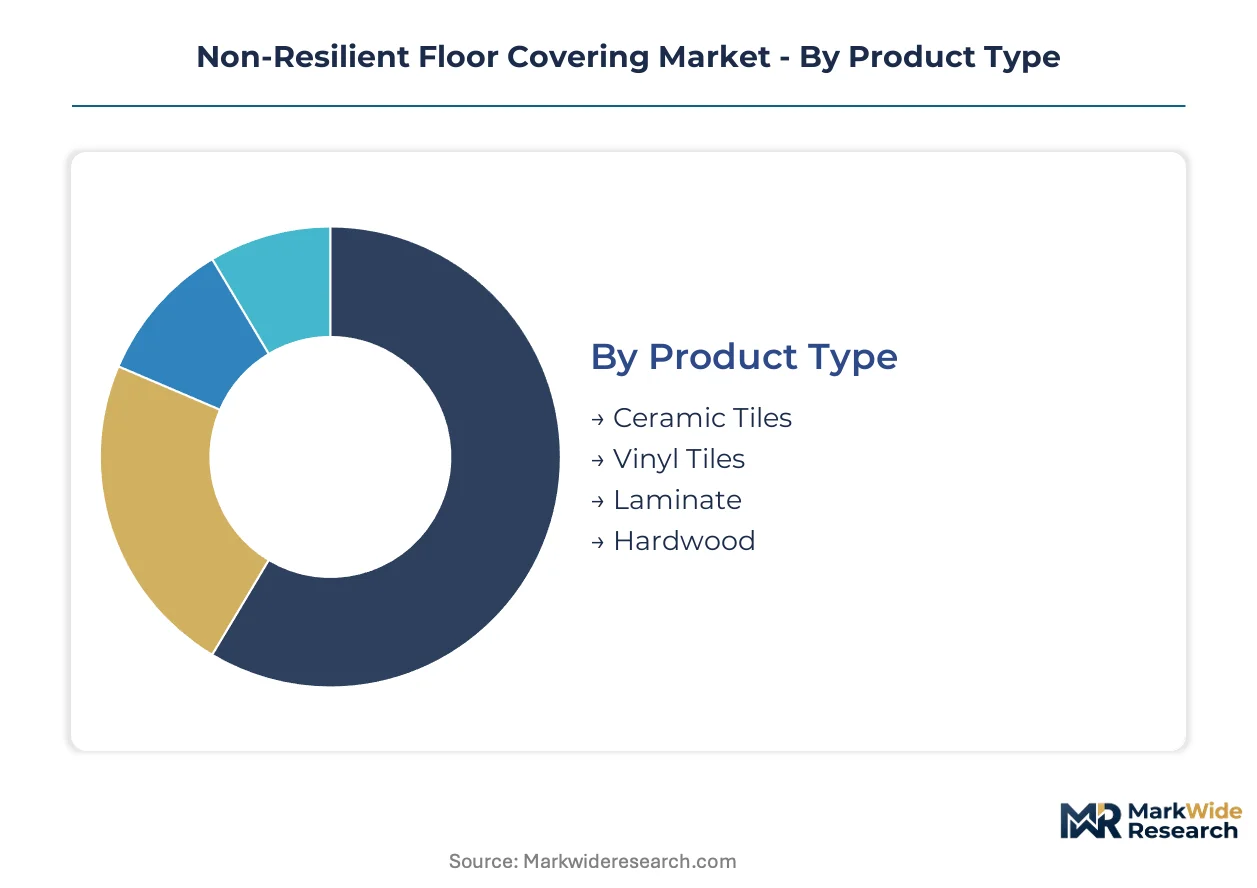
Segmentation in non-resilient floor covering reveals divergent capital requirements and margin structures across material categories. Installation methodology and end-use specifications further fragment procurement patterns, creating distinct competitive arenas with varying barriers to entry.
Product Type:
Capital intensity separates these segments sharply, with vitrified ceramic production requiring kiln infrastructure investments that laminate and vinyl converters avoid entirely.
- Ceramic Tiles:Fired clay compositions achieve Mohs hardness ratings above 7 through roller-hearth kiln processing at temperatures exceeding 1200°C. Demand concentrates in India's urban residential corridors where Kajaria Ceramics and domestic rivals anchor organized retail supply under tightening BIS dimensional stability mandates.
- Vinyl Tiles:PVC-based calendered or extruded sheets incorporate printed decorative layers with wear-resistant polyurethane coatings. US healthcare and food-service specification favors glue-down vinyl systems meeting EPA volatile organic compound emission limits for moisture-critical environments.
- Laminate:High-density fiberboard cores with melamine-impregnated decorative paper face layers.
- Hardwood:Solid timber planks or engineered multi-ply constructions requiring moisture-acclimation protocols.
Ceramic tiles absorb the bulk of installed capacity; vinyl tiles are expanding most quickly.
Installation Method:
Application environment dictates method selection, with moisture exposure and substrate conditions determining labor skill requirements and project timelines.
- Glue-Down:Direct adhesive bonding to prepared substrates creates impermeable seams essential for hospital operating theaters and commercial kitchens. EPA regulations on adhesive volatile organic compound emissions constrain product formulation choices for US-based installers.
- Floating:Interlocking edge profiles enable rapid deployment without subfloor penetration. Multi-family residential renovation in US metro corridors favors floating laminate and luxury vinyl systems for speed and labor cost reduction.
- Nail-Down:Mechanical fastening through tongue-and-groove profiles into wood subfloors.
- Grout:Cementitious or epoxy joint filling for ceramic and porcelain tile assemblies.
Glue-down methods retain the largest installed base; floating systems are climbing the fastest.
End User:
Performance specifications and warranty expectations diverge sharply across these demand channels, with commercial and hospitality procurement teams consolidating vendor panels.
- Residential:Individual homeowners and multi-family developers prioritize aesthetic flexibility and installation speed over extended performance warranties.
- Commercial:Office and retail developers demand static load ratings and slip-resistance certifications for high-traffic atrium spaces.
- Industrial:Manufacturing and warehouse facilities require chemical resistance and point-load capacity for heavy machinery.
- Hospitality:Hotel and resort developers in Dubai and Singapore specify thin-format large porcelain panels for seamless visual continuity in high-traffic atrium spaces.
Residential channels absorb the bulk of volume; hospitality specification is gaining share fastest.
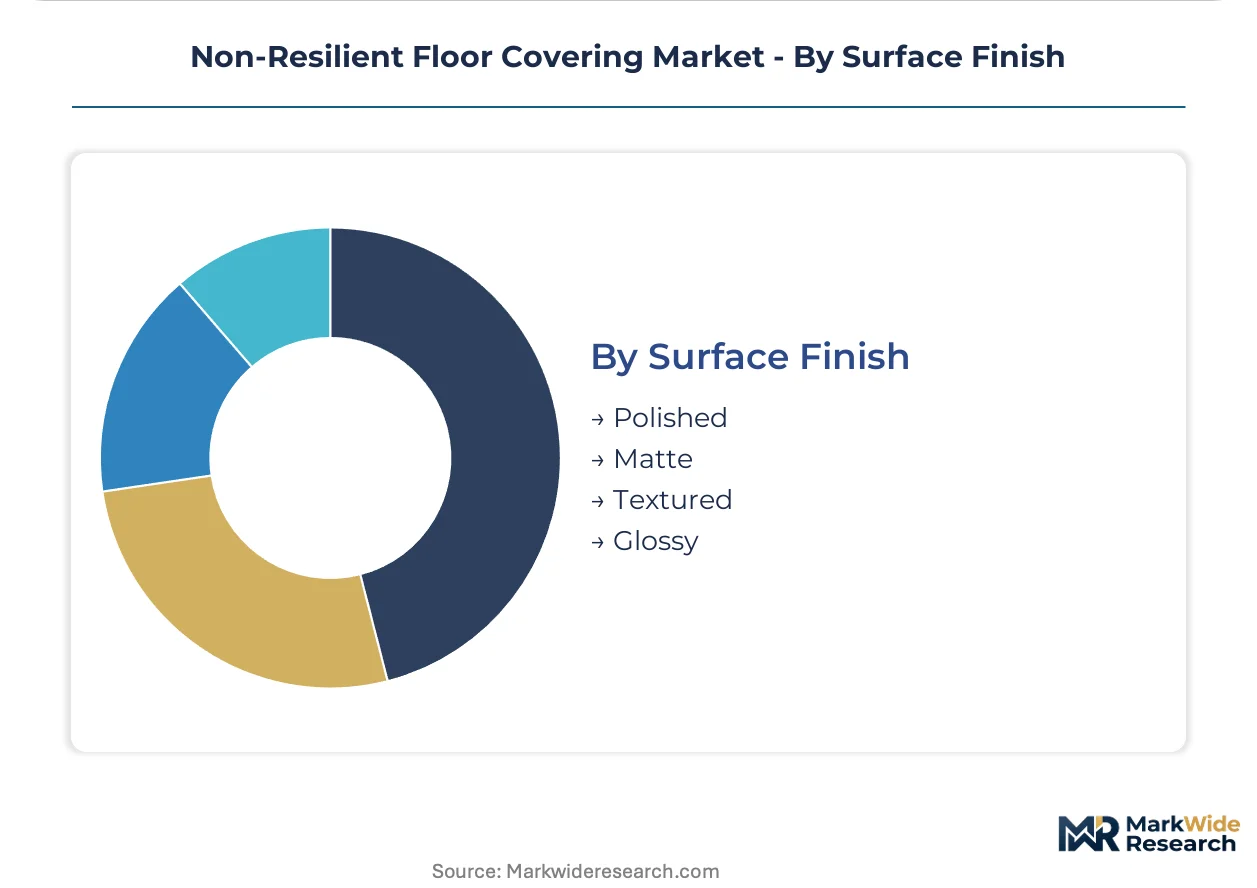
Surface Finish:
Manufacturing process steps and material inputs create tiered pricing structures across these aesthetic categories.
- Polished:Mechanical honing and buffing of vitrified surfaces achieves mirror reflectance.
- Matte:Controlled surface texture reduces glare and slip hazard in commercial corridors.
- Textured:Embossed or relief patterns enhance slip resistance for wet-area applications.
- Glossy:Glaze coatings create reflective surfaces with stain-resistant properties.
Matte finishes absorb the bulk of commercial specification; textured surfaces are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban residential construction corridors concentrate demand for vitrified ceramic tiles, while China's export-oriented manufacturers navigate tightening GB standards on formaldehyde emissions and radioactive nuclide limits.
United States
Healthcare facility construction and commercial kitchen renovation drive specification of glue-down ceramic and porcelain systems. EPA regulations on volatile organic compound emissions from adhesives constrain installer product choices. Manufacturing clusters in Georgia and California anchor domestic supply chains for institutional-grade flooring.
China
SAMR enforcement of GB standards on radioactive nuclide limits in ceramic tiles compresses margins for export-oriented producers. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate kiln operations serving Asia-Pacific commercial real estate developers.
India
Government housing schemes and metro corridor expansion channel investment into organized tile retail networks. BIS certification for ceramic tile dimensional stability creates compliance thresholds filtering smaller competitors. Gujarat and Rajasthan ceramic clusters scale production to capture urban residential densification demand.
Germany
REACH restrictions on crystalline silica in construction materials accelerate water-jet and dry-cutting equipment adoption across fabricator workshops. Energy-intensive kiln operations face margin pressure from natural gas price volatility. The North Rhine-Westphalia industrial corridor hosts shared cutting facility investments distributing compliance costs.
United Arab Emirates
Hospitality developers in Dubai specify thin-format large porcelain panels for high-traffic atrium spaces requiring seamless visual continuity. MOHAP building codes influence material specification for healthcare and commercial projects. Jebel Ali industrial zone concentrates import-distribution infrastructure serving Gulf Cooperation Council construction corridors.
Non-Resilient Floor Covering Market Competitive Landscape
Backward integration into raw material deposits dominates the current landscape, with North American manufacturers leveraging captive quarry access to sustain cost-advantaged output. The vendor base separates into three tiers: multinational conglomerates with integrated supply chains, regional specialists controlling distributor networks, and unorganized local producers facing certification barriers. Two strategic archetypes define positioning—scale-driven kiln operators competing on manufacturing throughput, and design-focused fabricators differentiating through surface aesthetic innovation. M&A activity and capacity expansion in India represent the dominant competitive vectors.
Among North American conglomerates, Mohawk Industries and Shaw Industries Group exemplify scale-driven archetypes with integrated fiber and quarry operations. Kajaria Ceramics Limited occupies a position within the regional specialist tier, anchoring India's organized retail channel through extensive distributor controls. These three entities represent divergent strategic postures—multinational vertical integration versus emerging market channel dominance—illustrating how geographic market structure shapes competitive positioning.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Mannington Mills, Inc. |
| Kajaria Ceramics Limited |
| Daltile |
| Porcelanosa Grupo A.I.E. |
| Crossville Inc. |
| IVC-Group |
| Polyflor Ltd |
| Others |
Value Network & Pricing Analysis
Certified moisture-mitigation installers in Gujarat and Rajasthan ceramic clusters anchor labor-cost differentials that widen pricing-tier spreads between glue-down healthcare specification and floating residential systems. Kajaria Ceramics and domestic rivals leverage this workforce concentration to compress installation labor premiums against European and North American benchmarks.
Pricing Analysis
Extended performance warranties that bundle material supply with installation labor separate premium hospitality specification from unbundled residential procurement. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—BIS dimensional stability marking filters unorganized competitors into economy tiers. Price erosion runs through laminate segments as luxury vinyl tile substitution accelerates in US multi-family renovation. Healthcare and food-service developers demonstrate least price sensitivity given moisture-critical code requirements.
Supply Chain Analysis
Container freight rate volatility from Yangtze River Delta and Pearl River Delta manufacturing belts to Jebel Ali and Singapore construction corridors compresses margin buffers for export-oriented producers. Ceramic tile supply draws from China, India, and Italy as dominant kiln operation geographies. Feldspar, kaolin, and natural gas inputs feed from captive quarry deposits and spot LNG markets respectively. Single-source vulnerability concentrates in glaze chemistry formulations held by Italian specialist suppliers. Distribution runs through organized retail networks in India and specification-driven dealer channels in US institutional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-format large porcelain panel technology is displacing traditional ceramic tile and natural stone in hospitality atrium specification, compressing product lifecycles while opening premium contract channels.
For Market Incumbents: Extend captive quarry access into downstream panel fabrication capacity to defend margin position against raw material volatility. Anchor specification relationships with sovereign wealth-backed hospitality developers through integrated subfloor system warranties. Counter luxury vinyl tile substitution by accelerating large-format porcelain cost reduction in residential channels. For New Entrants and Emerging Players: Digital surface aesthetic technology offers entry wedge into design-focused specification segments underserved by scale-driven kiln operators. Target India's BIS certification gaps among unorganized Rajasthan and Gujarat producers as acquisition-ready supply sources. Pursue modular prefabrication partnerships with offsite construction contractors in student housing and healthcare verticals. For Investors and Strategic Acquirers: Re-rating potential sits with laboratory-infrastructure-equipped regional specialists given India's tightening dimensional stability mandates and carbon-border adjustment preparation timelines. Long-term viability centers on embodied-carbon documentation capabilities across ceramic supply chains. Monitor EU CBAM implementation velocity as inflection indicator for certification premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Expansion | Mohawk Industries leverages North American feldspar deposits to sustain cost-advantaged porcelain output against volatile raw material markets. |
| Large-Format Panel Fabrication | Hospitality developers in Dubai consolidate vendor panels around thin-format porcelain systems with integrated subfloor warranties. |
| BIS Certification Infrastructure | Organized Indian players acquire laboratory capabilities to filter unorganized competitors under tightening dimensional stability mandates. |
| Carbon Footprint Documentation | Early movers in EU export channels capture certification premiums ahead of CBAM implementation timelines. |
| Modular Prefabrication Partnerships | Factory-finished porcelain panels open specification channels in offsite construction for hospitality and student housing. |
Research Methodology
Trade association publications, customs export-import databases, and SEC 10-K filings formed the secondary backbone, cross-referenced against primary interviews with ceramic plant managers, hospitality procurement directors, healthcare facility architects, and distributor network heads. Bottom-up volume triangulation across product type, installation method, and end-user segments converged with top-down macro construction spend analysis.
Historical trendline analysis of kiln capacity utilization, raw material input costs, and specification channel mix informed projection framework construction across material category, surface finish, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate construction output forecasts incorporated natural gas price volatility assumptions and carbon-border adjustment scenario weighting.
Several conditions sit outside the modeled scope, including sudden GB standard enforcement shifts in China, sovereign wealth fund liquidity contractions in Gulf Cooperation Council hospitality development, and breakthroughs in bio-based ceramic binders. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Carpet Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
China Wood Flooring Market