
 India Laminate Flooring Market | 2026-2036
India Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
India Laminate Flooring Market Foresight
Multi-source procurement among laminate flooring distributors is shifting toward direct mill partnerships in Gujarat and Punjab. Greenlam Industries leverages captive resin production to control raw material costs across its laminate portfolio. Inovar Floors India anchors its position through specialized high-traffic commercial-grade product lines. QuickStep competes on European design licensing and scratch-resistant surface technology.
Laminate flooring consists of a high-density fiberboard core bonded with decorative paper and aluminum oxide wear layers, manufactured through direct-pressure or high-pressure lamination processes. The 12 mm thickness category dominates residential replacement cycles due to superior acoustic dampening and subfloor tolerance. Commercial end-user demand concentrates among contractor-specified projects, where textured surface finishes command premium positioning over smooth alternatives. Specialty product types occupy niche margin pools in healthcare and education verticals requiring anti-bacterial surface treatments.
BIS mandates IS 12823 compliance for laminate flooring abrasion resistance and formaldehyde emission limits, compelling domestic manufacturers to upgrade testing infrastructure. India's PLI scheme for wood-based panels indirectly subsidizes laminate substrate capacity expansion. State-level RERA enforcement across Maharashtra, Karnataka, and Telangana standardizes builder material disclosures. Stakeholders must monitor evolving ESG disclosure requirements under BRSR mandates and their downstream impact on certified sustainable sourcing claims.
Market Dynamics
Residential real estate developers in Maharashtra and Gujarat are consolidating material specifications toward standardized laminate flooring SKUs, compressing distributor margins while accelerating direct mill procurement relationships across western India.
Growth Catalysts
- Maharashtra RERA Enforcement:Mandatory builder disclosure requirements standardize laminate flooring specifications across Mumbai and Pune metro projects, reducing specification variance and accelerating procurement cycles.
- Urban Housing Stock Renewal:Accelerated replacement of aging flooring stock in Ahmedabad and Surat residential complexes drives 12 mm thickness category demand for acoustic performance.
- IS 12823 Compliance Infrastructure:BIS-mandated testing upgrades among domestic manufacturers improve product consistency and reduce import dependency for certified abrasion-resistant grades.
Market Restraints
- Formaldehyde Emission Compliance Costs:E1-grade resin systems required under BIS limits raise substrate production costs by 15-20% versus uncertified alternatives.
- Decorative Paper Import Concentration:European and Korean suppliers control 70% of high-fidelity print paper supply, exposing domestic laminators to currency volatility and extended lead times.
- Vinyl Flooring Substitution:Luxury vinyl tile (LVT) products with waterproof cores capture moisture-prone kitchen and bathroom applications previously served by laminate.
Strategic Opportunities
- Tier-II City Penetration:Underdeveloped distribution infrastructure in Indore, Nagpur, and Coimbatore creates first-mover advantage for organized brands establishing retail-showroom networks.
- Anti-Bacterial Surface Treatments:Healthcare and education verticals in Karnataka and Telangana specify certified hygienic flooring, opening premium-margin specialty product lines.
- PLI Scheme for Wood-Based Panels:Central government production-linked incentives subsidize high-density fiberboard capacity expansion, lowering core material costs for domestic laminate producers.
Industry Challenges
- Skilled Installation Labor Scarcity:Floating-floor installation certification remains fragmented across state-level vocational programs, causing quality variance and callback rates in contractor-specified projects.
- Multi-Standard Certification Timelines:Concurrent BIS, Green Rating for Integrated Habitat Assessment (GRIHA), and private eco-label compliance extends product launch cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Laminate Flooring Market |
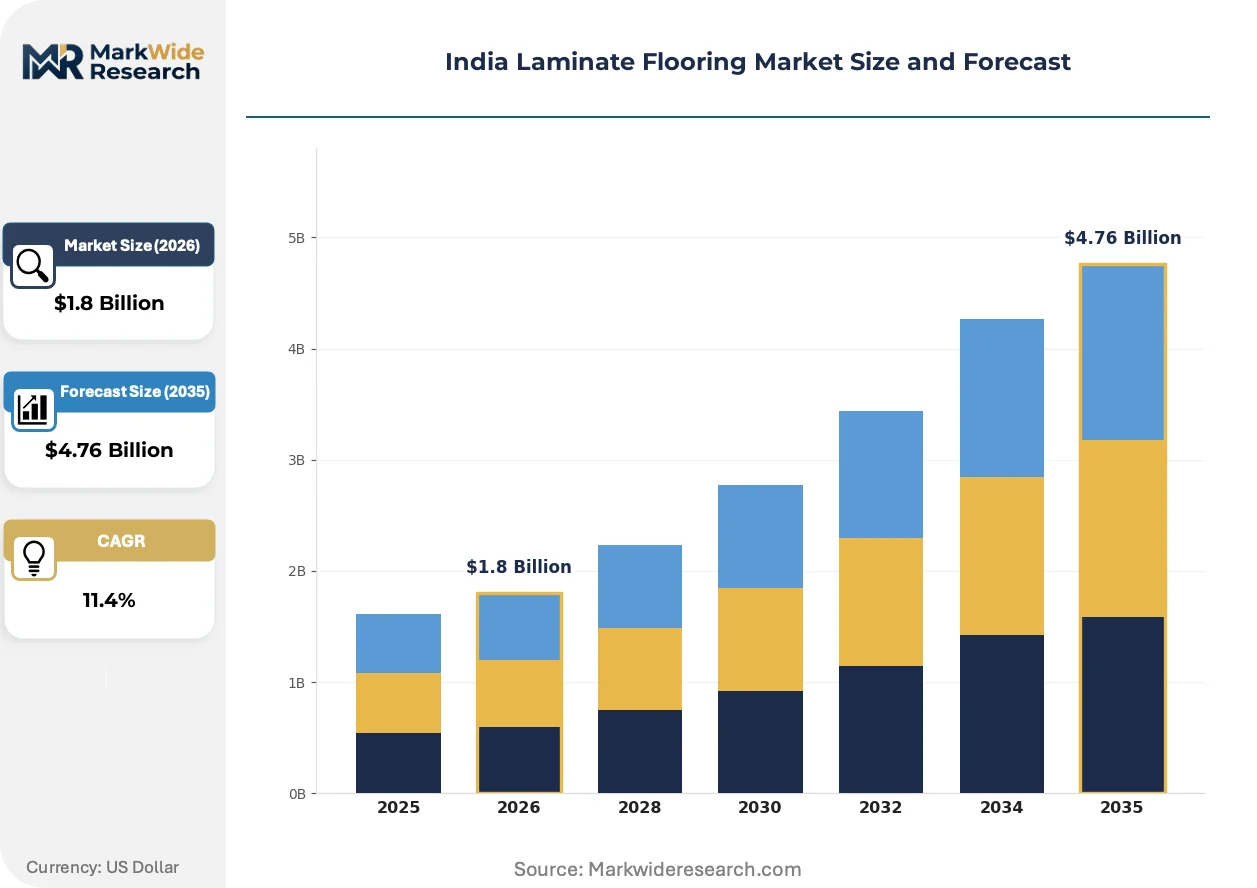
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Specialty Thickness: 8 mm, 10 mm, 12 mm, 15 mm Surface Finish: Smooth, Textured, Glossy, Matte End User: Homeowners, Contractors, Retailers, Builders |
| Companies Covered | Notion Flooring, Accord Floors, Inovar Floors India, Pergo, Surfaces India Flooring Pvt. Ltd, BVG Flooring, Marco Polo Flooring, QuickStep, Greenlam Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Laminate Flooring Market Shifts & Advancements
Surface engineering and specification digitization are compressing traditional product lifecycles while reshaping how developers source flooring materials across Indian metropolitan corridors.
Aluminum oxide-enhanced wear layers with embossed-in-register texture technology are absorbing premium positioning from smooth-finish alternatives in high-traffic commercial specifications. Mumbai and Bengaluru commercial fit-out contractors specify these surfaces for retail and hospitality applications where slip resistance and scratch performance outweigh initial cost premiums. The technology is absorbing margin compression in standard-grade segments by enabling tiered pricing based on abrasion class ratings rather than thickness alone.
BIS IS 12823:2022 amendments tightening formaldehyde emission thresholds are forcing substrate producers to migrate from urea-formaldehyde to melamine-fortified resin systems. Domestic high-density fiberboard mills in Gujarat and Punjab are retrofitting press lines to meet E1-grade certification, with compliance costs passed through to laminate flooring manufacturers. Maharashtra and Karnataka project developers now mandate certified emission documentation in tender specifications, filtering non-compliant imports from Southeast Asian suppliers.
Direct mill partnerships are replacing multi-tier distribution for volume residential projects in western India. Large developers in Ahmedabad and Pune negotiate annual framework agreements with laminate producers, bypassing traditional distributor markups while securing specification lock-in for multi-phase construction. This procurement model shift is most visible in affordable housing segments where material cost transparency determines project viability under RERA-mandated disclosure requirements.
India Laminate Flooring Market Segmentation
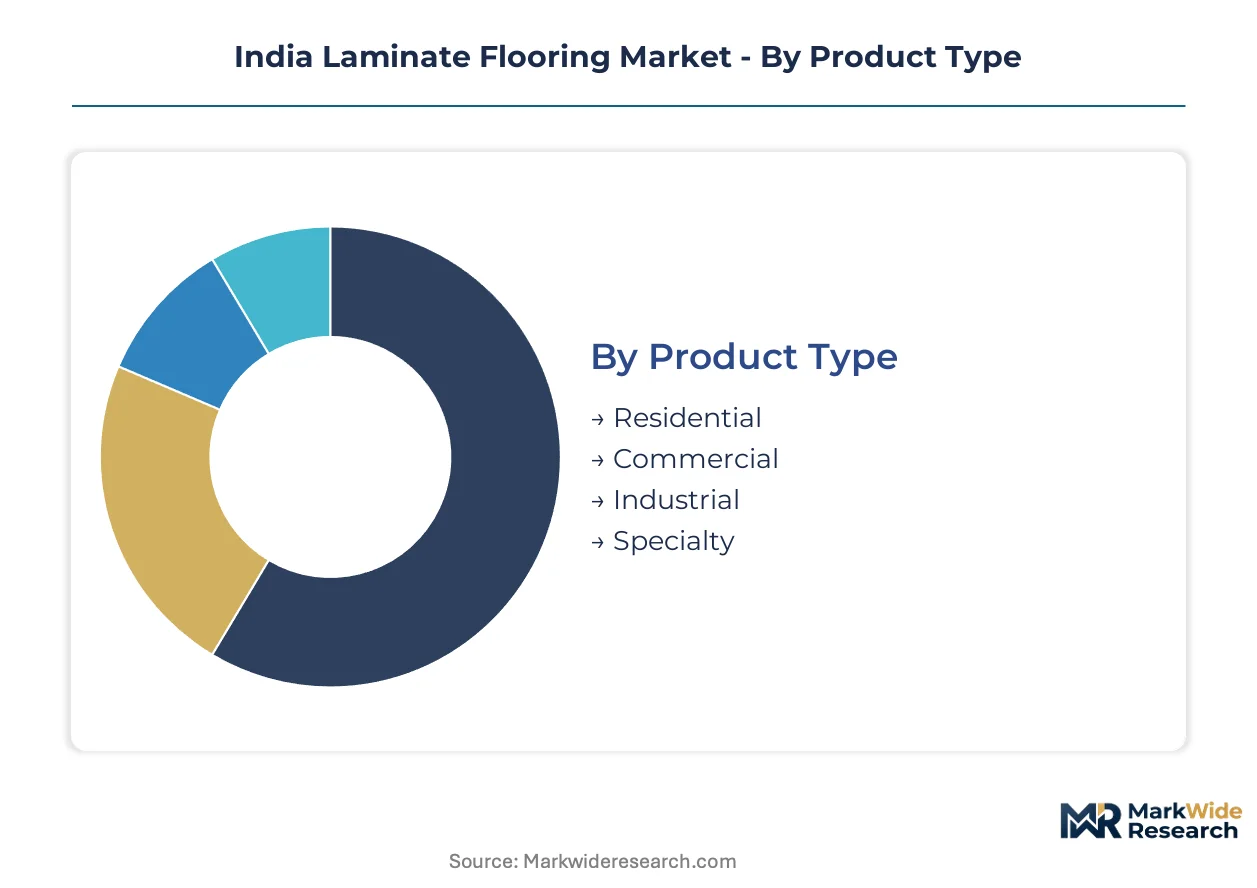
Segmentation in the India laminate flooring market determines which BIS certification tiers apply, where procurement channels concentrate, and how margin structures vary across specification intensity. Each dimension carries distinct regulatory and commercial logic that shapes manufacturer positioning and distributor economics.
Product Type:
BIS IS 12823 compliance requirements vary sharply across product type segments, with residential and commercial grades facing mandatory abrasion class certification while specialty products must clear additional anti-bacterial and slip-resistance protocols under healthcare-specific tender rules.
- Residential:High-density fiberboard cores with E1-grade formaldehyde certification dominate Maharashtra and Gujarat apartment specifications. Mumbai developers under RERA disclosure mandates are consolidating procurement around standardized 12 mm SKUs, compressing distributor margins while accelerating direct mill relationships.
- Commercial:Aluminum oxide-enhanced wear layers with embossed-in-register textures absorb premium positioning in Bengaluru retail and hospitality fit-outs. Contractor-specified projects in Mumbai command documented abrasion resistance ratings, filtering non-compliant Southeast Asian imports from tender participation.
- Industrial:Heavy-load tolerance specifications serve warehousing and logistics verticals in Pune and Chennai industrial corridors.
- Specialty:Anti-bacterial surface treatments target Karnataka and Telangana healthcare and education tenders requiring certified hygienic flooring documentation.
Residential sits at the top of the volume ranking, with Specialty climbing the fastest.
Thickness:
Thickness selection directly correlates with acoustic performance requirements and subfloor condition tolerance, driving cost tier differentiation across replacement versus new construction cycles.
- 12 mm:Superior acoustic dampening properties anchor dominance in Ahmedabad and Surat housing stock renewal projects. The category commands specification lock-in from Pune developers pursuing RERA-compliant material disclosure transparency across multi-phase construction.
- 8 mm:Entry-level pricing enables affordable housing penetration in Indore and Nagpur where cost transparency determines project viability under state-level enforcement.
- 10 mm:Mid-tier positioning balances performance and cost for secondary city residential retrofit demand.
- 15 mm:Premium acoustic and structural tolerance serves high-end commercial specifications in Mumbai and Bengaluru luxury retail.
12 mm maintains the dominant volume position, while 8 mm gains share fastest in emerging tier-II markets.
Surface Finish:
Finish selection determines slip-resistance certification requirements and maintenance protocol intensity, with textured surfaces commanding contractor preference in high-traffic commercial specifications.
- Textured:Embossed-in-register technology delivers slip resistance and scratch performance for Bengaluru retail and hospitality applications. Mumbai commercial fit-out contractors specify these surfaces where safety ratings outweigh initial cost premiums in tender evaluations.
- Smooth:Lower maintenance requirements serve residential replacement cycles in Gujarat urban housing complexes prioritizing cleaning efficiency over abrasion concealment.
- Glossy:Reflective aesthetics target premium residential segments in Pune and Mumbai where visual impact drives specification.
- Matte:Concealed wear patterns appeal to high-traffic education and healthcare verticals in Telangana.
Textured leads volume in commercial applications, with Matte expanding most quickly in institutional verticals.
End User:
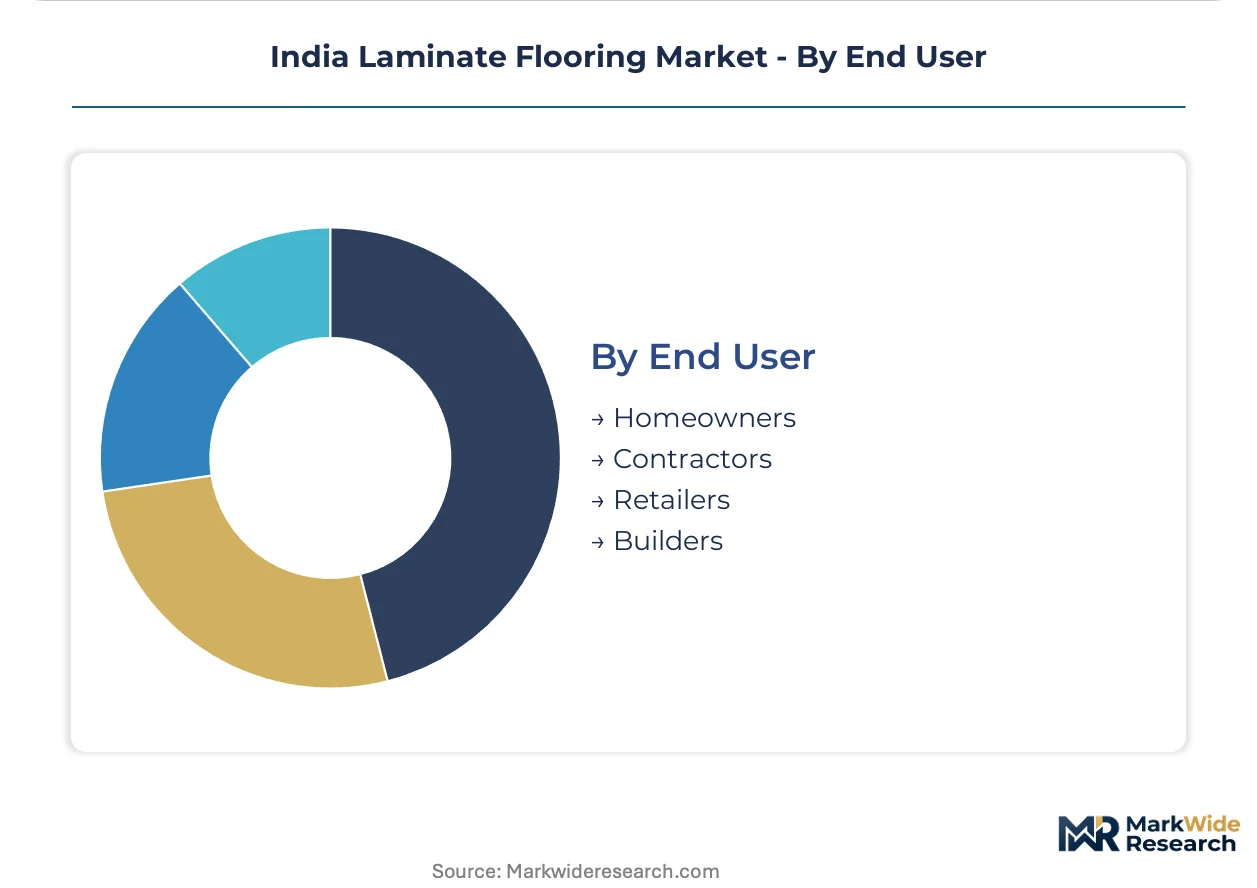
End user type determines procurement channel structure, with builders and contractors driving direct mill partnerships while homeowners and retailers sustain traditional distribution markups.
- Builders:Large Ahmedabad and Pune developers negotiate annual framework agreements bypassing distributor tiers, securing specification lock-in and cost transparency for RERA-mandated disclosures. Direct procurement concentrates in western India affordable housing segments.
- Contractors:Commercial fit-out specialists in Mumbai and Bengaluru specify abrasion-class-rated products with documented BIS compliance, filtering tender participation to certified domestic manufacturers.
- Homeowners:Replacement-driven demand in Surat and Ahmedabad residential complexes flows through retail-showroom networks with installation service bundling.
- Retailers:Multi-brand flooring distributors in Maharashtra face margin compression as organized brands establish proprietary showroom networks in tier-II cities.
Builders occupy the top volume tier, with Contractors gaining procurement influence fastest in metropolitan commercial fit-out markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Mumbai-Pune corridor anchors India's laminate flooring demand through RERA-mandated builder disclosures and accelerated residential project pipelines. State-level enforcement standardizes material specifications while compressing procurement cycles across western India's urban housing renewal.
Maharashtra
Mumbai developers under RERA disclosure mandates consolidate procurement around standardized 12 mm SKUs for multi-phase affordable housing projects. BIS IS 12823 compliance documentation filters non-certified imports from Southeast Asian suppliers. Pune's contractor-specified commercial fit-outs drive abrasion-class-rated product demand in retail and hospitality verticals.
Gujarat
Ahmedabad and Surat residential complexes accelerate aging flooring stock replacement, prioritizing acoustic performance in 12 mm thickness categories. The state's PLI scheme for wood-based panels subsidizes high-density fiberboard capacity expansion among domestic substrate producers. Direct mill partnerships bypass traditional distributor tiers in volume residential developments.
Karnataka
Bengaluru commercial fit-out contractors specify aluminum oxide-enhanced wear layers with embossed-in-register textures for retail applications. Healthcare and education tenders in the state mandate certified anti-bacterial surface treatments, opening premium-margin specialty product lines. State-level vocational programs address skilled installation labor gaps in floating-floor certification.
Telangana
Hyderabad's healthcare infrastructure expansion specifies hygienic flooring documentation for hospital and clinic verticals. Institutional end-users in the state prioritize matte surface finishes that conceal wear patterns in high-traffic education facilities. Local distributors face margin compression as organized brands establish proprietary showroom networks.
Tamil Nadu
Chennai's industrial warehousing corridors drive heavy-load tolerance specifications in logistics flooring applications. The state's housing stock renewal concentrates in secondary city residential retrofits where 8 mm entry-level pricing enables cost-transparent project viability. Multi-brand distributors sustain traditional markups among homeowner-driven replacement demand.
India Laminate Flooring Market Competitive Landscape
Global majors compete with regional champions across certification tiers and procurement channel structures. The vendor base stratifies between European design licensors, domestic integrated manufacturers, and specialized commercial-grade producers. Three archetypes dominate: captive resin producers controlling substrate costs, licensed technology partners leveraging European surface engineering, and vertical specialists targeting healthcare-education verticals. Capacity expansion and direct mill partnerships represent the dominant competitive moves reshaping distributor economics.
Among domestic integrated manufacturers, Greenlam Industries and Inovar Floors India exemplify contrasting strategic positions. Greenlam occupies the captive production archetype through backward integration into resin systems. Inovar Floors India anchors the commercial-grade specialization vector with documented high-traffic performance credentials. QuickStep represents the European technology licensing tier, competing on surface durability patents and design import relationships. These three illustrate how certification infrastructure and procurement channel control determine competitive positioning under tightening BIS mandates.
| Leading Market Players |
|---|
| Notion Flooring |
| Accord Floors |
| Inovar Floors India |
| Pergo |
| Surfaces India Flooring Pvt. Ltd |
| BVG Flooring |
| Marco Polo Flooring |
| QuickStep |
| Greenlam Industries |
| Others |
Supply & Pricing Matrix
Decorative paper import indices from European and Korean suppliers cascade through laminate flooring manufacturing tiers, compressing margins for domestic laminators lacking direct mill partnerships while amplifying pricing power for integrated producers with captive resin systems. BIS IS 12823 compliance costs for E1-grade substrate certification stratify pricing across certified and uncertified supply tiers, with Maharashtra and Gujarat developers absorbing premiums for documented emission documentation.
Pricing Analysis
Input-cost pass-through from melamine-fortified resin systems and aluminum oxide wear layers stratifies pricing across three performance tiers. Price differentiation hinges on BIS abrasion class certification and direct mill procurement scale, with volume residential developers in Pune and Ahmedabad securing framework-rate transparency. Cost compression in standard-grade segments intensifies as vinyl flooring substitution erodes moisture-prone application pricing. Affordable housing builders exhibit highest price sensitivity, while Bengaluru commercial fit-out contractors prioritize documented performance ratings over initial cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for wood-based panels are redirecting high-density fiberboard sourcing toward Gujarat and Punjab substrate mills. Raw material dependencies center on European decorative paper, Korean overlay films, and domestic resin systems. Single-source vulnerability concentrates in decorative paper supply, with currency volatility exposing laminators to margin erosion. Distribution runs through direct mill partnerships for volume builders and proprietary showroom networks for organized brands in tier-II cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India laminate flooring market functions as a geographic-arbitrage opportunity, with PLI-subsidized substrate capacity in Gujarat and Punjab offering 15-20% cost advantages against import-dependent competitors in Maharashtra and Karnataka.
For Market Incumbents: To counter vinyl flooring substitution in moisture-prone applications, domestic integrated manufacturers should deepen backward integration into captive melamine resin production and secure exclusive annual framework agreements with RERA-mandated developers in Pune and Ahmedabad. Certification investment in anti-bacterial surface treatments creates defensive positioning against specialty-product entrants in Karnataka healthcare tenders. For New Entrants and Emerging Players: Regional distributor partnerships in Indore, Nagpur, and Coimbatore offer the most penetrable white-space target, as underdeveloped retail-showroom infrastructure leaves tier-II cities exposed to first-mover capture. A direct-to-contractor specification strategy targeting Bengaluru commercial fit-out specialists bypasses entrenched multi-brand distribution and leverages documented BIS compliance as a tender-entry credential. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic substrate producers possessing E1-grade certification infrastructure and PLI scheme eligibility, as regulatory tightening under BIS IS 12823 amendments structurally disadvantages import-dependent laminators. The inflection signal to monitor is Maharashtra RERA enforcement extending disclosure mandates to secondary city municipal corporations, which would replicate Ahmedabad procurement-transparency dynamics across untapped geographies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Systems | Captive melamine production insulates Greenlam Industries from Korean import price volatility. |
| Direct Mill Partnership Expansion | Pune developers bypass distributor markups through annual framework agreements with laminate producers. |
| Anti-Bacterial Surface Certification | Healthcare tenders in Karnataka and Telangana mandate hygienic flooring documentation for hospital verticals. |
| Tier-II City Showroom Network Buildout | Organized brands establish proprietary retail presence in Indore and Nagpur ahead of distributor consolidation. |
| PLI Scheme Capacity Expansion | Central subsidies for wood-based panels lower high-density fiberboard costs for Gujarat substrate mills. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, Telangana, and Tamil Nadu, with primary inputs from each state combining structured interviews with residential real estate developers, commercial fit-out contractors, laminate flooring distributors, BIS certification auditors, and substrate plant managers. Secondary validation draws from BIS notification records, state RERA disclosure filings, PLI scheme administrative data, and customs import statistics for decorative paper and overlay films. Bottom-up channel checks triangulate against top-down market sizing across product type, thickness, and end-user segments.
Granularity-level modeling disaggregates volume and value projections by residential-commercial-specialty product tiers, 8-10-12-15 mm thickness categories, and builder-contractor-homeowner-retailer procurement channels across the projection horizon. CAGRs derive from replacement cycle analysis in Ahmedabad and Surat housing stock, RERA-mandated project pipeline tracking in Mumbai and Pune, and PLI capacity addition schedules for Gujarat and Punjab substrate mills. Industry-specific inputs include BIS IS 12823:2022 amendment implementation timelines and state-level vocational program expansion for floating-floor installation certification.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to decorative paper import price volatility, vinyl flooring substitution rates in moisture-prone applications, and BIS enforcement intensity across secondary city municipal jurisdictions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market