
 US Wood Flooring Market | 2026-2036
US Wood Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
US Wood Flooring Market Insights
A capital-intensity divergence between integrated hardwood processors and specialty importers is bifurcating the US wood flooring competitive landscape. Mohawk Industries leverages captive timber sourcing and resin formulation capabilities to sustain margin control across engineered wood lines. Somerset Hardwood Flooring anchors its position through Appalachian oak procurement networks and kiln-drying infrastructure. Mannington Mills differentiates via multi-channel distribution spanning big-box retail and independent flooring contractors.
Wood flooring comprises finished or unfinished timber products installed as interior walking surfaces, typically milled to thicknesses between three-eighths and three-quarters of an inch with wear-layer specifications dictating refinishing cycles and service life. Solid wood planks retain premium positioning in historic restoration and high-end residential applications where dimensional stability concerns are manageable. Engineered wood dominates new residential construction due to cross-layered plywood or high-density fiberboard cores that resist moisture deformation in slab-on-grade installations. Click-lock floating systems are gaining share among renovation contractors seeking reduced labor time and subfloor preparation costs.
The EPA enforces TSCA Title VI formaldehyde emission limits on composite wood products, compelling domestic manufacturers to maintain third-party certification and chain-of-custody documentation. The California Air Resources Board maintains ATCM Phase 2 standards that frequently preempt federal thresholds, creating a dual-compliance burden for national distribution strategies. USDA Biopreferred program specifications and LEED v4.1 low-emitting materials credits shape specification behavior among institutional and commercial buyers. Stakeholders must monitor evolving Lacey Act enforcement on imported timber species documentation and assess how pending FSC supply-chain verification requirements will filter accessible raw material pools.
Market Dynamics
Cross-layered core engineering is compressing moisture-deformation failure rates in slab-on-grade installations, forcing domestic manufacturers to retool kiln-drying and pressing infrastructure around dimensional stability specifications rather than traditional solid-plank aesthetics.
Growth Catalysts
- Residential renovation acceleration:Aging housing stock in Texas and Florida drives engineered wood demand for click-lock floating systems that reduce subfloor preparation costs.
- EPA TSCA Title VI enforcement:Third-party certification requirements for composite wood products filter out non-compliant imports, tightening supply for certified domestic producers.
- Cross-laminated timber cores:High-density fiberboard and plywood layering technologies enable wider plank formats in moisture-prone basements and ground-level installations.
Market Restraints
- Oak procurement concentration:Appalachian hardwood sourcing networks face weather-driven harvest volatility and logging labor shortages.
- Formaldehyde compliance dual burden:California Air Resources Board ATCM Phase 2 standards frequently preempt federal EPA thresholds, forcing national distributors to maintain parallel inventory SKUs.
- Luxury vinyl tile substitution:Waterproof rigid-core LVT captures renovation volume in bathrooms, kitchens, and rental properties where moisture risk deters wood specification.
Strategic Opportunities
- Southeast housing corridor:Florida and Texas sub-markets concentrate multifamily ground-up construction where engineered wood's cost-per-square-foot advantages align with developer pro formas.
- USDA Biopreferred program tailwind:Federal procurement preference for certified biobased products opens institutional specification channels for compliant domestic manufacturers.
- LEED v4.1 low-emitting materials credits:Commercial and educational construction projects weight indoor air quality scoring, favoring third-party certified wood flooring over conventional alternatives.
Industry Challenges
- Installation skill compression:Floating click-lock systems reduce traditional nail-down specialization requirements, eroding contractor differentiation and pressuring training program economics.
- Chain-of-custody documentation:Lacey Act enforcement on imported timber species demands enhanced supplier auditing and customs clearance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wood Flooring Market |
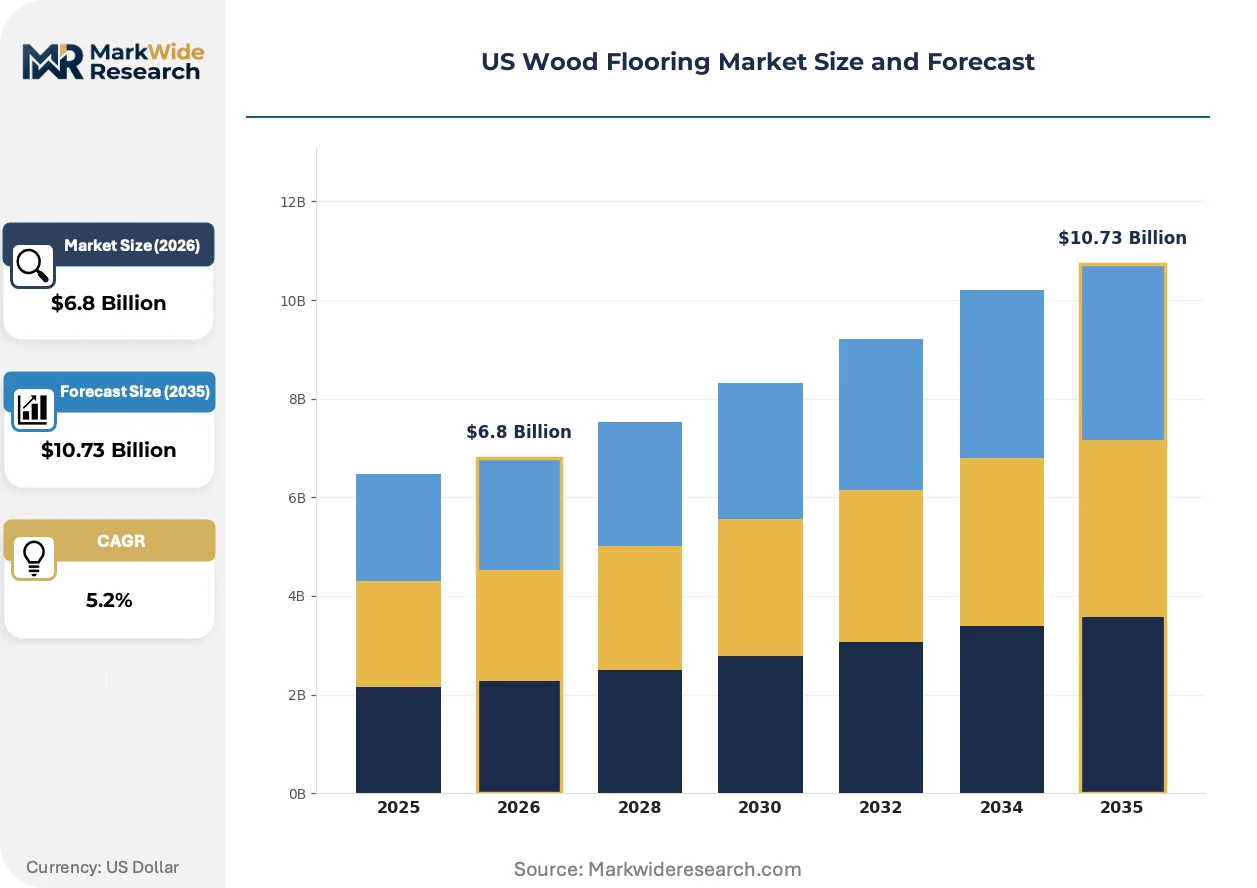
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Wood, Engineered Wood, Laminated Wood, Bamboo Form: Planks, Panels, Tiles, Strips Installation: Nail-down, Glue-down, Floating, Click-lock End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Mannington Mills, Inc., Armstrong Flooring, Inc., Tarkett SA, Pergo, Somerset Hardwood Flooring, Inc., AHF Products, EGGER Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wood Flooring Market Trends and Innovations
Moisture-resistant core engineering and digital specification tools are compressing traditional product lifecycles and reshaping how architects, contractors, and homeowners evaluate performance versus aesthetics trade-offs.
Cross-layered plywood and high-density fiberboard cores with aluminum oxide wear layers are miniaturizing the performance gap between engineered and solid wood in refinishing-cycle durability. Custom home builders in the Southeast specify these systems for slab-on-grade foundations previously restricted to tile or vinyl. The technology is miniaturizing the premium positioning of thick solid planks by delivering equivalent visual warmth with superior dimensional stability.
EPA TSCA Title VI formaldehyde emission limits compel domestic manufacturers to maintain continuous third-party certification and laboratory testing protocols. Composite wood product producers face recurring audit costs and documentation burdens that scale with SKU proliferation. National distributors respond by consolidating supplier relationships around certified domestic mills rather than managing fragmented import documentation.
Homeowner specification behavior increasingly prioritizes refinishing-cycle transparency over initial installed cost. Independent flooring contractors in Texas and Florida report extended consultation phases where wear-layer thickness documentation determines selection. This pattern compresses switching costs between product tiers and rewards suppliers with clear performance labeling and lifecycle cost calculators.
US Wood Flooring Market Segmentation
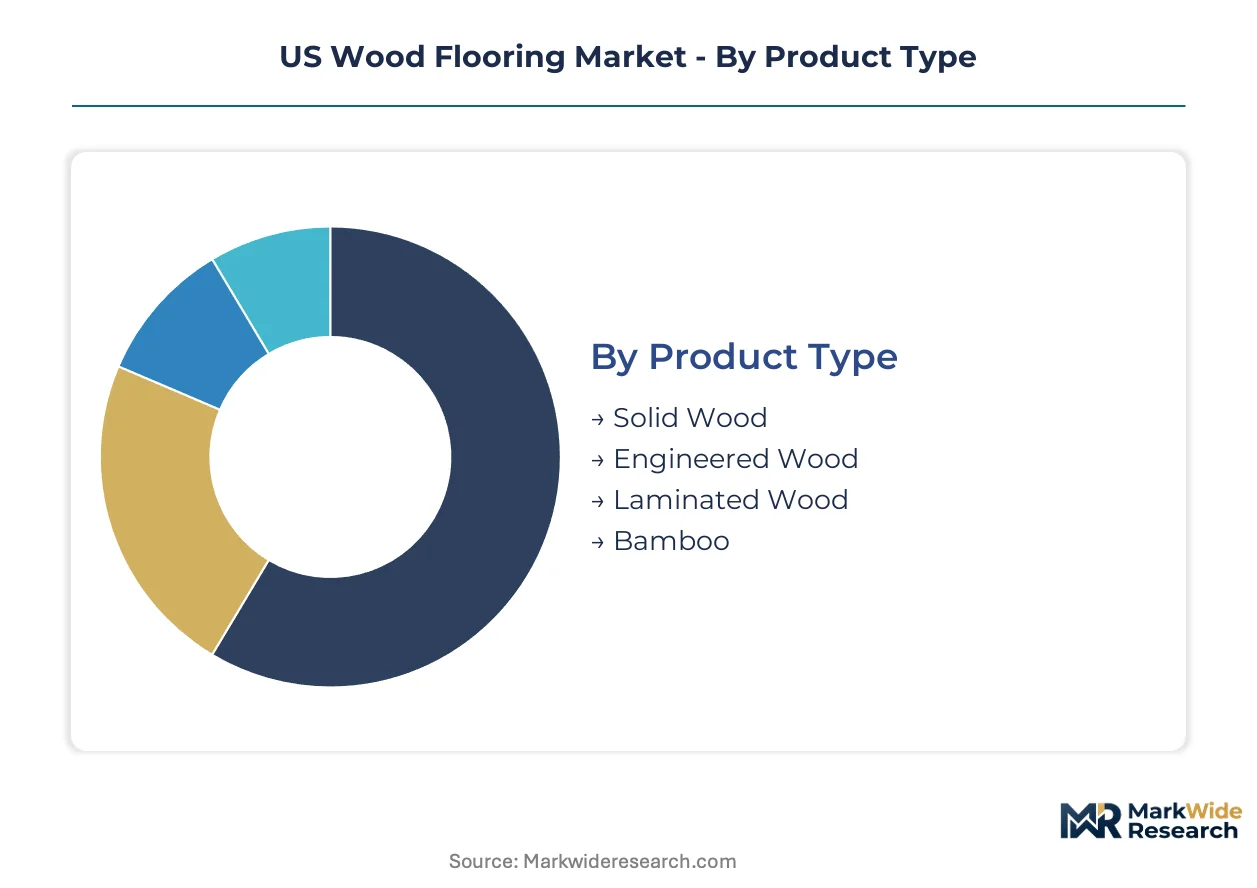
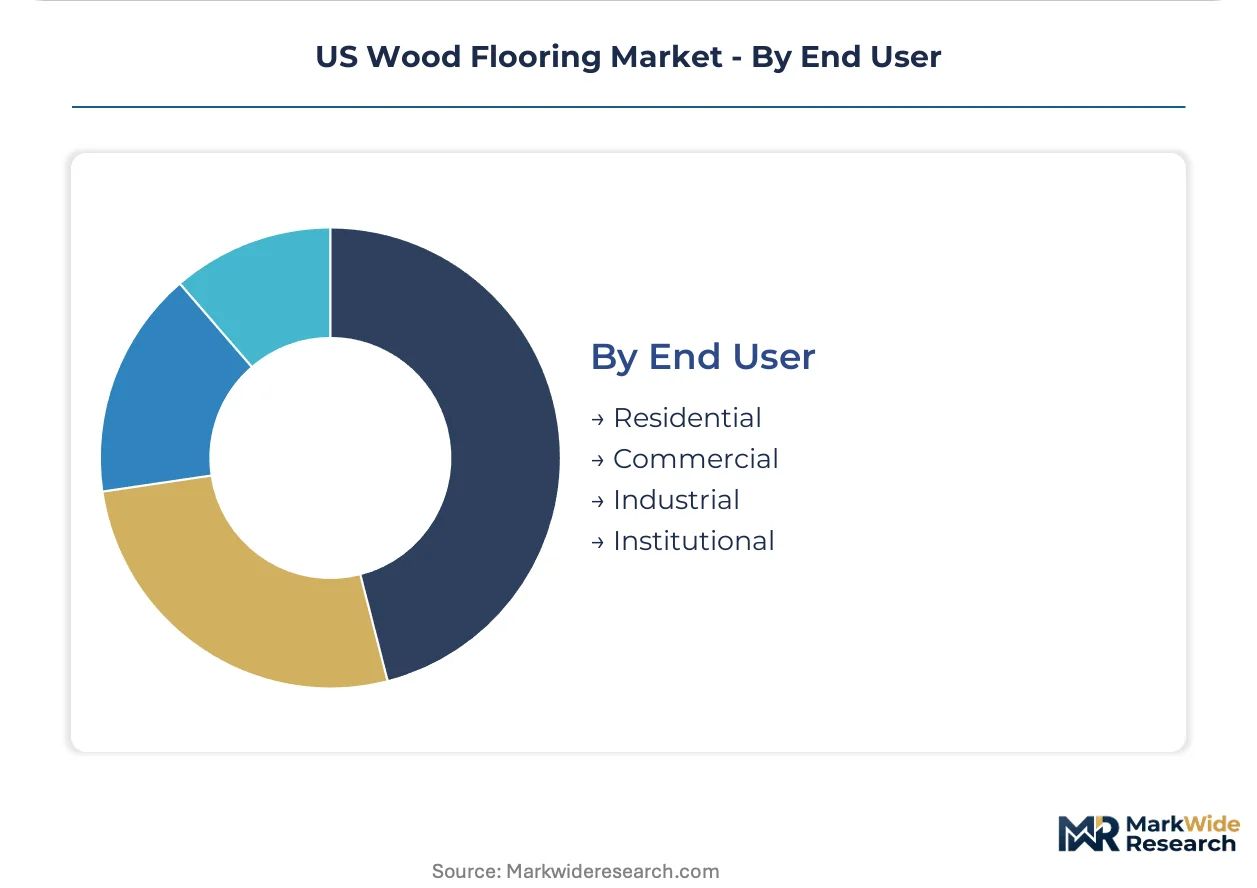
Wood flooring segmentation reveals how EPA TSCA Title VI compliance costs and moisture-performance specifications reshape procurement decisions across product tiers. Understanding these divisions exposes where certification burdens concentrate and where engineered alternatives displace traditional solid wood specification.
Product Type:
EPA formaldehyde emission limits under TSCA Title VI and California Air Resources Board ATCM Phase 2 standards create divergent compliance burdens across material compositions, filtering import availability and reshaping domestic manufacturing investment.
- Engineered Wood:Cross-layered plywood or high-density fiberboard cores deliver dimensional stability for slab-on-grade installations in Texas and Florida residential construction. Click-lock floating systems reduce subfloor preparation costs, accelerating adoption among renovation contractors facing labor compression.
- Solid Wood:Traditional three-quarter-inch planks milled from single timber pieces retain specification in historic restoration and premium residential applications where refinishing-cycle longevity outweighs moisture-deformation risks. Appalachian oak procurement networks from Somerset Hardwood Flooring and similar regional suppliers anchor supply.
- Laminated Wood:Composite core construction with photographic wood-grain surfaces occupies economy-tier renovation segments where installed cost sensitivity dominates specification.
- Bamboo:Grass-based material processed into strand-woven or horizontal-grain formats appeals to sustainability-weighted procurement under USDA Biopreferred program guidelines.
Established volume favors engineered wood; emerging adoption favors bamboo in federal and institutional specification channels.
Form:
Installation labor economics and subfloor condition variability drive format selection, with wider plank dimensions commanding premium positioning while standardized strips dominate volume production.
- Planks:Six to eight-inch widths with variable lengths deliver visual scale in open-concept residential layouts, with engineered constructions enabling formats previously restricted by solid wood dimensional instability.
- Panels:Large-format engineered products accelerate commercial installation timelines in multi-unit housing and institutional settings where labor cost minimization shapes procurement.
- Tiles:Square formats with parquet-style patterns concentrate in restoration and design-specified applications requiring geometric installation flexibility.
- Strips:Narrow two-to-three-inch widths maintain economy positioning and traditional nail-down installation compatibility in older housing stock renovation.
Production scale concentrates in planks; design differentiation concentrates in panels.
Installation:
Skill availability compression in the Southeast construction corridor is accelerating demand for reduced-specialization attachment methods that expand contractor addressable capacity.
- Click-lock:Floating mechanical interlock systems eliminate adhesive curing time and nail-down subfloor preparation, dominating renovation volume in Florida and Texas where moisture-barrier integration simplifies slab-on-grade specification.
- Floating:Non-attached installation over underlayment accommodates subfloor irregularity in aging housing stock, reducing preparation cost and timeline in residential renovation.
- Nail-down:Traditional cleat or staple attachment requires plywood subfloor and specialized flooring contractor skill, retaining position in solid wood premium segments and new construction with favorable framing conditions.
- Glue-down:Direct adhesive bonding to concrete or plywood subfloors concentrates in commercial applications where dimensional stability and acoustic performance requirements exceed floating system capabilities.
Contractor capacity constraints favor click-lock; performance specification favors glue-down in commercial segments.
End User:
LEED v4.1 low-emitting materials credits and USDA Biopreferred procurement preferences segment demand between air-quality-sensitive institutional buyers and cost-driven residential developers.
- Residential:Single-family new construction and renovation in Texas and Florida drives engineered wood volume, with homeowner specification behavior increasingly weighting wear-layer thickness documentation over initial installed cost.
- Commercial:Multi-unit housing developers and retail construction prioritize cost-per-square-foot efficiency, with engineered wood's installation speed advantages aligning with pro forma constraints in the Southeast housing corridor.
- Institutional:Educational and healthcare construction projects leverage LEED v4.1 credits and federal biobased procurement guidelines, filtering specification toward third-party certified products with documented chain-of-custody.
- Industrial:Warehouse and light manufacturing facility flooring concentrates in durability-optimized engineered products with enhanced wear-layer specifications for high-traffic maintenance environments.
Volume concentration sits with residential; specification margin expansion sits with institutional procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US wood flooring trade flows reflect a net import position in specialty tropical species balanced by Appalachian oak exports to European restoration markets. Domestic production concentrates in the Southeast and Mid-Atlantic corridors where timber procurement networks and kiln-drying infrastructure cluster.
Southeast
Texas and Florida housing starts drive engineered wood demand for slab-on-grade installations where moisture-resistant cores outperform solid alternatives. EPA TSCA Title VI enforcement filters import supply, tightening certified product availability for Atlanta and Charlotte distribution hubs. Georgia and Alabama mill complexes anchor domestic engineered wood production capacity.
Mid-Atlantic
Appalachian oak procurement networks from Kentucky through Pennsylvania supply premium solid wood segments for historic restoration and high-end residential renovation. USDA Biopreferred program specifications shape federal procurement in Washington DC and Baltimore institutional construction. Somerset Hardwood Flooring and regional suppliers concentrate kiln-drying infrastructure in this corridor.
Southwest
Arizona and Nevada residential expansion favors engineered wood click-lock systems that reduce installation labor in concrete-slab construction prevalent across Phoenix and Las Vegas sub-markets. California Air Resources Board ATCM Phase 2 standards create compliance barriers for direct shipment from non-certified mills. Distribution centers in Dallas-Fort Worth serve as transshipment points for California-bound inventory.
Pacific Northwest
Oregon and Washington timber resources historically supplied Douglas fir flooring for domestic and Asian export markets. Lacey Act enforcement on imported timber species documentation reshapes customs clearance protocols at Seattle and Portland ports. Regional producers pivot toward certified sustainable sourcing for LEED v4.1 specification in Seattle and San Francisco commercial construction.
Midwest
Illinois and Ohio manufacturing bases support engineered wood core production using regional poplar and softwood feedstocks. Chicago and Detroit renovation markets maintain demand for traditional nail-down solid wood in older housing stock. Distribution logistics favor rail-connected mill locations serving national big-box retail networks.
US Wood Flooring Market Competitive Landscape
Concentration sits with integrated hardwood processors possessing captive timber sourcing and resin formulation capabilities. Domestic manufacturers maintain advantage against import competition through EPA TSCA Title VI certification infrastructure that non-compliant foreign mills cannot easily replicate. Three archetypes define competitive positioning: vertically integrated timber-to-flooring processors, specialty importers with certification documentation expertise, and multi-surface flooring conglomerates leveraging cross-product distribution. M&A activity targets regional hardwood processors with Appalachian oak procurement networks, while capacity expansion concentrates in Southeast corridor mills serving Texas and Florida construction volume.
Among integrated processors, Mohawk Industries exemplifies the captive sourcing archetype through timberland and resin control. Mannington Mills represents multi-channel distribution reach spanning retail and contractor networks. Somerset Hardwood Flooring anchors the regional specialist tier with Appalachian procurement concentration. Shaw Industries Group occupies a position bridging scale and specialty capabilities. AHF Products and Armstrong Flooring sit within the diversified flooring portfolio segment. Tarkett SA and EGGER Group represent European-based multinationals with US manufacturing presence. Pergo exemplifies brand recognition in laminate and engineered wood crossover segments.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Mannington Mills, Inc. |
| Armstrong Flooring, Inc. |
| Tarkett SA |
| Pergo |
| Somerset Hardwood Flooring, Inc. |
| AHF Products |
| EGGER Group |
| Others |
Pricing and Supply Chain Analysis
Ninety-day Appalachian oak inventory cycles compress margin flexibility for domestic mills, concentrating pricing power among vertically integrated processors with captive timberland while forcing specialty importers toward certification-premium positioning to defend margin structure.
Pricing Analysis
The customization-premium spread between configured-to-order wide-plank engineered systems and standard strip formats runs three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on TSCA Title VI certification tier and wear-layer thickness specification, with California-bound inventory commanding additional ATCM Phase 2 compliance premiums. Cost compression in economy-tier laminated segments is intensifying because luxury vinyl tile substitution erodes volume leverage. Multi-unit housing developers exhibit highest price sensitivity; historic restoration contractors show lowest, prioritizing refinishing-cycle documentation over initial outlay.
Supply Chain Analysis
Appalachian hardwood harvesting capacity underwrites domestic solid wood availability, creating a chokepoint where logging labor shortages and weather-driven harvest volatility constrain feedstock flow to kiln-drying infrastructure. Geographic supply concentration centers on the Southeast corridor, with Georgia and Alabama mill complexes feeding Texas and Florida construction demand, while European multinationals anchor engineered wood core production in Austria and Germany. Raw material dependencies encompass phenol-formaldehyde resins, aluminum oxide wear-layer media, and cross-laminated timber cores. Single-source vulnerability concentrates in Appalachian oak procurement networks where regional weather patterns disrupt seasonal harvest windows. Distribution runs through Atlanta and Charlotte distribution hubs serving big-box retail and independent flooring contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wood flooring market functions as a service-attach opportunity where installation training certification and refinishing-cycle warranty programs expand recurring revenue faster than plank and panel hardware sales alone.
For Market Incumbents: Consolidate Appalachian oak procurement networks through regional hardwood processor acquisition, capturing kiln-drying infrastructure that non-integrated competitors cannot replicate. Deepen EPA TSCA Title VI certification infrastructure as a defensive moat against import competition lacking third-party laboratory testing protocols. Prioritize click-lock floating system R&D to counter luxury vinyl tile substitution in renovation segments. For New Entrants and Emerging Players: Lead with USDA Biopreferred program compliance as a specification wedge in federal and institutional procurement channels where incumbent certification portfolios remain underdeveloped. Target the institutional end-use segment in Washington DC and Baltimore where LEED v4.1 low-emitting materials credits filter specification toward compliant domestic manufacturers. Deploy direct-to-contractor digital specification tools that compress traditional distributor markup structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates where wood flooring operations represent non-core revenue concentration with underutilized certification infrastructure. Long-term viability over a multi-year horizon hinges on EPA enforcement consistency and Lacey Act documentation capability as import filtration mechanisms. Monitor Southeast housing start permits in Texas and Florida as the primary inflection indicator for engineered wood volume demand.| Strategic Initiative | Industry Significance |
|---|---|
| Appalachian Oak Procurement Network Acquisition | Captures kiln-drying infrastructure and logging labor relationships that anchor solid wood premium positioning. |
| EPA TSCA Title VI Certification Infrastructure Expansion | Creates import filtration barrier that non-compliant foreign mills cannot easily replicate for national distribution. |
| Click-Lock Floating System R&D Investment | Addresses contractor skill compression in Texas and Florida renovation markets where labor cost minimization dominates. |
| USDA Biopreferred Program Compliance Pathway | Opens federal procurement specification channels in Washington DC and Baltimore institutional construction segments. |
| Direct-to-Contractor Digital Specification Platform | Compresses traditional distributor markup while delivering wear-layer transparency that homeowner specification behavior increasingly demands. |
Research Methodology
The analysis maps engineered wood, solid wood, laminated wood, and bamboo product segments, each validated through plant managers at Southeast corridor mills, procurement leads at multi-unit housing developers, independent flooring contractors in Texas and Florida, and regulatory compliance officers at domestic manufacturers. Primary interview insights triangulate against secondary sources including EPA TSCA Title VI certification databases, USDA Biopreferred program product listings, Lacey Act enforcement records, and SEC 10-K filings from publicly traded flooring conglomerates. Bottom-up volume estimates from regional housing start data and top-down value projections from distribution channel revenue analysis converge through iterative reconciliation.
Consistency checks against external benchmarks validate volume and value outputs across the analysis window. The forecast framework models product type, installation method, end-use industry, and regional construction corridor dimensions. CAGRs derive from regression analysis of historical housing start correlations with flooring consumption intensity, adjusted for substitution effects from luxury vinyl tile and regulatory compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity and Southeast housing permit velocity would require recalibration. Practitioners should keep alternative scenarios live as formaldehyde emission standard harmonization between federal and California thresholds evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Global Flooring Market