
 Turkey Floor Covering Market | 2026-2036
Turkey Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Floor Covering Market Analytics
Digital printing on ceramic surfaces is tilting production economics toward shorter runs with richer visual variety. Delta Marble leverages captive quarry access to anchor its position in premium natural stone. Bien Seramik sustains R&D intensity in large-format porcelain slabs. Usak Seramik Sanayii AS competes through vertically integrated kiln operations across western Anatolia.
Turkey floor covering comprises finished surface materials installed over structural substrates to provide wear resistance, thermal comfort, and aesthetic finish, with ceramic tiles typically fired at 1,100–1,200°C and laminate products built around high-density fiberboard cores with aluminum oxide wear layers. Tile dominates value capture in commercial and hospitality specification due to durability and moisture resistance, while laminate expands fastest in residential retrofit where floating installation reduces labor cost. Carpet retains share in hospitality corridors and guest rooms where acoustic dampening is specified, though polyester face fibers face pressure from natural fiber alternatives in green-certified projects.
Turkey's Ministry of Environment, Urbanization and Climate Change enforces building energy performance regulations that shape insulation-underlayment combinations, while the Turkish Standards Institution (TSE) certifies slip resistance and fire reaction classifications for public-space installations. The EU-Turkey Customs Union alignment pressures exporters to meet CE marking requirements for flooring sold into European markets. Stakeholders must monitor how upcoming carbon border adjustments and domestic green building certification expansion will reroute procurement specifications toward low-emission manufacturing and recycled content thresholds.
Market Dynamics
Turkey's Ministry of Environment, Urbanization and Climate Change is tightening building energy codes that mandate thermal performance in flooring assemblies, forcing manufacturers to reformulate insulation-underlayment combinations and recertify product lines against updated TSE standards.
Growth Catalysts
- Istanbul-Ankara residential construction pipeline:Dense urban renewal across Turkey's Marmara and Central Anatolia regions sustains specification-grade procurement volumes for ceramic and laminate surfaces in multi-unit housing developments.
- EU-Turkey Customs Union alignment:CE marking requirements for flooring exports into European markets drive quality upgrades and factory certifications that spill over into domestic product lines.
- Digital inkjet decoration:Advanced printing systems enable shorter production runs with richer visual variety, allowing Turkish manufacturers to compete on design differentiation against Italian and Spanish rivals.
Market Restraints
- Natural gas price volatility:Ceramic tile firing at 1,100–1,200°C depends heavily on imported natural gas, exposing kiln operators to input cost swings that compress margin buffers.
- Western Anatolia supply concentration:Vertically integrated kiln operations cluster in Usak and surrounding provinces, creating geographic vulnerability to localized infrastructure disruptions or labor actions.
- Aluminum oxide wear layer import dependency:Laminate flooring producers rely on overseas suppliers for critical surface protection materials, subjecting production schedules to shipping lane congestion.
Strategic Opportunities
- Eastern Anatolia underpenetration:Lower per-capita flooring consumption in Turkey's eastern provinces presents expansion potential as regional income levels converge with western benchmarks.
- Green building certification expansion:Domestic green building programs are beginning to specify recycled content thresholds and low-emission manufacturing, creating first-mover advantage for certified producers.
- Large-format porcelain slabs:R&D investment in sintered stone surfaces opens specification opportunities in commercial hospitality and high-end residential verticals previously dominated by natural stone.
Industry Challenges
- Skilled installer shortage:Floating laminate installation requires trained labor that remains scarce outside Istanbul and Ankara, constraining residential retrofit penetration in secondary cities.
- TSE certification timelines:Slip resistance and fire reaction testing for public-space installations creates product launch delays that mismatch against fast-moving design trends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Floor Covering Market |
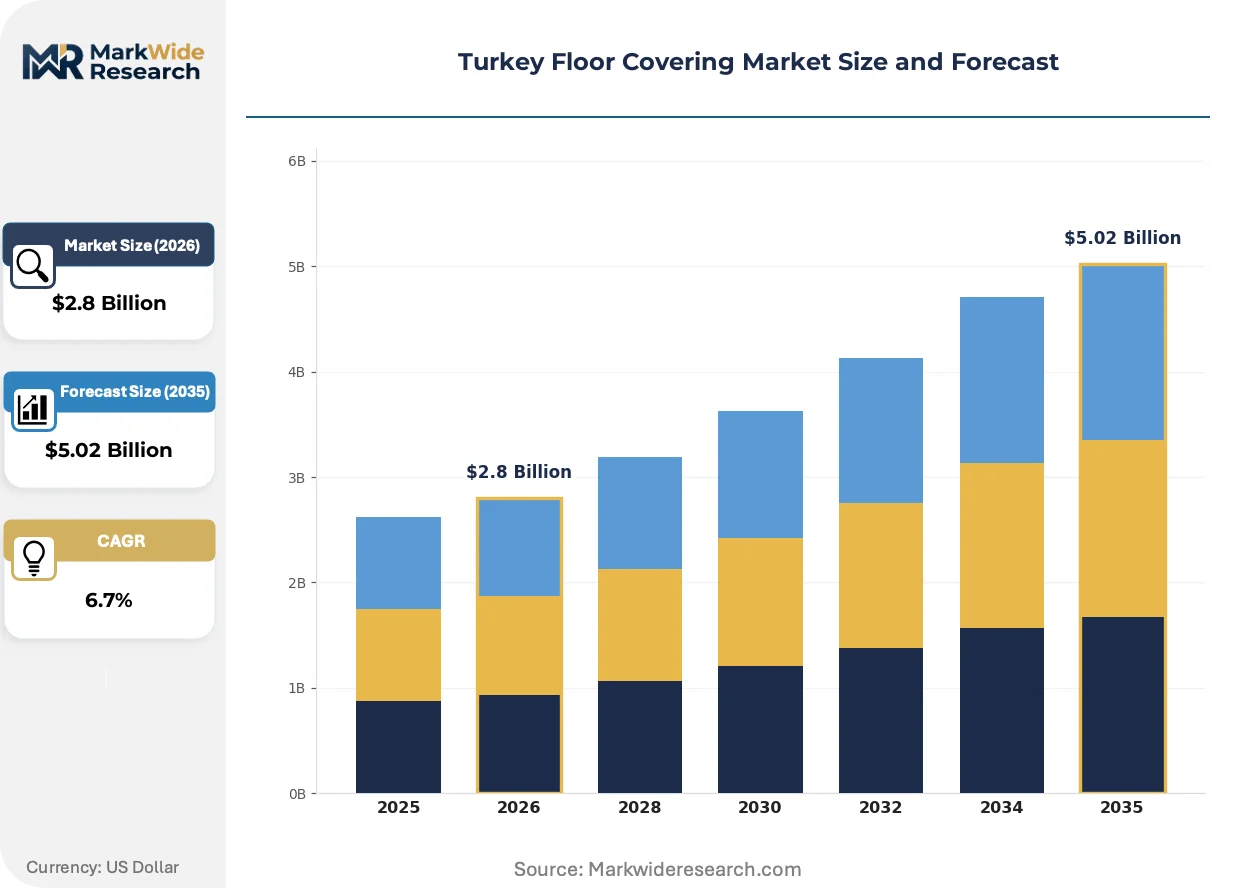
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Vinyl, Laminate, Tile Material: Wood, Ceramic, Polyester, Natural Fiber Installation Type: Glue-Down, Floating, Nailing, Stapling End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Delta Marble, Usak Seramik Sanayii AS, Bien Seramik, Anka Toprak Urunleri Sanayi ve Ticaret AS, Graniser, Okur Zemin, Karoistanbul, Tureks, Ado Floor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Floor Covering Market Evolving Landscape
Digital workflows and regulatory tightening are compressing product development cycles while expanding the addressable design space for Turkish manufacturers competing across domestic and export markets.
High-definition inkjet printing on ceramic surfaces is virtualizing the economics of tile decoration. Hospitality and commercial specifiers in Istanbul now demand batch sizes as small as 500 square meters with bespoke stone or wood visuals. This technology is virtualizing the traditional tradeoff between production scale and design variety, enabling Turkish plants to quote competitively against Italian producers on custom projects.
Turkey's Ministry of Environment, Urbanization and Climate Change has mandated thermal transmittance limits for flooring assemblies in new construction and major renovations. Manufacturers must now engineer insulation-underlayment combinations that satisfy U-value calculations. Ceramic producers serving public-space installations face the steepest compliance burden, as TSE certification for slip resistance must be renewed against updated test protocols.
Project owners in Turkey's hospitality sector are unbundling material supply from installation services, creating direct procurement relationships with flooring manufacturers. Traditional distributor-installer intermediaries lose margin share as hotel chains and commercial developers negotiate volume contracts. This pattern concentrates most visibly in Istanbul's dense hotel construction pipeline, where international brand standards override local sourcing customs.
Turkey Floor Covering Market Segmentation
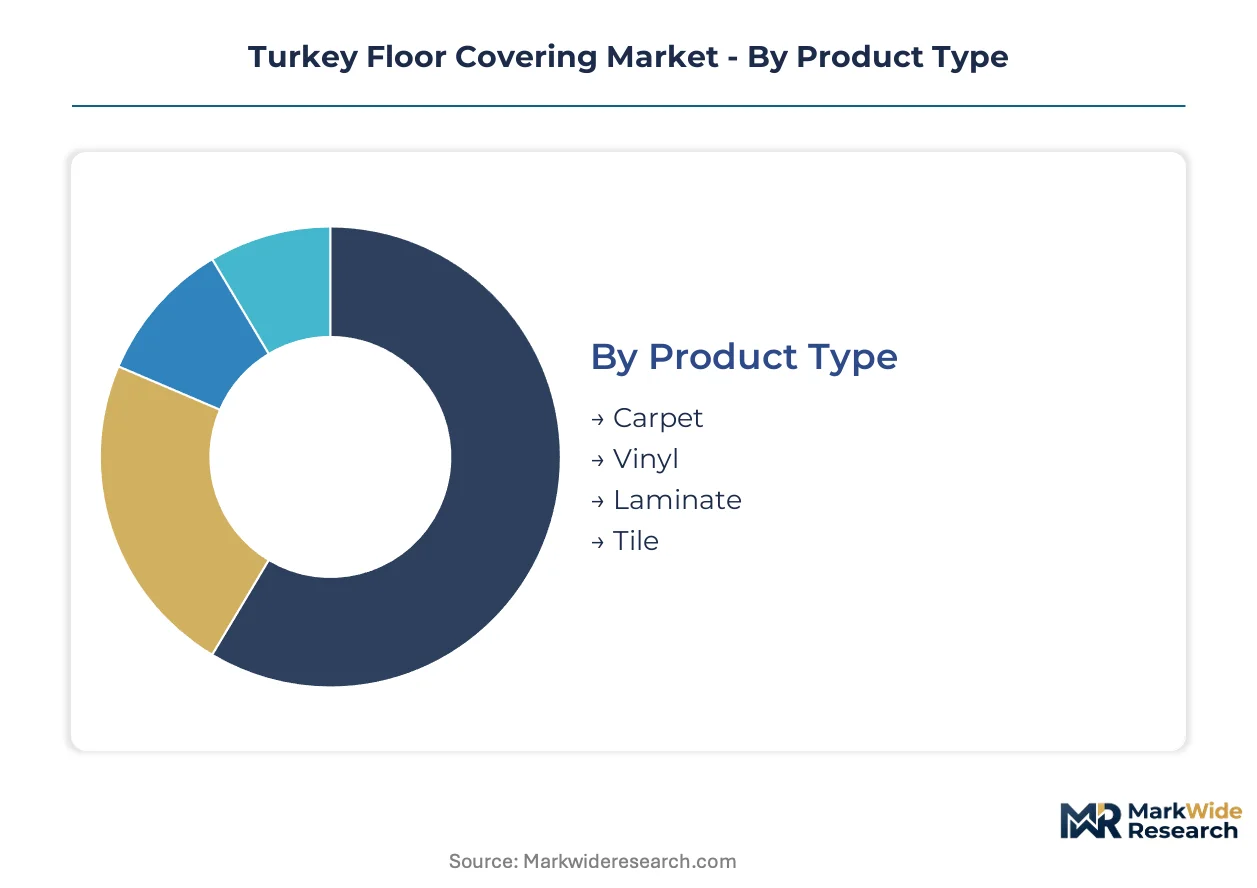
Floor covering procurement in Turkey splits across multiple technical and commercial dimensions. Specification decisions hinge on installation labor availability, thermal performance mandates from the Ministry of Environment, Urbanization and Climate Change, and end-use durability requirements.
Product Type:
Replacement cycles vary dramatically—residential carpet refreshes every 7-10 years while commercial tile installations endure 20+ years, creating divergent revenue recognition patterns for manufacturers.
- Tile:Ceramic and porcelain products fired at 1,100–1,200°C dominate Istanbul's commercial and hospitality specification due to moisture resistance and thermal mass compliance with building energy codes. Public-space installations require TSE-certified slip resistance and fire reaction classifications that extend procurement timelines.
- Laminate:High-density fiberboard cores with aluminum oxide wear layers expand fastest in Ankara residential retrofit where floating installation reduces skilled labor dependency. Natural gas price volatility compresses margins for competing ceramic options in price-sensitive segments.
- Carpet:Hospitality corridors and guest rooms in Istanbul's dense hotel construction pipeline specify polyester and natural fiber face fibers for acoustic dampening, though green-certified projects increasingly favor natural alternatives.
- Vinyl:Resilient sheet and luxury vinyl tile products serve healthcare and education verticals requiring seamless hygiene surfaces and rapid installation turnaround.
Tile anchors the volume base while laminate gains share at the steepest rate.
Material:
Cost tiers separate premium natural materials from engineered alternatives, with specification-grade procurement concentrating on performance-certified options regardless of origin.
- Ceramic:Digitally printed surfaces enable shorter production runs with bespoke visuals, allowing Turkish manufacturers to compete against Italian rivals on custom hospitality projects in Istanbul.
- Wood:Solid and engineered hardwood products serve premium residential verticals in Ankara and Izmir where natural material authenticity commands specification priority.
- Polyester:Synthetic face fibers dominate mass-market carpet production due to cost efficiency, though they face displacement pressure from natural fiber alternatives in green-certified hospitality projects.
- Natural Fiber:Wool and sisal products capture specification share in Istanbul luxury hospitality where acoustic performance and sustainability credentials override first-cost considerations.
Ceramic commands the largest installed base while natural fiber climbs the fastest among specification-grade segments.
Installation Type:
Customer type dictates installation method selection—professional contractors favor permanent attachment while residential retrofitters prioritize speed and reversibility.
- Floating:Click-lock laminate and luxury vinyl systems reduce labor cost and enable DIY installation, expanding penetration in Ankara and Istanbul residential retrofit where skilled installer scarcity constrains glue-down alternatives.
- Glue-Down:Permanent adhesive attachment dominates commercial and hospitality specification in Istanbul where heavy traffic loads and insurance requirements demand maximum dimensional stability.
- Nailing:Solid hardwood installation persists in premium residential new construction across Marmara region developments where structural substrates accommodate mechanical fastening.
- Stapling:Carpet stretch-in installation retains share in hospitality guest rooms where substrate conditions and acoustic underlayment combinations favor conventional attachment methods.
Glue-down methods dominate commercial specification value while floating installation expands most quickly in residential retrofit volume.
End User:
Application context determines performance requirements—thermal transmittance limits, slip resistance thresholds, and wear layer specifications vary sharply across user categories.
- Residential:Multi-unit housing developments across Istanbul and Ankara absorb ceramic and laminate surfaces in volume, with procurement decisions driven by developer cost controls and Ministry of Environment thermal performance mandates for flooring assemblies.
- Commercial:Office and institutional specifications in Istanbul prioritize durability and maintenance efficiency, with public-space installations requiring updated TSE certification protocols that delay product launches.
- Hospitality:Hotel chains in Istanbul's dense construction pipeline unbundle material supply from installation services, negotiating direct volume contracts with manufacturers against international brand standards.
- Retail:Store rollout programs favor rapid-install resilient products that minimize downtime during tenant improvements in shopping centers across Turkey's western provinces.
Residential absorbs the greatest product volume while hospitality exhibits the steepest expansion trajectory in specification-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial developers and hospitality chains in Istanbul's dense construction corridor drive specification-grade procurement volumes, while residential retrofit demand concentrates in Ankara's multi-unit housing pipeline. Regional consumption patterns split between Marmara's premium commercial specifications and Central Anatolia's cost-sensitive residential volumes.
Marmara Region
Istanbul's urban renewal pipeline absorbs the majority of ceramic tile and laminate flooring volumes, with hotel chains negotiating direct manufacturer contracts bypassing traditional distributors. The Ministry of Environment, Urbanization and Climate Change enforces thermal transmittance limits for flooring assemblies in new construction across the metropolitan area. Gebze and Çerkezköy industrial zones host vertically integrated kiln operations serving both domestic specification and export markets.
Central Anatolia
Ankara's residential retrofit segment expands fastest for floating laminate installations where skilled labor scarcity constrains glue-down alternatives. Turkish Standards Institution certification protocols for slip resistance and fire reaction delay product launches for public-space applications. The city's organized industrial zones concentrate laminate fabricators dependent on imported aluminum oxide wear layers.
Aegean Region
Izmir's hospitality and healthcare construction verticals specify moisture-resistant ceramic surfaces for durability in high-traffic environments. Building energy codes mandate insulation-underlayment combinations that reformulate procurement specifications for flooring assemblies. Torbalı and Kemalpaşa districts anchor ceramic production clusters with captive quarry access for premium natural stone alternatives.
Mediterranean Region
Antalya's tourism-driven hotel construction pipeline sustains demand for acoustic-dampening carpet in guest room specifications alongside hard surface alternatives. Green building certification programs increasingly specify recycled content thresholds and low-emission manufacturing criteria. Alanya and Manavgat sub-regions concentrate installation contractor networks serving resort property developments.
Black Sea Region
Samsun and Trabzon exhibit underpenetrated per-capita flooring consumption relative to western benchmarks, presenting expansion potential as regional income levels converge. Domestic logistics infrastructure constraints elevate landed costs for imported laminate wear layer materials. Local distributor networks retain stronger influence over procurement decisions compared to Istanbul's direct manufacturer relationships.
Turkey Floor Covering Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market segments. The vendor base clusters around three strategic archetypes: vertically integrated ceramic producers with captive raw material access, laminate specialists dependent on imported wear layer supply chains, and natural stone fabricators leveraging domestic quarry reserves. Competitive dynamics center on CE marking alignment for export qualification and thermal performance certification for domestic building code compliance. Capacity expansion in large-format porcelain and strategic partnerships for digital printing technology represent dominant competitive moves.
Among vertically integrated ceramic producers, Delta Marble and Usak Seramik Sanayii AS exemplify archetypes anchored in western Anatolia's kiln concentration. Bien Seramik occupies a position within the innovation-driven tier focused on large-format porcelain development. These three entities represent the competitive spectrum from quarry-integrated natural stone through kiln-optimized ceramic production to R&D-intensive sintered stone surfaces.
| Leading Market Players |
|---|
| Delta Marble |
| Usak Seramik Sanayii AS |
| Bien Seramik |
| Anka Toprak Urunleri Sanayi ve Ticaret AS |
| Graniser |
| Okur Zemin |
| Karoistanbul |
| Tureks |
| Ado Floor |
| Others |
Value Network & Pricing Analysis
Natural gas price volatility in Turkey determines both the spread between ceramic and laminate pricing tiers and the geographic clustering of kiln operations around western Anatolia's pipeline infrastructure. Manufacturers absorb input cost swings through reformulated insulation-underlayment combinations while procurement officers shift volume toward floating laminate alternatives where thermal performance codes permit.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate procurement agreements between ceramic producers and Istanbul developers. Pricing stratifies across premium specification-grade, standard commercial, and economy residential tiers based on TSE certification level and volume scale. Cost compression in the economy tier is intensifying because imported aluminum oxide wear layer prices fluctuate with shipping lane congestion. Residential retrofit buyers in Ankara exhibit the highest price sensitivity, while hospitality chains in Istanbul prioritize durability over first cost.
Supply Chain Analysis
EU-Turkey Customs Union alignment restricts technology flows for advanced digital printing systems, limiting domestic access to Italian and Spanish equipment vendors. Ceramic tile production draws from western Anatolia, China, and Italy for kiln technology and decorative inks. Raw material dependencies include imported natural gas for firing, aluminum oxide from overseas suppliers for laminate wear layers, and captive marble quarries for premium stone alternatives. Single-source vulnerability concentrates in natural gas supply contracts. Distribution runs through project-direct relationships in Istanbul and traditional distributor networks in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's floor covering market tracks residential construction cycles, with Istanbul's urban renewal pipeline providing the current cyclical uplift. The Ministry of Environment's thermal performance mandates create regulatory tailwinds for compliant manufacturers across the analysis window.
For Market Incumbents: Insulate margin position by deepening backward integration into captive quarry reserves and expanding large-format porcelain capacity in Gebze industrial zones. Delta Marble and Usak Seramik Sanayii AS should prioritize TSE certification renewal timelines to preempt launch delays against fast-moving hospitality specifications. Natural gas price hedging represents a critical defensive lever. For New Entrants and Emerging Players: Pursue white-space expansion in eastern Anatolia's underpenetrated provinces where per-capita flooring consumption lags western benchmarks. Samsun and Trabzon present the most penetrable geographies as regional income convergence accelerates. A direct-installation service model bypasses scarce skilled labor constraints in secondary cities. For Investors and Strategic Acquirers: Carbon border adjustment implementation reshapes the acquisition landscape toward low-emission manufacturing capabilities and recycled content certification. Long-term viability favors vertically integrated ceramic producers with captive energy hedging and EU export qualification. Monitor Ministry of Environment building code amendments as the primary inflection signal for specification-grade demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Large-Format Porcelain Capacity Expansion | Bien Seramik's R&D intensity in sintered stone surfaces opens commercial hospitality specification previously dominated by Italian producers. |
| Backward Integration into Captive Quarries | Delta Marble's marble reserves anchor premium natural stone positioning against engineered ceramic alternatives in Istanbul luxury developments. |
| Digital Printing Technology Partnership | Advanced inkjet systems enable 500-square-meter custom production runs competitive with Italian design differentiation. |
| Thermal Performance Certification Investment | Compliance with Ministry of Environment U-value mandates secures specification in Marmara region urban renewal projects. |
| Eastern Anatolia Distribution Network Buildout | Direct manufacturer relationships bypass traditional intermediaries in Samsun and Trabzon as income convergence accelerates regional demand. |
Research Methodology
Operator-level perspectives from ceramic plant managers, laminate fabricators, Istanbul hospitality procurement directors, and Ankara residential developers anchored the qualitative base. Secondary validation drew from Turkish Standards Institution certification records, Ministry of Environment building code filings, EU-Turkey Customs Union trade documentation, and organized industrial zone production statistics. Bottom-up segment sizing triangulated against top-down construction pipeline valuations.
Scenario-bracketing around natural gas price trajectories and urban renewal completion rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, installation method, end-user vertical, and regional consumption cluster. CAGRs derived from construction spend elasticities and replacement cycle analysis, with ceramic firing energy costs and laminate wear layer import prices as industry-specific forecast inputs.
Sensitivities concentrate around Ministry of Environment regulatory amendments, EU carbon border adjustment implementation timing, and natural gas contract renegotiation cycles. Forecasts reflect documented assumptions on construction permit issuance rates and thermal code enforcement intensity. Material shifts in Istanbul urban renewal pipeline velocity or eastern Anatolia income convergence trajectories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market