
 China Non-Resilient Floor Covering Market | 2026-2036
China Non-Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
China Non-Resilient Floor Covering Market Outlook
Commercial developers is unwinding residential homeowners as the dominant buyer archetype in China's non-resilient flooring procurement. DongPeng Ceramics Co anchors its position through captive supply of porcelain slabs across tier-one commercial projects. The Marco Polo Group differentiates via R&D intensity in large-format sintered stone surfaces. Yihua Lifestyle Technology Co Ltd leverages backward integration into laminate substrate production to control input costs.
China non-resilient floor covering comprises rigid surfacing materials—ceramic tile, porcelain, natural stone, laminate, and luxury vinyl tile—engineered for dimensional stability under load without elastic recovery, typically installed via mortar bedding, adhesive bonding, or mechanical interlock systems. These materials serve structural and aesthetic functions in high-traffic commercial and residential environments where abrasion resistance and moisture tolerance outweigh cushioning requirements. Tiles dominates volume flows through Foshan's manufacturing corridor, though vinyl captures expanding share in hospitality retrofits seeking faster installation cycles. Stone commands premium positioning in luxury commercial lobbies and educational institutional builds where lifecycle durability justifies first-cost outlay.
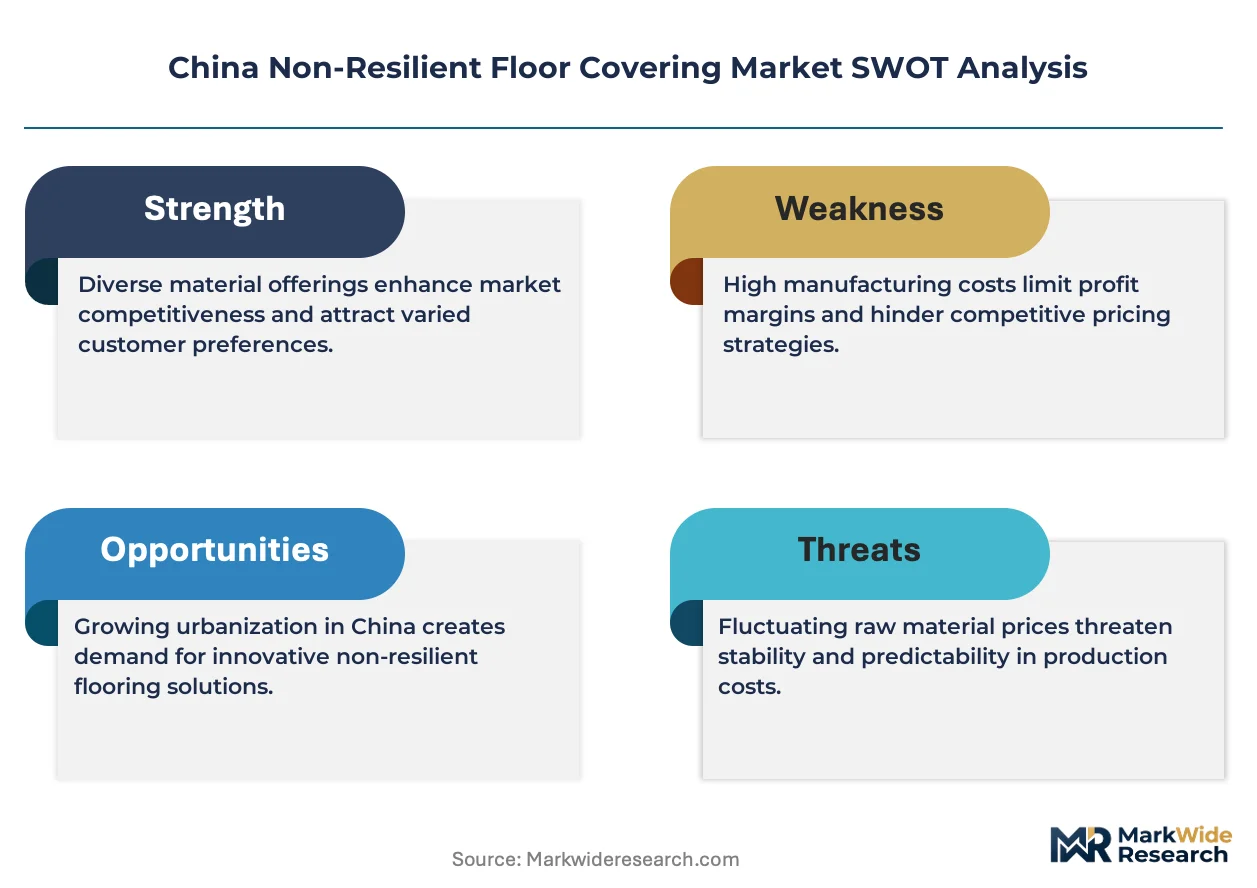
MIIT enforces GB standards governing formaldehyde emissions in laminate substrates and radon limits in natural stone imports, while MEE's dual carbon goals are forcing kiln electrification across Guangdong ceramic belts. SAMR monitors product labeling compliance and anti-dumping enforcement on imported vinyl substrates. Stakeholders must track evolving carbon intensity benchmarks and substrate certification requirements to secure project-specifier approval in China's tightening built-environment compliance landscape.
Market Dynamics
MIIT's GB standards for formaldehyde emissions and MEE's dual carbon goals are compressing kiln operations across Guangdong's ceramic belt, forcing manufacturers to electrify production or surrender market access.
Growth Catalysts
- Dual carbon mandates:MEE emissions benchmarks are accelerating kiln electrification investments, qualifying compliant producers for state procurement preference in public infrastructure tenders.
- Commercial mixed-use expansion:Developers in tier-one cities are specifying porcelain slabs and sintered stone for high-traffic lobbies, displacing resilient alternatives in prestige positioning.
- Foshan cluster agglomeration:Concentrated raw material access and specialized logistics infrastructure are reducing unit production costs for ceramic tile exports to Southeast Asian markets.
Market Restraints
- Natural gas price volatility:Kiln operations remain dependent on imported LNG feedstock, exposing margin structures to energy cost swings that electric conversion cannot yet fully offset.
- Single-province supply concentration:Over 70 percent of domestic ceramic tile volume originates in Guangdong, creating systemic disruption risk from localized environmental enforcement or logistics bottlenecks.
- Radon certification friction:SAMR import screening for natural stone substrates delays project timelines, compressing specification share for domestic porcelain alternatives in commercial bids.
Strategic Opportunities
- Western province underpenetration:Sichuan and Shaanxi construction markets exhibit specification gaps for large-format sintered stone, offering first-mover positioning for compliant manufacturers.
- Healthcare facility retrofit wave:Hospital renovation cycles are accelerating demand for antimicrobial porcelain surfaces in operating theaters and patient circulation zones.
- Digital specification platforms:Architect-facing material databases are compressing traditional distributor influence, enabling direct manufacturer engagement with project design teams.
Industry Challenges
- Electrification capex burden:Kiln retrofit requirements demand capital allocations that strain mid-tier producers without state-backed green financing access.
- Cross-border substrate certification:Export markets impose divergent radon and formaldehyde testing protocols, fragmenting quality assurance workflows and extending batch release timelines.
- Specialized installer scarcity:Large-format sintered stone deployment requires certified mortar-bed technicians, creating project completion bottlenecks in tier-two and tier-three urban markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Non-Resilient Floor Covering Market |
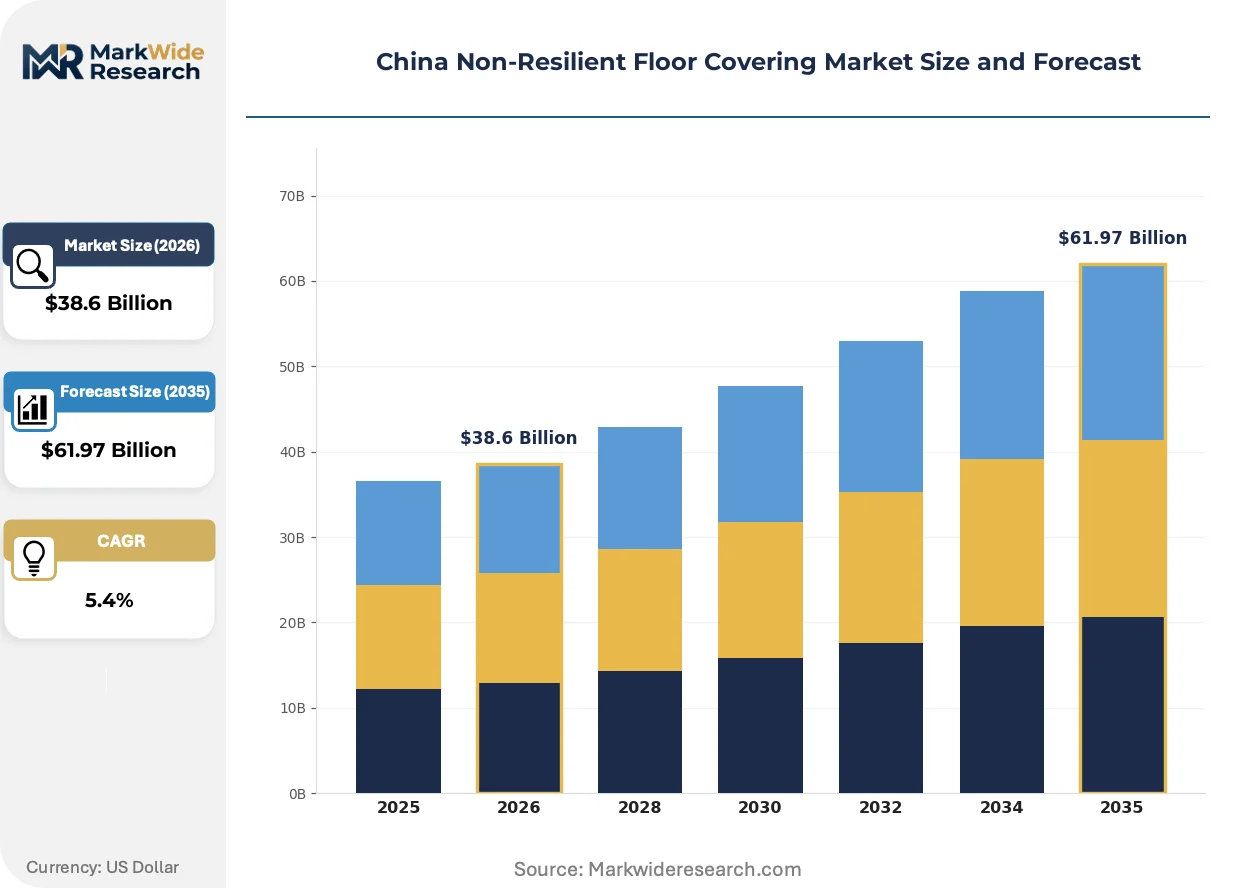
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tiles, Laminate, Vinyl, Stone Application: Residential, Commercial, Educational, Hospitality Installation Method: Glue-down, Click-lock, Loose lay, Nail-down End User: Homeowners, Contractors, Developers, Designers |
| Companies Covered | Zhejiang Shiyou Timber Co Ltd, Yihua Lifestyle Technology Co Ltd, China Ceramics Co Ltd, DongPeng Ceramics Co, Foshan Hanse Industrial Co Ltd, Rak Cermics PJSC, The Marco Polo Group, Nature Home Holding Co Ltd, Foshan Wondrous Building Materials Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Non-Resilient Floor Covering Market Strategic Shifts
Digital inkjet decoration and thin-body porcelain technologies are collapsing traditional barriers between ceramic performance and aesthetic versatility, reshaping specification behavior across commercial and residential verticals.
Thin-body porcelain slabs are decomposing the historical trade-off between dimensional stability and installation weight, enabling high-rise commercial retrofits previously excluded by structural load constraints. Hospitality operators in Shanghai and Shenzhen are specifying 3mm gauged porcelain for rapid renovation cycles, compressing project downtime from weeks to days. The technology is decomposing distributor inventory models by enabling just-in-time fabrication of custom surface dimensions.
MEE's dual carbon enforcement timeline is hardening emissions disclosure requirements for building material procurement in state-funded projects, disqualifying coal-fired kiln output from public tender eligibility. Ceramic producers are responding with biomass hybrid firing trials and renewable energy power purchase agreements to secure compliance certification. Guangdong-based manufacturers face the steepest transition curves given their concentration of legacy fossil-fuel infrastructure.
Architect specification behavior is rotating toward lifecycle cost documentation over first-cost bidding, elevating porcelain and sintered stone in commercial tender evaluations. Design institutes in Beijing and Guangzhou are embedding 20-year maintenance forecasts into material selection matrices, disadvantaging vinyl alternatives with shorter replacement cycles. This shift is most visible in educational and healthcare institutional builds where total cost of ownership dominates capital allocation decisions.
China Non-Resilient Floor Covering Market Segmentation
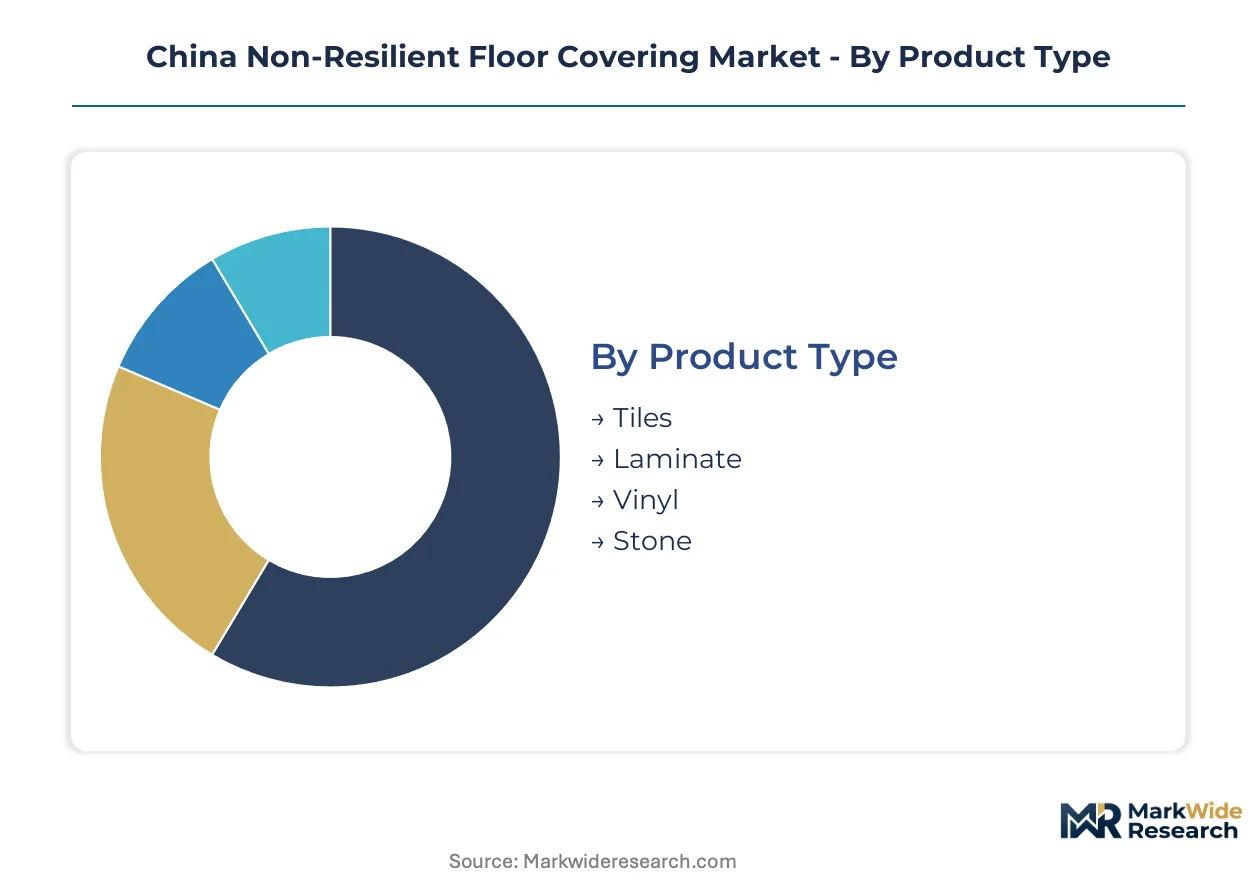
Segmentation in China's non-resilient flooring market reveals how procurement channels, compliance requirements, and installation constraints reshape competitive positioning across material categories. Distinct buyer archetypes and project specifications drive divergent margin structures and channel strategies for manufacturers.
Product Type:
Channel mix varies sharply by material rigidity and weight—ceramic tile flows through project distributors serving Foshan cluster manufacturers, while vinyl substrates reach hospitality retrofits via direct specification platforms.
- Tiles:Fired clay and porcelain compositions deliver compressive strength exceeding 35 MPa for high-traffic commercial lobbies. Guangdong province's manufacturing corridor supplies 70 percent of domestic volume, though MIIT electrification mandates are compressing kiln capacity and elevating compliant producer pricing power.
- Laminate:High-density fiberboard cores with aluminum oxide wear layers achieve Class 32 abrasion ratings at lower installed cost than ceramic. GB standards on formaldehyde emissions from MIIT are disqualifying non-compliant substrate imports from state-funded residential projects.
- Vinyl:Rigid core SPC and WPC constructions enable 48-hour installation cycles in Shanghai hospitality renovations. Click-lock systems reduce skilled labor dependency versus mortar-bed alternatives.
- Stone:Granite and marble slabs command premium positioning in luxury commercial builds, though SAMR radon screening delays import timelines and compresses specification share against domestic porcelain alternatives.
Tiles dominates installed base. Vinyl is where expansion concentrates.
Application:
Cost tier stratification separates prestige positioning in commercial mixed-use towers from volume-driven residential replacement cycles.
- Residential:Laminate and LVT capture renovation demand in tier-two cities where homeowners prioritize first-cost economics over lifecycle durability. GB formaldehyde compliance certifications increasingly gate distributor shelf access.
- Commercial:Large-format porcelain slabs and sintered stone define mixed-use lobby specifications in Shenzhen and Beijing, where developers embed 20-year maintenance forecasts into capital allocation decisions.
- Educational:Antimicrobial porcelain surfaces gain traction in K-12 facility retrofits, driven by hygiene protocols and abrasion resistance requirements in high-density circulation zones.
- Hospitality:Thin-body gauged porcelain enables rapid renovation cycles in Shanghai hotel assets, compressing project downtime from weeks to days versus traditional tile removal.
Commercial applications command premium margin tiers. Hospitality retrofits are climbing the fastest as asset managers prioritize speed-to-revenue.
Installation Method:
Volume concentration in Guangdong's manufacturing belt shapes logistics economics for mortar-dependent systems versus floating floor alternatives.
- Glue-down:Permanent adhesive bonding for stone and large-format tile in commercial lobbies demands certified mortar-bed technicians, creating completion bottlenecks in tier-three markets.
- Click-lock:Mechanical interlock systems in SPC vinyl reduce skilled labor requirements and enable rapid deployment in hospitality retrofits seeking minimal operational disruption.
- Loose lay:Friction-based installation for modular carpet tile and select vinyl formats supports temporary event flooring and rapid reconfiguration in exhibition spaces.
- Nail-down:Limited to engineered wood and laminate substrates in residential applications, declining as floating systems capture specification preference.
Glue-down retains prestige commercial share. Click-lock is where technology investment concentrates.
End User:
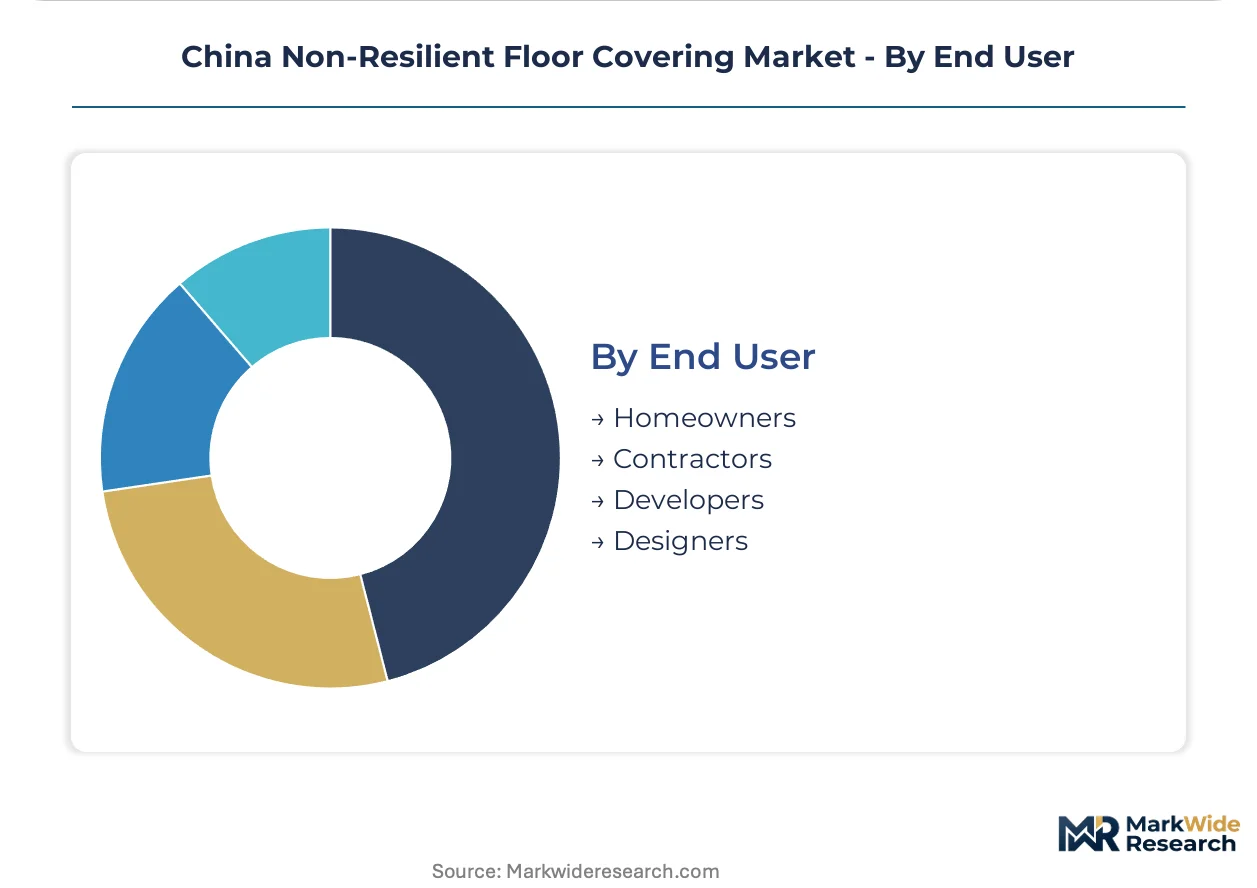
Customer type determines specification influence—architects and developers control commercial project decisions, while contractors mediate residential procurement.
- Homeowners:Price-sensitive buyers in tier-two and tier-three cities drive laminate and economy vinyl volume through retail distributor channels.
- Contractors:Installation firms influence material selection in residential renovation, prioritizing product availability and familiar handling characteristics over performance differentiation.
- Developers:Mixed-use project sponsors in tier-one cities specify porcelain and sintered stone for common area prestige positioning, embedding lifecycle cost documentation into tender evaluations.
- Designers:Architecture firms in Beijing and Guangzhou leverage digital specification platforms to engage manufacturers directly, compressing traditional distributor influence in commercial bids.
Developers control premium project flow. Designers are where channel disruption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese ceramic tile exports flow primarily to Southeast Asian construction markets, with Vietnam and Indonesia absorbing expanding volumes of porcelain slabs from Guangdong's manufacturing corridor.
Guangdong Province
Foshan's ceramic cluster generates over 70 percent of domestic tile volume, serving mixed-use commercial projects in Shenzhen and Guangzhou with large-format porcelain specifications. MIIT electrification mandates are forcing kiln retrofits across the Pearl River Delta, elevating compliance costs for legacy producers. The province's specialized logistics infrastructure enables just-in-time delivery to Southeast Asian export markets.
Yangtze River Delta
Shanghai's hospitality retrofit wave drives specification of thin-body gauged porcelain for rapid renovation cycles in hotel assets. SAMR import screening for natural stone substrates compresses project timelines, redirecting demand toward domestic ceramic alternatives. Nanjing and Hangzhou design institutes embed lifecycle cost documentation into material selection matrices for educational and healthcare institutional builds.
Beijing-Tianjin-Hebei
Capital region developers specify sintered stone and porcelain slabs for prestige positioning in mixed-use lobby spaces, prioritizing 20-year maintenance forecasts over first-cost economics. MEE dual carbon disclosure requirements disqualify coal-fired kiln output from state-funded public infrastructure tenders. Tianjin's port infrastructure facilitates raw material imports for laminate substrate producers serving northern residential renovation markets.
Sichuan-Chongqing
Western China construction markets exhibit specification gaps for large-format sintered stone, offering first-mover positioning for compliant manufacturers with GB certification. Chongqing's healthcare facility retrofit wave accelerates demand for antimicrobial porcelain surfaces in hospital operating theaters. Provincial logistics constraints limit Guangdong ceramic penetration, creating protected demand for local production capacity.
Shandong Peninsula
Qingdao and Yantai manufacturing bases serve laminate and engineered wood demand in tier-two residential renovation markets across northern provinces. GB formaldehyde emission standards from MIIT gate distributor shelf access for non-compliant substrate imports. The region's port infrastructure supports export flows to Japanese and South Korean markets with divergent certification protocols.
China Non-Resilient Floor Covering Market Competitive Environment
Listed leaders compete with private specialists across capital access and compliance certification dimensions, creating tiered competitive dynamics in China's non-resilient flooring sector. State-affiliated producers leverage green financing access for kiln electrification investments, while private fabricators concentrate on niche specification segments with lower capital barriers. Three archetypes dominate: scale-driven ceramic conglomerates with captive raw material supply, technology-focused sintered stone specialists, and cost-optimized laminate substrate integrators. Capacity expansion and backward integration into raw material production represent the dominant competitive moves as manufacturers defend margin structures against energy cost volatility.
Within the scale-driven ceramic tier, DongPeng Ceramics Co and China Ceramics Co Ltd occupy positions as representative listed entities with established project distributor relationships across tier-one commercial developments. Yihua Lifestyle Technology Co Ltd exemplifies the substrate integration archetype, with corporate naming indicating lifestyle-oriented positioning and technology-focused operational structure. The Marco Polo Group represents specialized sintered stone fabrication, with naming conventions suggesting heritage-brand positioning in premium surface categories. These three entities collectively illustrate the competitive spectrum from volume-scale ceramic production through technology-differentiated stone surfaces to cost-controlled laminate manufacturing.
| Leading Market Players |
|---|
| Zhejiang Shiyou Timber Co Ltd |
| Yihua Lifestyle Technology Co Ltd |
| China Ceramics Co Ltd |
| DongPeng Ceramics Co |
| Foshan Hanse Industrial Co Ltd |
| Rak Cermics PJSC |
| The Marco Polo Group |
| Nature Home Holding Co Ltd |
| Foshan Wondrous Building Materials Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Foshan's kiln capacity utilization rates above 85 percent generate scale economies that compress unit costs for compliant ceramic producers while elevating entry barriers for non-electrified competitors. Guangdong's manufacturing corridor concentrates 70 percent of domestic tile volume, creating pricing power asymmetries where MEE-certified producers command premium positioning in state-funded tenders while legacy coal-fired operations face margin erosion from compliance exclusion.
Pricing Analysis
Thin-body porcelain technologies command 15-25 percent premiums over conventional ceramic tile, while legacy laminate substrates face downward pressure from GB formaldehyde compliance requirements. Three-tier pricing structure across premium, standard, and economy levels separates MEE-certified sintered stone from mid-grade porcelain and entry-level vinyl imports. Cost compression in economy vinyl runs through Shanghai hospitality retrofits seeking rapid installation cycles. Residential homeowners in tier-two cities exhibit highest price sensitivity, while Beijing mixed-use developers prioritize lifecycle cost documentation over first-cost bidding.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes and Pearl River Delta port congestion elevate inbound logistics costs for raw material imports to Shandong laminate producers. Manufacturing gravity centers on China, with secondary supply nodes in Vietnam and Indonesia for ceramic tile finishing. Kiln operations draw from imported LNG feedstock, kaolin clay deposits, and aluminum oxide wear layer substrates. Single-province supply concentration creates systemic disruption risk from localized environmental enforcement. Distribution runs through project distributors serving Foshan cluster manufacturers for mortar-bed systems, while direct specification platforms capture vinyl flows to hospitality retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified mortar-bed technician scarcity and MEE electrification compliance gaps create capability bottlenecks that constrain large-format sintered stone deployment in tier-two markets. Manufacturers with captive technical training infrastructure and green financing access capture disproportionate share of premium commercial specifications.
For Market Incumbents: Shield margin structures by accelerating kiln electrification investments before MEE enforcement hardens, and secure backward integration into kaolin clay supply to offset LNG price volatility. DongPeng-scale ceramic conglomerates face emerging threat from technology-focused sintered stone specialists capturing specification share in Beijing mixed-use lobbies. Channel control through certified installer networks represents the critical defensive lever against click-lock vinyl displacement in hospitality retrofits. For New Entrants and Emerging Players: GB certification fast-track for antimicrobial porcelain surfaces opens positioning in Sichuan-Chongqing healthcare facility retrofits where Guangdong logistics constraints limit incumbent penetration. Western province underpenetration for large-format sintered stone offers white-space opportunity with lower capital barriers than Foshan kiln retrofit requirements. Direct engagement with Beijing and Guangzhou design institutes through digital specification platforms bypasses traditional distributor gatekeeping in commercial bids. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sintered stone specialists with R&D intensity in thin-body gauged porcelain over scale-driven ceramic conglomerates facing electrification capex burdens. Five-to-ten year viability hinges on MEE compliance certification durability and biomass hybrid firing technology maturation. Acquisition target archetype: mid-tier producers with GB-certified capacity and established project distributor relationships in tier-one commercial markets. Signal to watch: SAMR radon screening protocol harmonization with EU standards, which would compress natural stone import timelines and redirect specification flows.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Investment | MEE dual carbon compliance secures state procurement preference in public infrastructure tenders. |
| Backward Integration into Kaolin Supply | Captive raw material access insulates margin structures from LNG-driven energy cost volatility. |
| Certified Installer Network Development | Technical capability scarcity in tier-two markets creates completion bottleneck mitigation. |
| Digital Specification Platform Deployment | Direct architect engagement compresses traditional distributor influence in commercial bidding. |
| Antimicrobial Surface Certification | Healthcare facility retrofit demand accelerates for compliant porcelain in operating theater applications. |
Study Parameters
Desk research of MIIT regulatory filings, SAMR product registration databases, and Guangdong provincial industrial statistics preceded structured interviews with ceramic plant operations directors, commercial project developers in Shenzhen and Beijing, hospitality asset managers, and architecture firm specification leads. Primary fieldwork captured installation method constraints and procurement channel evolution. Secondary validation drew from customs export records, MEE emissions disclosure reports, and Foshan cluster production surveys. Bottom-up volume modeling triangulated against top-down construction spending allocation across application verticals.
Variance decomposition across product type, application, installation method, and end user dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured material rigidity tiers, project scale categories, and regional regulatory cluster differences. CAGRs derived from fitted growth curves applied to construction completion forecasts and replacement cycle assumptions. Industry-specific inputs included kiln electrification capex schedules and GB standard compliance transition timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained MEE enforcement intensity and stable LNG import pricing; material deviation would warrant model refresh. Forecasts embed assumptions regarding SAMR screening efficiency and biomass firing technology maturation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market