
 Quarter Sawn Flooring Market | 2026-2036
Quarter Sawn Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Quarter Sawn Flooring Market Analytics
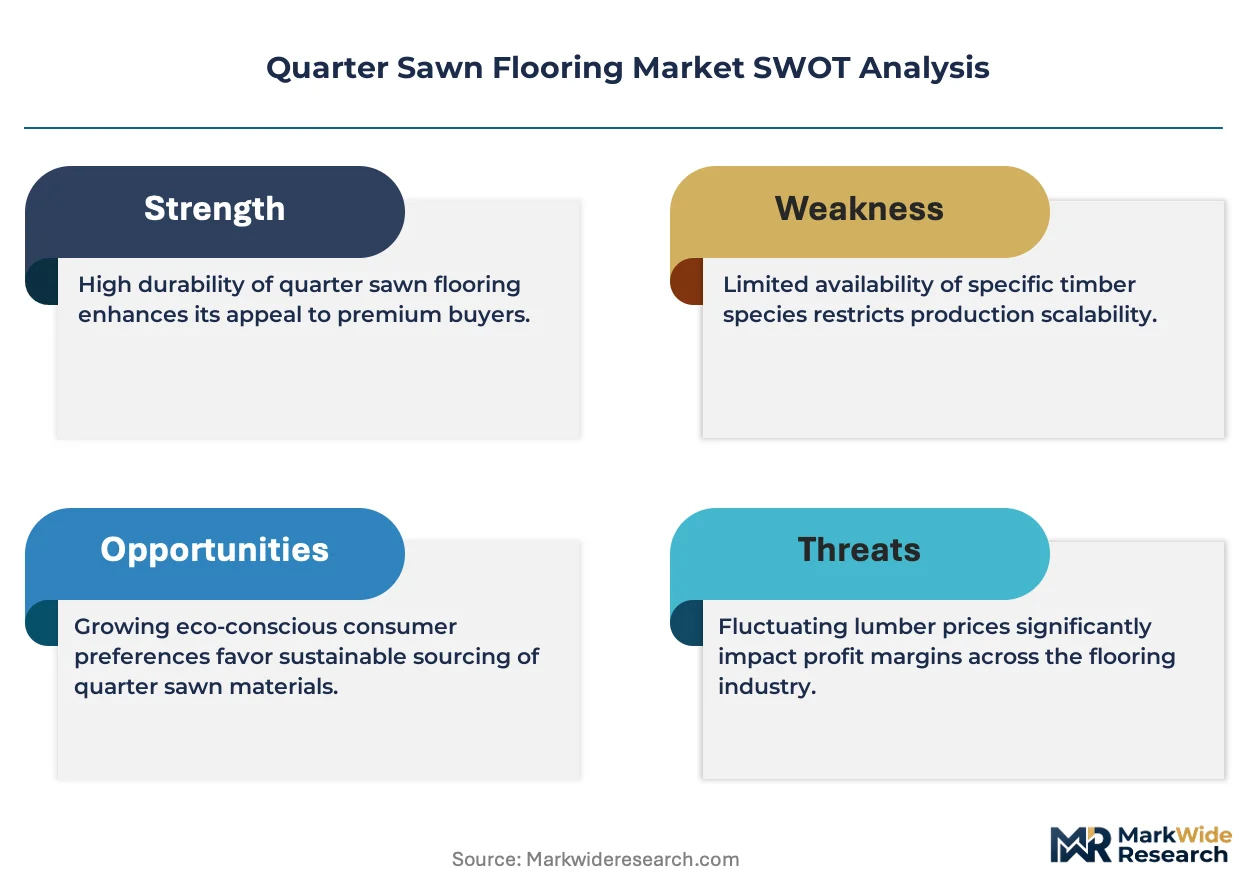
The Great Lakes manufacturing corridor is narrowing its cost gap with Appalachian sawmill regions as Wisconsin and Michigan expand kiln-drying capacity for white oak quarter sawn stock. Frank Miller Lumber Company leverages vertical integration from Appalachian timberlands through Indiana milling operations to control grade consistency. Taylor Lumber anchors its market position in premium residential channels through specialized rift-and-quartered product lines. Northwest Hardwoods competes on volume scale across commercial specification grades.
Quarter sawn hardwood refers to boards cut at a 60-90 degree angle to the growth rings, producing straight grain with prominent medullary ray fleck and superior dimensional stability against cupping and warping. Oak dominates material type demand due to its favorable ray structure and established specification in high-end residential and heritage commercial restoration projects. Pre-finished products capture expanding share as factory-applied UV-cured aluminum oxide coatings reduce on-site labor and volatile organic compound exposure. Nail-down installation retains primacy in solid hardwood applications while floating systems gain traction in multi-family residential retrofits over concrete subfloors.
EPA TSCA Title VI governs formaldehyde emissions from composite wood products including engineered quarter sawn flooring substrates, while OSHA workplace standards regulate sawdust exposure in milling operations. The EU Timber Regulation and associated EUTR due diligence requirements constrain import sourcing for European market access, favoring chain-of-custody certified suppliers. Stakeholders must monitor hardwood timber supply constraints from oak decline syndrome and emerging competing demand from bourbon barrel cooperage.

Market Dynamics
EPA TSCA Title VI formaldehyde emission standards are compressing engineered flooring margins while concentrating supply among vertically integrated manufacturers with captive adhesive chemistry capabilities. This regulatory pressure intersects with oak timber supply constraints from Appalachian decline syndrome to reshape competitive positioning across the Great Lakes manufacturing corridor.
Growth Catalysts
- Heritage Commercial Restoration:Historic building renovation projects across the United States and Canada specify quarter sawn oak for its authentic ray fleck pattern and dimensional stability under climate-controlled museum and institutional environments.
- EPA TSCA Title VI Compliance:Stricter formaldehyde emission standards for composite wood products are accelerating consolidation toward manufacturers with in-house low-emitting adhesive formulation expertise and third-party certification infrastructure.
- Kiln-Drying Technology Advancement:Wisconsin and Michigan sawmills deploying computer-controlled drying schedules reduce moisture content variation in white oak quarter sawn stock, improving grade yields and reducing downstream waste.
Market Restraints
- White Oak Timber Supply Concentration:Appalachian timberland ownership concentrates among a limited number of institutional landowners, creating input cost volatility and long-term supply uncertainty from oak decline syndrome.
- Competing Bourbon Barrel Demand:Kentucky and Tennessee cooperage operations consume premium white oak staves, diverting grade-suitable logs from flooring manufacturers and compressing available supply for quarter sawn production.
- Substitution by Luxury Vinyl Tile:High-end LVT products with embossed-in-register grain patterns capture specification share in multi-family residential and commercial sectors where moisture resistance outweighs authentic hardwood preference.
Strategic Opportunities
- Pre-Finished Product Expansion:Factory-applied UV-cured aluminum oxide coatings reduce on-site labor costs and volatile organic compound exposure, opening specification channels in healthcare and educational facilities with strict indoor air quality protocols.
- Floating Installation Systems:Click-lock engineered quarter sawn products enable retrofit applications over concrete subfloors in urban multi-family housing stock across Chicago, Detroit, and Cleveland without traditional nail-down requirements.
- EU Timber Regulation Compliance:Chain-of-custody certification under EUTR due diligence requirements creates export market access for North American suppliers with documented sustainable sourcing, differentiating against non-certified competitors.
Industry Challenges
- Skilled Sawyer Shortage:Quarter sawing requires precise log positioning and specialized headrig operation to achieve 60-90 degree ring angles, with aging workforce demographics constraining production capacity expansion in the Great Lakes corridor.
- Grade Consistency Certification:Maintaining consistent ray fleck prominence and dimensional stability across production lots demands rigorous quality control infrastructure that smaller independent mills struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quarter Sawn Flooring Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Oak, Maple, Cherry, Ash Finish Type: Pre-finished, Unfinished, Matte, Glossy Application: Residential, Commercial, Sports Facilities, Retail Stores Installation Method: Nail Down, Glue Down, Floating, Staple Down |
| Companies Covered | Quarter-Sawn Flooring Inc., Taylor Lumber, Stonewood Products, The Hickman Lumber Company, Frank Miller Lumber Company, Timberline Hardwood Floors, Sheoga Hardwood Flooring, Northwest Hardwoods, Baillie Lumber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quarter Sawn Flooring Market Evolving Landscape
Manufacturing technology and regulatory compliance requirements are converging to reshape product configuration and distribution models across the quarter sawn flooring value chain. Three distinct developments are compressing traditional competitive advantages while creating new specification barriers.
Factory-applied UV-cured aluminum oxide coating systems are migrating from niche premium positioning toward standard specification across engineered quarter sawn product lines. Luxury residential developers in the United States and Canada increasingly require pre-finished products to reduce on-site labor scheduling complexity and accelerate project completion timelines. This technology compression is eliminating margin differentiation previously captured by site-finished installations while concentrating volume among manufacturers with captive coating lines.
EPA TSCA Title VI formaldehyde emission standards for composite wood products are tightening adhesive chemistry requirements across engineered flooring substrates. Manufacturers without in-house low-emitting resin formulation capabilities face third-party certification costs and supply chain documentation burdens that favor larger integrated producers. The engineered segment bears disproportionate compliance impact as solid hardwood variants fall outside composite wood product definitions.
Specification patterns among luxury residential architects are rotating toward documented chain-of-custody certification as a prerequisite for project inclusion. The EU Timber Regulation and associated due diligence requirements constrain European market access, while LEED and WELL building standards in North America reward verified sustainable sourcing. This behavioral shift concentrates specification share among suppliers with Forest Stewardship Council or Programme for the Endorsement of Forest Certification documentation infrastructure.
Quarter Sawn Flooring Market Segmentation
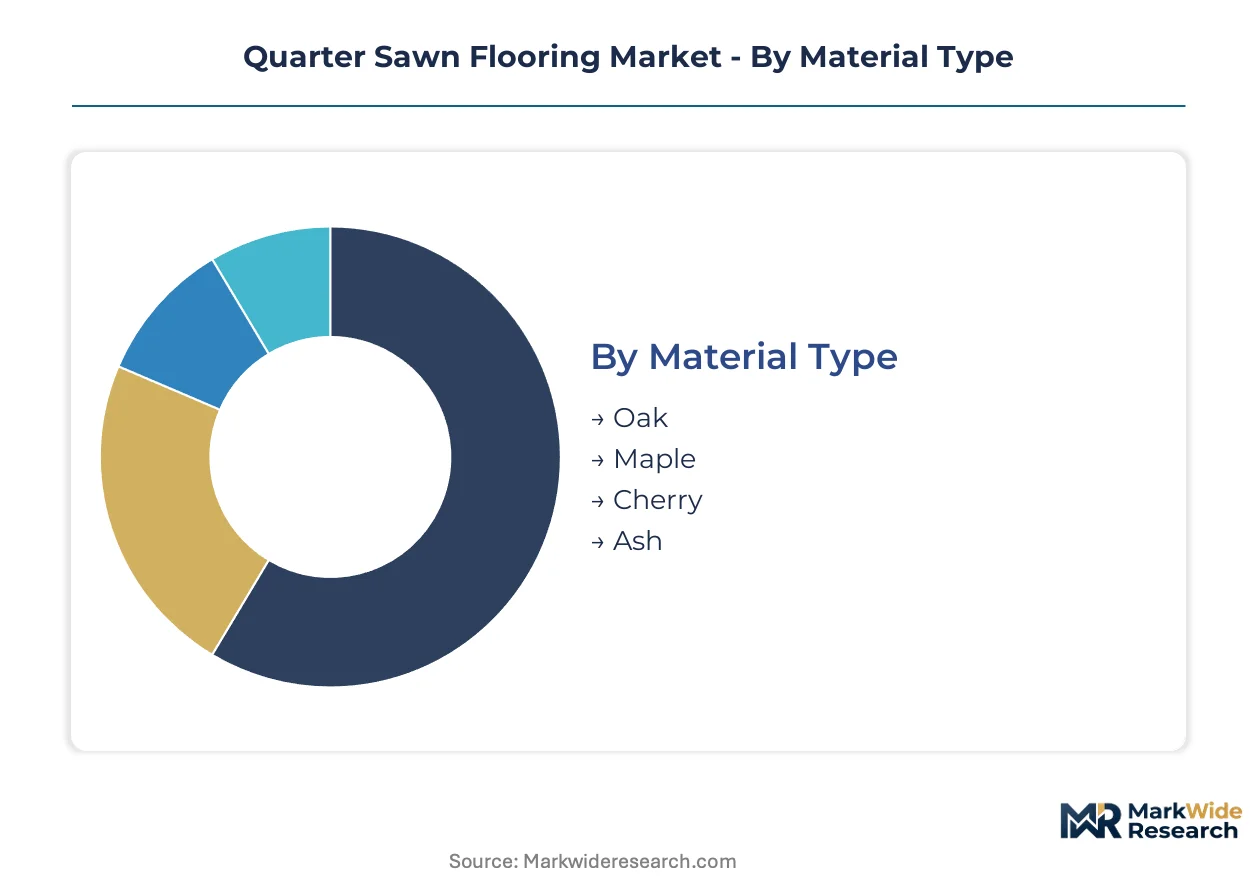
Quarter sawn flooring procurement decisions cascade through material specification, finish chemistry, and installation constraints. Each segmentation dimension carries distinct service intensity requirements that reshape supplier relationships and margin structures across the value chain.
Material Type:
After-sales service intensity varies sharply across species due to differential moisture response and restoration complexity.
- Oak:White oak's prominent medullary ray structure produces the signature fleck pattern architects specify for heritage commercial restoration. Demand concentrates in the Great Lakes corridor where Wisconsin and Michigan sawmills serve Chicago, Detroit, and Cleveland luxury residential developers. EPA TSCA Title VI compliance costs compress margins for engineered variants.
- Maple:Hard maple offers superior abrasion resistance for sports facility applications with less pronounced ray fleck. Canadian specification in Toronto and Vancouver hockey arenas and dance studios drives steady demand, though narrower plank availability limits residential penetration.
- Cherry:Darkening patina development requires customer education on color evolution over time.
- Ash:Emerald ash borer devastation has collapsed North American supply, forcing European import reliance.
By volume, Oak leads. By growth pace, Maple is ahead in commercial specification channels.
Finish Type:
Cost tier separation between factory and site-applied finishes is widening as labor rates escalate.
- Pre-finished:UV-cured aluminum oxide coatings applied under controlled factory conditions eliminate on-site volatile organic compound exposure. Healthcare and educational facilities in California and New York mandate these products for indoor air quality compliance. Factory warranties reduce contractor liability exposure.
- Unfinished:Site-sanding and oil-based polyurethane application retains specification among custom homebuilders seeking seamless integration with existing floors. High-end Manhattan and Hamptons residential projects favor this approach despite extended project timelines.
- Matte:Low-sheen aesthetics align with Scandinavian-influenced interior design trends.
- Glossy:High-build finishes persist in traditional formal residential settings.
Pre-finished products dominate new construction volume; unfinished retains renovation share where floor matching is critical.
Application:
Customer type determines specification authority and decision speed across end-use segments.
- Residential:Luxury single-family construction and high-end renovation specify quarter sawn oak for dimensional stability in climate-controlled environments. Architect-driven selection in Aspen, Napa Valley, and Nantucket prioritizes ray fleck prominence and chain-of-custody certification.
- Commercial:Corporate headquarters and hospitality projects balance first-cost against lifecycle performance. LEED and WELL building standard compliance rewards documented sustainable sourcing, concentrating specification among FSC-certified suppliers.
- Sports Facilities:Shock absorption and ball rebound specifications govern maple selection.
- Retail Stores:Brand environment durability requirements favor engineered construction for high-traffic zones.
Residential generates the largest absolute volume; commercial specification is climbing fastest as heritage restoration accelerates.
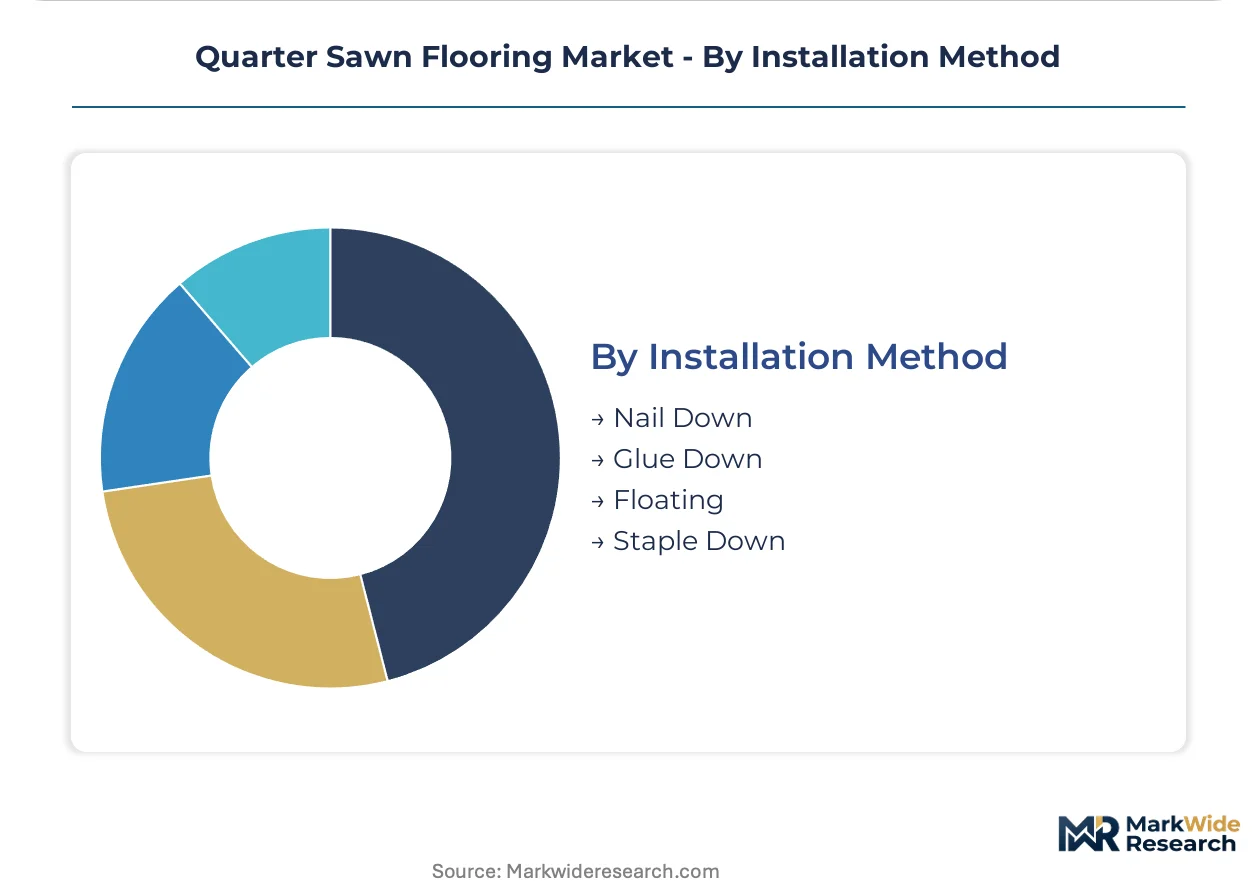
Installation Method:
Supply concentration in the Great Lakes corridor shapes regional installation capability development.
- Nail Down:Traditional solid hardwood installation over plywood subfloors retains primacy in new residential construction. Wisconsin and Michigan contractor networks maintain specialized skills for quarter sawn plank handling to prevent edge splintering during fastening.
- Glue Down:Direct adhesive bonding to concrete subfloors enables engineered product specification in urban multi-family retrofits. Chicago and Detroit building stock conversion projects favor this approach for acoustic isolation performance.
- Floating:Click-lock systems reduce skilled labor requirements and enable future removal.
- Staple Down:Pneumatic fastening of engineered products offers speed advantages in production homebuilding.
Nail down remains the volume leader; floating systems are expanding most quickly in renovation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States luxury residential developers prize quarter sawn oak for dimensional stability and ray fleck aesthetics, while Canadian specification emphasizes chain-of-custody certification for European export compliance. German heritage restoration projects drive white oak demand with distinct grading requirements.
United States
Luxury single-family construction in Aspen, Napa Valley, and Nantucket specifies quarter sawn oak for climate-controlled environments where dimensional stability prevents seasonal gapping. EPA TSCA Title VI formaldehyde emission standards govern engineered substrate compliance, compressing margins for non-integrated manufacturers. The Great Lakes corridor spanning Michigan, Wisconsin, and Ohio anchors production capacity with expanding kiln-drying infrastructure for white oak stock.
Canada
Toronto and Vancouver architects specify hard maple for sports facilities and commercial installations requiring superior abrasion resistance. The EU Timber Regulation drives chain-of-custody certification adoption among Ontario and Quebec mills seeking European market access. British Columbia suppliers leverage proximity to Pacific export terminals for Asian specification-grade shipments.
Germany
Heritage commercial restoration across Berlin, Munich, and Hamburg demands authentic ray fleck patterns for museum and institutional environments. REACH chemical regulations constrain adhesive formulations for engineered imports, favoring domestic mills with compliant chemistry. Bavarian timber processors specialize in white oak quarter sawn production for Central European heritage projects.
United Kingdom
London and Southeast England luxury residential renovation specifies quarter sawn oak for period property restoration matching original 19th-century installations. The Timber Regulation due diligence requirements mandate documented sustainable sourcing for all hardwood imports. Scottish mills develop specialized rift-and-quartered product lines for high-end Edinburgh and Glasgow residential channels.
Japan
Tokyo and Osaka commercial interiors specify quarter sawn white oak for Scandinavian-influenced design trends emphasizing natural grain prominence. JIS standards govern dimensional tolerance and moisture content for imported flooring materials. Nagoya-area distributors concentrate inventory for central Japan construction projects requiring documented chain-of-custody certification.
Quarter Sawn Flooring Market Competitive Landscape
Capability concentration sits with vertically integrated timberland-to-mill operators; scale advantage sits with volume-oriented distributors serving commercial specification channels. The market structures around three archetypes: Appalachian timberland owners with captive sawmill operations, Great Lakes specialists in kiln-dried white oak production, and national distributors leveraging multi-species portfolio breadth. Consolidation pressures favor backward integration into timberland assets and captive adhesive chemistry capabilities.
Within the integrated timberland-milling tier, Frank Miller Lumber Company and Taylor Lumber exemplify divergent strategic positioning. Frank Miller Lumber Company anchors its market presence through Appalachian timberland ownership extending through Indiana milling operations. Taylor Lumber occupies a specialist position in premium residential channels through concentrated rift-and-quartered product development. Northwest Hardwoods represents the scale-driven archetype competing across commercial specification grades with volume-based logistics infrastructure.
| Leading Market Players |
|---|
| Quarter-Sawn Flooring Inc. |
| Taylor Lumber |
| Stonewood Products |
| The Hickman Lumber Company |
| Frank Miller Lumber Company |
| Timberline Hardwood Floors |
| Sheoga Hardwood Flooring |
| Northwest Hardwoods |
| Baillie Lumber |
| Others |
Value Network & Pricing Analysis
The Great Lakes manufacturing corridor spanning Michigan, Wisconsin, and Ohio commands downstream pricing power through concentrated kiln-drying capacity for white oak quarter sawn stock. EPA TSCA Title VI compliance costs for engineered substrates and competing bourbon barrel demand for premium staves compress margin flexibility across the value chain.
Pricing Analysis
Long-term offtake contracts between Great Lakes sawmills and luxury residential developers anchor volume pricing, while spot market transactions for heritage restoration projects capture premium tiers. Price differentiation rests on ray fleck grade consistency and FSC chain-of-custody certification, with certified products commanding substantial premiums over uncertified alternatives. Cost compression in engineered variants is intensifying because captive adhesive chemistry capabilities concentrate among vertically integrated manufacturers. Commercial specification buyers exhibit highest price sensitivity, whereas architect-driven residential projects in Aspen and Nantucket demonstrate lowest sensitivity to cost escalation.
Supply Chain Analysis
Extended payment terms from national distributors to Appalachian timberland owners strain working capital across the value chain, favoring institutional landowners with supply-chain finance facilities. Raw material supply concentrates in the United States, Canada, and Germany, with white oak timber from Appalachian holdings feeding Great Lakes milling operations and Bavarian processors serving Central European heritage projects. The supply chain draws from specialized sawyer labor pools, computer-controlled kiln-drying equipment, and low-emitting adhesive formulations. Single-source vulnerability in Appalachian timberland ownership creates structural risk from oak decline syndrome. Distribution runs through regional hardwood distributors serving commercial specification channels and direct mill relationships for premium residential projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as specification authority fragments among architects, sustainability consultants, and heritage restoration specialists, each demanding differentiated product documentation and service intensity.
For Market Incumbents: Pre-empt substitution pressure from luxury vinyl tile by expanding captive pre-finishing capacity with UV-cured aluminum oxide coating lines. Consolidate timberland positions in Appalachian holdings to secure white oak supply against bourbon barrel cooperage competition. Backward integration into kiln-drying technology preserves grade yield advantages over independent sawmills lacking capital for computer-controlled drying infrastructure. For New Entrants and Emerging Players: Japanese commercial interiors present underpenetrated specification channels where Scandinavian-influenced design trends favor natural grain prominence and documented chain-of-custody certification. Target floating installation systems for Chicago and Detroit multi-family retrofits over concrete subfloors, where click-lock engineered products reduce skilled labor requirements. Pursue EU Timber Regulation compliance as a go-to-market wedge, differentiating against North American competitors lacking EUTR documentation infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated timberland-to-mill operators with captive adhesive chemistry capabilities and pre-finishing infrastructure. Long-term viability over the projection horizon rests on oak timber supply security and regulatory compliance infrastructure rather than volume scale. Monitor bourbon barrel cooperage demand as the critical inflection signal for white oak log availability and input cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Timberland Acquisition | Appalachian white oak holdings secure supply against bourbon barrel competition and oak decline syndrome. |
| Pre-Finishing Capacity Expansion | Factory-applied UV-cured coatings capture healthcare and educational specification channels with indoor air quality compliance. |
| EUTR Certification Investment | Chain-of-custody documentation opens European heritage restoration projects and differentiates against non-certified competitors. |
| Kiln-Drying Technology Deployment | Computer-controlled drying schedules improve white oak grade yields and reduce moisture content variation. |
| Floating System Product Development | Click-lock engineered platforms enable urban multi-family retrofits over concrete subfloors without nail-down requirements. |
Research Methodology
A spread of perspectives from sawmill operations managers, hardwood distribution procurement leads, luxury residential architects, heritage restoration contractors, and EPA compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of publicly traded timberland REITs, Forest Stewardship Council certification databases, and EPA TSCA Title VI compliance registries. Bottom-up volume estimates from mill capacity utilization and grade yield data triangulated against top-down demand projections from construction permit filings and architectural specification surveys.
Demand-supply balance modeling across material type, finish configuration, installation method, and application segments generated volume and value outputs over the projection horizon. The analytical framework incorporated white oak timber supply constraints from Appalachian decline syndrome, competing bourbon barrel cooperage demand, and EPA formaldehyde emission standard compliance costs as industry-specific forecast inputs. CAGRs derived from segment-level growth rate assumptions weighted by base-year volume shares.
The forecast holds incumbent behavior within observed patterns; aggressive timberland acquisition moves by institutional investors or rapid LVT substitution in multi-family residential would shift outcomes. Macroeconomic deviation in luxury residential construction, regulatory tightening on formaldehyde emissions, or technological breakthrough in engineered wood adhesives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market