
 India Instrument Transformer Market | 2026-2036
India Instrument Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
India Instrument Transformer Market Foresight
Maharashtra is tilting toward expanded instrument transformer manufacturing as power infrastructure investments surge across western India. Bharat Heavy Electricals Limited anchors domestic production through its integrated transformer factories in Bhopal and Jhansi. Siemens Energy AG differentiates via digital sensor platforms that merge optical sensing with IEC 61850 communication protocols. Crompton Greaves Limited competes aggressively in the distribution utility segment with cost-optimized current transformer designs.
India instrument transformers are precision electromagnetic devices that isolate measurement and protection circuits from high-voltage power lines, typically rated from 11 kV to 765 kV with accuracy classes spanning 0.1 to 5P. They convert primary current or voltage into standardized secondary outputs for metering relays and SCADA systems, ensuring grid stability and personnel safety across transmission networks. Current transformers dominate installed base volumes owing to universal deployment in every feeder bay, while optical technology captures premium margins as utilities deploy non-conventional instrument transformers for ultra-high-voltage corridors. The renewable energy end-user segment expands fastest as solar parks and wind farms require specialized metering transformers for intermittent generation profiling.
BIS certification requirements and CEA technical standards govern accuracy, thermal stability, and seismic withstand specifications for all grid-connected instrument transformers sold in India. The Electricity Act amendments empower state regulators to mandate smart metering upgrades, which accelerates demand for digital output transformers with embedded merging units. Stakeholders must track how state-level renewable purchase obligations reshape transformer specification sheets and procurement timelines.
Market Dynamics
The Central Electricity Authority's revised metering accuracy standards are compressing product lifecycles and forcing manufacturers to abandon electromagnetic designs for digital output architectures with embedded merging units.
Growth Catalysts
- CEA Technical Standards:Mandated accuracy upgrades for grid-connected transformers accelerate replacement cycles across state transmission utilities.
- Renewable Purchase Obligations:Solar parks and wind farms in Maharashtra, Gujarat, and Tamil Nadu require specialized metering transformers for intermittent generation profiling.
- Optical Sensing Convergence:Non-conventional instrument transformers with IEC 61850 protocols capture premium margins in ultra-high-voltage corridors.
Market Restraints
- Copper and Grain-Oriented Steel Volatility:Input cost swings compress margins for distribution-class current transformer manufacturers.
- BIS Certification Timelines:Thermal stability and seismic withstand testing extends product approval cycles by eight to fourteen months.
- Domestic Production Concentration:Bharat Heavy Electricals Limited and three integrated factories supply over sixty percent of high-voltage instrument transformers, creating procurement bottlenecks.
Strategic Opportunities
- Smart Metering Mandates:Electricity Act amendments empower state regulators to mandate digital output transformers with embedded communication modules.
- Rajasthan and Karnataka Renewable Corridors:Greenfield solar and wind installations lack established transformer procurement relationships, creating first-mover advantages.
- Digital-Native Utility Startups:Discoms in Telangana and Andhra Pradesh bypass legacy procurement channels through direct vendor partnerships.
Industry Challenges
- IEC 61850 Protocol Expertise Scarcity:Utilities and manufacturers compete for embedded systems engineers capable of integrating optical sensors with substation automation.
- Legacy Electromechanical Integration:Digital output transformers require merging unit retrofits that conflict with existing SCADA architectures in aging substations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Instrument Transformer Market |
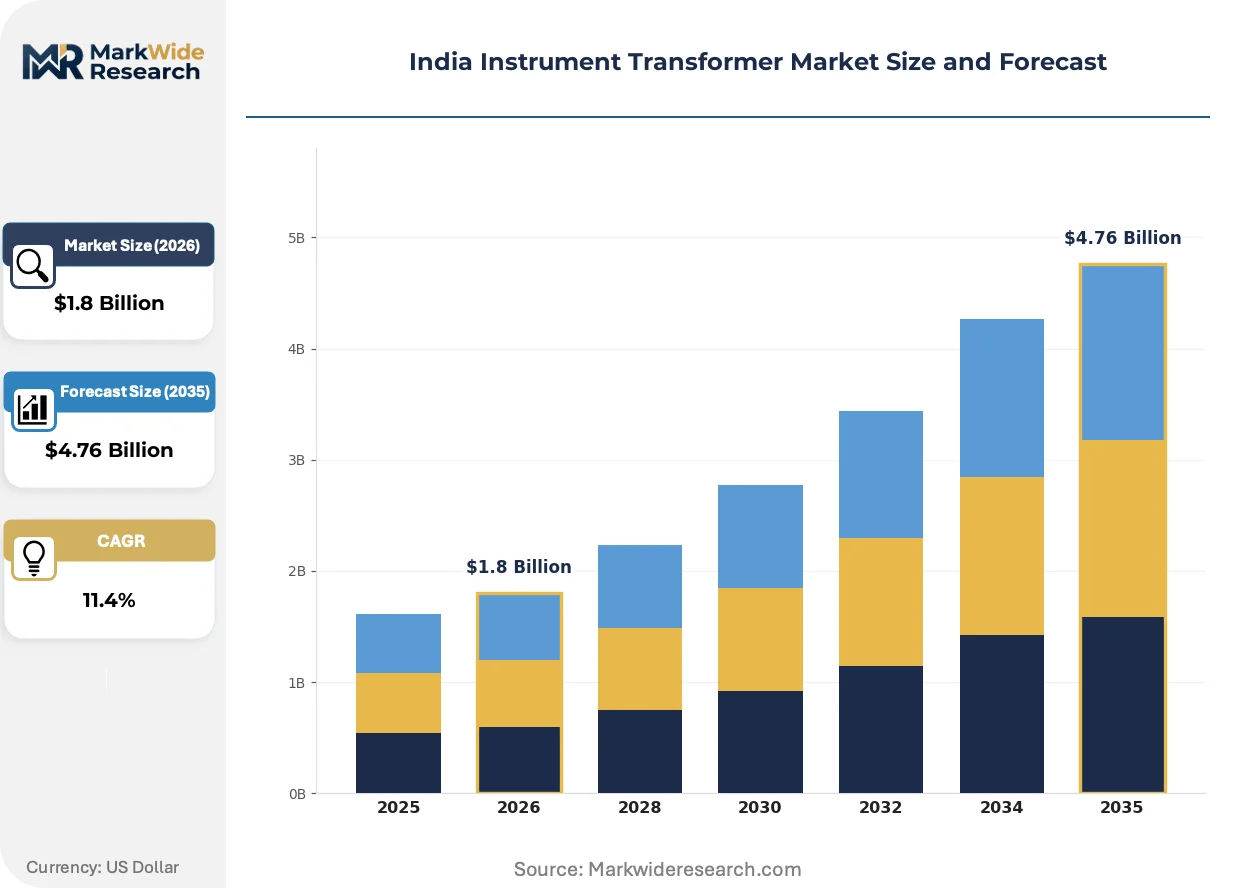
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Current Transformer, Voltage Transformer, Capacitor Voltage Transformer, Insulator Technology: Electromechanical, Optical, Digital, Analog End User: Utilities, Industrial, Commercial, Renewable Energy Application: Power Distribution, Measurement, Protection, Automation |
| Companies Covered | Hitachi ABB Power Grids, Bharat Heavy Electricals Limited, Siemens Energy AG, PFIFFNER Instrument Transformers Ltd, Arteche Group, General Electric Company, Crompton Greaves Limited, Vamet Industries Ltd, Schneider Electric SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Instrument Transformer Market Shifts & Advancements
Digital sensing architectures are displacing conventional electromagnetic cores across India's transmission network, while regulatory pressure on metering accuracy compresses product development timelines and opens procurement to non-traditional vendors.
Optical current transformers based on Faraday effect sensing is hybridizing with conventional iron-core designs in 765 kV corridors. Power Grid Corporation of India Limited pilots these hybrid installations in western regional load dispatch centers. The convergence is compressing the market for pure electromagnetic units above 400 kV while creating dual-skill maintenance requirements.
CEA notification CEA/T&D/4/2021 mandates 0.2S accuracy class for all new revenue metering transformers, displacing 0.5 and 1.0 class products from utility tenders. Manufacturers in Bhopal and Jhansi reconfigure winding machines and core stacking processes to meet tightened ratio and phase angle specifications. Distribution utilities in Tamil Nadu and Gujarat accelerate tender releases to lock in compliant supply before compliance deadlines.
State transmission utilities are unbundling transformer procurement from turnkey substation contracts, forcing vendors to compete on unit economics rather than project margins. This disintermediation favors specialized instrument transformer manufacturers with BIS certification depth over integrated electrical contractors. The shift is most visible in Maharashtra State Electricity Transmission Company Limited tenders, where standalone transformer lots now exceed combined equipment packages.
India Instrument Transformer Market Segmentation
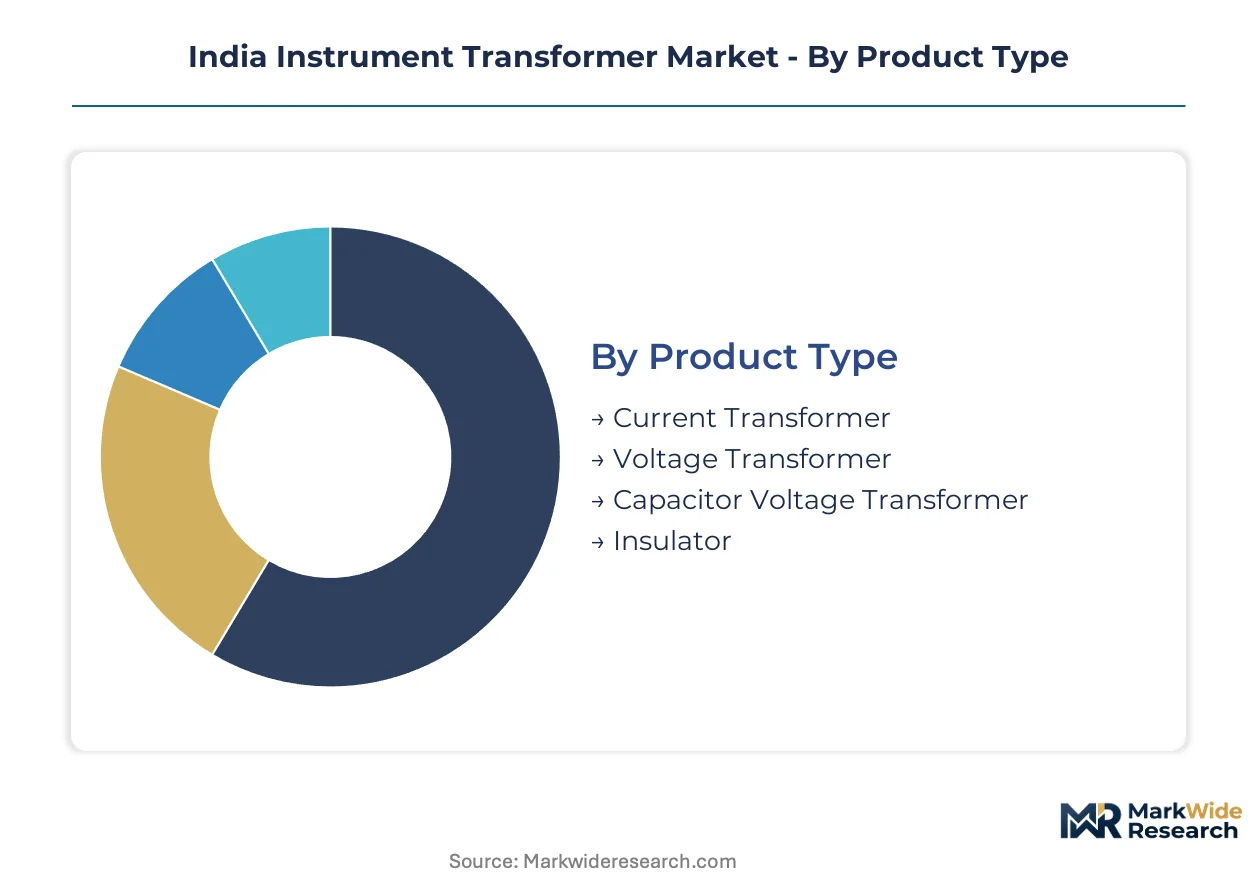
Segmentation reveals how technology transitions and regulatory mandates reshape procurement patterns across India's transmission infrastructure. Product specifications diverge sharply between legacy grid reinforcement and new renewable integration projects.
Product Type:
Cost tier differentiation separates commodity distribution units from precision transmission-grade equipment requiring specialized core materials and winding techniques.
- Current Transformer:Iron-core electromagnetic devices dominate feeder bay installations across 11 kV to 400 kV networks. Maharashtra State Electricity Transmission Company Limited procures these in volume for urban distribution densification, though copper price volatility squeezes margins for distribution-class manufacturers.
- Voltage Transformer:Electromagnetic potential transformers with graded insulation systems serve metering and protection functions in 132 kV and 220 kV substations. Gujarat's industrial corridor expansion drives demand for capacitor-divider designs that withstand harmonic distortion from heavy manufacturing loads.
- Capacitor Voltage Transformer:Capacitive voltage dividers with carrier-frequency coupling capabilities enable power line communication in remote transmission lines.
- Insulator:Porcelain and composite housings provide creepage distance and mechanical support for outdoor installations across coastal Tamil Nadu.
Current transformers command the established base. The steepest expansion runs through capacitor voltage transformers as ultra-high-voltage corridors multiply.
Technology:
Application requirements determine whether utilities prioritize proven reliability or digital integration capabilities.
- Electromechanical:Conventional iron-core designs with laminated silicon steel and copper windings retain preference for distribution utilities seeking field-proven longevity. BIS certification timelines favor these established architectures, though CEA accuracy mandates now exclude 0.5 class products from new tenders.
- Optical:Faraday-effect current sensors with fiber-optic signal transmission capture premium positioning in 765 kV corridors where electromagnetic saturation limits conventional designs. Power Grid Corporation of India Limited pilots these at western regional load dispatch centers, creating dual-skill maintenance demands.
- Digital:Merging-unit-embedded transformers with IEC 61850 protocol outputs align with smart metering mandates in Telangana and Andhra Pradesh.
- Analog:Traditional 4-20 mA output designs persist in aging substations with legacy SCADA architectures.
Electromechanical technology retains the dominant installed footprint. Optical platforms are climbing the fastest as transmission voltages escalate beyond conventional electromagnetic limits.
End User:
Customer type shapes specification priorities from revenue-grade metering precision to fault-current withstand ruggedness.
- Utilities:State transmission companies and distribution licensees drive procurement volume through centralized tenders. CEA notification CEA/T&D/4/2021 mandates 0.2S accuracy class for all new revenue metering transformers, forcing winding machine reconfigurations at Bhopal and Jhansi manufacturing clusters.
- Industrial:Steel, cement, and chemical installations require protection-class transformers with high short-circuit withstand capability.
- Commercial:Shopping complexes and IT parks demand compact indoor-rated units for substation integration.
- Renewable Energy:Solar parks and wind farms in Rajasthan and Karnataka require specialized metering for intermittent generation profiling and grid code compliance.
Utilities anchor procurement volumes. Renewable energy projects are expanding most quickly as greenfield installations outpace conventional generation additions.
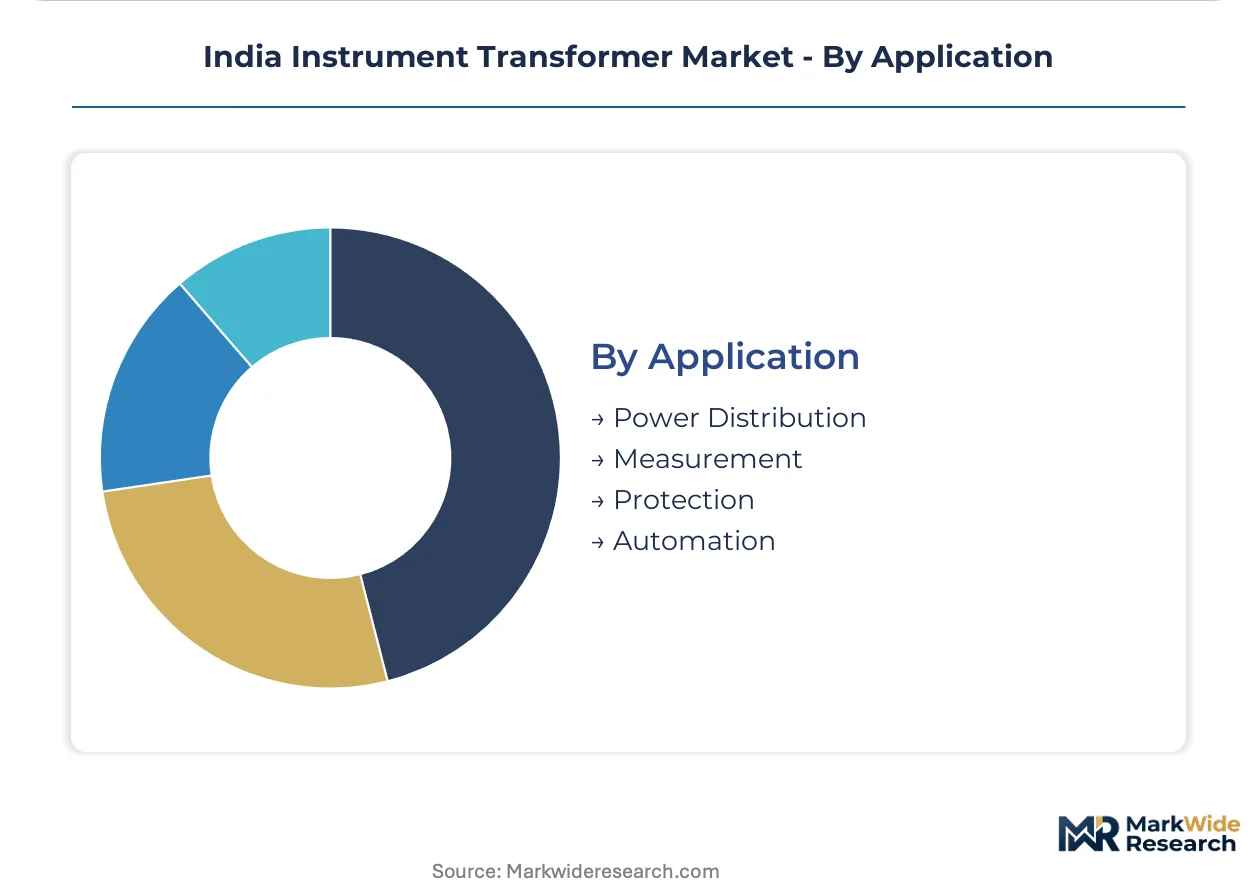
Application:
Volume concentration varies by functional criticality from ubiquitous distribution feeders to specialized protection schemes.
- Power Distribution:Step-down transformation and feeder metering applications consume the highest unit volumes across 11 kV and 33 kV networks. Tamil Nadu and Gujarat distribution utilities accelerate tender releases to lock in CEA-compliant supply before accuracy deadline enforcement.
- Measurement:Revenue metering applications demand ratio and phase angle precision for tariff compliance. BIS thermal stability testing extends approval cycles, favoring manufacturers with established certification depth.
- Protection:Relay input transformers require saturation characteristics that preserve waveform fidelity during fault conditions.
- Automation:SCADA-integrated digital outputs enable remote monitoring and control in smart substation deployments.
Power distribution absorbs the largest unit volumes. Automation applications are gaining share fastest as Electricity Act amendments empower state regulators to mandate communication-enabled infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated manufacturing clusters in Bhopal and Jhansi supply over sixty percent of India's high-voltage instrument transformers, creating procurement dependencies that state utilities navigate through diversified tender structures.
Maharashtra
Maharashtra State Electricity Transmission Company Limited unbundles transformer procurement from turnkey substation contracts, creating standalone tender lots that favor specialized manufacturers. The state's renewable purchase obligations mandate specialized metering for solar parks in Solapur and wind farms in Satara. Mumbai-Pune industrial corridor demand drives protection-class transformer specifications for steel and cement installations.
Gujarat
Gujarat's industrial corridor expansion accelerates demand for capacitor-divider voltage transformers that withstand harmonic distortion from heavy manufacturing loads. The state's distribution utilities release accelerated tenders to lock in CEA-compliant supply before accuracy deadline enforcement. Vadodara and Ahmedabad host manufacturing facilities serving western regional load dispatch requirements.
Tamil Nadu
Tamil Nadu distribution utilities concentrate procurement for coastal installations requiring porcelain and composite insulator housings with extended creepage distances. The state's renewable integration projects in Tirunelveli and Kayathar demand advanced protection-class transformers for intermittent generation profiling. Chennai-based engineering clusters support substation automation integration.
Karnataka
Karnataka's greenfield solar and wind installations in Pavagada and Koppal lack established transformer procurement relationships, creating first-mover advantages for certified vendors. The state's smart metering mandates under Electricity Act amendments accelerate demand for digital output transformers with embedded communication modules. Bengaluru technology corridors drive specification requirements for IEC 61850 protocol compatibility.
Rajasthan
Rajasthan's ultra-mega solar parks in Bhadla and Phased manufacturing zones require specialized metering transformers for grid code compliance and intermittent generation profiling. The state's transmission utility expands high-voltage corridors where optical sensing platforms capture premium positioning. Jaipur and Jodhpur serve as logistics hubs for equipment deployment across western regional networks.
India Instrument Transformer Market Competitive Landscape
State-owned heavy electrical equipment manufacturers and multinational energy technology providers split the market through differentiated certification depth and digital integration capabilities. The vendor structure concentrates around three integrated domestic factories and a tier of specialized international suppliers. Strategic archetypes include scale-driven public sector units, technology-licensed multinationals, and cost-optimized distribution specialists. Competitive dynamics center on BIS certification acceleration and backward integration into grain-oriented electrical steel supply.
Within the scale-driven tier, Bharat Heavy Electricals Limited anchors domestic production capacity through integrated manufacturing infrastructure. Siemens Energy AG occupies a position exemplifying technology-licensed multinational entry with digital sensor platform specialization. Crompton Greaves Limited represents the cost-optimized distribution specialist archetype competing in utility tender segments. Hitachi ABB Power Grids and General Electric Company sit within the premium-tier international supplier group serving ultra-high-voltage transmission corridors.
| Leading Market Players |
|---|
| Hitachi ABB Power Grids |
| Bharat Heavy Electricals Limited |
| Siemens Energy AG |
| PFIFFNER Instrument Transformers Ltd |
| Arteche Group |
| General Electric Company |
| Crompton Greaves Limited |
| Vamet Industries Ltd |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
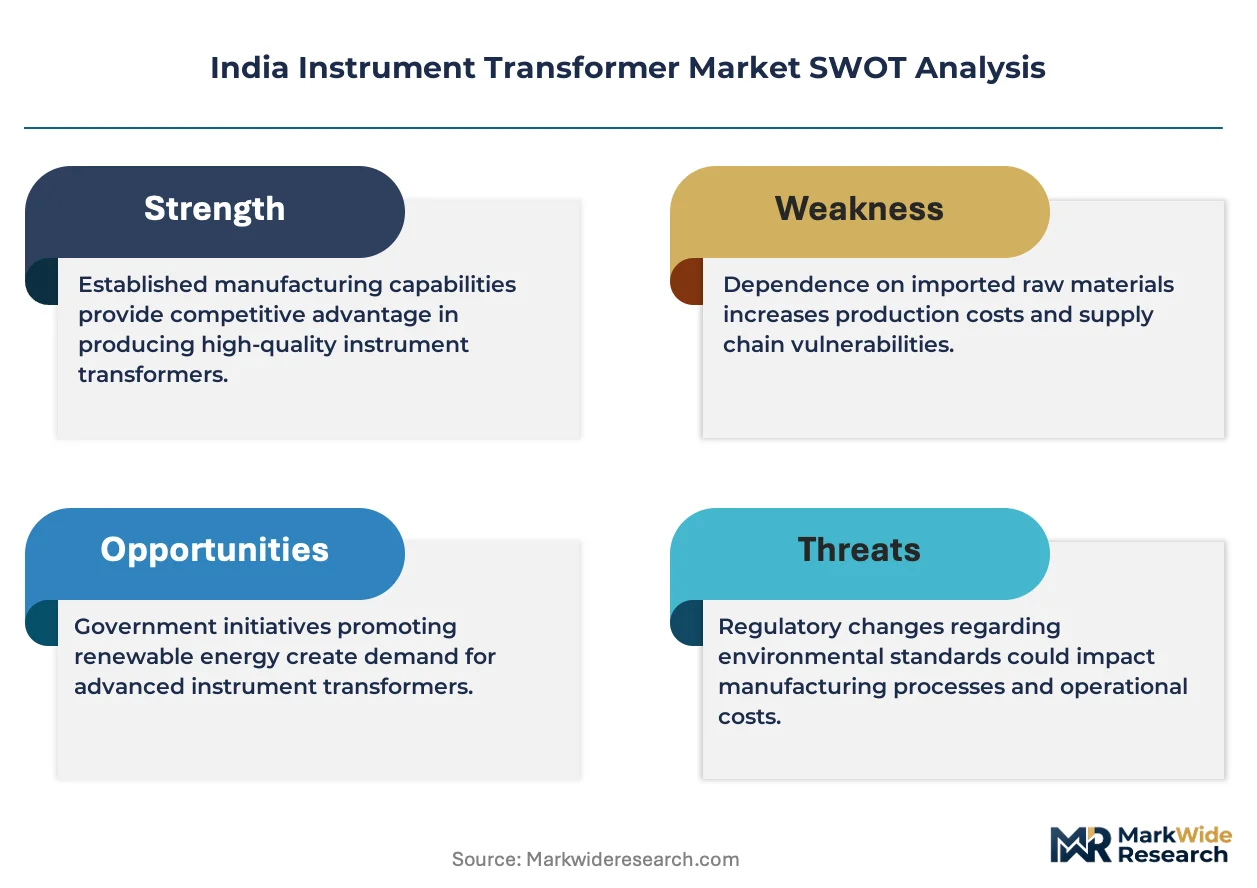
The Mumbai-Jaipur freight corridor compresses logistics costs for grain-oriented electrical steel shipments, amplifying price differentiation between Bhopal-Jhansi integrated manufacturers and coastal assemblers dependent on imported core materials. This corridor dynamic concentrates procurement leverage with domestic producers while forcing distribution-class competitors to absorb volatile copper pricing through thinner margins.
Pricing Analysis
CEA notification CEA/T&D/4/2021 dictates the pricing tier structure by mandating 0.2S accuracy class for revenue metering transformers, eliminating 0.5 and 1.0 class products from utility tenders. Pricing stratifies across IEC 61850-enabled digital units, conventional electromagnetic designs, and cost-optimized distribution transformers. Price differentiation hinges on BIS certification depth and backward integration into core material supply. Cost compression in distribution-class segments intensifies because copper and grain-oriented steel volatility erodes manufacturer margins. State transmission utilities exhibit lowest price sensitivity due to mandated accuracy upgrades, while commercial substation integrators prioritize unit economics over performance specifications.
Supply Chain Analysis
Single-source vulnerability around grain-oriented electrical steel imports from Japan and South Korea dominates supply chain risk assessment for Indian instrument transformer manufacturers. Production gravity centers on Bhopal and Jhansi, where Bharat Heavy Electricals Limited and integrated factories control over sixty percent of high-voltage capacity. Raw material sourcing draws from copper cathode imports, domestic silicon steel processing, and porcelain insulator fabrication in Gujarat and Tamil Nadu. Distribution runs through state transmission utility tender channels and direct vendor partnerships with digital-native Discoms in Telangana and Andhra Pradesh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical sensing platforms based on Faraday effect principles threaten conventional electromagnetic transformer incumbents as Power Grid Corporation of India Limited pilots gain operational scale. Incumbents must accelerate digital output integration to defend against substitution in 765 kV corridors.
For Market Incumbents: Insulate core revenue streams by accelerating IEC 61850 protocol integration in merging-unit designs before optical sensor pilots expand beyond western regional load dispatch centers. Pursue backward integration into grain-oriented electrical steel supply to neutralize import dependency exposure. Prioritize BIS certification maintenance for 0.2S accuracy class products as CEA enforcement deadlines approach. For New Entrants and Emerging Players: Rajasthan and Karnataka renewable corridors present first-mover opportunities in greenfield solar and wind installations lacking established procurement relationships. Target specialized metering transformers for intermittent generation profiling in ultra-mega solar parks where incumbent presence remains thin. Establish direct vendor partnerships with digital-native Discoms bypassing legacy tender channels. For Investors and Strategic Acquirers: CEA notification CEA/T&D/4/2021 reshapes the acquisition landscape by compressing product lifecycles and elevating digital capability premiums. Long-term viability favors manufacturers with embedded systems engineering depth and optical sensor integration expertise. Monitor Power Grid Corporation of India Limited pilot expansion signals as inflection indicators for optical platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Protocol Integration | Enables seamless merging-unit communication with SCADA systems in smart substation deployments. |
| Backward Integration into Core Steel | Captive supply of grain-oriented electrical steel neutralizes import price volatility exposure. |
| BIS Certification Acceleration | Compressed approval timelines secure eligibility for CEA-mandated 0.2S accuracy class tenders. |
| Optical Sensor Platform Development | Faraday-effect current sensing addresses electromagnetic saturation limits in 765 kV corridors. |
| Direct Discom Partnership Formation | Bypasses traditional tender channels with Telangana and Andhra Pradesh digital-native utilities. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, transformer manufacturing plant managers, EPC contractors, and state regulatory commission technical staff; and secondary validation through CEA technical notifications, BIS certification records, state transmission utility tender documents, and Power Grid Corporation of India Limited pilot disclosures. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts.
Forecast inputs considered technology substitution curves, regulatory compliance deadlines, and renewable capacity addition trajectories across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, and application function. CAGRs were derived from installed base replacement cycles and greenfield project pipelines. Industry-specific inputs incorporated CEA accuracy mandate enforcement timelines and optical sensor pilot expansion rates.
Practitioners should monitor copper price volatility, BIS certification backlog durations, and optical platform pilot outcomes for early signals of forecast revision necessity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market