
 Gas Insulated Switchgear Sales Market | 2026-2036
Gas Insulated Switchgear Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Insulated Switchgear Sales Market Insights
SF6-free insulation tier upgrades is unwinding legacy procurement patterns across the Gas Insulated Switchgear Sales Market. Siemens AG leverages extensive in-house fluoronitrile research to anchor European utility tenders. ABB sustains technology leadership through its dry-air insulated portfolio, while Hitachi Energy competes aggressively in Asian high-voltage substation projects.
Gas insulated switchgear encloses electrical conductors and circuit breakers within sealed metal chambers pressurized with sulfur hexafluoride or alternative insulating gas, achieving dielectric strength vastly superior to air at equivalent dimensions; manufacturers deploy robotic welding and helium leak detection to maintain chamber integrity below 0.5% annual gas loss rates. High voltage configurations dominate absolute revenue pools given their critical role in bulk power transmission, while medium voltage segments are expanding fastest as urban densification forces underground substation deployment. Compact product variants concentrate margin in space-constrained commercial and offshore renewable applications where footprint reduction commands premium positioning.
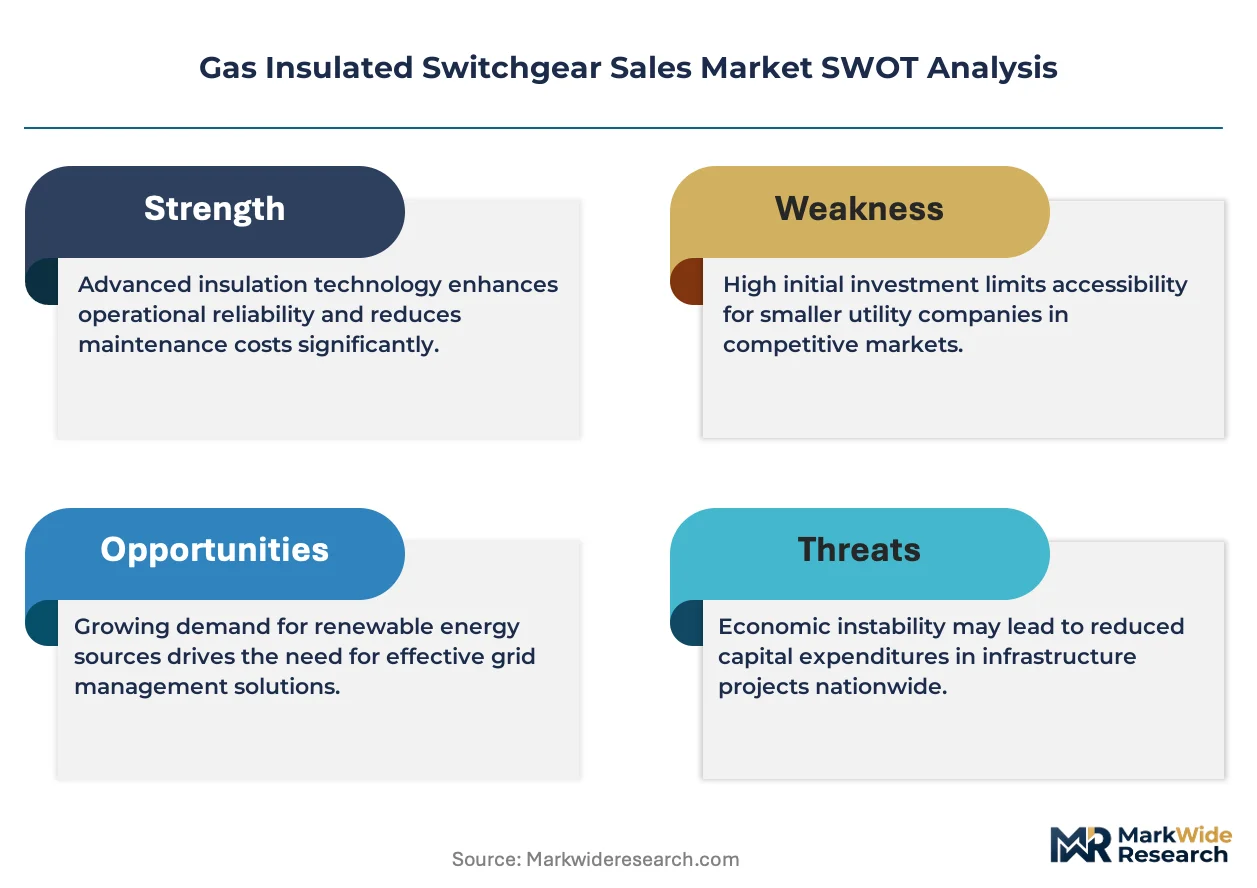
EPA greenhouse gas reporting mandates and the EU F-Gas Regulation are tightening SF6 handling protocols and accelerating capital redirection toward alternative insulation technologies. IEEE and IEC standards govern dielectric testing and seismic qualification, creating compliance thresholds that filter regional suppliers from premium tender participation. Stakeholders must weigh stranded asset risk in installed SF6 base against the engineering maturity timeline of emerging gas mixtures and vacuum interrupter hybrids.
Market Dynamics
The EU F-Gas Regulation phase-down is compressing SF6 procurement timelines and forcing utilities to pre-commit capital toward fluoronitrile and dry-air alternatives before full technical validation completes.
Growth Catalysts
- Offshore wind interconnection mandates:China's coastal provinces and Germany's North Sea clusters require compact high-voltage substations that only GIS footprint can deliver. Transmission operators in India are following similar density constraints.
- F-Gas Regulation enforcement:The EU's binding SF6 reduction quotas are creating immediate replacement demand for existing switchgear fleets. Member state penalties for non-compliance accelerate procurement decisions.
- Urban undergrounding directives:Tokyo, Seoul, and Singapore municipal authorities are prohibiting new air-insulated substations in central districts. GIS becomes the sole compliant technology for these constrained sites.
Market Restraints
- Copper and aluminum price volatility:Conductor materials constitute 35-45% of GIS bill-of-materials. LME price swings above 20% annually disrupt manufacturer margin planning and tender pricing stability.
- SF6 gas supply concentration:Three Chinese chemical producers control 70% of global sulfur hexafluoride refining capacity. Geopolitical friction or export restrictions would strand European and North American assembly lines.
- Alternative gas technical immaturity:Fluoronitrile mixtures require 15-20% higher operating pressure to match SF6 dielectric performance. This increases mechanical stress on seals and extends validation timelines.
Strategic Opportunities
- Vietnam and Philippines grid buildout:Both markets remain below 15% GIS penetration in medium-voltage distribution. Japanese and Korean equipment suppliers are establishing localized assembly to capture tariff-advantaged positioning.
- Digital twin integration:GIS vendors combining physical equipment with predictive maintenance software are capturing 5-8 year service contracts. This recurring revenue model displaces traditional break-fix arrangements.
- US Inflation Reduction Act transmission incentives:The IRA's $12.5 billion grid resilience and innovation program prioritizes SF6-free technologies. Qualifying projects receive accelerated depreciation and loan guarantees.
Industry Challenges
- Welding technician scarcity:Robotic seam welding for stainless steel enclosures requires certified operators with 3-5 year training curves. European and Japanese manufacturers report 18-month backlogs for qualified personnel.
- Type test certification duration:IEC 62271-203 high-voltage qualification protocols demand 12-18 months for new gas mixtures. Product launches lag R&D completion by multiple tender cycles.
- Legacy SF6 inventory stranding:Utilities with 10,000+ installed GIS bays face write-down risk if regulatory bans accelerate beyond equipment depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Insulated Switchgear Sales Market |
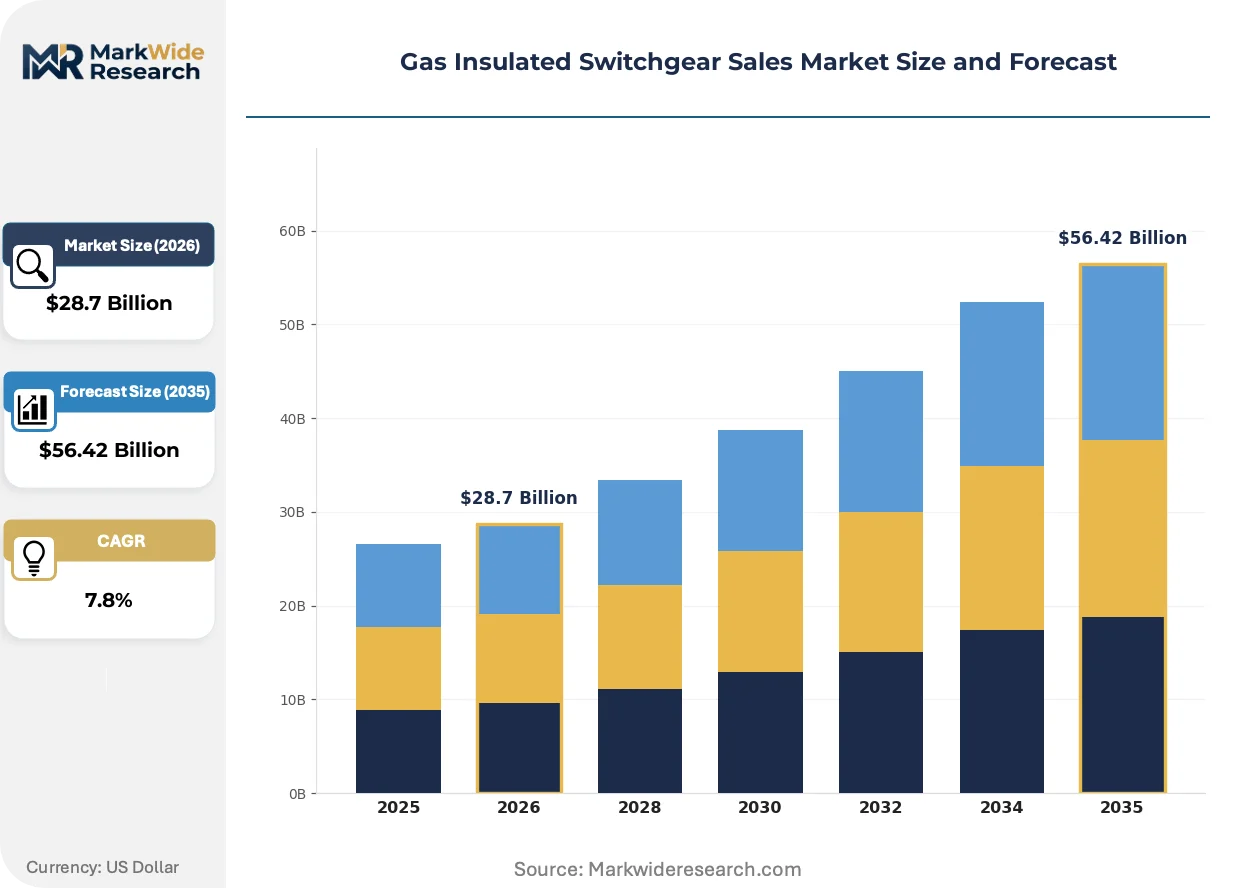
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $56.42 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Compact End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Indoor, Outdoor, Stationary, Portable Service Type: Installation, Maintenance, Repair, Upgrading |
| Companies Covered | Siemens AG, ABB, Schneider Electric, Mitsubishi Electric Corporation, Hitachi Energy, General Electric, Eaton Corporation, Toshiba, CG Power and Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Insulated Switchgear Sales Market Trends and Innovations
Solid-insulation hybrid designs and modular containerized substations are compressing project delivery timelines while regulatory pressure on fluorinated gases intensifies material science investment.
Three-position disconnector integration within vacuum interrupter chambers is miniaturizing medium-voltage GIS to half the footprint of conventional designs. Data center operators in Frankfurt and Singapore are specifying these compact variants to maximize land utilization. The technology is miniaturizing substation real estate requirements for urban commercial developments.
The EPA's Mandatory Greenhouse Gas Reporting Rule expansion to electrical equipment is forcing US utilities to inventory every SF6-filled asset above 17,820 pounds CO2-equivalent. Industrial consequence includes accelerated capital planning for replacement procurement. High-voltage transmission operators in Texas and California are responding with 10-year phase-out commitments in IRP filings.
Performance-based service contracting is displacing traditional equipment-plus-maintenance tenders among European distribution network operators. E.ON and Enel are unbundling capital expenditure from availability guarantees. This shift is most visible in Germany and Italy where regulatory asset base frameworks reward uptime outcomes over ownership.
Gas Insulated Switchgear Sales Market Segmentation
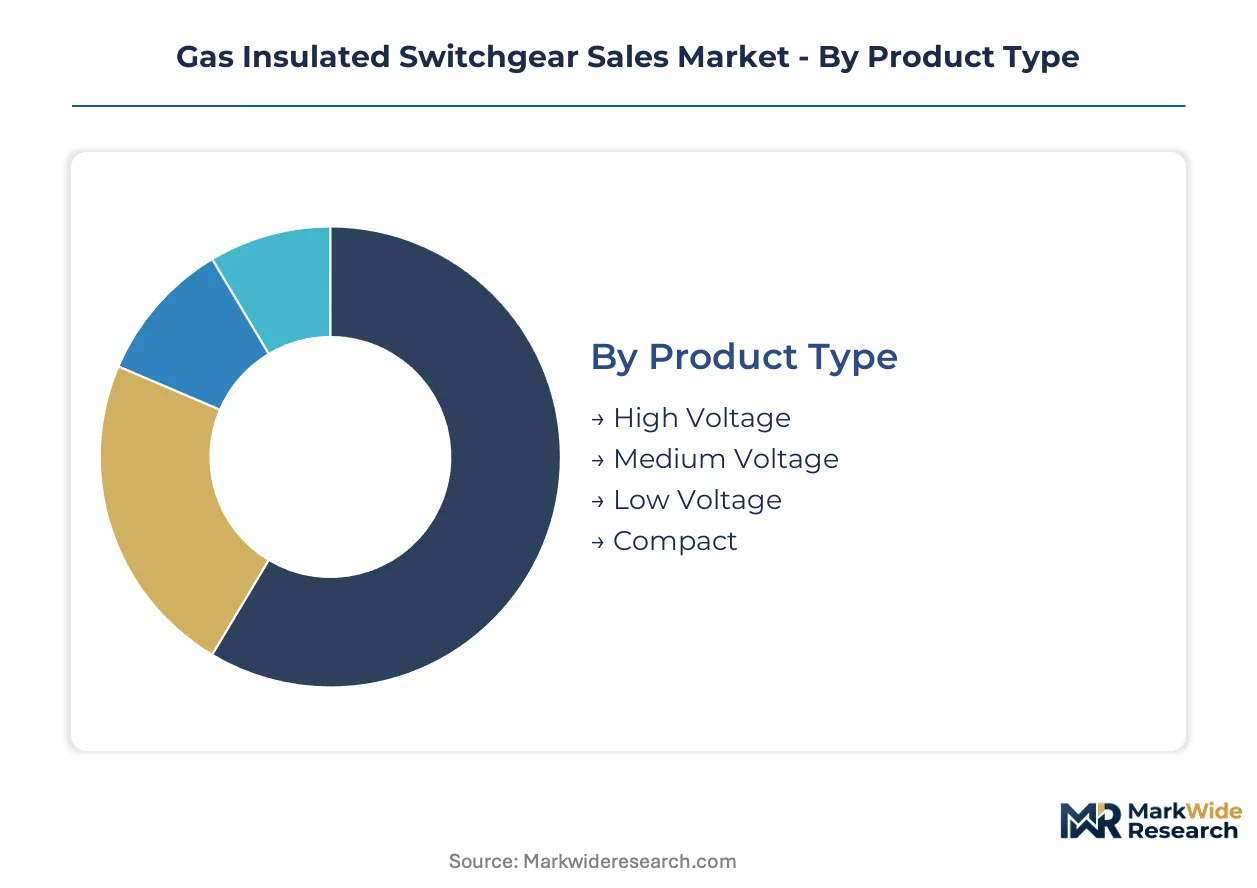
Segmentation in the Gas Insulated Switchgear Sales Market reveals distinct margin architectures across voltage classes and service models. Product configuration directly determines capital intensity, while end-use concentration shapes regional demand patterns and procurement timelines.
Product Type:
High voltage configurations command the deepest margin pools given their critical role in bulk power transmission and the engineering complexity of dielectric containment at elevated ratings.
- High Voltage:Enclosures rated above 52 kV rely on multi-chamber designs with precision-welded aluminum or stainless steel housings. Demand concentrates in Germany's North Sea offshore clusters and China's coastal transmission corridors where land scarcity mandates compact substation footprints.
- Medium Voltage:Segments spanning 1 kV to 52 kV serve urban undergrounding mandates in Tokyo, Seoul, and Singapore where municipal authorities prohibit air-insulated alternatives. Three-position disconnector integration is compressing these units to half conventional dimensions for data center operators.
- Low Voltage:Compact designs for commercial buildings and industrial facilities below 1 kV.
- Compact:Containerized variants for offshore renewable interconnection and emergency mobile deployment.
The dominant share belongs to High Voltage, while Medium Voltage is closing the gap fastest.
End User:
Customer archetypes diverge sharply in procurement sophistication, with transmission utilities operating multi-year capital cycles while commercial buyers prioritize speed-to-energization.
- Utilities:Grid operators in India and Germany drive standardization through framework agreements covering thousands of bays. Their tenders increasingly mandate SF6-free alternatives ahead of full technical validation, compressing supplier R&D timelines.
- Industrial:Heavy manufacturing and process industries require ruggedized enclosures for harsh environments.
- Commercial:Real estate developers in dense Asian metros specify compact GIS to maximize leasable floor area above substation vaults.
- Renewable Energy:Offshore wind developers in China's coastal provinces and Germany's North Sea clusters demand high-voltage compact configurations that only GIS footprint can deliver for platform-based substations.
Utilities retain the largest installed base, though Renewable Energy procurement is expanding most quickly.
Installation Type:
Deployment environment dictates enclosure specifications and determines whether manufacturers capture premium positioning through specialized engineering.
- Indoor:Vault and basement installations in urban cores require corrosion-resistant finishes and enhanced fire suppression integration. Tokyo and Singapore municipal codes drive specification intensity for these applications.
- Outdoor:Exposed installations demand IP65+ sealing and thermal management for extreme ambient temperature ranges.
- Stationary:Permanent substation foundations constitute the standard deployment mode across utility infrastructure.
- Portable:Mobile skid-mounted units serve emergency restoration and temporary construction power in markets with unreliable grid coverage.
Stationary deployments anchor volume, yet Indoor specifications are gaining share fastest as urban undergrounding accelerates.
Service Type:
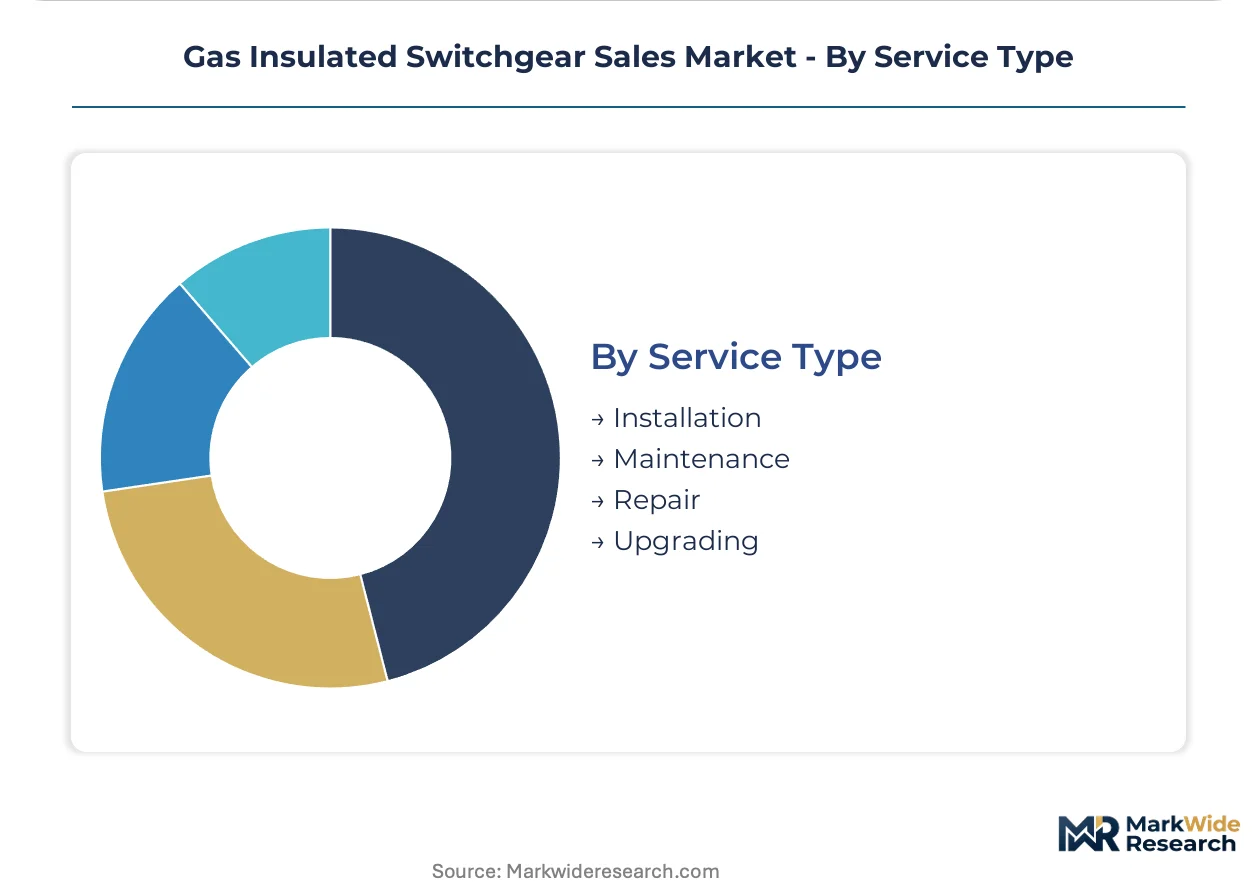
Recurring revenue streams from aftermarket services are displacing pure equipment sales as vendors pursue long-term contract structures.
- Installation:Commissioning protocols include helium leak detection and partial discharge testing that require certified technician teams. European manufacturers report 18-month backlogs for qualified welding specialists.
- Maintenance:Predictive service contracts spanning 5-8 years are capturing preference among German and Italian distribution network operators under performance-based regulatory frameworks.
- Repair:Legacy SF6 inventory management is emerging as a specialized discipline as phase-down regulations tighten.
- Upgrading:Retrofit services for fluoronitrile and dry-air migration address stranded asset risk in installed European fleets.
Installation commands the immediate revenue share, while Maintenance contracts are climbing the fastest as availability-guarantee models displace traditional break-fix arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export dependence on Chinese SF6 refining capacity is reshaping procurement security calculations for European and North American utilities. Import substitution programs in India and Germany are accelerating localized assembly investments. Trade friction risks are forcing transmission operators to diversify gas supply chains and accelerate fluoronitrile validation timelines.
China
Coastal provinces in Jiangsu and Guangdong are deploying high-voltage GIS for offshore wind interconnection at scale. The National Energy Administration's grid modernization directives mandate compact substation footprints for urban expansion zones. The Yangtze River Delta transmission corridor is absorbing the highest concentration of 550 kV installations for industrial load centers.
Germany
North Sea offshore clusters require platform-based GIS configurations that minimize topside weight and footprint. The EU F-Gas Regulation's binding phase-down quotas are compressing replacement timelines for existing switchgear fleets. Bavarian and Baden-Württemberg utilities are pre-committing capital to SF6-free alternatives ahead of full technical validation.
India
State transmission utilities in Maharashtra and Gujarat are expanding 400 kV corridors to accommodate renewable energy zones in Rajasthan and Tamil Nadu. The Central Electricity Authority's technical standards are tightening dielectric performance requirements for high-altitude installations. Grid modernization programs in Karnataka and Telangana are driving medium-voltage undergrounding mandates for Bangalore and Hyderabad metros.
United States
Texas and California transmission operators are responding to EPA greenhouse gas reporting mandates with 10-year SF6 phase-out commitments in integrated resource plans. The Inflation Reduction Act's grid resilience incentives prioritize SF6-free technologies with accelerated depreciation benefits. ERCOT and CAISO interconnection queues are concentrating demand in the Permian Basin and Central Valley renewable zones.
Japan
Tokyo metropolitan authorities are prohibiting new air-insulated substations in central districts, mandating GIS for all underground vault installations. METI's carbon neutrality roadmap is accelerating fluoronitrile pilot programs with major electric power companies. The Kansai region around Osaka is deploying compact medium-voltage configurations for data center load growth.
Gas Insulated Switchgear Sales Market Competitive Landscape
Concentration sits with diversified electrical equipment conglomerates that command integrated manufacturing and service networks. The vendor base stratifies across three tiers: full-spectrum high-voltage specialists, medium-volume regional assemblers, and niche compact-variant designers. Strategic moves center on backward integration into gas production and predictive maintenance software bundling to capture recurring revenue streams.
Among European-headquartered industrial conglomerates, Siemens AG and ABB exemplify the diversified high-voltage archetype with extensive in-house fluoronitrile research programs. Hitachi Energy occupies a position representing aggressive Asian competition in high-voltage substation tenders. These three anchors illustrate the competitive tension between established European technology leadership and accelerating Asian scale advantages in project execution capacity.
| Leading Market Players |
|---|
| Siemens AG |
| ABB |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| Hitachi Energy |
| General Electric |
| Eaton Corporation |
| Toshiba |
| CG Power and Industrial Solutions |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation phase-down schedule gates supplier qualification and price differentiation simultaneously. IEC 62271-203 certification tiers separate premium vendors from regional assemblers in tender participation. Utilities in Germany and Japan pay certification premiums for SF6-free validated designs. Copper and aluminum commodity exposure compresses margin planning across all tiers.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across the Gas Insulated Switchgear Sales Market. Pricing stratifies across IEC-certified premium, CE-marked standard, and economy tiers without full type-test validation. Cost compression in medium-voltage segments is intensifying because fluoronitrile R&D amortization loads early-adopter premiums. Commercial real estate developers in Asian metros exhibit highest price sensitivity; offshore wind transmission operators show least.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for stainless steel enclosures and precision welding equipment. Manufacturing gravity centers on China, Germany, and Japan for high-voltage chamber assembly. SF6 gas supply draws from Chinese chemical refiners; copper conductor stock feeds from Chilean and Peruvian mining operations. Single-source vulnerability concentrates in fluoronitrile precursor chemicals. Distribution runs through utility framework agreements and EPC contractor specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SF6-free alternative technologies threaten incumbent positioning as regulatory phase-downs accelerate beyond equipment depreciation schedules. Incumbents must navigate stranded asset risk in installed base while defending margin pools.
For Market Incumbents: Fortify backward integration into fluoronitrile gas production to capture supply security premiums. Siemens AG and ABB anchor European tenders through in-house material science programs. Accelerate dry-air and vacuum interrupter R&D to match Hitachi Energy's Asian project execution capacity. Certification investment in IEC 62271-203 validation protocols maintains tender access against emerging regional assemblers.
For New Entrants and Emerging Players: IEC type-test fast-track programs compress 12-18 month qualification timelines for new gas mixtures. White-space targets concentrate in Vietnam and Philippines medium-voltage distribution, both markets below 15% GIS penetration. Japanese and Korean suppliers are establishing localized assembly to capture tariff-advantaged positioning. Go-to-market angle: digital twin bundling with 5-8 year predictive maintenance contracts displaces traditional equipment-plus-service tenders.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across SF6-free alternative development programs. Long-term viability favors vendors with captive gas supply and software-enabled recurring revenue streams. Acquisition target archetype: mid-tier regional assemblers with IEC certification progress and established utility relationships. Signal to watch: EPA reporting rule expansion to electrical equipment accelerating US utility phase-out commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoronitrile Production | Siemens AG and ABB secure supply autonomy against Chinese SF6 concentration. |
| IEC 62271-203 Type-Test Certification | Validation protocols filter regional suppliers from premium tender participation in Germany. |
| Digital Twin Platform Integration | Predictive maintenance software captures 5-8 year service contracts from E.ON and Enel. |
| Localized Assembly in Vietnam | Japanese suppliers exploit tariff advantages in underpenetrated medium-voltage distribution. |
| SF6-Free Portfolio Migration | EU F-Gas Regulation penalties accelerate capital redirection toward dry-air alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, IEC standards documentation, and utility integrated resource plans. Primary interviews covered utility planning officers, EPC contractor procurement leads, GIS manufacturer R&D directors, and aftermarket service heads. Secondary validation drew from FERC interconnection queue data, EPA greenhouse gas reporting disclosures, and EU ETS registry records. Bottom-up project pipeline analysis triangulates against top-down transmission investment forecasts.
Segmentation dimensions modeled span voltage class, insulation technology, installation environment, and end-user archetype across the projection horizon. CAGRs derive from regression analysis of historical tender awards and announced grid modernization program budgets. Industry-specific forecast inputs include offshore wind interconnection mandates in China's coastal provinces and Germany's North Sea clusters, plus urban undergrounding directives in Tokyo and Singapore.
Underlying assumptions cover continued EU F-Gas Regulation enforcement trajectory, with deviation risk concentrated in alternative gas technical validation delays and copper price volatility. Forecasts reflect documented conditions without scenario weighting. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market