
 India Transformer Market | 2026-2036
India Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
India Transformer Market Foresight
Renewable energy integration is hardening the end-use vertical mix for India's transformer manufacturers. Solar park developers and wind farm operators now command a larger share of orders than traditional coal-linked utilities. CG Power & Industrial Solutions Ltd leverages its manufacturing scale to anchor utility-scale renewable projects. Bharat Heavy Electricals Ltd sustains dominance in the above 10 MVA segment through captive foundry capacity. Hitachi Energy India Ltd differentiates on digital monitoring systems for grid-connected installations.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 Hz in India and designed with core materials such as grain-oriented electrical steel to minimize hysteresis losses. Its primary industrial purpose is voltage step-up for efficient long-distance transmission and step-down for safe distribution to end consumers. Distribution transformers occupy the largest volume share due to rural electrification mandates and urban distribution network densification. Power transformers above 10 MVA carry the deepest margin pools, driven by greenfield substations and inter-regional transmission corridors. Instrument transformers are gaining traction alongside smart grid deployments requiring precise metering and protection relay coordination.
The Central Electricity Authority mandates efficiency standards that shape procurement specifications for state transmission utilities, while the Bureau of Indian Standards enforces IS 2026 for transformer testing and IS 1180 for distribution transformer energy performance. The Ministry of Power's revised tariff regulations from CERC push utilities toward lifecycle-cost optimization rather than lowest-bid acquisition. Stakeholders must monitor how PLI scheme disbursements for domestic electrical steel affect core material costs and localization timelines.
Market Dynamics
India's transformer sector is contending with a structural pivot from coal-linked procurement toward renewable energy integration, forcing manufacturers to recalibrate thermal ratings and cooling systems for solar park and wind farm duty cycles.
Growth Catalysts
- CEA Efficiency Mandates:The Central Electricity Authority's revised technical standards for power transformers are compelling state transmission utilities to retire aging assets ahead of schedule.
- Solar Park Deployment:Renewable energy developers in Rajasthan and Gujarat are commissioning 33/220 kV pooling substations that require specialized step-up transformers.
- Grain-Oriented Electrical Steel Localization:PLI scheme disbursements for domestic core material production are shortening import-dependent lead times.
Market Restraints
- Copper Price Volatility:Winding material costs fluctuate with LME pricing, compressing margins on fixed-price utility contracts.
- Import Concentration in CRGO Steel:Domestic cold-rolled grain-oriented supply remains insufficient for high-MVA unit cores, creating dependency on Japanese and Korean mills.
- IS 2026 Testing Bottlenecks:Bureau of Indian Standards certification queues at NABL-accredited laboratories extend project timelines by 8-14 weeks.
Strategic Opportunities
- Smart Grid Instrumentation:Current transformer and potential transformer demand is accelerating alongside state-level advanced metering infrastructure rollouts.
- Andhra Pradesh Transmission Ring:Greenfield 400 kV corridor development offers first-mover positioning for 315 MVA+ unit suppliers.
- Dry-Type Transformer Penetration:Urban underground substation constraints favor cast-resin units over oil-immersed alternatives in Mumbai and Bengaluru distribution networks.
Industry Challenges
- Winding Technician Scarcity:Precision coil winding for 220 kV+ units requires skills concentrated in Maharashtra and Tamil Nadu manufacturing clusters.
- Retrofit Integration Complexity:Digital monitoring system overlays on 1990s-era transformer fleets demand protocol bridging that delays smart grid synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Transformer Market |
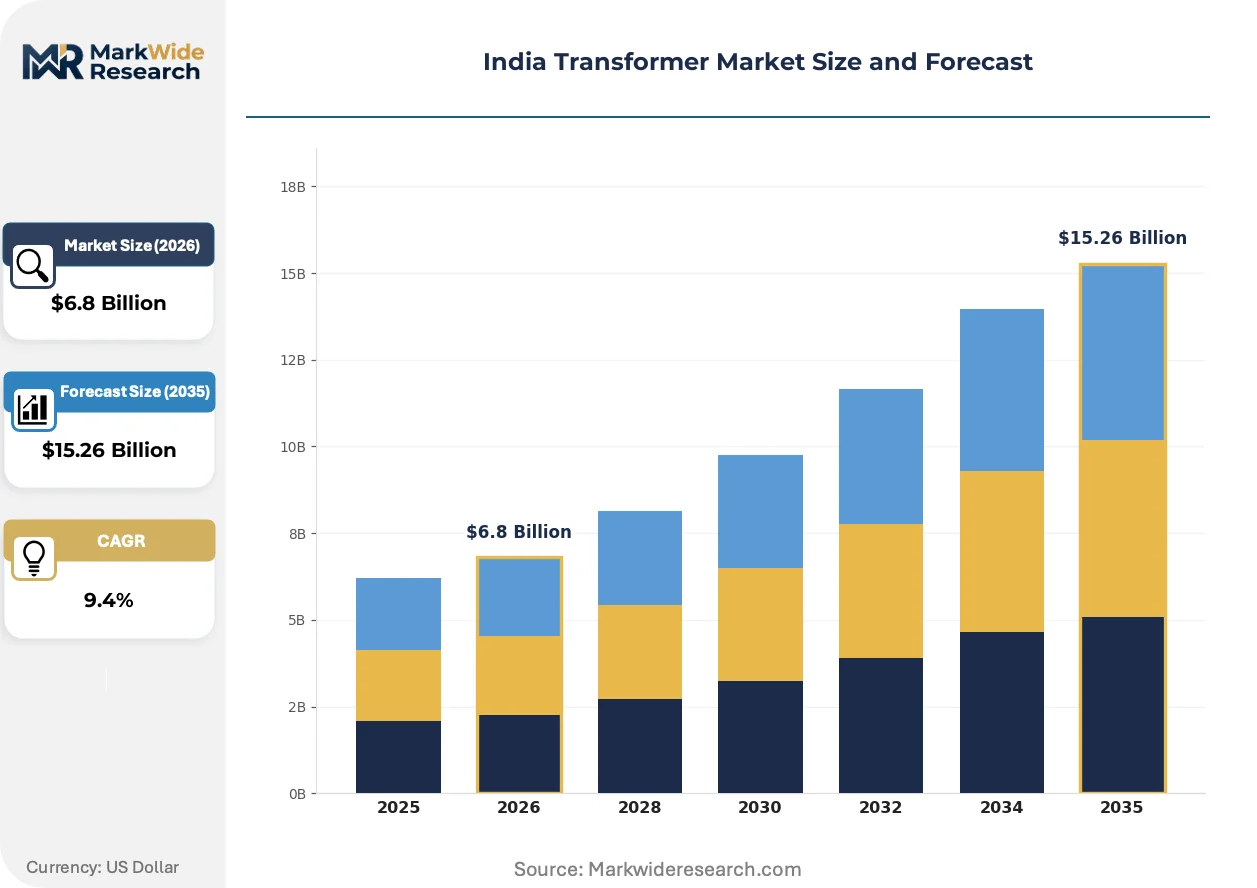
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distribution Transformer, Power Transformer, Instrument Transformer, Isolation Transformer Installation Type: Indoor, Outdoor, Substation, Mobile End User: Utilities, Industrial, Commercial, Residential Capacity: Up to 1 MVA, 1-5 MVA, 5-10 MVA, Above 10 MVA |
| Companies Covered | CG Power & Industrial Solutions Ltd, Transformers & Rectifiers India Ltd, Bharat Heavy Electricals Ltd, ABB India, Voltamp Transformers Ltd, Hitachi Energy India Ltd, GE T&D India Ltd, Kirloskar Electric Co Ltd, Siemens Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Transformer Market Shifts & Advancements
Transformer architecture is evolving through material substitution, regulatory tightening on losses, and buyer consolidation around lifecycle-cost procurement rather than capital expenditure minimization.
Amorphous metal core technology is absorbing hysteresis losses in distribution transformers below 500 kVA. State electricity boards in Kerala and Karnataka are piloting these units for rural feeder applications. The efficiency gain is compressing payback periods for utilities operating under Aggregate Technical and Commercial loss reduction targets.
Bureau of Indian Standards revised IS 1180 Part 1 in 2024, mandating maximum total losses for three-phase distribution transformers that exceed previous tiers by 15-20 percent. Manufacturers are redesigning core laminations and conductor geometries to comply. Distribution transformer suppliers serving Madhya Pradesh and Uttar Pradesh discoms are accelerating prototype testing to meet the January 2025 enforcement window.
Lifecycle-cost procurement is displacing lowest-bid evaluation at Maharashtra State Electricity Transmission Company and Gujarat Urja Vikas Nigam. Total cost of ownership modeling over 25-year asset life now dominates tender scoring. This behavioral shift is most visible in 66 kV and 132 kV power transformer categories where efficiency differentials compound into substantial operating expenditure variance.
India Transformer Market Segmentation
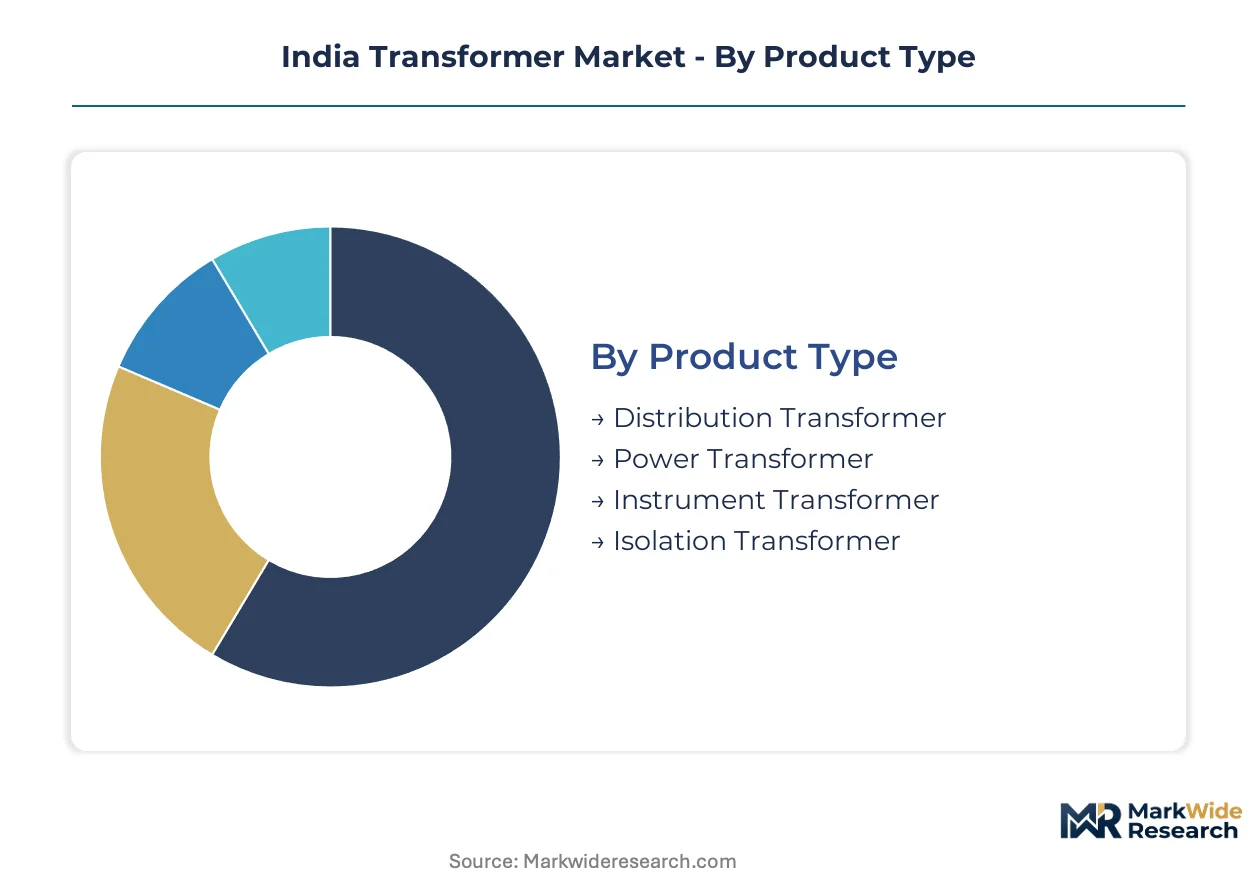
Transformer procurement in India fragments across technical specifications, deployment environments, and buyer economics. Each segmentation axis reveals distinct margin structures and competitive dynamics that manufacturers must navigate.
Product Type:
Voltage transformation architecture defines the core technology stack across Indian installations.
- Distribution Transformer:These units step down voltage from 33 kV to 415 V for last-mile delivery. Rural electrification mandates in Uttar Pradesh and Bihar drive volume procurement under the Saubhagya scheme, though discom payment delays strain manufacturer working capital.
- Power Transformer:Step-up and inter-regional transmission units above 33 kV rating carry specialized insulation and cooling requirements. Greenfield 765 kV corridors for the National Grid demand 315 MVA+ capacity ratings where Bharat Heavy Electricals and CG Power dominate tender awards.
- Instrument Transformer:Current and potential transformers enable metering accuracy and protection relay coordination for smart grid deployments. State-level advanced metering infrastructure rollouts in Maharashtra and Gujarat are accelerating precision unit procurement.
- Isolation Transformer:Galvanic separation units protect sensitive industrial loads from grid disturbances. IT parks in Bengaluru and Hyderabad specify these for data center power conditioning.
Distribution Transformer leads on scale; Instrument Transformer leads on momentum.
Installation Type:
Physical deployment constraints dictate cooling system design and enclosure specifications.
- Indoor:Cast-resin dry-type units occupy basement substations and commercial building electrical rooms. Mumbai's coastal humidity and space-constrained infrastructure favor these for high-rise distribution.
- Outdoor:Oil-immersed units with weatherproof housings dominate utility substations and rural feeder installations. Rajasthan's solar parks specify outdoor-rated 33/220 kV step-up transformers for pooling substations.
- Substation:Integrated transformer-switchgear assemblies for 66 kV and 132 kV grid nodes. Tamil Nadu Transmission Corporation's urban densification projects specify compact substation designs.
- Mobile:Skid-mounted and trailer-deployed units for emergency restoration and temporary load centers. Kerala State Electricity Board maintains mobile transformer fleets for monsoon-related outage response.
Outdoor installations command volume dominance; Indoor configurations are gaining share fastest in metro distribution networks.
End User:
Buyer procurement behavior varies sharply across public utility and private sector accounts.
- Utilities:State transmission and distribution companies operate under CERC tariff regulations with lifecycle-cost evaluation criteria. Maharashtra State Electricity Transmission Company and Gujarat Urja Vikas Nigam have shifted from lowest-bid to total cost of ownership scoring.
- Industrial:Steel, cement, and chemical plants procure captive power transformers for reliability-critical process loads. Odisha's aluminum smelters and Jharkhand's steel complexes specify high-fault-withstand designs.
- Commercial:Shopping complexes, hospitals, and IT campuses demand compact, low-noise units. Bengaluru's Whitefield tech corridor specifies dry-type transformers for indoor electrical rooms.
- Residential:Builder-electrical contractor procurement for apartment complex substations. Mumbai and Pune developers prioritize compact footprint over efficiency ratings.
Utilities anchor procurement volume; Industrial buyers offer the steepest expansion trajectory as captive power capacity expands.
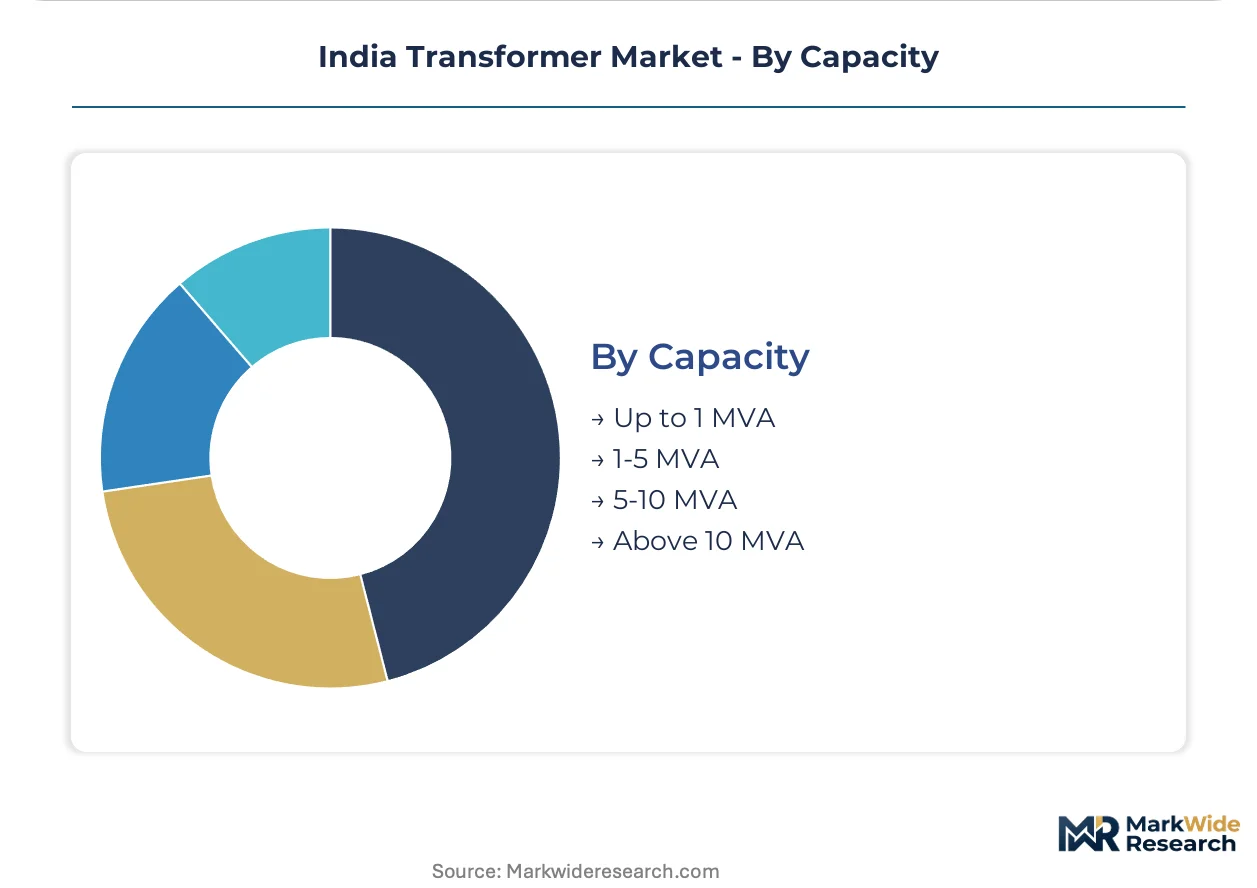
Capacity:
MVA rating determines core material intensity, winding complexity, and manufacturing facility requirements.
- Up to 1 MVA:Pole-mounted and plinth-mounted distribution units for rural feeders. Madhya Pradesh and Rajasthan discoms bulk-procure these under central government electrification targets.
- 1-5 MVA:Urban distribution substations and small industrial estates. Tamil Nadu's manufacturing clusters around Coimbatore consume significant volumes in this bracket.
- 5-10 MVA:Industrial captive power and renewable energy pooling stations. Wind farm developers in Gujarat specify these ratings for 33 kV collection systems.
- Above 10 MVA:Inter-regional transmission and large industrial complexes. The 400 kV Andhra Pradesh Transmission Ring and greenfield 765 kV National Grid corridors demand 315 MVA and 500 MVA units.
Up to 1 MVA leads on unit volume; Above 10 MVA leads on value concentration and import substitution priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between states are redistributing transformer manufacturing capacity across India. Maharashtra and Gujarat offer faster BIS certification timelines, drawing fabrication investment from eastern regions where CEA clearance queues lag by months.
Maharashtra
Maharashtra State Electricity Transmission Company's 765 kV corridor expansion drives demand for 315 MVA+ power transformers. The state's modified industrial policy grants electricity duty exemptions for greenfield electrical equipment plants. Mumbai's coastal substations favor dry-type cast-resin units for basement installations in high-rise districts.
Gujarat
Gujarat Urja Vikas Nigam's renewable energy integration mandates require specialized 33/220 kV step-up transformers for solar pooling stations. The state's single-window clearance mechanism compresses factory licensing to 30 days. Sanand and Mundra host concentrated manufacturing clusters serving western regional load dispatch centers.
Tamil Nadu
Tamil Nadu Transmission Corporation's urban densification projects specify compact 66 kV substation designs. The state's electronics manufacturing policy extends capital subsidies to transformer component suppliers. Coimbatore's industrial belt consumes significant 1-5 MVA distribution capacity for textile and engineering clusters.
Rajasthan
Rajasthan Renewable Energy Corporation's solar park tenders require outdoor-rated 33/220 kV transformers for Bhadla and Phased evacuation infrastructure. The Bureau of Energy Efficiency's state-designated agency enforces loss reduction targets on discom procurement. Jodhpur and Jaisalmer substations anchor the western renewable evacuation corridor.
Andhra Pradesh
Andhra Pradesh Green Energy Corporation's 400 kV transmission ring development offers first-mover positioning for high-MVA unit suppliers. The state's new industrial policy reserves land parcels for electrical equipment manufacturing zones. Visakhapatnam's port infrastructure facilitates CRGO steel import logistics for core lamination fabricators.
India Transformer Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale winding facilities to capture renewable energy procurement waves. The market structures around three tiers: state-owned heavy electrical equipment producers, diversified industrial conglomerates with electrical divisions, and specialized transformer-focused fabricators. Strategic archetypes include utility-scale project anchors, distribution-focused volume players, and digital monitoring system integrators. Competitive intensity centers on backward integration into core material supply and geographic proximity to state transmission utility headquarters.
Among diversified industrial conglomerates, CG Power & Industrial Solutions Ltd and Bharat Heavy Electricals Ltd exemplify contrasting scale positions. CG Power leverages private-sector agility in renewable energy project execution. Bharat Heavy Electricals occupies the public-sector anchor role through captive foundry capacity. Hitachi Energy India Ltd represents the technology-led archetype, differentiating on grid-connected digital infrastructure. These three players illustrate the strategic segmentation between manufacturing scale, state-backed vertical integration, and intelligent system integration.
| Leading Market Players |
|---|
| CG Power & Industrial Solutions Ltd |
| Transformers & Rectifiers India Ltd |
| Bharat Heavy Electricals Ltd |
| ABB India |
| Voltamp Transformers Ltd |
| Hitachi Energy India Ltd |
| GE T&D India Ltd |
| Kirloskar Electric Co Ltd |
| Siemens Ltd |
| Others |
Supply & Pricing Matrix
Captive backward integration into grain-oriented electrical steel production anchors both supply security and pricing power for India's transformer manufacturers. The PLI scheme disbursements for domestic CRGO capacity are compressing import-dependent lead times while insulating high-MVA unit producers from Korean and Japanese mill pricing volatility.
Pricing Analysis
Distributor margins on distribution transformers below 500 kVA compress under discom bulk procurement pressure, while direct-to-utility contracts for 315 MVA+ units sustain healthier project-based pricing. Three-tier pricing structure across premium, standard, and economy levels differentiates on Bureau of Indian Standards certification tier and after-sales service bundling. Price erosion runs through the sub-1 MVA segment as Uttar Pradesh and Madhya Pradesh discoms consolidate purchase orders. Industrial captive buyers show least price sensitivity, prioritizing fault-withstand ratings over capital expenditure minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from state transmission utilities, bypassing distributor markups for 132 kV and above installations. Core lamination supply draws from Japan, South Korea, and domestic PLI-commissioned mills, while copper winding material feeds from Chilean and Indonesian concentrate sources. Single-source vulnerability in high-grade CRGO steel creates procurement risk for 220 kV+ unit manufacturers. Distribution runs through project-specific EPC contractor networks rather than stocked inventory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's transformer market rests on lifecycle-cost procurement normalization and amorphous metal core localization. The shift from lowest-bid to total cost of ownership scoring at Maharashtra State Electricity Transmission Company and Gujarat Urja Vikas Nigam rewards efficiency-tier premium positioning.
For Market Incumbents: Extend digital monitoring system integration capabilities to defend against Hitachi Energy India's technology-led positioning. Backward integration into domestic electrical steel production secures core material supply against import concentration risk. Capacity addition in Gujarat's Sanand cluster captures renewable energy procurement proximity to Rajasthan solar parks.
For New Entrants and Emerging Players: Enter via dry-type cast-resin transformer specialization for Mumbai and Bengaluru urban underground substation constraints. The indoor installation segment shows penetrable white space with less entrenched incumbent presence. Target IT park and data center power conditioning specifications through compact footprint differentiation.
For Investors and Strategic Acquirers: Roll-up economics work for regional distribution transformer fabricators because discom payment delays and working capital intensity prevent organic scaling. The 5-10 year viability window favors acquisition of BIS-certified facilities in Maharashtra and Tamil Nadu manufacturing clusters. Watch PLI scheme disbursement velocity for domestic CRGO steel as inflection indicator for import substitution margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel | PLI-commissioned domestic CRGO capacity reduces Korean mill dependency for 315 MVA+ units. |
| Digital Monitoring System Deployment | Grid-connected transformer fleets require protocol-compliant sensor overlays for smart grid synchronization. |
| Amorphous Metal Core Adoption | Kerala and Karnataka state electricity boards pilot hysteresis-loss reduction for rural feeder efficiency targets. |
| Compact Substation Design Development | Tamil Nadu Transmission Corporation's urban densification projects specify space-constrained 66 kV installations. |
| Lifecycle-Cost Procurement Positioning | Maharashtra and Gujarat utilities now score tenders on 25-year total cost of ownership rather than capital expenditure. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with state transmission utility planning officers, renewable energy developer procurement leads, transformer plant managers, and EPC contractor project directors combined with secondary validation from Central Electricity Authority filings, Bureau of Indian Standards certification records, and Ministry of Power PLI scheme disclosures. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map transformer MVA ratings against end-use deployment environments, installation type specifications, and regional regulatory clusters across the projection horizon. Segmentation dimensions modeled include product architecture, capacity tier, installation constraints, and buyer procurement behavior. CAGRs derive from regression analysis of historical procurement data against renewable energy capacity addition trajectories and transmission corridor development pipelines.
Inputs from CEA and BIS regulatory filings were available through the study window; gaps in real-time discom payment cycle data introduce uncertainty bands around manufacturer working capital assumptions. Forecasts reflect documented assumptions regarding PLI scheme disbursement timelines and import substitution velocity. Periodic stress-testing of base assumptions against copper price volatility and CRGO steel supply continuity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Power Transformer Market
Transformers
United States Large Power Transformer Market
Transformers
China Transformer Market
Transformers
United States Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
North America Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
Uninhibited Transformer Oil Market
Transformers
Europe Distribution Transformer Market
Transformers
Three Phase Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Oil Filled Transformer Market
Transformers
Global Transformer Market
Transformers
Phase-Shifting Transformer Market